
 Electrical Enclosures Market | 2026-2036
Electrical Enclosures Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Enclosures Market Analysis
Electrical distribution through industrial integrators is reconfiguring as direct procurement from enclosure manufacturers gains share. Rittal GmbH & Co. KG leverages its German manufacturing base to dominate European supply chains for climate-controlled cabinets. Schneider Electric anchors its position through integrated software-hardware bundles that extend beyond physical enclosure sales. Eaton Corporation competes on severe-duty certifications for oil and gas applications, sustaining premium positioning in hazardous location segments.
Electrical enclosures are sealed housings, typically fabricated from cold-rolled steel, aluminum, or thermoplastic composites, designed to protect electrical components from environmental contaminants, moisture, and mechanical impact while managing thermal loads through passive ventilation or active cooling systems. Their primary purpose is ensuring operational continuity of switchgear, control systems, and power distribution equipment across industrial and commercial installations. Floor-mounted enclosures occupy the largest revenue pool due to heavy infrastructure deployment in utilities and heavy manufacturing, while stainless steel and fiberglass materials represent the fastest-growing material categories driven by corrosion resistance requirements in chemical processing and marine environments. Wall-mounted configurations lead volume in commercial building retrofits where spatial constraints dominate specification decisions.
NEMA enclosure standards in the United States, IEC 60529 ingress protection codes across Europe, and UL 508A industrial control panel requirements collectively dictate material selection, sealing performance, and market access for manufacturers serving cross-border projects. China's GB standards and compulsory certification protocols administered by SAMR impose additional compliance layers for foreign suppliers targeting infrastructure buildouts. Buyers must monitor evolving harmonization between NEMA and IEC rating systems, as divergence in test methodologies continues to fragment procurement specifications and complicate global product platform strategies.
Market Dynamics
Manufacturing reshoring across the United States, Germany, and China is compressing procurement cycles and forcing enclosure suppliers to regionalize production footprints, fundamentally altering how specifications travel from engineering desks to factory floors.
Growth Catalysts
- Renewable Energy Substation Deployment:Wind and solar farm buildouts in the United States and China require NEMA 4X and IP66-rated enclosures for inverter housings and transformer protection, driving specification volume.
- NEMA-IEC Harmonization Pressure:Industrial buyers operating cross-border projects demand dual-certified products, compelling manufacturers to engineer unified platforms that satisfy both standard systems simultaneously.
- Corrosion-Resistant Material Substitution:Chemical processing facilities and offshore platforms specify stainless steel and fiberglass composites in place of cold-rolled steel, expanding addressable demand in harsh-environment segments.
Market Restraints
- Steel and Aluminum Input Volatility:Cold-rolled steel and aluminum pricing fluctuations compress margin predictability for fabricators serving price-sensitive commercial building retrofit segments.
- Supply Concentration in German Precision Manufacturing:Climate-controlled cabinet production clusters heavily in southern Germany, creating geographic vulnerability for European industrial buyers seeking rapid fulfillment.
- Technical Limitation of Passive Thermal Management:High-density power electronics in data center applications exceed passive ventilation capacities, restricting enclosure applicability without costly active cooling retrofits.
Strategic Opportunities
- India Infrastructure Buildout:Transmission and distribution expansion under CEA mandates creates unmet demand for medium-voltage switchgear housings as domestic manufacturing capacity lags requirement growth.
- Integrated Software-Hardware Bundles:Convergence of physical enclosures with power monitoring and predictive maintenance software opens recurring revenue streams beyond one-time equipment sales.
- Marine and Offshore Certification Gap:Specialized ABS and DNV-GL certified enclosures for vessel electrical systems remain undersupplied relative to expanding shipbuilding activity in South Korea and China.
Industry Challenges
- Thermal Engineering Talent Scarcity:Design of active cooling systems for high-power density applications requires specialized mechanical and electrical engineering expertise that resides in limited supplier engineering centers.
- UL 508A Certification Timeline Compression:Industrial control panel assemblers face extended lead times for third-party certification, delaying project commissioning and straining customer relationships.
- Legacy System Integration Complexity:Retrofit projects in aging industrial facilities demand custom fabrication to interface with non-standard existing equipment, eroding standard product margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Enclosures Market |
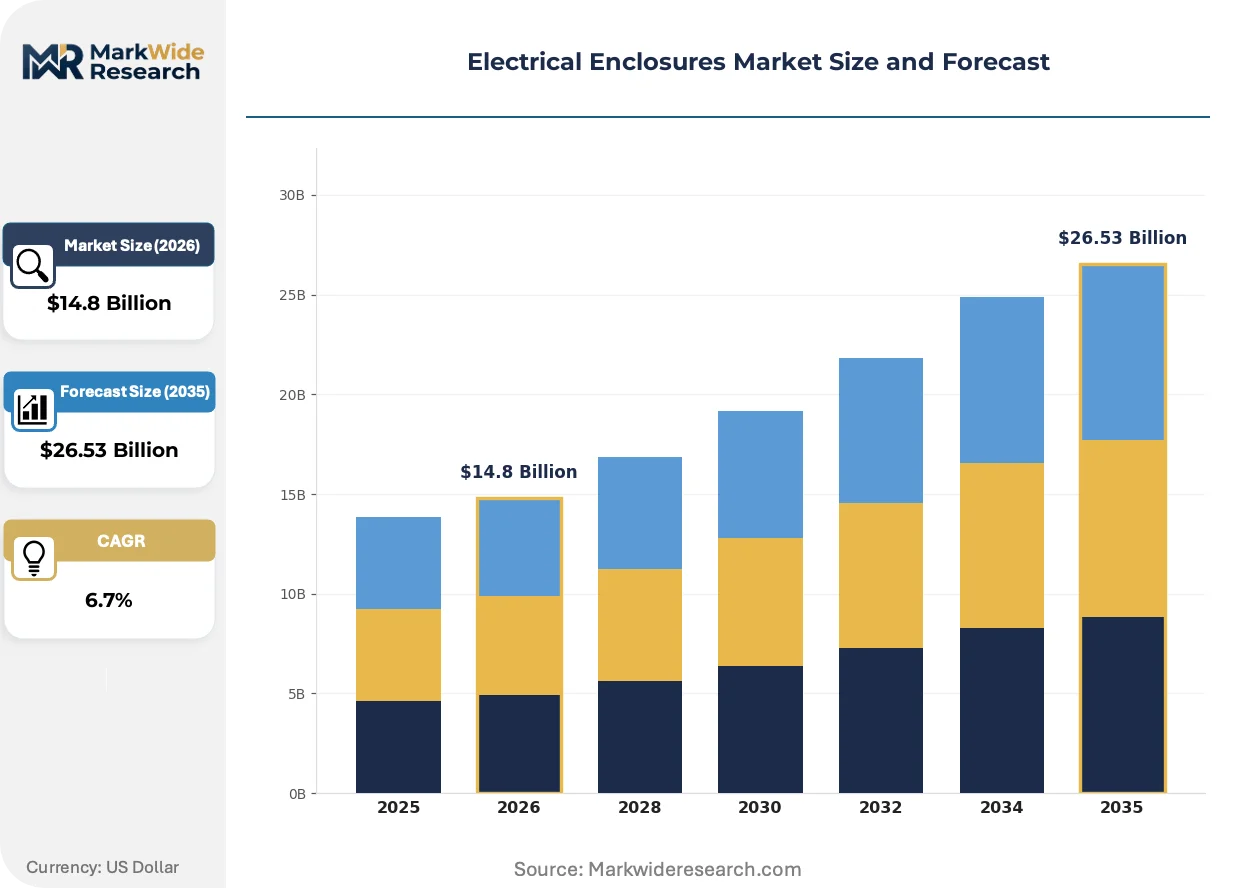
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Floor-Mounted, Modular, Rack-Mounted Material: Metal, Plastic, Stainless Steel, Fiberglass Application: Industrial Equipment, Commercial Buildings, Telecommunications, Renewable Energy Protection Rating: IP54, IP65, NEMA 12, NEMA 4X |
| Companies Covered | Rittal GmbH & Co. KG, Schneider Electric, ABB Ltd, Eaton Corporation, Emerson Electric Co., Hammond Manufacturing, Pentair PLC, nVent Electric PLC, Hubbell Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Enclosures Market Emerging Trajectories
Thermal management architectures and certification frameworks are undergoing simultaneous transformation as power density requirements escalate and regulatory jurisdictions tighten environmental and safety specifications.
Active liquid cooling systems are migrating from data center white space into industrial power distribution enclosures. Semiconductor fabrication facilities and battery gigafactories in Taiwan and Germany now specify liquid-cooled housings for medium-voltage drives. This migration from air-cooled to liquid-cooled architectures compresses footprint requirements by forty percent while demanding new supplier competencies in fluid dynamics and leak-proof sealing.
REACH restrictions on hexavalent chromium surface treatments are eliminating traditional galvanizing processes for European-sourced steel enclosures. Manufacturers serving EU industrial buyers have converted to zinc-aluminum-magnesium coatings and powder-coated alternatives. The chemical processing and wastewater treatment sectors, where corrosion resistance is non-negotiable, absorb premium pricing for compliant material finishes.
Direct procurement from enclosure manufacturers is displacing electrical distributor intermediaries for large industrial accounts. Automotive OEMs and utility operators in the United States now maintain approved manufacturer lists and issue blanket purchase orders. This channel compression concentrates volume with vertically integrated suppliers capable of engineering support and global fulfillment.
Electrical Enclosures Market Segmentation
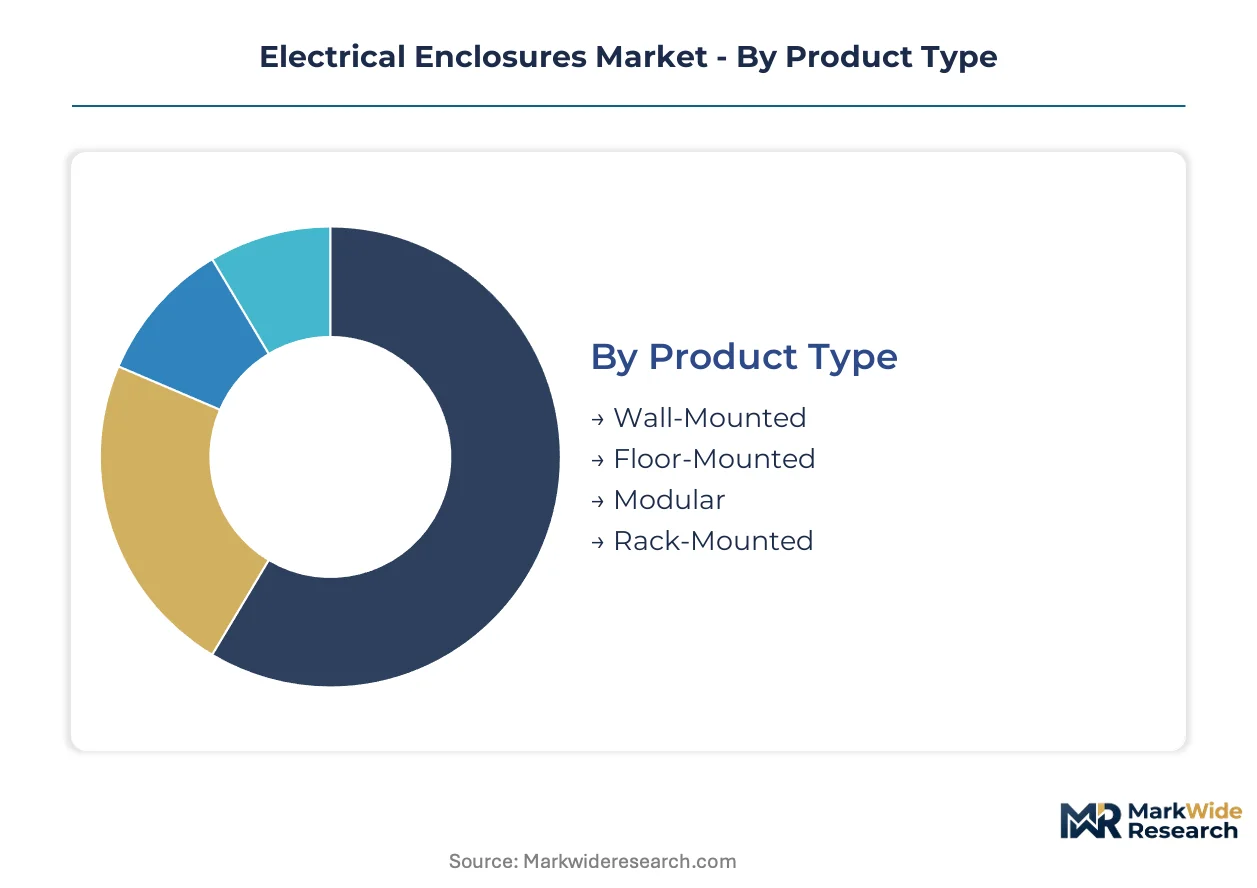
Segmentation in electrical enclosures reveals how procurement cycles, specification complexity, and environmental compliance requirements vary dramatically across installation types and material classes. Understanding these divides allows suppliers to align production footprints with demand velocity and margin profiles.
Product Type:
Floor-mounted enclosures turn over slowest due to capital-intensive infrastructure deployment, while rack-mounted configurations cycle fastest through data center refresh programs.
- Wall-Mounted:Compact housings fabricated from sheet steel or aluminum for distribution panels and control stations. Commercial building retrofits in Germany and the United States concentrate demand here, driven by spatial constraints in aging facilities and accelerated permit timelines for vertical installations.
- Floor-Mounted:Freestanding cabinets and multi-bay assemblies housing medium-voltage switchgear and motor control centers. Utilities and heavy manufacturing in China anchor demand, with procurement cycles extending across multi-year infrastructure buildouts and requiring extensive factory acceptance testing.
- Modular:Interconnectable bay systems allowing field-configurable expansion. Chemical processing facilities specify these for phased capacity additions.
- Rack-Mounted:Standardized 19-inch enclosures for server and telecommunications equipment. Hyperscale data center operators drive rapid replacement cycles.
Floor-mounted enclosures anchor the volume base while rack-mounted configurations gain share at the steepest rate.
Material:
Cost tiers separate commodity metals from corrosion-resistant premium grades, with specification decisions increasingly driven by total lifecycle cost rather than upfront acquisition price.
- Metal:Cold-rolled steel and aluminum sheet forming the baseline for commercial and light industrial applications. Price-sensitive construction segments in India specify these most heavily, though REACH compliance costs in Europe are compressing margins for traditional galvanizing finishes.
- Stainless Steel:AISI 304 and 316 grades delivering chemical and marine corrosion resistance. Offshore platforms in the North Sea and chemical processing corridors along the US Gulf Coast concentrate demand, with NORSOK and ABS certification requirements extending procurement lead times.
- Plastic:Polycarbonate and ABS thermoplastics for lightweight, non-conductive housings. Food processing and pharmaceutical cleanrooms favor these for washdown compatibility.
- Fiberglass:Reinforced polymer composites combining corrosion immunity with electromagnetic transparency. Coastal substations and radar installations drive niche specification.
Metal materials anchor the volume base while stainless steel climbs the fastest on corrosion-driven substitution.
Application:
End-use concentration determines whether specifications prioritize thermal management sophistication, aesthetic integration, or hazardous location certification.
- Industrial Equipment:Heavy-duty housings for manufacturing automation, process control, and power distribution. Automotive OEMs in Germany and battery gigafactories in the United States concentrate demand, with active liquid cooling specifications expanding for high-density drive systems.
- Renewable Energy:Inverter housings, transformer shelters, and battery enclosure systems for solar and wind installations. Utility-scale projects in China and the United States specify NEMA 4X and IP66 ratings for desert and coastal exposure.
- Commercial Buildings:Aesthetic-conscious panels for office, retail, and hospitality electrical distribution. Architects in France and Italy drive demand for customizable finishes.
- Telecommunications:Weatherproof cabinets for fiber distribution and 5G edge computing nodes. Tower companies in India and Brazil deploy these across climate extremes.
Industrial equipment anchors the volume base while renewable energy expands most quickly on substation buildout acceleration.
Protection Rating:
Certification grade directly maps to price tier and geographic regulatory environment, with dual NEMA-IEC compliance commanding substantial premiums.
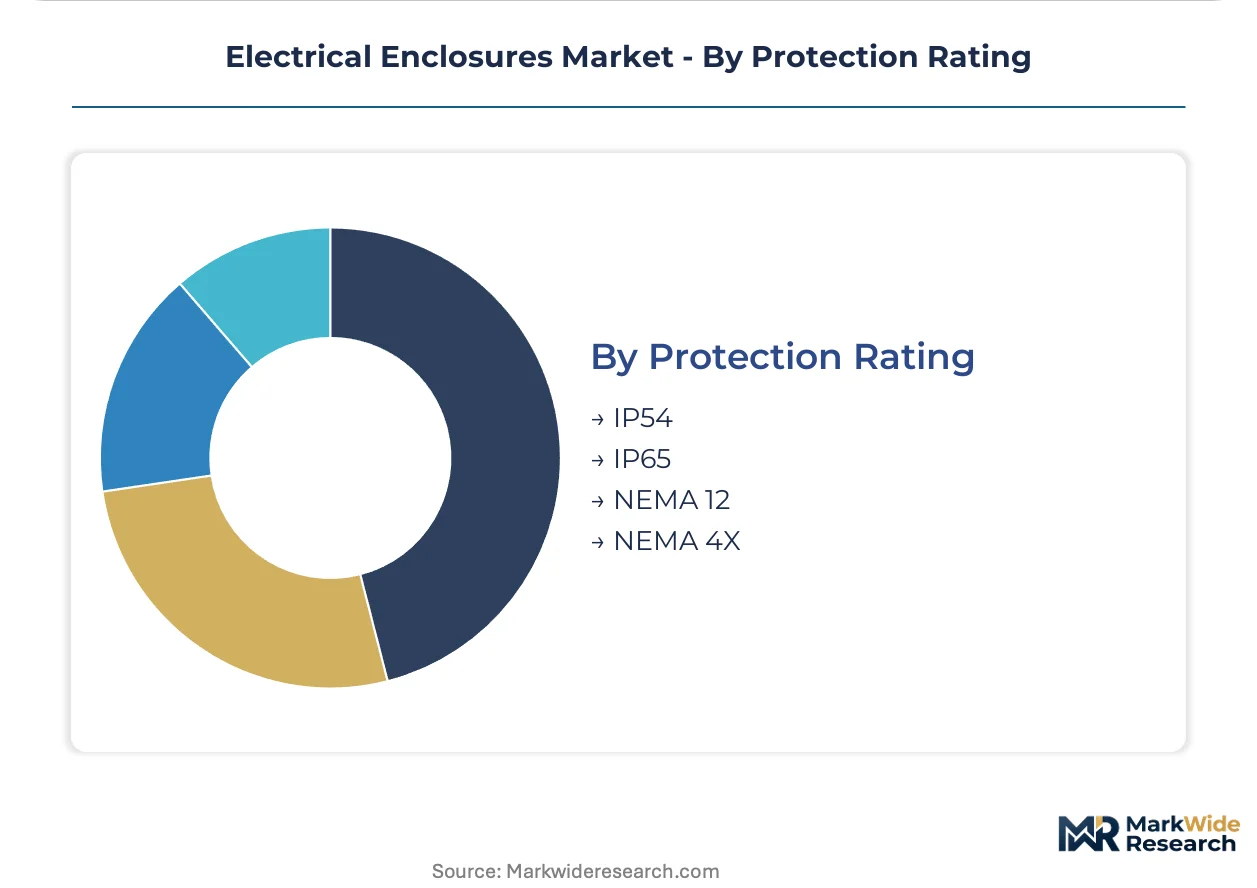
- IP65:Dust-tight and protected against water jets, satisfying most outdoor industrial requirements. European utilities and manufacturing facilities specify this as the baseline for cross-border project standardization.
- NEMA 4X:Corrosion-resistant watertight protection for harsh chemical and marine environments. US chemical processing and offshore oil operations mandate this, with UL certification timelines creating supply bottlenecks.
- IP54:Limited dust and water splash protection for indoor commercial applications. Cost-sensitive retrofit projects favor this tier.
- NEMA 12:Indoor protection against dust, dirt, and dripping non-corrosive liquids. Light manufacturing and data center white space deployments specify these.
IP65 anchors the volume base while NEMA 4X gains share fastest on corrosion-resistant substitution in chemical and marine sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's manufacturing tax credits are accelerating reshoring of electrical equipment production across multiple industrial corridors. Germany's Industry 4.0 subsidies and China's dual carbon goals are similarly redirecting capital flows into domestic enclosure supply chains. These policy vectors are compressing procurement cycles and forcing suppliers to regionalize fabrication footprints.
United States
Utility-scale solar and battery storage deployments in Texas and Arizona are consuming NEMA 4X-rated inverter housings at unprecedented rates. FERC interconnection queue reforms are expediting substation commissioning timelines. The Gulf Coast chemical processing corridor stretching from Houston to New Orleans anchors demand for severe-duty stainless steel enclosures.
Germany
Automotive battery gigafactories in Lower Saxony and Baden-Württemberg specify liquid-cooled medium-voltage drive enclosures. REACH restrictions on hexavalent chromium galvanizing are eliminating traditional surface treatments. The precision manufacturing cluster around Stuttgart maintains European supply chain dominance for climate-controlled cabinet systems.
China
Wind farm buildouts in Inner Mongolia and offshore installations in Jiangsu province require IP66-rated transformer shelters. SAMR compulsory certification protocols impose compliance layers on foreign suppliers. The Yangtze River Delta manufacturing belt concentrates domestic enclosure production for infrastructure export projects.
India
Central Electricity Authority mandates for transmission expansion are outpacing domestic switchgear housing capacity. BIS standards for medium-voltage equipment are tightening import specifications. The industrial corridor between Mumbai and Pune concentrates demand from automotive OEM automation retrofits.
Electrical Enclosures Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated specialists capable of engineering support and global fulfillment. German precision manufacturers anchor European supply chains for climate-controlled systems. Scale-driven diversified industrials compete through integrated software-hardware bundles. Three archetypes dominate: climate-control specialists, severe-duty certification holders, and integrated power management platforms. Competitive moves center on backward integration into material finishing and geographic expansion through regional fabrication facilities.
Among German-based fabricators, Rittal GmbH & Co. KG exemplifies the climate-control specialist archetype through its southern Germany manufacturing concentration. Schneider Electric occupies a position representing the integrated platform model, bundling physical enclosures with power monitoring software. Eaton Corporation sits within the severe-duty certification tier, anchoring hazardous location positioning through oil and gas industry relationships.
| Leading Market Players |
|---|
| Rittal GmbH & Co. KG |
| Schneider Electric |
| ABB Ltd |
| Eaton Corporation |
| Emerson Electric Co. |
| Hammond Manufacturing |
| Pentair PLC |
| nVent Electric PLC |
| Hubbell Inc. |
| Others |
Supply Flow & Price Mechanics
Steel and aluminum input volatility compresses margin predictability for fabricators while simultaneously dictating tier spreads between cold-rolled commodity enclosures and corrosion-resistant premium grades. This raw material instability forces buyers toward long-term contract structures that lock in supply security at the expense of pricing flexibility, reshaping how procurement desks balance upfront acquisition cost against total lifecycle value.
Pricing Analysis
Certification level creates the primary spread between NEMA 4X severe-duty housings and baseline IP54 commercial panels. Three-tier pricing structure across premium stainless steel, mid-grade aluminum, and economy cold-rolled steel segments reflects corrosion resistance and thermal management sophistication. Cost compression in the economy tier intensifies as Indian and Southeast Asian fabricators expand sheet metal capacity. Automotive OEMs and utility operators exhibit lowest price sensitivity due to specification rigidity, while commercial building retrofitters prioritize acquisition cost over performance margins.
Supply Chain Analysis
Contract manufacturing concentration rests with German precision fabricators around Stuttgart and domestic Chinese producers in the Yangtze River Delta. Cold-rolled steel draws from mills in Germany, China, and the United States, while specialty stainless steel feeds from Finnish and Japanese metallurgical suppliers. Single-source vulnerability concentrates in climate-controlled cabinet production anchored in southern Germany. Distribution runs through direct manufacturer relationships with large industrial accounts, displacing traditional electrical distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing reshoring across multiple industrial corridors signals cyclical recovery as infrastructure capital deployment accelerates procurement velocity. Policy support for domestic production in the United States, Germany, and China reinforces this cyclical upswing.
For Market Incumbents: Insulate margin position through backward integration into zinc-aluminum-magnesium coating processes that satisfy REACH restrictions without premium outsourcing. Secure UL 508A certification capacity expansion to compress third-party validation timelines that currently strain customer relationships. Threat substitution from liquid-cooled architectures demands engineering talent retention in thermal management disciplines.
For New Entrants and Emerging Players: Build out regional fabrication footprints in India where CEA transmission mandates outpace domestic switchgear housing supply. Target marine and offshore certification gaps for ABS and DNV-GL rated enclosures in South Korean and Chinese shipbuilding corridors. Go-to-market leverage hinges on engineering support capabilities that match vertically integrated incumbents.
For Investors and Strategic Acquirers: NEMA-IEC harmonization pressure reshapes the acquisition landscape toward dual-certified platform specialists capable of unified product engineering. Long-term viability favors vertically integrated fabricators with captive thermal management expertise and regional fulfillment networks. Signal to monitor: FERC interconnection queue clearance rates as proxy for utility-scale enclosure demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Fabrication Expansion | Proximity to Texas and Arizona solar buildouts compresses delivery timelines for NEMA 4X inverter housings. |
| Dual Certification Investment | Unified NEMA-IEC platforms capture cross-border industrial projects without redundant engineering. |
| Liquid Cooling Integration | Taiwanese semiconductor fabs and German battery gigafactories specify fluid-cooled medium-voltage drive enclosures. |
| REACH-Compliant Finishing | ECHA restrictions on hexavalent chromium galvanizing eliminate traditional surface treatments for EU-bound production. |
| Direct Procurement Channels | Automotive OEM approved manufacturer lists concentrate volume with engineering-capable suppliers. |
Methodological Framework
A spread of perspectives from plant engineers, OEM procurement teams, EPC contractors, and aftermarket service heads converged on the working assumptions around specification migration and thermal management requirements. Primary fieldwork combined with secondary validation through SEC filings, customs trade data, FERC interconnection databases, and NEMA standard documentation. Bottom-up volume builds across product type, material grade, protection rating, and application segments triangulated against top-down industrial capital expenditure patterns.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include enclosure mounting configuration, material corrosion resistance tier, protection certification grade, and end-use industry concentration. CAGRs derived from production capacity expansion announcements, utility interconnection queue data, and manufacturing reshoring policy implementation timelines. Forecast inputs incorporated steel and aluminum price trajectory assumptions alongside REACH compliance cost escalation for European market access.
Stress conditions across raw material volatility, certification timeline compression, and thermal engineering talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure spending continuity and regulatory harmonization progress. Quarterly review of FERC queue clearance rates, SAMR certification protocol changes, and CEA transmission mandate execution is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electrical Label Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Smart Heater Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Electrical Bushings Market