
 Global Telecom Tower Power System Market | 2026-2036
Global Telecom Tower Power System Market Size, Share, and Industry Trends Forecast 2026-2036
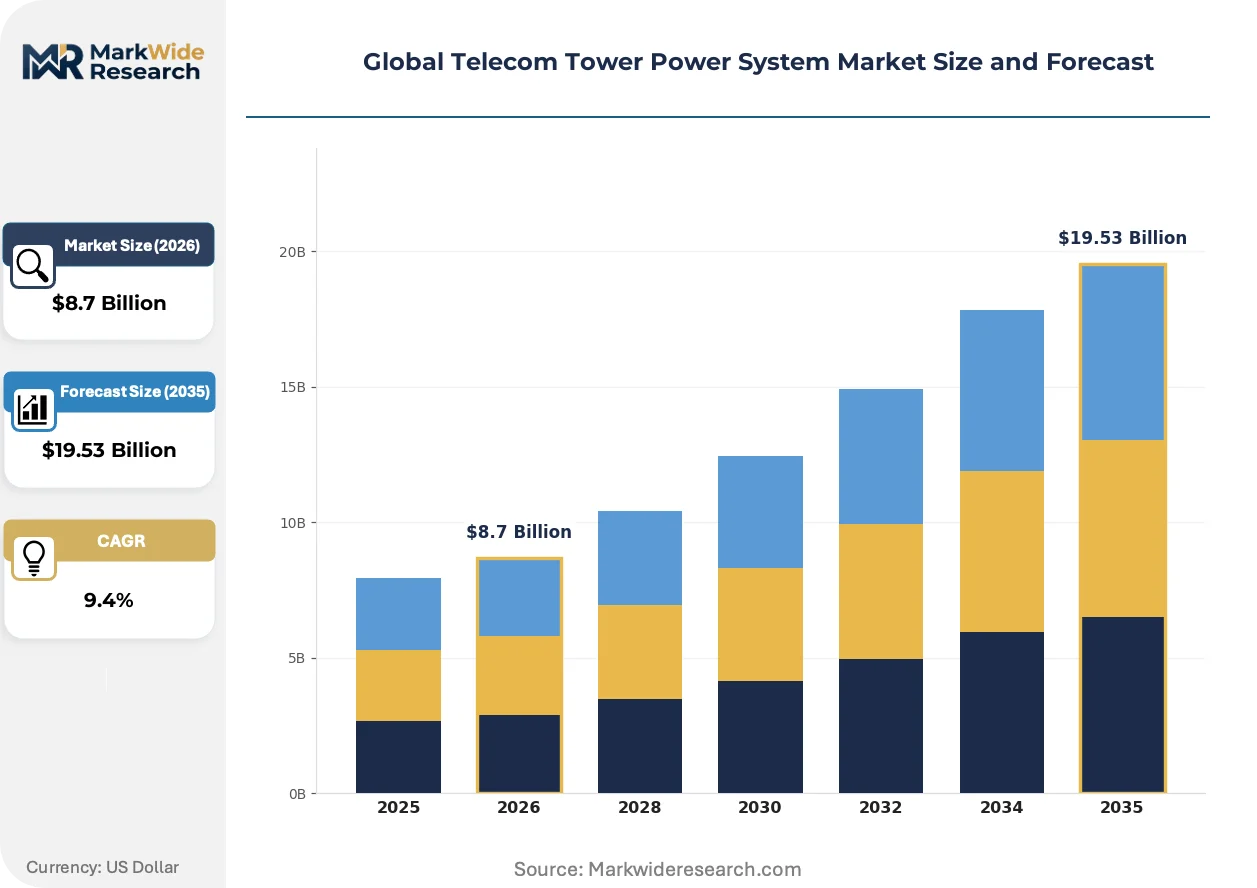
Global Telecom Tower Power System Market Outlook
IEC 62236 electromagnetic compatibility certification is bifurcating the vendor landscape into qualified system integrators and component-only suppliers. Huawei Technologies leverages its integrated power electronics portfolio to dominate turnkey deployments across Asia-Pacific and Africa. Schneider Electric sustains competitive positioning through its EcoStruxure platform, anchoring microgrid controls for remote tower sites. Cummins Inc. specializes in diesel-hybrid genset architectures, competing on fuel efficiency metrics in markets with weak grid infrastructure.
Telecom tower power systems comprise rectifiers, battery banks, gensets, solar PV arrays, wind turbines, and hybrid controllers engineered to deliver continuous DC or AC power at voltages typically ranging from 48V to 400V, with autonomy requirements spanning 4 to 72 hours depending on site criticality. These systems ensure network uptime for base transceiver stations, microwave links, and radio access nodes operating across rural, urban, and off-grid environments. Diesel power source configurations retain the largest installed base but carry the weakest margin pools as fuel logistics erode operational economics. Hybrid power source segments, combining solar PV with lithium-ion storage and intelligent dispatch controllers, represent the fastest-expanding category as tower operators prioritize opex reduction and carbon compliance. Rooftop installation types face structural constraints in dense urban cores, pushing growth toward ground-mounted and containerized formats that accommodate larger renewable footprints and battery enclosures.
FCC equipment authorization rules in the United States govern RF emissions from integrated power control systems, while India's CEA grid interconnection standards and renewable purchase obligations shape hybrid system specifications for tower companies. The EU Green Deal's F-Gas Regulation and REACH chemical restrictions are phasing out certain battery chemistries and insulating gases, forcing redesigns of thermal management and energy storage subsystems. Stakeholders must monitor evolving carbon border adjustments and local content requirements as procurement criteria shift from capital cost minimization toward total cost of ownership and emissions intensity metrics.
Market Dynamics
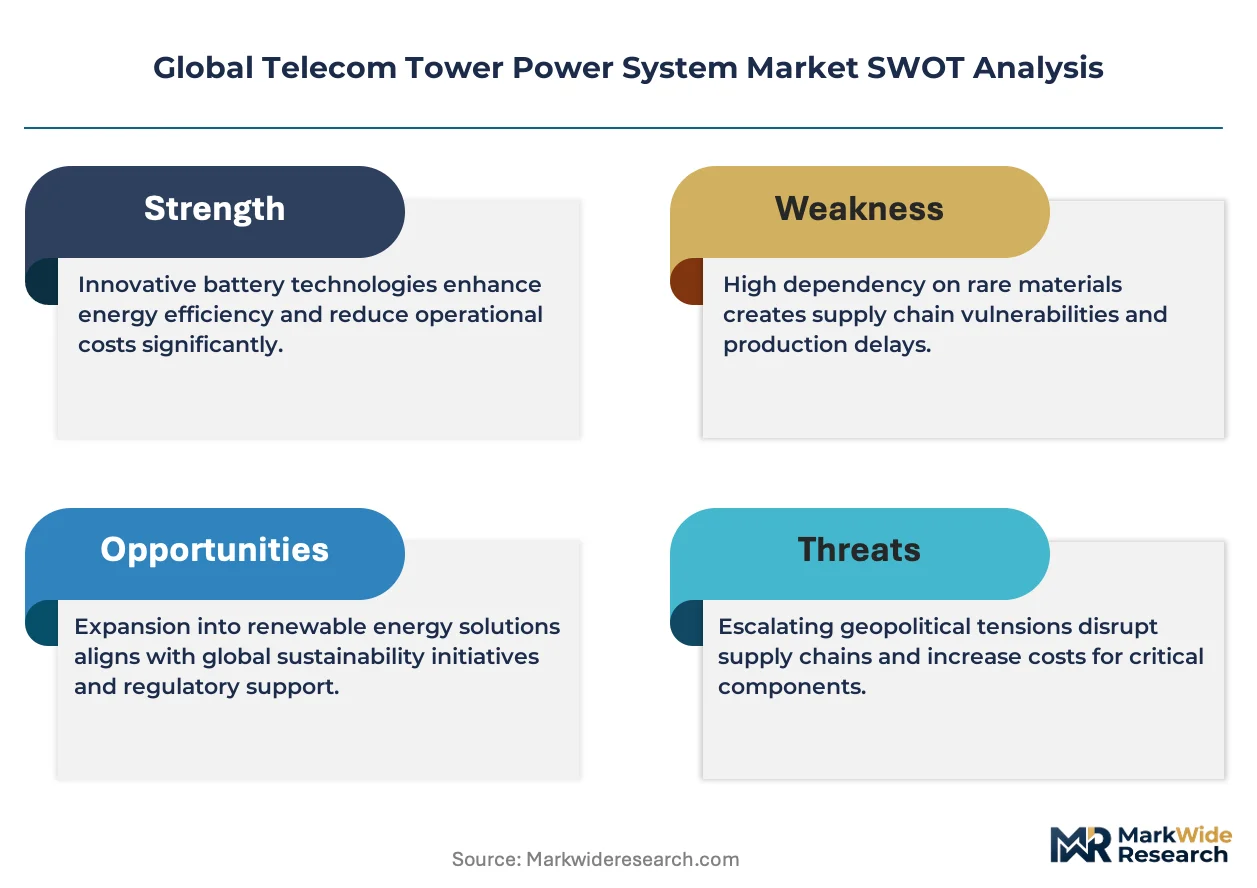
Hybrid power architectures are compressing diesel dependency as tower operators confront fuel logistics costs and carbon compliance mandates across emerging markets.
Growth Catalysts
- India's PLI scheme for telecom equipment:Domestic manufacturing incentives accelerate local assembly of solar-hybrid controllers and lithium battery enclosures, reducing import dependency for tower companies.
- 5G densification:Network rollouts in Nigeria and Indonesia multiply site counts, forcing power system procurement at scale where grid reliability remains intermittent.
- IEC 62236 electromagnetic compatibility certification:Standardized testing protocols reduce vendor qualification cycles, enabling faster deployment of integrated power electronics across multi-country tower portfolios.
Market Restraints
- Lithium carbonate price volatility:Battery chemistry cost swings compress margins on storage-heavy hybrid configurations, particularly for tower operators with fixed opex contracts.
- Chinese power electronics concentration:Rectifier and inverter supply chains cluster in Shenzhen and Dongguan manufacturing corridors, exposing procurement to single-source disruption risk.
- EU F-Gas Regulation phase-down:Thermal management system redesigns extend product development timelines, delaying hybrid system certifications for European tower deployments.
Strategic Opportunities
- Indonesia's outer island connectivity:Maritime logistics barriers strand thousands of unelectrified tower sites, creating captive demand for containerized solar-diesel microgrids with 72-hour autonomy.
- AI-driven predictive dispatch:Machine learning algorithms optimizing battery cycling against solar irradiance forecasts converge with edge computing at tower bases, enabling autonomous power management without centralized SCADA.
- India's renewable purchase obligations:Mandated clean energy quotas for commercial consumers create guaranteed offtake channels for tower operators investing in surplus solar generation capacity.
Industry Challenges
- IEC 62236 certification backlog:Testing laboratory capacity constraints extend vendor qualification timelines, delaying product launches for system integrators competing on turnkey deployment speed.
- Legacy 48V DC infrastructure incompatibility:Older tower sites require complete power train replacement to accommodate 400V AC solar inverters, complicating brownfield upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecom Tower Power System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Solar, Diesel, Wind, Hybrid Installation Type: Ground-mounted, Rooftop, Pole-mounted, Containerized Telecom Technology: 4G, 5G, LTE, Wi-Fi End User: Mobile Network Operators, Tower Companies, Enterprises, Government |
| Companies Covered | ABB Ltd., Cummins Inc., Huawei Technologies, Vertiv Holdings, General Electric Company, Delta Electronics, Schneider Electric, ZTE Corporation, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecom Tower Power System Market Strategic Shifts
Power system architectures are converging around intelligent dispatch algorithms and modular hardware platforms that compress deployment timelines while extending operational autonomy.
GaN-based power conversion semiconductors are replacing silicon IGBTs in rectifier and inverter stages, cutting switching losses by half. Tier-1 tower operators in India and Nigeria are piloting these devices in 10kW-class hybrid controllers. The technology is miniaturizing thermal management footprints, enabling higher power density in containerized enclosures where space constraints previously capped renewable integration.
India's CEA grid interconnection standards now mandate bidirectional power flow capabilities for tower-connected solar installations, forcing inverter redesigns. This regulatory friction accelerates vendor consolidation as smaller power electronics suppliers lack certification resources. Tower companies respond by pre-qualifying integrated system providers rather than component assemblers, compressing their vendor panels.
Energy-as-a-service contracting is displacing capital purchase models for rural tower sites. Under this arrangement, power system ownership remains with the equipment vendor, who charges per-kWh tariffs indexed to diesel price benchmarks. Nigerian tower operators lead this transition, transferring fuel price risk while locking in uptime guarantees. The model concentrates procurement authority with specialized hybrid system financiers rather than traditional tower infrastructure lessors.
Global Telecom Tower Power System Market Segmentation
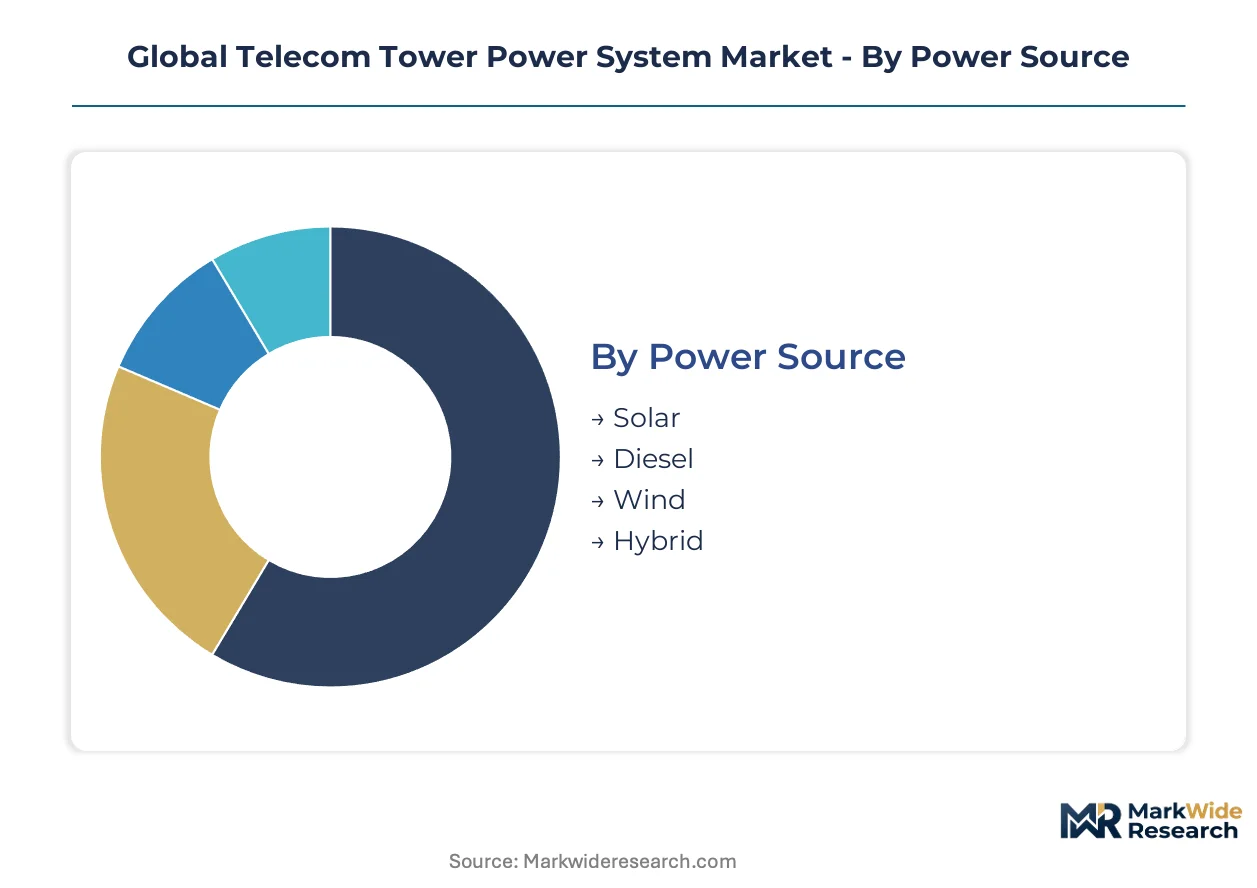
Power system segmentation in telecom infrastructure determines procurement strategies, regulatory compliance pathways, and total cost of ownership calculations across diverse deployment environments. Each dimension carries distinct margin profiles and technology trajectories that reshape vendor positioning.
Power Source:
CEA grid interconnection standards in India and EU F-Gas Regulation create divergent certification burdens that filter supplier participation by chemistry and thermal management approach.
- Hybrid:Combines solar PV, lithium-ion storage, and intelligent dispatch controllers with diesel backup for seamless autonomy. Tower operators in Nigeria and Indonesia prioritize these configurations where grid reliability fluctuates and fuel logistics erode diesel economics.
- Diesel:Standalone genset architectures delivering 48V DC or 400V AC power through rectifier banks and battery backup. Retains the largest installed base across sub-Saharan Africa and rural India, though margin pools compress as carbon compliance tightens.
- Solar:Photovoltaic arrays with lead-acid or lithium storage for off-grid and weak-grid sites. India's renewable purchase obligations accelerate deployment where surplus generation creates guaranteed offtake channels.
- Wind:Small-scale turbines integrated with battery buffering for coastal and high-altitude tower locations. Niche adoption concentrates in maritime corridor sites where diurnal wind patterns complement solar intermittency.
Diesel handles the majority of throughput; Hybrid is the fastest mover on share.
Installation Type:
Structural constraints and land availability drive cost tier differentiation between urban densification and rural greenfield deployments.
- Containerized:Pre-integrated power enclosures housing rectifiers, batteries, and renewable controllers in ISO-standard footprints. Indonesian outer island connectivity projects demand these formats for 72-hour autonomy where maritime logistics strand conventional supply chains.
- Ground-mounted:Open-air installations accommodating large solar arrays and battery enclosures with minimal structural loading. Dominates rural India and Nigeria where land costs remain negligible and tower densification for 5G multiplies site counts.
- Rooftop:Space-constrained deployments on building structures in dense urban cores. Structural load limits cap renewable integration, forcing reliance on compact lithium storage and high-efficiency rectifiers.
- Pole-mounted:Compact power systems attached directly to tower structures for microcell and small cell applications. 5G densification in Indonesian cities drives demand where street furniture rights-of-way restrict ground access.
Ground-mounted configurations retain volume leadership; Containerized formats are climbing the fastest.
Telecom Technology:
Radio access node power budgets and uptime requirements vary sharply across generation standards, reshaping autonomy specifications and backup duration.
- 5G:Massive MIMO arrays and millimeter-wave radios demanding 400V AC distribution with sub-10ms failover. Indian tower companies deploy hybrid microgrids at scale as TRAI mandates accelerate rural 5G rollout timelines.
- 4G:Macrocell base transceiver stations with established 48V DC infrastructure and 4-8 hour battery autonomy. Legacy installed base across Nigeria requires brownfield power system upgrades where 400V incompatibility forces complete replacements.
- LTE:Intermediate-generation equipment with flexible voltage acceptance and moderate power consumption. Transitional deployments concentrate in Indonesian suburban corridors awaiting 5G spectrum allocation.
- Wi-Fi:Low-power access points with minimal backup requirements and PoE distribution. Enterprise and government campus networks in Indian smart city projects drive modular procurement.
4G carries the bulk of installed power capacity; 5G deployment is gaining share fastest.
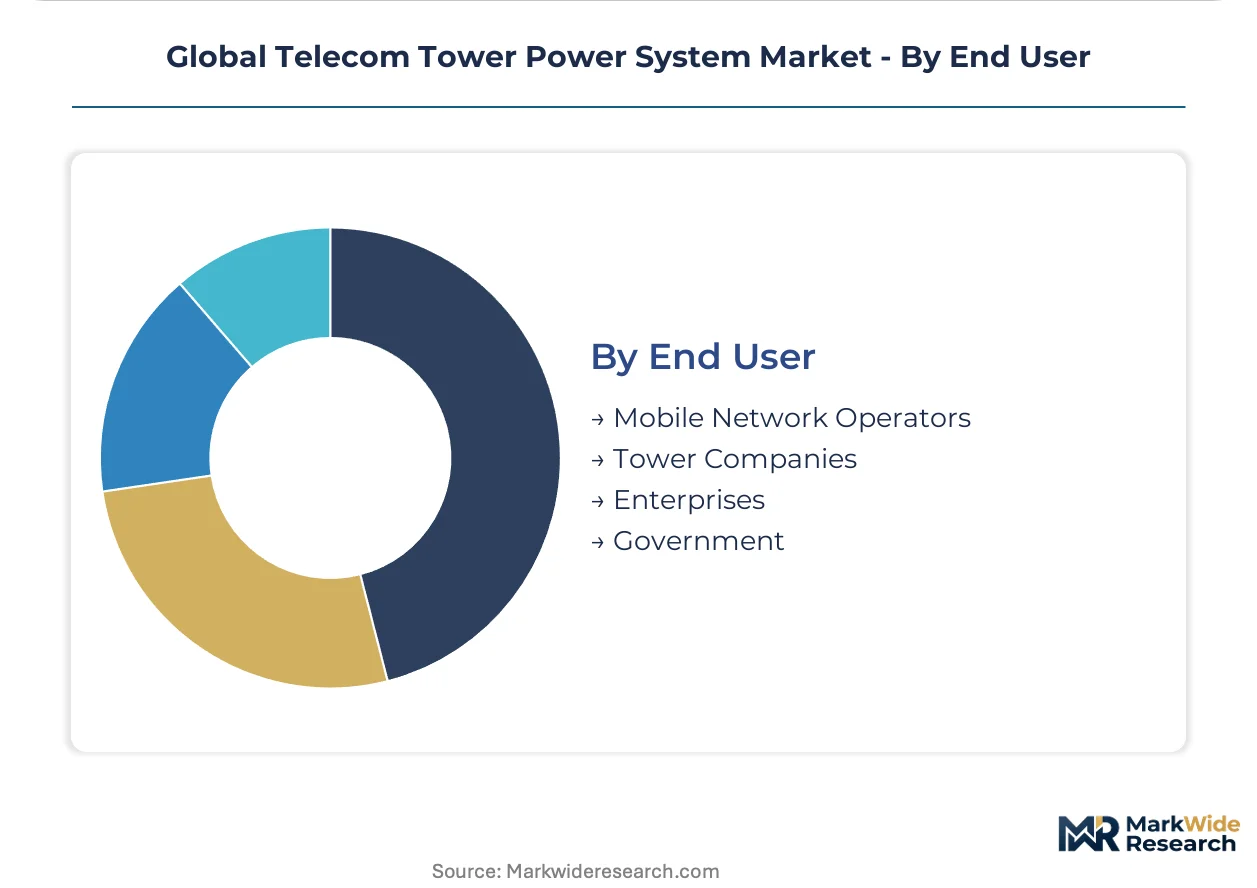
End User:
Contracting models and risk allocation diverge between asset-owning tower companies and service-procuring mobile operators.
- Mobile Network Operators:Spectrum holders outsourcing passive infrastructure while retaining active equipment decisions. Nigerian MNOs lead energy-as-a-service adoption, transferring fuel price risk to specialized hybrid system financiers.
- Tower Companies:Infrastructure-lessors standardizing power platforms across multi-tenant sites. Indian tower operators leverage PLI scheme incentives to localize solar-hybrid controller assembly and reduce import dependency.
- Enterprises:Private network deployers in mining, logistics, and industrial corridors. Indonesian plantation and maritime operators procure containerized microgrids for captive connectivity outside public network footprints.
- Government:Universal service obligation programs and rural connectivity schemes. Indian BharatNet and Nigerian rural broadband initiatives tender turnkey power systems with 72-hour autonomy specifications.
Tower Companies dominate procurement volume; Mobile Network Operators are expanding most quickly through energy-as-a-service transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for telecom equipment and renewable integration mandates are accelerating diesel-to-solar conversions across emerging markets. Mobile network operators in Nigeria and Indonesia are expanding rural coverage, driving adoption of hybrid power systems where grid reliability remains variable and tower densification for 5G is accelerating.
India
Tower densification for 5G rollout and TRAI rural connectivity mandates are multiplying site counts across Maharashtra and Gujarat. The CEA grid interconnection standards and PLI scheme incentives are forcing inverter redesigns and localizing solar-hybrid controller assembly. Manufacturing clusters in Pune and Chennai are scaling production of lithium battery enclosures and intelligent dispatch controllers for tower operators.
Nigeria
Maritime logistics barriers and weak grid infrastructure are stranding thousands of unelectrified tower sites in the Niger Delta and northern corridors. The Nigerian Communications Commission rural broadband initiatives are tendering turnkey power systems with 72-hour autonomy specifications. Lagos-based tower operators are leading energy-as-a-service transitions, transferring fuel price risk to specialized hybrid system financiers.
Indonesia
Outer island connectivity programs and 5G densification in Jakarta are creating captive demand for containerized solar-diesel microgrids. The Ministry of Communication and Informatics universal service obligations are mandating extended autonomy for remote archipelago deployments. Batam and Surabaya industrial zones are emerging as assembly hubs for ISO-standard power enclosures serving maritime logistics-constrained sites.
United States
FCC equipment authorization rules governing RF emissions from integrated power control systems are shaping procurement specifications for 5G massive MIMO deployments. The Inflation Reduction Act clean energy incentives are accelerating solar-storage hybrid adoption for rural tower sites in Texas and California. Phoenix and Dallas-Fort Worth corridor operators are piloting GaN-based power conversion in 10kW-class hybrid controllers.
Germany
EU F-Gas Regulation phase-down and REACH chemical restrictions are forcing thermal management system redesigns for battery enclosures and insulating gases. The EU Green Deal carbon border adjustments are shifting procurement criteria toward total cost of ownership and emissions intensity metrics. Bavarian industrial clusters around Munich are specializing in microgrid controls for remote tower sites with bidirectional power flow capabilities.
Global Telecom Tower Power System Market Competitive Environment
Player mix skews toward integrated power electronics specialists and diesel-hybrid genset architects competing on turnkey deployment speed and fuel efficiency metrics. Market structure concentrates procurement authority with system integrators holding IEC 62236 electromagnetic compatibility certification, filtering out component-only suppliers. Two strategic archetypes dominate: vertically integrated technology conglomerates with captive semiconductor portfolios, and specialized power infrastructure vendors with modular hardware platforms. Competitive moves center on pre-qualification partnerships with tower companies and localization of manufacturing to capture PLI scheme incentives.
Within the integrated technology tier, Huawei Technologies and ZTE Corporation exemplify the vertically integrated archetype with captive power electronics supply chains. Schneider Electric occupies a position among specialized infrastructure vendors, anchoring microgrid control platforms for remote deployments. Cummins Inc. represents the diesel-hybrid genset specialization, competing in markets with weak grid infrastructure where fuel efficiency determines procurement decisions. These three companies collectively illustrate the vendor landscape bifurcation between qualified system integrators and component-only suppliers.
| Leading Market Players |
|---|
| ABB Ltd. |
| Cummins Inc. |
| Huawei Technologies |
| Vertiv Holdings |
| General Electric Company |
| Delta Electronics |
| Schneider Electric |
| ZTE Corporation |
| Eaton Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Shenzhen and Dongguan manufacturing corridors shapes both supply concentration and price floors for power electronics, as rectifier and inverter production clusters compress procurement options while IEC 62236 certification requirements anchor premium tiers.
Pricing Analysis
Certification level (IEC 62236 electromagnetic compliance) creates the primary spread between qualified system integrators and component-only suppliers. Three-tier pricing structure across IEC-certified turnkey providers, regional assemblers, and unqualified component vendors dominates procurement. Cost compression in diesel-hybrid configurations is intensifying because lithium carbonate volatility erodes fixed opex contract margins. Tower companies with energy-as-a-service contracts exhibit lowest price sensitivity; rural government tenders show highest.
Supply Chain Analysis
China anchors rectifier and inverter manufacturing, with South Korea and Taiwan feeding power semiconductor wafers. Lithium carbonate from Chile and Australia, copper busbar from Zambia, and rare earth magnets from Myanmar constitute critical inputs. Single-source vulnerability concentrates in Shenzhen manufacturing corridors where geopolitical friction threatens component flows. Distribution runs through tower operator pre-qualification panels rather than open procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid power architectures are displacing diesel dependency across emerging markets, as India's PLI scheme and renewable purchase obligations create regulatory inflection points that reward localized manufacturing and carbon-compliant procurement.
For Market Incumbents: Compound certification advantages by accelerating IEC 62236 qualification for integrated power electronics portfolios. Deepen backward integration into lithium battery enclosure manufacturing at Pune and Chennai clusters to capture PLI incentives. Defend against specialized hybrid system financiers eroding turnkey deployment margins through energy-as-a-service contracting.
For New Entrants and Emerging Players: Differentiate on GaN-based power conversion semiconductors for 10kW-class hybrid controllers where Tier-1 tower operators in India and Nigeria are piloting next-generation efficiency. Target Indonesian outer island connectivity programs with containerized solar-diesel microgrids offering 72-hour autonomy. Lead with maritime logistics expertise and ISO-standard enclosure assembly at Batam to bypass incumbent supply chain chokepoints.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized power infrastructure vendors with modular hardware platforms over vertically integrated conglomerates facing regulatory friction. Long-term viability hinges on software-defined power management capabilities converging with edge computing at tower bases. Watch AI-driven predictive dispatch algorithm adoption rates as inflection indicator for autonomous power management displacement of centralized SCADA.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62236 Certification Investment | Testing laboratory partnerships compress vendor qualification timelines for turnkey deployment speed. |
| GaN Semiconductor Platform Launch | 10kW-class hybrid controllers cut switching losses for Indian and Nigerian tower operators. |
| Energy-as-a-Service Partnership | Per-kWh tariffs indexed to diesel benchmarks transfer fuel price risk in Nigerian markets. |
| PLI Scheme Manufacturing Localization | Pune and Chennai assembly hubs reduce import dependency for solar-hybrid controllers. |
| Containerized Microgrid Deployment | ISO-standard enclosures serve maritime logistics-constrained Indonesian archipelago sites. |
Study Parameters
A standing panel of tower company procurement directors, mobile network operator infrastructure leads, power electronics system integrators, and IEC certification laboratory managers provided ongoing calibration across primary interview cycles. Secondary validation drew from TRAI deployment filings, CEA grid interconnection standards, Nigerian Communications Commission rural broadband tenders, and Indonesian Ministry of Communication universal service obligation disclosures. Bottom-up unit economics for hybrid power configurations triangulated against top-down tower densification projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include power source architecture, installation type format, telecom technology generation, and end-user contracting structure. CAGRs derived from installed base replacement cycles, 5G rollout timelines, and renewable purchase obligation compliance trajectories. Forecast inputs incorporated lithium carbonate price volatility bands and maritime logistics cost indices for archipelago deployments.
Material uncertainties — regulatory phase-down timelines for EU F-Gas and REACH restrictions, geopolitical disruption to Chinese power electronics supply chains, and tower operator solvency under fixed opex contracts — sit outside the modeled envelope. Forecasts reflect assumptions on technology substitution rates and certification backlog resolution. Recalibration cycles align with material shifts in India's PLI scheme disbursement schedules and Indonesian outer island connectivity program awards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Japan Surge Protector Market
Power Systems
Bypass Thyristor Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
PV Inverter Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Low Voltage Drives Market
Power Systems
Europe Micro Inverter Market
Power Systems
Power Semiconductor Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
Intelligent Power Module (IPM) Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Global Data Center Transformer Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
North America Telecom Power Systems Market