
 Automotive Inverters Market | 2026-2036
Automotive Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Inverters Market Outlook
China is reshaping automotive inverter supply dynamics through aggressive domestic capacity expansion for electric vehicle power electronics. Robert Bosch GmbH leverages its integrated manufacturing footprint across European and Asian plants to sustain cost advantages in high-volume onboard inverter production. Denso Corporation anchors its position through captive relationships with Toyota hybrid platforms, while Infineon Technologies AG competes on silicon carbide chip supply to multiple Tier-1 module assemblers.
Automotive inverters are power electronic devices that convert direct current from traction batteries into alternating current for electric motor propulsion, typically operating at switching frequencies between 10 kHz and 20 kHz with efficiency targets exceeding 97 percent. Onboard inverters dominate unit volume as OEMs integrate propulsion electronics directly into vehicle architectures rather than sourcing standalone assemblies. Battery inverters command premium positioning within energy storage system applications where bidirectional power flow and grid synchronization capabilities create differentiated margin pools.
FDA oversight of electromagnetic compatibility in medical-adjacent vehicle applications, EPA tailpipe and fuel economy standards, and NHTSA functional safety requirements collectively tighten inverter efficiency and reliability specifications in the United States. EMA transport electrification guidelines and REACH substance restrictions in Europe add parallel compliance layers for semiconductor materials and thermal interface compounds. Stakeholders must monitor how silicon carbide substrate supply constraints versus silicon IGBT availability reshape procurement timelines and module design commitments.
Market Dynamics
Silicon carbide semiconductor transitions are compressing inverter efficiency thresholds while EPA tailpipe rules force redesign cycles below traditional automotive development timelines.
Growth Catalysts
- EPA Fuel Economy Standards:United States emissions rules tighten efficiency floors for electric drivetrains, forcing OEMs to refresh inverter architectures ahead of standard vehicle platform cycles.
- Silicon Carbide Substrates:Wide-bandgap semiconductors cut switching losses by half versus silicon IGBTs, enabling smaller thermal management packages and extended vehicle range.
- Passenger EV Platform Absorption:OEMs integrate propulsion electronics directly into vehicle architectures, concentrating inverter demand within high-volume electric vehicle programs.
Market Restraints
- Substrate Supply Concentration:Silicon carbide wafer fabrication clusters in limited geographies, creating procurement bottlenecks for Tier-1 module assemblers expanding capacity.
- Technical Limitation:Gate driver integration with silicon carbide MOSFETs demands specialized expertise scarce outside established power electronics engineering clusters.
- Cost Structure:Thermal interface materials compliant with REACH substance restrictions command premiums versus legacy compounds, pressuring module-level margins.
Strategic Opportunities
- Grid Synchronization Capabilities:Bidirectional battery inverters for vehicle-to-grid applications open premium positioning within energy storage system markets.
- China Domestic Capacity:Aggressive expansion of electric vehicle power electronics manufacturing creates white space for localized supply chain partnerships.
- ISO 26262 Certification:Functional safety standard compliance becomes a differentiable credential as NHTSA requirements harden for autonomous-capable electric platforms.
Industry Challenges
- Power Electronics Talent Gap:Specialized gate driver and thermal management engineering functions face recruitment competition from aerospace and industrial automation sectors.
- Certification Timeline Compression:EPA rule acceleration forces inverter validation cycles to compress from 48 months to 24 months without compromising ISO 26262 ASIL ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Inverters Market |
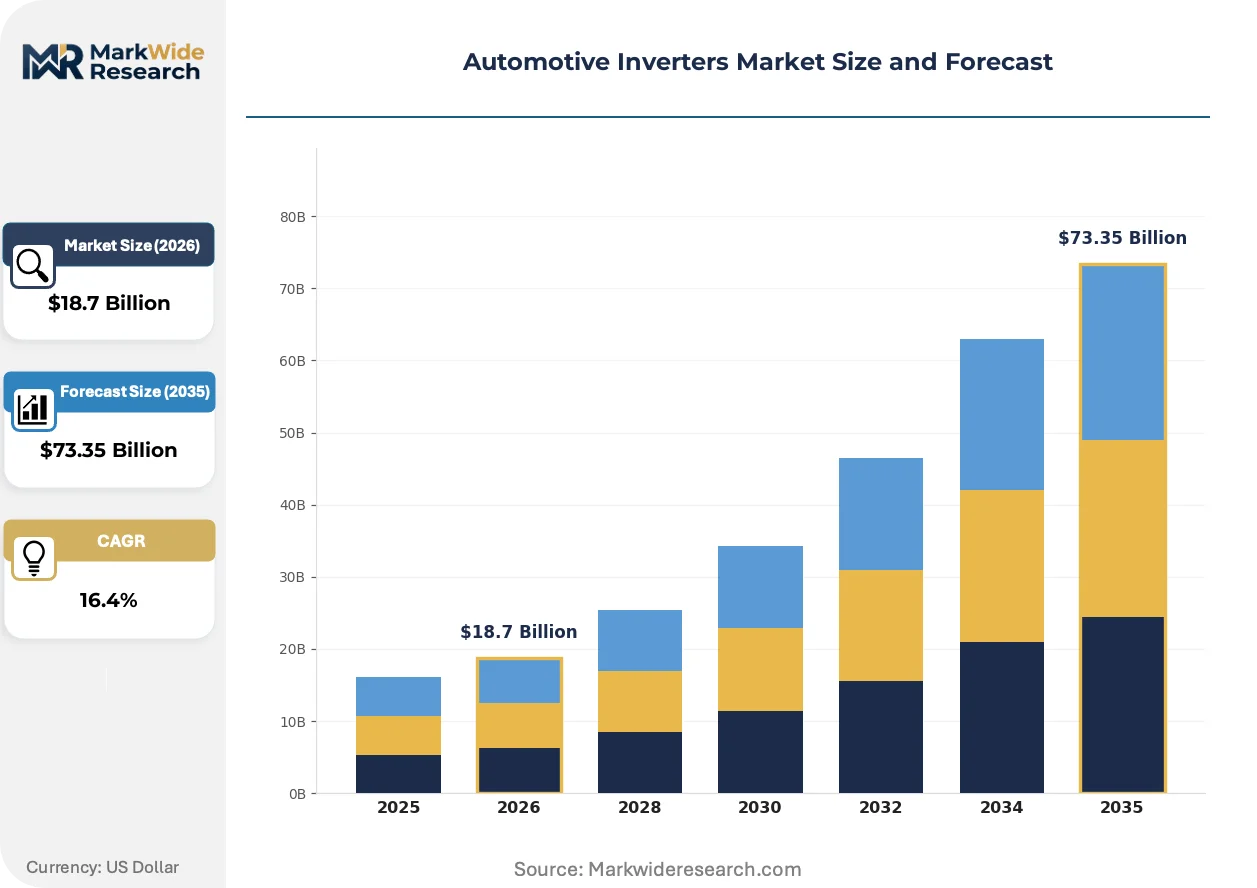
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Inverter, Onboard Inverter, Standalone Inverter, Auxiliary Inverter End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Pure Sine Wave, Modified Sine Wave, DC-DC Converter, Digital Inverter Application: Electric Vehicles, Hybrid Vehicles, Energy Storage Systems, Marine Applications |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Mitsubishi Electric Corporation, Continental AG, Valeo SA, Hitachi Automotive Systems, Toyota Industries Corporation, Infineon Technologies AG, Fuji Electric Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Inverters Market Strategic Shifts
Power semiconductor material transitions and functional safety standard evolution are rewriting inverter design priorities faster than traditional automotive supplier relationships can adapt.
Silicon carbide MOSFETs enable switching frequencies above 50 kHz with lower thermal losses than silicon IGBTs. Tier-1 suppliers are qualifying these devices for 800-volt electric vehicle platforms launching from 2025. The technology is rendering obsolete the discrete module assemblies that dominated 400-volt system architectures.
REACH substance restrictions in Europe now govern thermal interface compounds and encapsulation materials used in power modules. Manufacturers reformulating greases and gap pads to eliminate restricted substances face qualification delays. Battery inverter segments serving grid-tied storage applications absorb these compliance costs fastest due to margin structures.
Buyer concentration among OEMs integrating inverters into proprietary vehicle platforms is squeezing standalone module suppliers. Direct sourcing relationships between automakers and semiconductor foundries are displacing traditional Tier-1 assembly contracts. Germany and the United States exhibit this procurement pattern most acutely as domestic electric vehicle production scales.
Automotive Inverters Market Segmentation
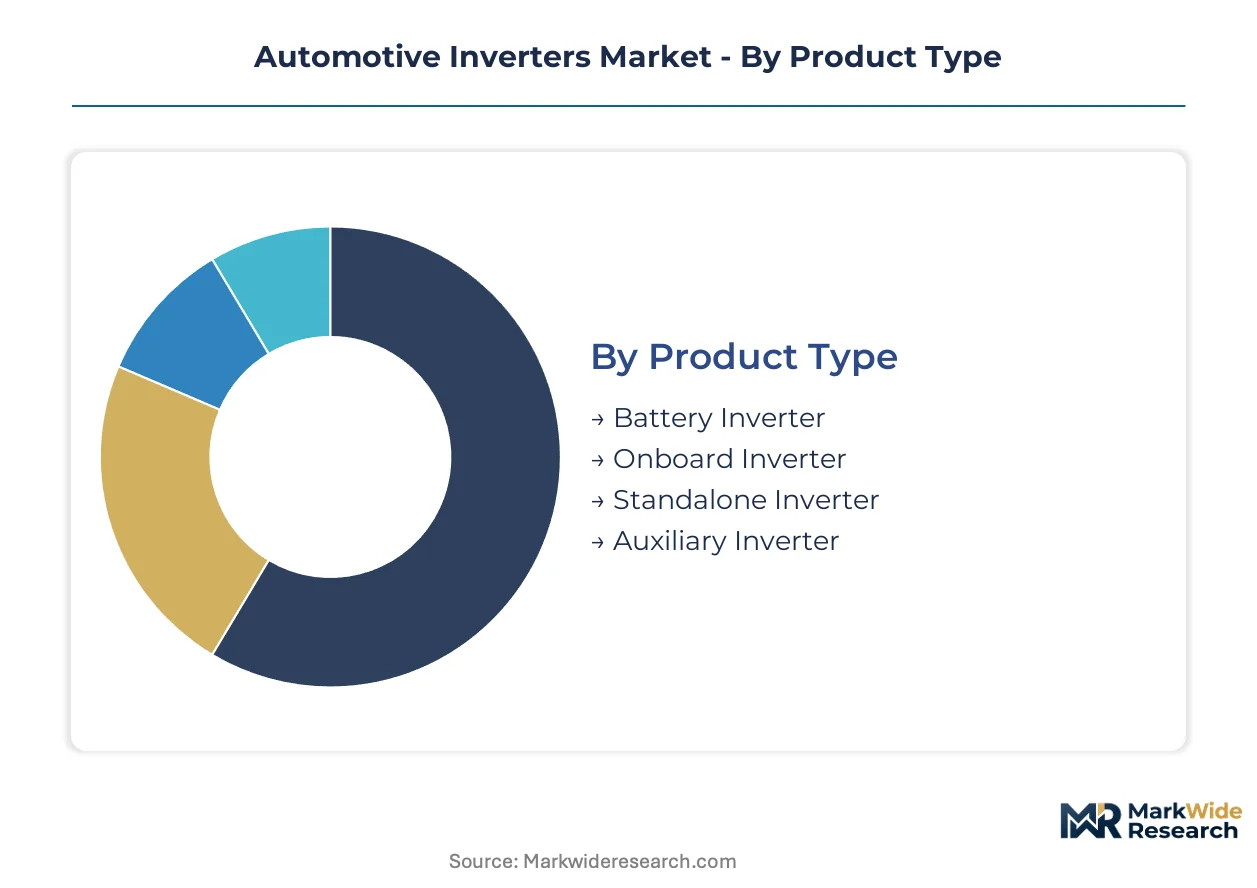
Automotive inverter segmentation reflects divergent power electronics requirements across vehicle electrification architectures. Each dimension captures distinct procurement patterns, semiconductor specifications, and thermal management constraints that reshape supplier positioning.
Product Type:
Power conversion functions span traction propulsion, auxiliary loads, and stationary energy interfaces with radically different duty cycles and efficiency thresholds.
- Onboard Inverter:Integrated propulsion electronics convert DC battery output to variable-frequency AC for traction motors, operating at 97%+ efficiency with liquid-cooled thermal management. Passenger EV platforms from OEMs in China, Germany, and the United States absorb the majority of new capacity as architectures consolidate power electronics into vehicle-integrated assemblies.
- Battery Inverter:Bidirectional power electronics enable DC-AC conversion for grid-tied energy storage with synchronization capabilities and extended voltage ranges. Energy storage system applications in California and Texas command premium positioning where grid interconnection standards from IEEE and local utilities impose stringent harmonic distortion limits.
- Standalone Inverter:Modular assemblies serve retrofit applications and specialty vehicle conversions with discrete packaging.
- Auxiliary Inverter:Lower-power units supply HVAC compressors, steering pumps, and thermal management subsystems.
Established volume favors Onboard Inverter; emerging adoption favors Battery Inverter.
End User:
Procurement concentration varies sharply between captive manufacturing and outsourced module assembly.
- OEMs:Automakers with proprietary EV platforms are bringing inverter design in-house, establishing direct foundry relationships for silicon carbide MOSFET supply. Tesla, BYD, and Volkswagen Group now specify their own gate driver architectures and thermal interface specifications.
- Tier-1 Suppliers:Bosch, Denso, and Continental retain high-volume contracts for hybrid platforms where power electronics integration demands established manufacturing scale. These suppliers compete on ISO 26262 functional safety certification and qualification speed.
- Vehicle Assemblers:Contract manufacturers absorb inverter module integration for emerging EV startups lacking power electronics engineering depth.
- Aftermarket Providers:Independent distributors serve conversion shops and fleet retrofits with limited warranty coverage.
Direct procurement is climbing the fastest among OEMs; outsourced manufacturing retains share in hybrid segments.
Technology:
Waveform fidelity and control architecture determine semiconductor switching strategies and filter component sizing.
- Pure Sine Wave:Low-harmonic output enables direct grid interconnection and sensitive motor control with minimal electromagnetic interference. EPA emissions compliance testing and FCC electromagnetic compatibility requirements in the United States mandate this architecture for vehicle-to-grid applications.
- Digital Inverter:Software-defined control loops enable over-the-air updates and adaptive switching frequency modulation. Silicon carbide MOSFET integration demands these control capabilities for gate timing precision at 50+ kHz operation.
- Modified Sine Wave:Simplified power stages serve cost-constrained auxiliary loads with acceptable harmonic content.
- DC-DC Converter:Voltage transformation stages bridge 400V and 800V architectures for compatibility with legacy charging infrastructure.
Regulatory pressure favors Pure Sine Wave; semiconductor transition favors Digital Inverter.
Application:
Duty cycle intensity and environmental exposure create divergent reliability specifications across mobility and stationary contexts.
- Electric Vehicles:Traction inverters endure continuous high-load operation with vibration resistance and automotive temperature grades. China's NEV subsidy programs and EPA fuel economy standards in the United States are forcing efficiency thresholds upward faster than traditional development cycles accommodate.
- Energy Storage Systems:Stationary battery inverters prioritize bidirectional power flow and grid-forming capabilities over power density. California's Title 24 building codes and Germany's EEG grid connection rules impose certification requirements that extend validation timelines.
- Hybrid Vehicles:Start-stop cycling and blended power modes demand wider operating temperature ranges.
- Marine Applications:Salt spray corrosion and shock resistance specifications exceed automotive grades.
Passenger electrification dominates unit volume; grid-tied storage offers steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe emissions rules in the United States are tightening efficiency floors faster than traditional automotive development cycles accommodate. Silicon carbide semiconductor transitions and passenger EV platform absorption are compressing inverter procurement timelines across major producing geographies. Demand concentrates where OEMs and Tier-1 suppliers maintain integrated manufacturing footprints.
China
Domestic capacity expansion for electric vehicle power electronics is absorbing the bulk of new inverter manufacturing investment. MIIT dual carbon goals and NEV subsidy programs are accelerating silicon carbide substrate qualification timelines. The Yangtze River Delta manufacturing cluster around Shanghai hosts the densest concentration of power module assembly operations serving BYD and domestic OEM platforms.
Germany
EMA transport electrification guidelines and REACH substance restrictions are layering compliance requirements onto thermal interface material specifications. KBA type-approval processes for 800-volt architectures are compressing validation cycles below 24 months. Bavaria and Baden-Württemberg host the core engineering clusters where Bosch and Continental maintain captive inverter design capabilities.
United States
EPA fuel economy standards and NHTSA functional safety requirements are forcing inverter efficiency thresholds above 97 percent. The Inflation Reduction Act domestic content provisions are reshaping semiconductor procurement patterns for Detroit Three EV platforms. Michigan and Texas manufacturing corridors concentrate Tier-1 module assembly capacity serving integrated OEM propulsion architectures.
Japan
METI carbon neutrality roadmaps are accelerating hybrid and battery electric vehicle inverter refresh cycles. JIS standards for electromagnetic compatibility are tightening gate driver integration specifications. The Nagoya industrial corridor anchors Denso and Toyota Industries manufacturing scale for hybrid platform power electronics.
South Korea
MFDS automotive electromagnetic compatibility oversight and national EV adoption targets are driving inverter platform consolidation. Seoul Capital Area engineering clusters are specializing in digital inverter control architectures for 800-volt systems. Hyundai-Kia integrated platform strategies are concentrating procurement within domestic supply chain partnerships.
Automotive Inverters Market Competitive Environment
Capability concentration sits with semiconductor foundries and gate driver specialists; scale advantage sits with integrated Tier-1 module assemblers. The market structures around three tiers: captive OEM design houses, high-volume Tier-1 suppliers, and specialist semiconductor vendors. Dominant archetypes include silicon carbide substrate suppliers, functional safety certification holders, and thermal management system integrators. Competitive moves center on backward integration into wafer supply and accelerated ISO 26262 qualification timelines.
Among German-based diversified industrials, Robert Bosch GmbH and Continental AG occupy positions spanning module assembly through system integration. Denso Corporation exemplifies the captive Tier-1 model anchored to hybrid platform scale. Infineon Technologies AG represents the semiconductor archetype supplying wide-bandgap devices to multiple module assemblers. These three entities illustrate the capability-scale tension reshaping procurement relationships as OEMs bring inverter design in-house.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Continental AG |
| Valeo SA |
| Hitachi Automotive Systems |
| Toyota Industries Corporation |
| Infineon Technologies AG |
| Fuji Electric Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide wafer supply concentration in Japan and the United States determines both pricing tier spreads across automotive inverter modules and supply chain shape as Tier-1 assemblers negotiate long-term offtake agreements versus spot market exposure.
Pricing Analysis
China and Germany exhibit the widest price spreads for automotive inverters, with domestic Chinese manufacturing commanding 15-20 percent discounts against German-engineered modules due to integrated silicon carbide substrate capacity and lower thermal interface material compliance costs. The market operates on a contract-based long-term offtake structure with volume-scale and ISO 26262 certification level as the primary price differentiation drivers. Cost compression in standard-grade silicon IGBT modules is intensifying because Chinese OEMs are absorbing in-house production capacity. Fleet procurement teams at commercial vehicle operators demonstrate the highest price sensitivity, while energy storage system integrators absorb premiums for grid-synchronization capabilities.
Supply Chain Analysis
Silicon carbide wafer feedstock draws from Japan, the United States, and China, with epitaxial layer processing concentrated in Taiwan and South Korea before module assembly in Germany and China. Raw material dependencies include high-purity silicon carbide substrates, silver sintering pastes, and REACH-compliant thermal interface compounds. Single-source vulnerability around 150mm silicon carbide wafer supply from Japanese foundries creates procurement risk for European Tier-1 suppliers expanding 800-volt platform capacity. Distribution runs through direct OEM foundry relationships and Tier-1 module assembler contracts, with aftermarket channels serving limited retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
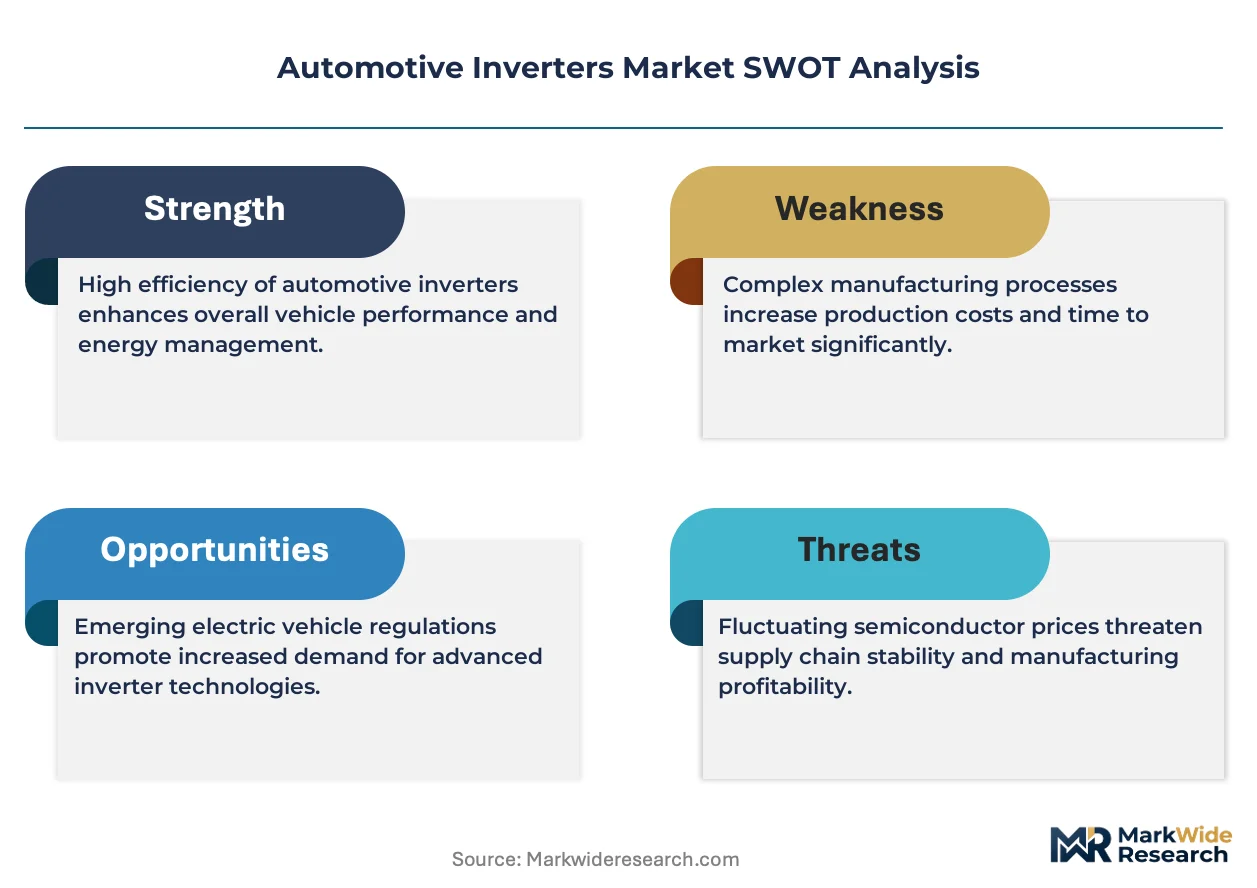
OEM vertical integration into inverter design is consolidating buyer power, with proprietary platform strategies at Tesla, BYD, and Volkswagen Group displacing traditional Tier-1 supply relationships and compressing supplier margins.
For Market Incumbents: Pre-empt semiconductor supply bottlenecks by securing captive silicon carbide wafer allocations through joint ventures with Japanese or American substrate manufacturers before EPA fuel economy standard acceleration locks in 800-volt platform commitments. Accelerate ISO 26262 ASIL-D certification timelines to defend against emerging Chinese module assemblers competing on qualification speed rather than functional safety depth. For New Entrants and Emerging Players: India's nascent electric vehicle power electronics manufacturing base offers the most penetrable geographic entry point, with domestic OEMs lacking in-house inverter engineering depth and government PLI scheme subsidies offsetting initial capital requirements. Target grid-tied battery inverter applications in Texas and California where IEEE 1547 interconnection standards create certification barriers that favor specialized engineering over manufacturing scale. Pursue white-label manufacturing partnerships with Korean digital inverter control specialists to bypass gate driver integration expertise gaps. For Investors and Strategic Acquirers: EPA tailpipe emissions rule acceleration reshapes the acquisition landscape toward functional safety certification holders and silicon carbide gate driver IP owners rather than pure-play module assemblers. Position portfolios for a 5-10 year window where backward integration into wafer supply separates viable suppliers from margin-compressed assemblers. Watch for MIIT dual carbon goal enforcement intensity as the signal indicating whether Chinese domestic capacity expansion becomes export-competitive or remains captive to local OEM demand.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Locks in substrate access before EPA rules accelerate 800-volt platform adoption. |
| ISO 26262 Certification Investment | Creates differentiable credential as NHTSA functional safety requirements harden. |
| Geographic Manufacturing Footprint | Positions assembly capacity within IRA domestic content corridors for Detroit Three supply. |
| Software-Defined Control Architecture | Enables over-the-air gate timing updates for silicon carbide MOSFET precision at 50+ kHz. |
| Grid Interconnection Partnership | Opens vehicle-to-grid revenue streams under California Title 24 and Germany EEG frameworks. |
Study Parameters
The analysis maps traction inverter, battery inverter, auxiliary inverter, and standalone inverter sub-sectors, each validated through OEM platform engineers, Tier-1 supplier procurement leads, semiconductor foundry account managers, and energy storage system integrators. Primary interview data triangulates against secondary sources including EPA fuel economy standard filings, MIIT NEV subsidy program disclosures, IHS Markit vehicle production databases, and REACH substance restriction updates from ECHA. Bottom-up unit volume estimates from semiconductor substrate shipments reconcile with top-down OEM platform absorption forecasts.
Assumptions held fixed include EPA tailpipe emissions rule enforcement timelines and silicon carbide substrate yield rates at major foundries; variables tested include Chinese NEV subsidy extension scenarios and German KBA type-approval cycle compression. Segmentation dimensions modeled span propulsion architecture, voltage class, semiconductor technology, and regional production cluster. CAGRs derive from logistic diffusion curves fitted to OEM platform launch schedules and foundry capacity expansion announcements, with switching cost dynamics and regulatory compliance burden as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese OEMs or accelerated EPA rulemaking would shift outcomes beyond modeled ranges. Cross-checking against IEA electric vehicle deployment benchmarks and MIIT power electronics capacity utilization disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Module-Level Power Electronics (MLPE) Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Traction Inverter Market
Power Systems
Pulse Generator Market
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Harmonic Generators Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Series Reactor Market
Power Systems
Linear Voltage Regulators Market
Power Systems
Integrated UPS Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Global DC Power Supply Module Market