
 Electric Vehicle Power Inverter Market | 2026-2036
Electric Vehicle Power Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Power Inverter Market Analysis
China is narrowing the cost gap between silicon IGBT and silicon carbide MOSFET inverter platforms through aggressive capacity build-outs in Ningbo and Shenzhen manufacturing corridors. Mitsubishi Electric Corporation leverages its power module heritage to sustain high-voltage inverter leadership across Japanese and Southeast Asian OEM supply chains. Robert Bosch GmbH anchors European demand with integrated axle-drive systems that embed inverter, motor, and gearbox in single housings.
An electric vehicle power inverter converts direct current from the battery pack into alternating current for the traction motor, typically operating at switching frequencies between 10 kHz and 20 kHz to optimize motor efficiency and thermal losses. Central inverter architectures dominate high-volume passenger EV platforms where packaging constraints and economies of scale favor consolidated power electronics, while multilevel inverter technology is gaining traction in heavy-duty commercial vehicles seeking superior waveform quality for extended motor life. OEM captive production of in-house inverter systems is reshaping supplier relationships, with torque coupling and DSP controlled platforms representing distinct engineering bets across the technology landscape.
The EPA tailpipe emission standards and NHTSA fuel economy mandates in the United States compel automakers to electrify powertrains, directly expanding inverter specification volumes in vehicle program planning. China's MIIT new energy vehicle credit system and GB/T charging standards enforce domestic content ratios that favor locally certified inverter suppliers. Stakeholders must monitor semiconductor substrate supply commitments and qualification timelines for next-generation wide-bandgap materials as these decisions will determine competitive positioning in the coming product cycles.
Market Dynamics
Silicon carbide semiconductor transitions are compressing thermal management tolerances while expanding power density ceilings across supplier engineering roadmaps, forcing simultaneous material science and packaging architecture bets.
Growth Catalysts
- MIIT NEV Credit System:China's mandatory production quotas for new energy vehicles compel domestic OEMs to vertically integrate powertrain electronics, directly expanding certified inverter procurement pipelines.
- Mass Transit Electrification:Urban bus fleet operators in Shenzhen, Ningbo, and Chengdu are specifying high-voltage inverters with extended duty cycles, creating dedicated procurement categories separate from passenger vehicle programs.
- Silicon Carbide Substrates:Wide-bandgap material adoption at switching frequencies above 15 kHz reduces thermal losses and enables compact packaging for 800-volt battery architectures.
Market Restraints
- Substrate Supply Concentration:Silicon carbide wafer production clusters in specific manufacturing corridors, creating qualification bottlenecks for second-source approval timelines.
- IGBT Cost Asymmetry:Mature silicon insulated-gate bipolar transistor supply chains maintain price advantages in 400-volt platforms, delaying full platform transitions for cost-sensitive vehicle segments.
- GB/T Certification Friction:China's domestic content enforcement requires localized testing protocols that extend supplier onboarding cycles for non-Chinese inverter manufacturers.
Strategic Opportunities
- Heavy-Duty Commercial Vehicles:Multilevel inverter architectures for extended motor life are penetrating long-haul trucking and construction equipment segments previously dominated by mechanical powertrains.
- Integrated Axle-Drive Systems:Convergence of inverter, motor, and gearbox into single housings creates value-capture opportunities for suppliers with mechatronics integration capabilities.
- EPA Tailpipe Standards:US emission mandates compel powertrain electrification timelines that expand inverter specification volumes in Detroit and Tennessee manufacturing footprints.
Industry Challenges
- Wide-Bandgap Talent Scarcity:Power electronics engineers with silicon carbide device physics expertise command premium compensation, constraining R&D team scaling for mid-tier suppliers.
- Dual Sourcing Complexity:OEMs requiring redundant semiconductor substrate commitments face extended qualification timelines that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Power Inverter Market |
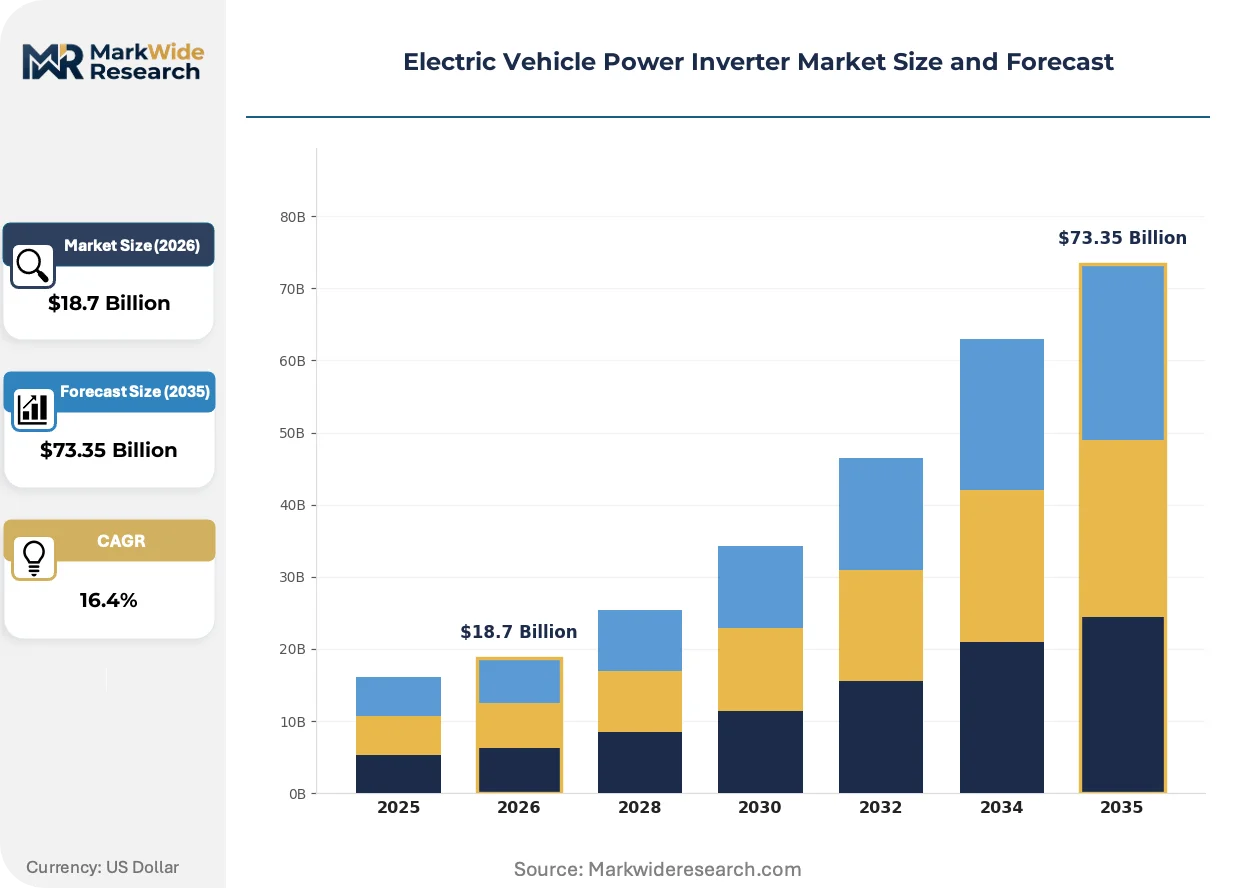
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Central Inverter, Micro Inverter, String Inverter, Hybrid Inverter Technology: Torque Coupling, PWM, DSP Controlled, Multilevel Inverter End User: OEMs, Electric Vehicle Manufacturers, Aftermarket Suppliers, Fleet Operators Installation: Onboard, Offboard, Residential, Commercial |
| Companies Covered | Mitsubishi Electric Corporation, Hitachi Astemo, Inc., Robert Bosch GmbH, Vitesco Technologies, Valeo SA, Continental AG, BorgWarner Inc., Toyota Industries Corporation, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Power Inverter Market Emerging Trajectories
Power semiconductor material transitions and inverter architecture consolidation are simultaneously enabling higher voltage platforms while compressing supplier value capture windows across the technology stack.
Silicon carbide MOSFET technology operates at switching frequencies between 15 kHz and 20 kHz with substantially lower switching losses than silicon alternatives. Heavy-duty commercial vehicle manufacturers in Germany and Japan are adopting these devices for 800-volt traction systems ahead of passenger vehicle programs. Higher frequency operation is rendering obsolete traditional liquid cooling architectures that dominated 400-volt IGBT inverter designs.
The EU Green Deal's automotive CO2 performance standards mandate fleet-average emission reductions that compel powertrain electrification timelines across Stuttgart, Wolfsburg, and Munich manufacturing centers. Industrial consequence includes accelerated inverter specification in vehicle program planning with compressed development cycles. Premium passenger EV platforms are most affected, responding with centralized inverter architectures that consolidate power electronics for packaging efficiency.
Fleet operators are unbundling after-sales service contracts from hardware procurement, creating separate performance-based maintenance agreements with inverter subsystem specialists. Direct contracting with power electronics service providers is displacing traditional OEM-captive service networks in California and Texas commercial vehicle deployments. This pattern is most visible in urban bus electrification programs where uptime guarantees drive specification criteria.
Electric Vehicle Power Inverter Market Segmentation
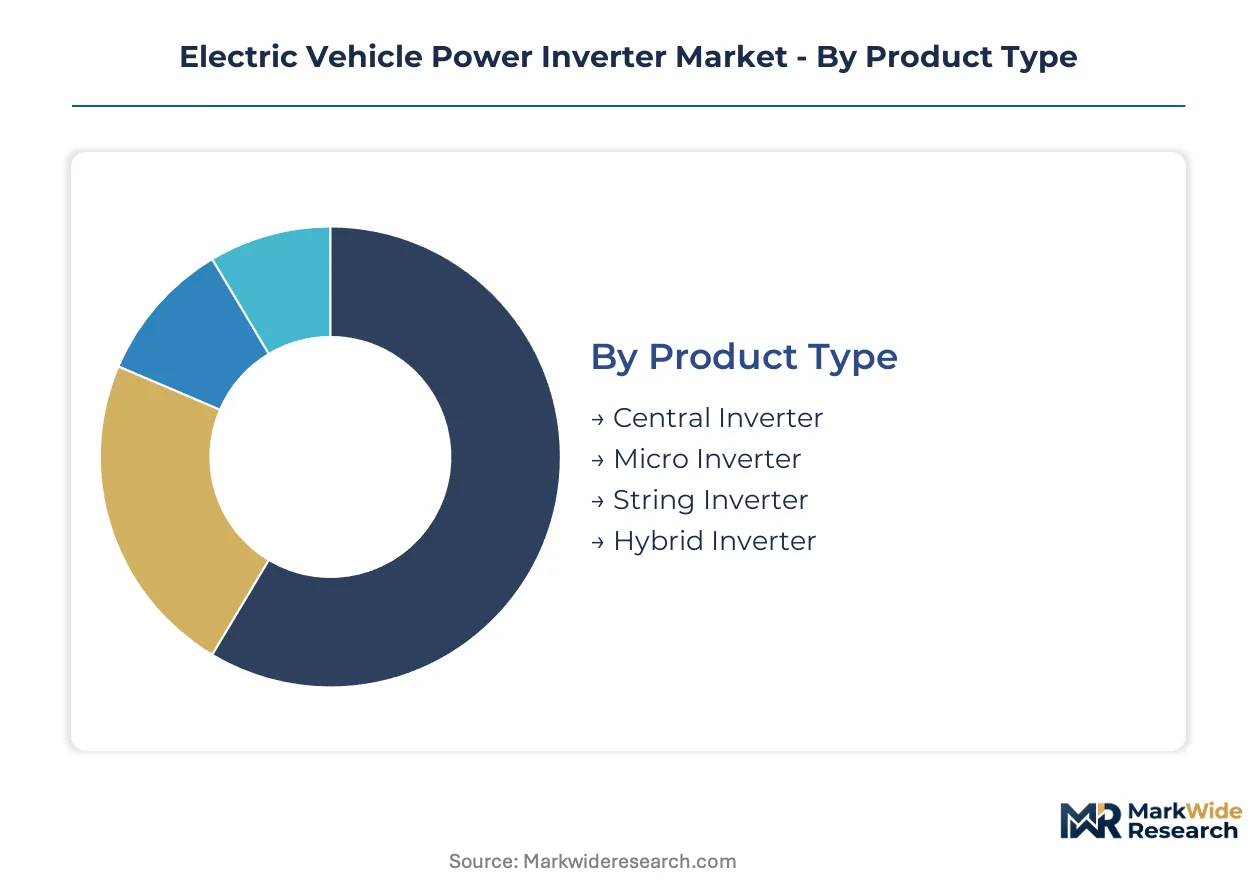
Power inverter segmentation reveals how engineering specifications, procurement channels, and deployment contexts fragment demand across distinct commercial pathways. Each dimension carries unique margin profiles and qualification barriers that reshape supplier positioning.
Product Type:
Cost tier differentiation separates consolidated high-volume platforms from distributed architectures serving specialized applications.
- Central Inverter:Single consolidated unit manages full battery-to-motor power conversion for passenger EV platforms. Demand concentrates in high-volume Chinese OEM programs where packaging efficiency and economies of scale dominate procurement criteria. GB/T certification requirements favor domestically qualified suppliers for these high-unit deployments.
- Micro Inverter:Modular distributed units enable granular power management across individual motor windings or auxiliary systems. Fleet operators in California commercial vehicle deployments specify these for uptime-critical applications where fault isolation prevents full-system shutdowns.
- String Inverter:Intermediate aggregation architecture balancing modularity with component count reduction. European integrated axle-drive suppliers embed these in heavy-duty commercial vehicle platforms.
- Hybrid Inverter:Dual-mode units accommodating both battery DC and range-extender or fuel cell inputs. Japanese OEMs specify these for transitional powertrain architectures bridging full electrification timelines.
Central Inverter commands the established base. The steepest expansion runs through Hybrid Inverter.
Technology:
Control methodology and switching topology determine thermal performance ceilings and semiconductor material compatibility.
- Torque Coupling:Direct mechanical-electrical integration linking inverter output to motor torque response with minimal intermediate processing. German commercial vehicle manufacturers specify these for construction equipment requiring precise load-matching.
- PWM:Pulse-width modulation at fixed carrier frequencies between 10 kHz and 15 kHz dominates mature silicon IGBT implementations. Cost-sensitive 400-volt passenger platforms in India sustain procurement volumes despite efficiency limitations.
- DSP Controlled:Digital signal processor architectures enable adaptive switching algorithms optimizing efficiency across variable load conditions. Silicon carbide MOSFET pairings in 800-volt systems leverage these control platforms for thermal loss reduction.
- Multilevel Inverter:Cascaded voltage-stepping topologies deliver superior waveform quality reducing motor insulation stress. Long-haul trucking electrification in the United States drives specification for extended motor life in high-mileage duty cycles.
PWM retains the volume base. DSP Controlled is climbing the fastest as wide-bandgap transitions accelerate.
End User:
Customer type fragmentation creates divergent procurement patterns across captive production, tiered supply, and direct service contracting.
- OEMs:Vertically integrated automakers specifying in-house or contract-manufactured inverter systems for proprietary powertrain programs. Chinese domestic OEMs dominate this channel through MIIT credit system compliance requirements.
- Electric Vehicle Manufacturers:Dedicated EV producers without legacy ICE infrastructure, prioritizing rapid platform development cycles. These buyers favor modular inverter architectures enabling faster vehicle program iteration.
- Aftermarket Suppliers:Independent service and replacement part providers addressing warranty extensions and retrofits. California and Texas fleet operators increasingly contract directly with these specialists for performance-based maintenance agreements.
- Fleet Operators:Large-scale vehicle purchasers unbundling hardware procurement from service contracts. Urban bus electrification in Shenzhen and Chengdu creates dedicated procurement categories with uptime guarantee specifications.
OEMs anchor current procurement volumes. Fleet Operators are gaining share fastest as service unbundling spreads.
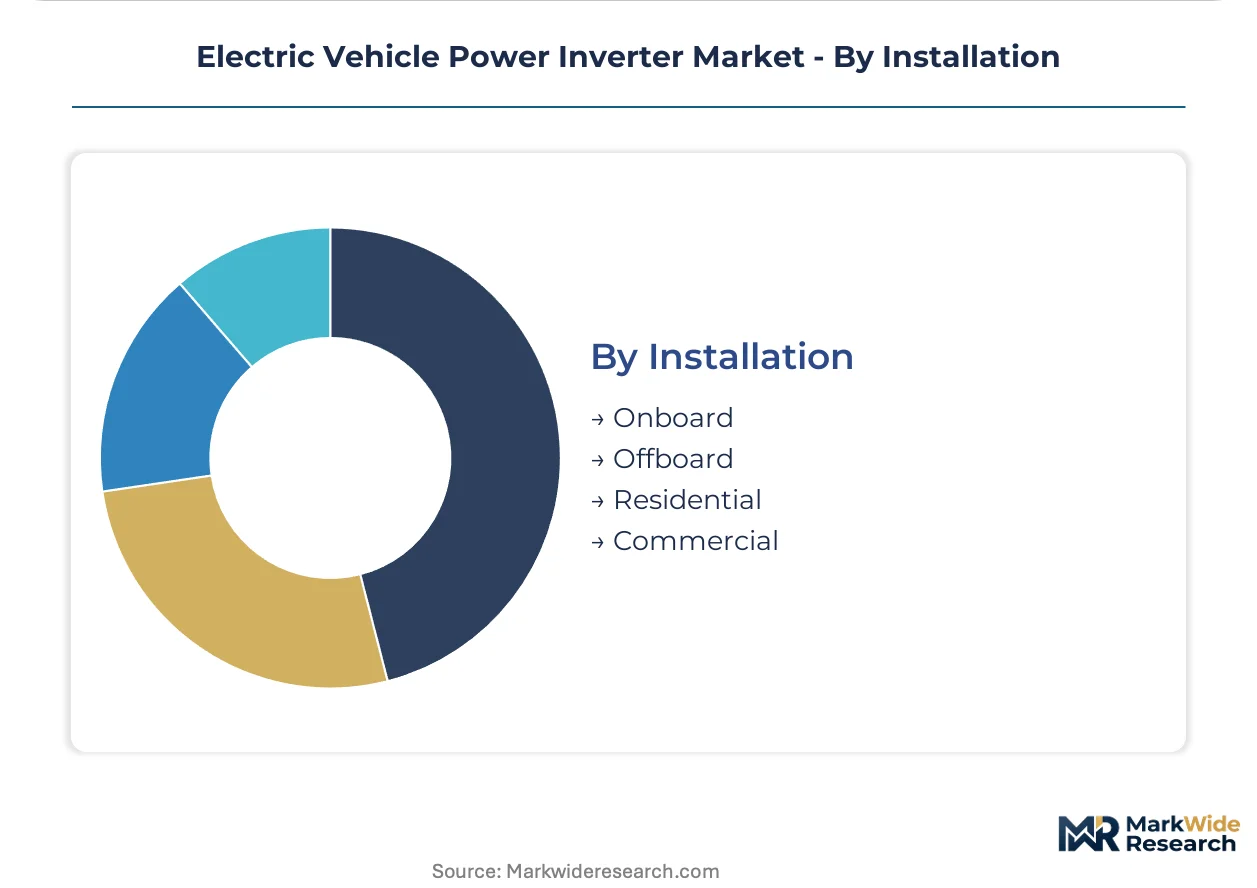
Installation:
Deployment context determines environmental sealing, thermal management, and grid-interconnection requirements.
- Onboard:Vehicle-integrated units operating within powertrain thermal envelopes and vibration specifications. All passenger EV platforms require these, with 800-volt architectures demanding redesigned cooling circuits.
- Offboard:Stationary charging infrastructure inverters converting grid AC to battery-compatible DC. China's GB/T charging standard enforcement shapes supplier qualification for these deployments.
- Residential:Home-based charging systems with lower power ratings and simplified thermal management. European markets with dense urban housing stock show concentration in compact wall-mounted units.
- Commercial:Fleet depot and public charging installations with extended duty cycles and higher power throughput. EPA tailpipe standards indirectly expand these specifications as commercial vehicle electrification accelerates.
Onboard installations hold the dominant position. Commercial is expanding most quickly as depot electrification scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication clusters in Ningbo and Shenzhen concentrate silicon carbide substrate capacity, creating geographic lock-in effects that ripple through downstream inverter assembly networks. Supplier qualification timelines now hinge on proximity to these manufacturing corridors.
China
Domestic OEMs in Shenzhen and Chengdu are scaling vertically integrated powertrain production to satisfy MIIT new energy vehicle credit quotas. GB/T certification standards enforce local testing protocols that extend onboarding cycles for foreign suppliers. Ningbo manufacturing corridors anchor silicon carbide wafer capacity build-outs that narrow cost gaps against silicon IGBT alternatives.
Germany
Stuttgart and Wolfsburg manufacturing centers face EU Green Deal automotive CO2 mandates that compress powertrain electrification timelines. KBA type-approval requirements shape inverter specification criteria for integrated axle-drive systems. Bavaria-based suppliers embed multilevel architectures in heavy-duty commercial vehicle platforms seeking extended motor life.
United States
Detroit and Tennessee manufacturing footprints expand inverter procurement volumes under EPA tailpipe emission standards and NHTSA fuel economy mandates. California fleet operators unbundle service contracts from hardware procurement, creating direct contracting channels with power electronics specialists. Texas commercial vehicle deployments drive performance-based maintenance agreements with aftermarket providers.
Japan
METI industrial policy supports wide-bandgap semiconductor transitions across Nagoya and Tokyo supplier networks. Toyota Industries Corporation and Denso Corporation leverage captive power module heritage to sustain high-voltage inverter leadership. Southeast Asian OEM supply chains source from Japanese engineering roadmaps prioritizing thermal management innovation.
South Korea
Seoul Capital Area battery manufacturers coordinate 800-volt architecture transitions with inverter suppliers switching to silicon carbide MOSFET platforms. MFDS regulatory alignment with international standards accelerates qualification timelines for export-oriented production. Busan-Ulsan industrial complexes concentrate thermal packaging expertise for high-frequency switching applications.
Electric Vehicle Power Inverter Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in semiconductor and thermal management layers. The supplier base organizes around three archetypes: diversified automotive conglomerates with captive power electronics divisions, dedicated powertrain suppliers pursuing mechatronics convergence, and semiconductor substrate specialists extending downstream into module assembly. Capacity expansion in wide-bandgap materials and strategic partnerships for integrated axle-drive architectures dominate competitive maneuvering.
Among diversified conglomerates, Mitsubishi Electric Corporation and Robert Bosch GmbH occupy positions that exemplify divergent geographic strategies. Hitachi Astemo, Inc. sits within the dedicated powertrain tier alongside Vitesco Technologies, representing the specialist archetype focused on integrated system solutions. These companies anchor competitive dynamics without dictating uniform technology roadmaps across the supplier landscape.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Hitachi Astemo, Inc. |
| Robert Bosch GmbH |
| Vitesco Technologies |
| Valeo SA |
| Continental AG |
| BorgWarner Inc. |
| Toyota Industries Corporation |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Ningbo and Shenzhen manufacturing corridors concentrate silicon carbide wafer capacity, compressing substrate costs and redistributing pricing power toward vertically integrated OEMs with captive supply commitments. GB/T certification requirements and MIIT credit system enforcement create tiered procurement access that separates qualified domestic suppliers from higher-cost foreign entrants.
Pricing Analysis
MIIT NEV credit system dictates the pricing tier structure across the Electric Vehicle Power Inverter Market, stratifying procurement access by certification status and domestic content ratios. Three-tier pricing separates GB/T-certified premium platforms from standard-grade silicon IGBT implementations and economy-tier refurbished units. Price differentiation rests on semiconductor substrate grade and thermal management complexity. Cost compression in 400-volt silicon IGBT segments is intensifying because mature supply chains face utilization pressure from wide-bandgap transitions. Fleet operators in Shenzhen urban bus programs exhibit lowest price sensitivity due to uptime guarantee requirements, while Indian passenger EV platforms remain most cost-conscious.
Supply Chain Analysis
Hon Hai Precision Industry and BYD Electronic hold contract-manufacturing concentration for power module assembly, anchoring downstream capacity allocation decisions. Geographic supply concentrates in China, South Korea, and Japan for semiconductor substrates, thermal interface materials, and magnetics. Raw material dependencies draw from silicon carbide wafers, copper busbars, and ceramic substrates. Single-source vulnerability runs through Ningbo wafer fabrication clusters where qualification bottlenecks delay second-source approvals. Distribution runs through OEM captive channels, tiered supplier networks, and direct fleet contracting in California and Texas commercial vehicle deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle Power Inverter Market rewards engineering teams with silicon carbide device physics expertise, a capability pool that remains thin relative to platform electrification timelines. This scarcity elevates compensation premiums and constrains R&D scaling for mid-tier suppliers.
For Market Incumbents: Build captive substrate commitments as a moat against qualification bottlenecks. Secure long-term silicon carbide wafer offtake agreements with Ningbo corridor producers before second-source windows close. Invest in DSP control platform R&D to maintain thermal efficiency leadership as switching frequencies rise above 15 kHz. Channel control through integrated axle-drive system partnerships protects margin position against modular disruptors. For New Entrants and Emerging Players: Establish a beachhead in aftermarket service contracting for California and Texas commercial vehicle fleets. Unbundled performance-based maintenance agreements represent the most penetrable channel where OEM-captive networks face displacement. Target micro inverter architectures for uptime-critical applications where fault isolation commands premium positioning. Go-to-market leverage rests on direct fleet relationships bypassing traditional tiered supply hierarchies. For Investors and Strategic Acquirers: Long-term, this sits as a materials-scarcity play because silicon carbide substrate capacity expansion trails powertrain electrification demand across the analysis window. Acquisition target archetype: power electronics specialists with qualified thermal packaging expertise and existing GB/T certification pathways. Monitor semiconductor equipment order backlogs at Ningbo fabrication facilities as the inflection signal for supply constraint duration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Capacity Expansion | Ningbo corridor build-outs narrow cost gaps against silicon IGBT alternatives for 800-volt platforms. |
| Integrated Axle-Drive System Development | Robert Bosch GmbH anchors European demand with consolidated inverter-motor-gearbox housings. |
| GB/T Certification Investment | Domestic content enforcement extends supplier onboarding cycles for non-Chinese manufacturers. |
| Aftermarket Service Network Buildout | California fleet operators increasingly contract directly with power electronics specialists. |
| DSP Control Platform R&D | Adaptive switching algorithms optimize efficiency for silicon carbide MOSFET pairings. |
Methodological Framework
Cross-validation between primary fieldwork with OEM platform engineers and secondary validation through vehicle production databases anchors the qualitative findings in the Electric Vehicle Power Inverter Market. Primary interviews covered Tier 1 supplier procurement leads, thermal packaging specialists, semiconductor substrate planners, fleet operations managers, and aftermarket service directors. Secondary sources included MIIT production quota disclosures, EPA tailpipe standard filings, GB/T certification registries, and IHS Markit vehicle registration data. Bottom-up segment sizing triangulates against top-down powertrain electrification forecasts.
Calibration against historical silicon IGBT adoption curves and wide-bandgap transition timelines in rail and renewable applications shaped the analytical framework. Segmentation dimensions modeled include inverter architecture type, semiconductor material platform, vehicle class, propulsion voltage tier, and regional regulatory cluster. CAGRs derive from unit volume build-ups multiplied by content-per-vehicle estimates, cross-checked against OEM procurement pipeline disclosures. Forecast inputs incorporate MIIT credit system enforcement trajectories and EPA rulemaking comment period submissions.
Stress conditions across silicon carbide wafer yield rates, GB/T certification timeline extensions, and IGBT cost asymmetry persistence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about powertrain electrification mandates and semiconductor capacity expansion schedules. Quarterly review of Ningbo corridor equipment order backlogs and MIIT NEV credit price trajectories is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
EV Power Module Market
Power Systems
String Inverter Market
Power Systems
Automotive Power Electronics Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Integrated UPS Market
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
Burner Management System (BMS) Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Battery Equalizer Market
Power Systems
Photovoltaic Inverters Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
MOSFET and IGBT Gate Driver Market
Power Systems
South America DC Distribution Network Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
USB Power Adapters Market