
 Bypass Thyristor Market | 2026-2036
Bypass Thyristor Market Size, Share, and Industry Trends Forecast 2026-2036
Bypass Thyristor Market Insights
Multi-source procurement for silicon wafers and specialty packaging is pivoting toward captive supply arrangements among tier-one vendors. WeEn Semiconductors Co., Ltd leverages integrated fabrication capabilities across China to control wafer costs. Mitsubishi Electric Corporation anchors its position through proprietary gate-commutated thyristor architectures for HVDC applications. Vishay Intertechnology competes via broad distribution reach and standardized product platforms serving industrial automation.
A bypass thyristor is a high-power semiconductor switch fabricated from silicon or silicon carbide, rated for blocking voltages exceeding several kilovolts and conducting currents above one kiloampere, designed to provide a parallel current path that protects sensitive power electronics from overvoltage or fault conditions. Fast Recovery Thyristors command premium positioning in motor drives and inverter applications where rapid turn-off minimizes energy dissipation. Silicon Carbide Technology is displacing conventional silicon in renewable energy systems, though gallium nitride alternatives remain confined to lower-voltage consumer electronics segments. Standard Thyristors sustain volume leadership in mature lighting control and industrial power supply installations where cost sensitivity outweighs efficiency gains.
FERC grid reliability standards and China's GB/T national standards for ultra-high-voltage equipment shape product certification requirements and testing protocols for bypass thyristor suppliers seeking utility procurement eligibility. The EU Green Deal's decarbonization targets for power transmission infrastructure are tightening efficiency benchmarks that favor advanced semiconductor materials over legacy silicon designs. Stakeholders must monitor substrate supply constraints and qualification timelines for wide-bandgap technologies as procurement specifications evolve.
Market Dynamics
Silicon carbide substrate maturation is compressing qualification timelines for next-generation bypass thyristors while China's State Grid Corporation accelerates ultra-high-voltage procurement cycles. This dual pressure is forcing incumbent silicon suppliers to defend position through cost restructuring rather than performance parity.
Growth Catalysts
- HVDC transmission expansion:China's GB/T standards for ultra-high-voltage equipment mandate bypass thyristor protection in new converter stations, creating procurement pull from grid operators in India and Brazil pursuing similar infrastructure.
- Renewable integration mandates:The EU Green Deal's decarbonization targets for power transmission infrastructure require semiconductor upgrades that favor advanced materials over legacy silicon in offshore wind interconnect projects.
- Silicon carbide thermal performance:Wolfspeed and II-VI substrate advances enable 200°C junction temperatures, reducing cooling system footprint in desert solar installations and subsea cable terminations.
Market Restraints
- Substrate supply concentration:Six-inch silicon carbide wafer output remains captive to three dominant suppliers, creating allocation risk for thyristor fabricators qualifying wide-bandgap designs.
- FERC reliability compliance costs:Grid interconnection standards require 18-month type testing protocols that extend product launch timelines and freeze engineering resources.
- Gallium nitride voltage ceiling:GaN devices remain confined to sub-650V applications, blocking substitution in kilovolt-class bypass protection despite superior switching frequency.
Strategic Opportunities
- India transmission buildout:Power Grid Corporation of India targets 12,000 km of HVDC lines by 2030, creating first-mover advantage for suppliers establishing local testing partnerships.
- Modular converter architectures:Distributed power electronics in data center uninterruptible power supplies enable bypass thyristor penetration in megawatt-scale commercial installations previously served by mechanical breakers.
- Japan METI hydrogen corridor funding:Electrolyzer rectifier protection requirements align with thyristor fault-current handling characteristics, opening industrial demand outside traditional grid applications.
Industry Challenges
- Wide-bandgap packaging thermal cycling:Ceramic substrate attachment processes require vacuum brazing expertise scarce outside Japanese and German supplier bases.
- Legacy thyristor qualification drag:Utilities specify 30-year service life guarantees that conflict with silicon carbide reliability data spanning only 10-15 years of field operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bypass Thyristor Market |
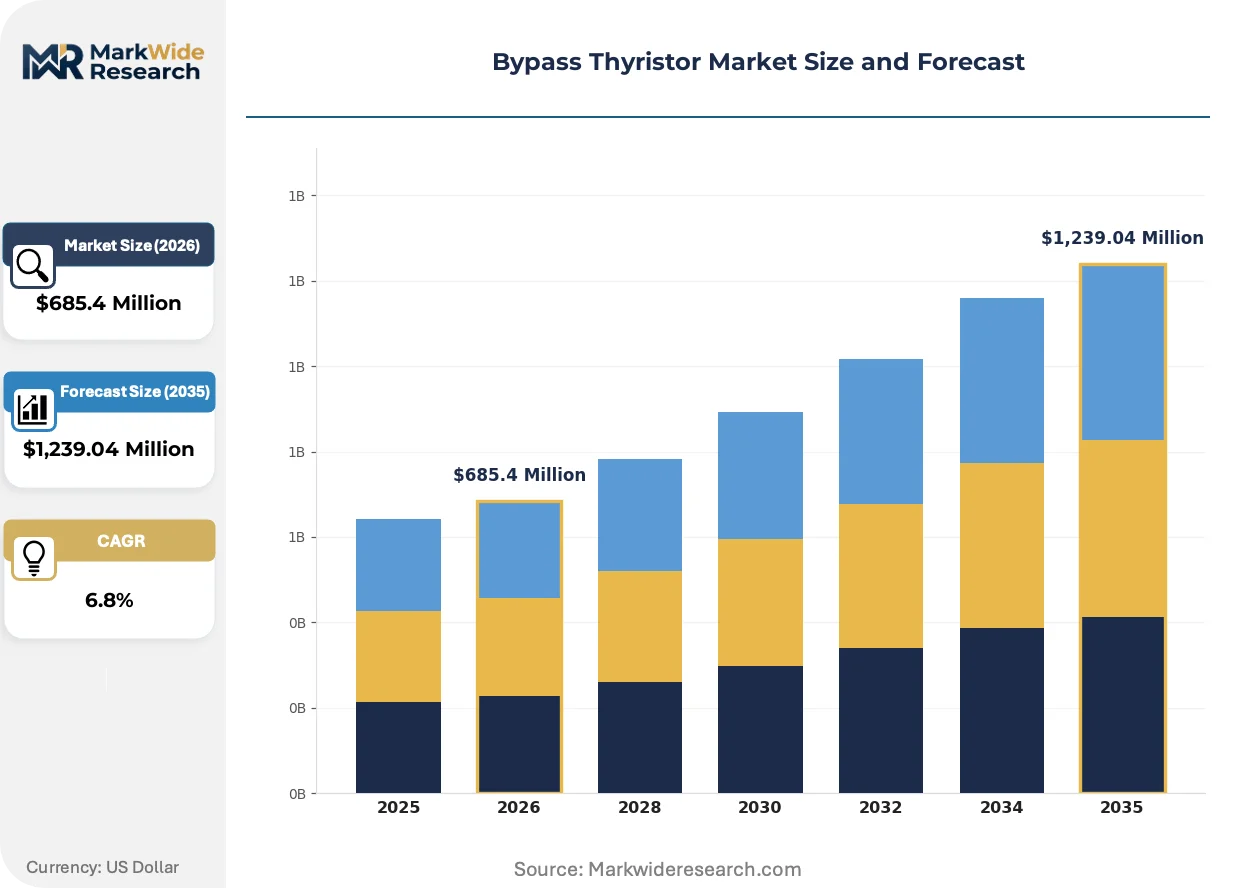
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Thyristors, Fast Recovery Thyristors, Light-Triggered Thyristors, Controlled Thyristors Application: Motor Drives, Power Supplies, Lighting Control, Renewable Energy Systems End User: Industrial Automation, Consumer Electronics, Automotive, Aerospace Technology: Silicon Technology, Silicon Carbide Technology, Gallium Nitride Technology, Others |
| Companies Covered | WeEn Semiconductors Co., Ltd, Littelfuse, Semikron Danfoss, Fuji Electric Co., Ltd, Dynex Semiconductor, Hitachi Energy, Mitsubishi Electric Corporation, Solid State Manufacturing, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bypass Thyristor Market Trends and Innovations
Material science breakthroughs and procurement centralization are restructuring competitive position in high-power semiconductor protection. Three converging developments are compressing product lifecycles and redrawing vendor relationships.
Silicon carbide epitaxy is automating the transition from 150mm to 200mm wafer processing, enabling foundries to pattern twice as many thyristor dice per substrate. Mitsubishi Electric and WeEn Semiconductors are qualifying 6.5kV SiC modules for motor drive inverters, replacing silicon press-pack devices in 3MW-class applications. This substrate scaling is automating cost parity with silicon in 3.3kV and above ratings by compressing die cost trajectories faster than equipment depreciation schedules assumed.
The EU F-Gas Regulation's phasedown of sulfur hexafluoride insulating gas is forcing HVDC converter station redesigns that eliminate sealed-tank thyristor valve halls. Station designers at Siemens Energy and Hitachi Energy are specifying open-rack air-insulated thyristor assemblies with enhanced environmental sealing. European transmission system operators in Germany and Italy are absorbing 15-20% capital cost premiums to comply with 2030 phase-out deadlines, redirecting procurement specifications toward modular outdoor designs.
Consolidated procurement through China's State Grid Corporation and India's Power Grid Corporation is compressing vendor qualification from six suppliers to three preferred partners per voltage class. These central buyers now mandate joint technology development agreements with semiconductor fabricators, replacing arm's-length component purchasing. The procurement compression is most visible in 800kV ultra-high-voltage projects where single-source thyristor valve contracts exceed $50 million, forcing European and Japanese suppliers to establish local joint ventures or forfeit eligibility.
Bypass Thyristor Market Segmentation
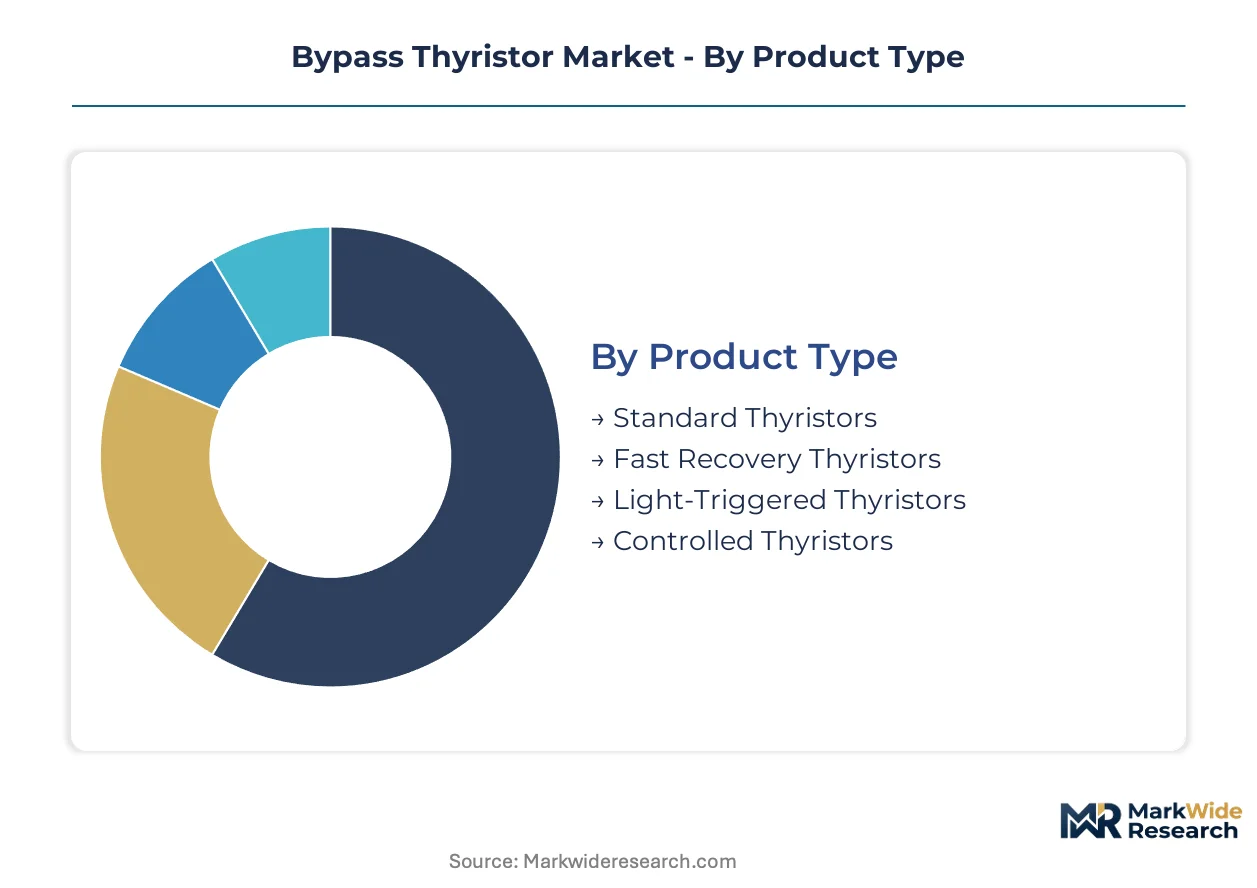
Bypass thyristor procurement patterns diverge sharply between standalone protection modules and embedded converter systems, with integration depth determining specification priorities and supplier relationships. Understanding these structural divisions reveals where silicon carbide substitution accelerates versus where legacy silicon maintains cost advantages.
Product Type:
Standalone protection modules require discrete thyristor assemblies with independent gate drivers, while embedded converter designs integrate protection functions into larger valve structures with shared control architectures.
- Standard Thyristors:Silicon-based devices rated for 1.2kV to 6.5kV blocking voltages with microsecond-scale turn-off times. Mature industrial power supply installations in Germany and Italy specify these for cost-sensitive lighting control and heating applications where efficiency gains cannot justify wide-bandgap premiums.
- Fast Recovery Thyristors:Optimized for sub-10-microsecond reverse recovery through platinum or electron irradiation doping profiles. Motor drive inverters above 1MW in Japan's steel and chemical sectors demand these for reduced switching losses during frequent start-stop cycles.
- Light-Triggered Thyristors:Optical gate firing eliminates electromagnetic interference in ultra-high-voltage valve halls. China's State Grid Corporation mandates these for 800kV converter stations where electrical isolation between control and power stages is non-negotiable.
- Controlled Thyristors:Integrated gate-commutated architectures enabling forced commutation without external circuits. HVDC line-commutated converters in India's Power Grid Corporation expansion projects utilize these for enhanced fault-current limiting.
Standard Thyristors lead volumes today; Fast Recovery Thyristors are gaining share fastest.
Application:
Cost tier stratification separates premium-positioned renewable integration from mature industrial segments where price-per-ampere dominates procurement scoring.
- Motor Drives:Variable-frequency drives above 500kW require press-pack thyristor assemblies with double-sided cooling. Germany's automotive manufacturing base and Japan's precision machinery sectors drive specification toward 6.5kV modules with integrated freewheeling diodes.
- Power Supplies:Uninterruptible power systems and industrial rectifiers specify phase-control thyristors for AC line regulation. Data center operators in the United States and Germany are absorbing 15-20% capital premiums for modular outdoor designs eliminating sulfur hexafluoride insulation.
- Lighting Control:Phase-angle dimming circuits in commercial buildings utilize low-voltage thyristor pairs. This segment sustains volume through replacement demand in Europe's existing building stock rather than new construction.
- Renewable Energy Systems:Solar inverters and wind turbine converters demand wide-bandgap protection for desert and offshore environments. Silicon carbide thermal performance enables 200°C junction temperatures that reduce cooling system footprint in subsea cable terminations.
Power Supplies dominate installed base; Renewable Energy Systems are expanding most quickly.
End User:
Customer type concentration shapes procurement centralization, with utility-scale grid operators consolidating vendor qualification while fragmented industrial buyers sustain distributor channels.
- Industrial Automation:Factory automation and process control systems specify thyristor modules for motor soft-starters and heating controls. Germany's mechanical engineering export base and Japan's robotics manufacturers drive demand for 1.2kV to 2.5kV standard devices with standardized footprints.
- Consumer Electronics:Limited to low-power applications below 1kV where thyristors have ceded ground to MOSFETs and IGBTs. Universal power adapters and dimmer switches represent residual demand concentrated in cost-optimized Asian manufacturing.
- Automotive:Traction inverter protection and onboard charger circuits specify automotive-grade thyristors with extended temperature cycling qualification. Electric vehicle platforms in Germany and Japan are testing silicon carbide alternatives for 800V architectures.
- Aerospace:Satellite power conditioning and aircraft starter-generator systems require radiation-hardened and high-reliability screening. This segment commands premium pricing through specialized testing protocols despite low unit volumes.
Industrial Automation anchors current procurement; Automotive is climbing the fastest.
Technology:
Substrate supply concentration constrains migration timelines, with six-inch silicon carbide wafer output captive to three dominant suppliers creating allocation risk for qualifying fabricators.
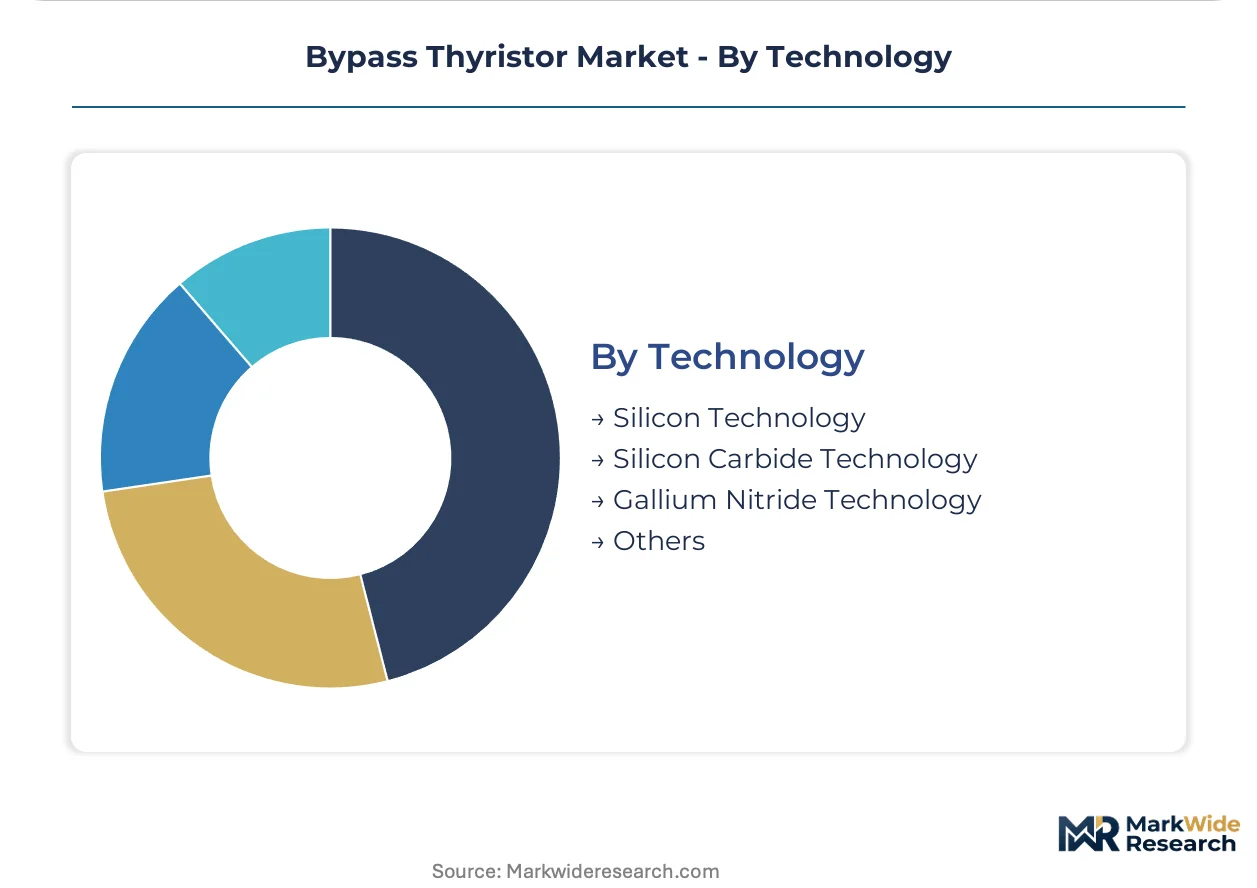
- Silicon Technology:Mature epitaxial growth and diffusion processes yield consistent 6.5kV blocking capability. China's State Grid Corporation and India's Power Grid Corporation specify these for 30-year service life guarantees where silicon carbide reliability data remains insufficient.
- Silicon Carbide Technology:4H-SiC substrates enable 10kV-class thyristors with tenfold switching loss reduction. Wolfspeed and II-VI supply advances are compressing cost parity timelines for 3.3kV and above ratings through 200mm wafer scaling.
- Gallium Nitride Technology:Confined to sub-650V applications by fundamental material limits on critical electric field strength. Consumer power adapters and low-voltage motor drives represent addressable market boundaries.
- Others:Emerging wide-bandgap candidates including gallium oxide and diamond substrates remain in research phase with no commercial thyristor products qualified for grid or industrial applications.
Silicon Technology maintains volume leadership; Silicon Carbide Technology shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters dominate bypass thyristor procurement, with China's State Grid Corporation and India's Power Grid Corporation driving ultra-high-voltage transmission investments. European utilities accelerate silicon carbide adoption under decarbonization mandates. North American data center operators reshape demand for modular power protection systems.
China
State Grid Corporation procurement for 800kV converter stations consumes the majority of light-triggered thyristor output. GB/T national standards for ultra-high-voltage equipment mandate bypass protection in all new HVDC installations. Xiangjiaba-Shanghai and Jinping-Sunan transmission corridors anchor demand concentration in the Yangtze River Delta manufacturing belt.
India
Power Grid Corporation targets 12,000 km of HVDC lines by 2030, creating sustained demand for controlled thyristor architectures. Central Electricity Authority technical standards require fault-current protection in renewable energy evacuation infrastructure. Gujarat and Maharashtra host the principal converter station construction clusters.
Germany
Siemens Energy and Hitachi Energy specify open-rack air-insulated thyristor assemblies to comply with EU F-Gas Regulation phase-out deadlines. Industrial automation demand from Baden-Württemberg's automotive manufacturing base sustains standard thyristor volumes. Bavaria's data center corridor absorbs premium modular protection systems.
Japan
METI hydrogen corridor funding drives electrolyzer rectifier protection requirements outside traditional grid applications. Kansai region steel and chemical sectors specify fast recovery thyristors for 1MW-plus motor drive inverters. Tokyo Electric Power and Chubu Electric integrate advanced protection in offshore wind interconnect projects.
United States
FERC grid reliability standards impose 18-month type testing protocols that extend product launch timelines for domestic suppliers. Texas and California data center operators deploy megawatt-scale uninterruptible power supplies with modular thyristor protection. PJM Interconnection procurement specifications favor established silicon designs over wide-bandgap alternatives.
Bypass Thyristor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue silicon carbide qualification and captive substrate supply. The vendor base stratifies across three tiers: integrated fabricators with in-house wafer production, module assemblers dependent on external die supply, and specialized packaging houses serving aerospace and radiation-hardened niches. Dominant competitive moves include backward integration into silicon carbide epitaxy and joint venture formation with Chinese grid operators to secure procurement eligibility.
Among Asia-Pacific-based fabricators, WeEn Semiconductors Co., Ltd and Mitsubishi Electric Corporation exemplify the integrated production archetype, while Vishay Intertechnology occupies a position emphasizing broad distribution reach. These three entities represent distinct strategic postures: captive supply chain control, proprietary device architectures, and standardized platform scale respectively.
| Leading Market Players |
|---|
| WeEn Semiconductors Co., Ltd |
| Littelfuse |
| Semikron Danfoss |
| Fuji Electric Co., Ltd |
| Dynex Semiconductor |
| Hitachi Energy |
| Mitsubishi Electric Corporation |
| Solid State Manufacturing |
| Vishay Intertechnology |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate costs cascade through bypass thyristor pricing tiers, with six-inch wafer premiums from Wolfspeed and II-VI compressing margins at 3.3kV and above ratings while China's State Grid Corporation procurement volumes extract volume discounts from captive suppliers.
Pricing Analysis
Input-cost pass-through from silicon carbide epitaxy runs through three distinct pricing tiers. Premium positioning commands GB/T certification and 30-year service life guarantees for ultra-high-voltage projects, while standard silicon devices compete on price-per-ampere in industrial automation. Pricing pressure intensifies as silicon carbide approaches cost parity at 6.5kV ratings, forcing legacy suppliers into restructuring. Industrial automation buyers exhibit highest price sensitivity; grid operators absorb premiums for reliability assurance.
Supply Chain Analysis
GB/T and FERC qualification gating concentrates supply among fabricators with 18-month type testing capabilities. Taiwan, China, and Japan anchor wafer processing and packaging operations. The supply chain draws from silicon carbide substrates, ceramic packaging materials, and specialized gate driver electronics. Single-source vulnerability persists in six-inch SiC wafer output from three dominant suppliers. Distribution runs through direct procurement contracts with State Grid Corporation and Power Grid Corporation, supplemented by distributor channels for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's sulfur hexafluoride phase-out compounds demand for open-rack thyristor assemblies, creating procurement pull that rewards early qualification.
For Market Incumbents: Deploy backward integration into silicon carbide epitaxy to secure substrate allocation and defend position against emerging SiC specialists. Mitsubishi Electric and WeEn Semiconductors demonstrate this through captive wafer production. Accelerate joint venture formation with Chinese grid operators to maintain procurement eligibility as vendor consolidation compresses qualification slots. Counter gallium nitride substitution threats by emphasizing kilovolt-class fault-current handling where GaN voltage ceilings block entry. For New Entrants and Emerging Players: Digital-channel partnerships with industrial automation distributors offer low-friction market entry beneath consolidated utility procurement. India's Power Grid Corporation 12,000 km HVDC expansion presents the most penetrable geography for suppliers establishing local testing partnerships. Target modular data center UPS protection as a white-space application where mechanical breaker displacement creates new demand. Pursue METI hydrogen corridor funding alignment for electrolyzer rectifier protection outside traditional grid verticals. For Investors and Strategic Acquirers: Consolidation pressure builds where silicon carbide qualification timelines exceed 24 months and substrate supply remains captive to three suppliers. Long-term viability favors fabricators with demonstrated FERC and GB/T certification track records across multiple voltage classes. Acquisition target archetype: mid-cap packaging specialists with vacuum brazing expertise scarce outside Japanese and German supplier bases. Watch silicon carbide reliability data maturation as the signal for 30-year guarantee eligibility and subsequent procurement specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Epitaxy Integration | Wolfspeed and II-VI substrate advances enable cost parity compression at 3.3kV and above ratings. |
| Joint Venture Formation with Grid Operators | State Grid Corporation procurement consolidation mandates local partnerships for ultra-high-voltage contract eligibility. |
| Open-Rack Assembly Qualification | EU F-Gas Regulation compliance redirects Siemens Energy and Hitachi Energy specifications toward modular outdoor designs. |
| Local Testing Partnership Establishment | Power Grid Corporation of India procurement requires domestic qualification facilities for HVDC line protection. |
| Vacuum Brazing Capability Acquisition | Ceramic substrate attachment expertise scarcity in wide-bandgap packaging creates defensive moat for qualified suppliers. |
Research Methodology
Direct dialogue with HVDC project engineers, semiconductor procurement managers at grid operators, thyristor packaging specialists, and power electronics R&D directors grounded qualitative findings. Secondary validation drew from FERC reliability standard filings, GB/T national standard documentation, SEC 10-K disclosures from listed fabricators, and EIA transmission infrastructure data. Bottom-up unit economics triangulated against top-down grid investment forecasts across the analysis window.
Segment-level outputs reflect modeled trajectories by product type, application, end user, and technology substrate across the projection horizon. CAGRs derived from installation volume build-ups tied to State Grid Corporation and Power Grid Corporation procurement pipelines, silicon carbide wafer scaling curves, and F-Gas Regulation compliance timelines. Forecast inputs incorporated HVDC line-kilometer expansion targets, converter station thyristor valve counts, and wide-bandgap substitution elasticity assumptions.
Substrate supply disruption, regulatory timeline acceleration, and silicon carbide reliability data maturation are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in GB/T or FERC certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Electrical and Automation System Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Low Voltage Drives Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
Global DC Power Supply Module Market
Power Systems
MOSFET and IGBT Gate Driver Market
Power Systems
Flyback Transformer Market
Power Systems
DC Power Supplies Market
Power Systems
Micro-Inverter Market
Power Systems
Thyristor Market
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
Battery Racks Market