
 DC-DC Converter Market | 2026-2036
DC-DC Converter Market Size, Share, and Industry Trends Forecast 2026-2036
DC-DC Converter Market Intelligence
China's expanding manufacturing capacity is fragmenting the competitive landscape for power components. This shift creates opportunities for both established and specialized firms. Texas Instruments leverages its extensive analog and embedded processing portfolio to offer integrated solutions. Vicor Corporation specializes in high-performance, high-density power modules for demanding applications, while Delta Electronics competes on manufacturing scale and system-level power solutions.
A DC-DC converter is an electronic circuit that converts a source of direct current from one voltage level to another. These devices utilize switching regulators with components like inductors and capacitors to achieve high efficiency in power conversion. Within product types, non-isolated converters dominate volume due to their use in consumer electronics. Isolated converters, however, are critical for safety and noise reduction in telecommunications equipment and industrial control systems, commanding higher margins.
Regulatory compliance is a critical design constraint, governed by standards such as the EU's CE marking for safety and RoHS for hazardous substances. In the United States, FCC regulations on electromagnetic interference (EMI) dictate shielding and layout requirements for converters. The key decision for designers will be balancing the trade-offs between higher switching frequencies for smaller size and managing the associated EMI and thermal challenges.
Market Dynamics
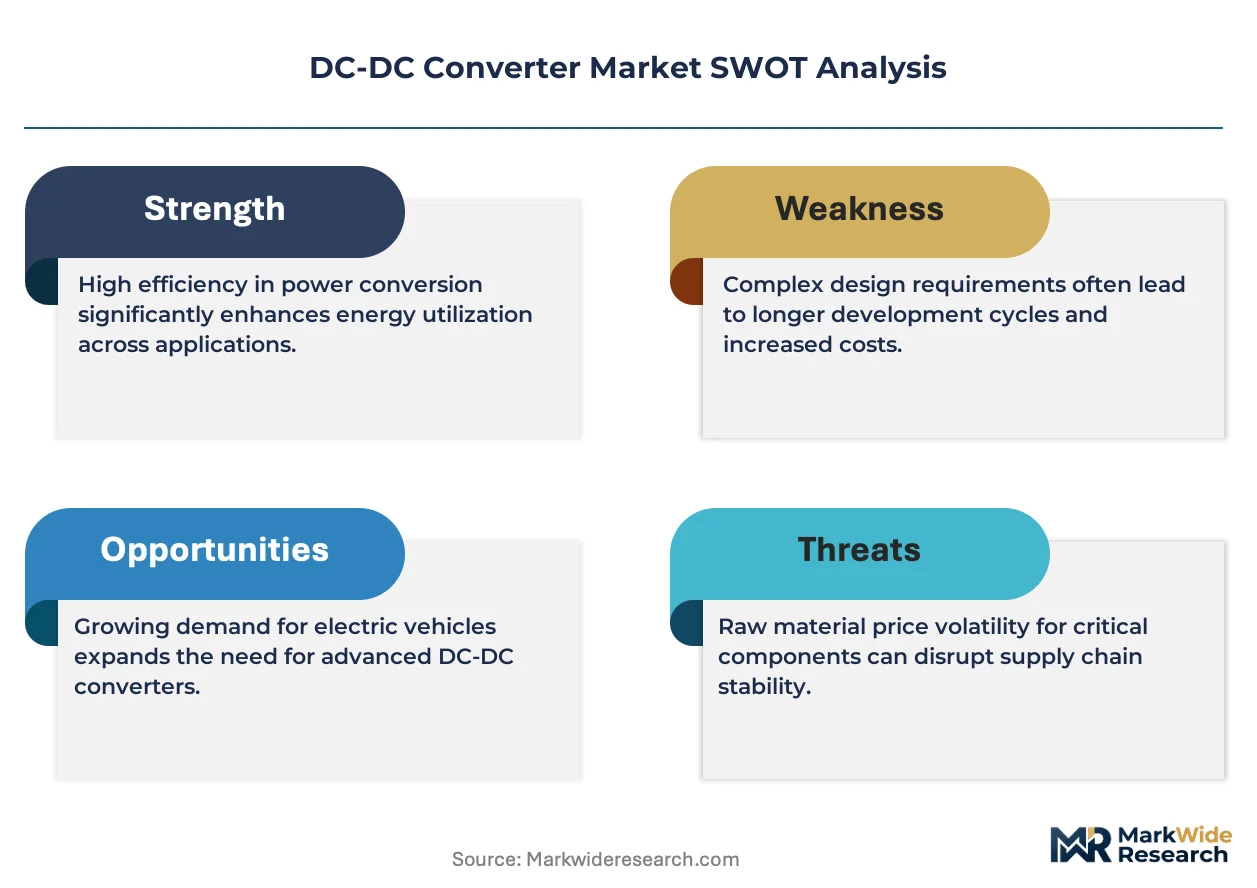
The central dynamic shaping the DC-DC converter market is the persistent engineering tension between the drive for higher power density and the fundamental thermal and electromagnetic challenges this creates, forcing innovation in materials, topology, and packaging.
Growth Catalysts
- Wide-Bandgap Semiconductors:The adoption of Gallium Nitride (GaN) and Silicon Carbide (SiC) materials enables converters to operate at higher frequencies and temperatures, significantly boosting efficiency and reducing physical size for applications in data centers and electric vehicles.
- 5G Infrastructure Expansion:The global deployment of 5G base stations and related telecommunications equipment requires a massive volume of high-efficiency, isolated DC-DC converters to power radio units and processing hardware reliably.
- Automotive Electrification:The transition to electric and hybrid vehicles creates substantial demand for a wide range of DC-DC converters to manage power between the main high-voltage battery and the low-voltage auxiliary systems that run lights, infotainment, and controls.
Market Restraints
- Raw Material Volatility:The cost and supply of key materials, including copper for magnetic windings and specialized ceramics for capacitors, are subject to significant price fluctuations, impacting manufacturer margins and product pricing stability.
- EMI Management Complexity:Higher switching frequencies, while enabling smaller converter sizes, generate more electromagnetic interference (EMI), requiring more complex and costly filtering and shielding solutions to meet FCC and CE regulations.
- Technical Miniaturization Limits:As converters shrink, thermal management becomes a primary constraint, with heat dissipation limiting the achievable power density without resorting to expensive, complex cooling systems or exotic packaging materials.
Strategic Opportunities
- 48V Data Center Architectures:The shift to 48V power distribution within data center racks presents a significant opportunity for intermediate bus converters and direct conversion technologies that improve system efficiency and reduce distribution losses.
- Digital Power Management:Integrating digital controllers and PMBus communication into converters allows for real-time monitoring, control, and optimization of power systems, creating value in complex applications like industrial automation and advanced computing.
- Renewable Energy Systems:Growth in distributed energy resources, particularly in solar and energy storage systems in markets like India and Australia, opens new applications for specialized DC-DC converters used for maximum power point tracking and battery management.
Industry Challenges
- Power Electronics Talent Gap:A persistent shortage of engineers with specialized skills in high-frequency magnetics design, advanced control loop theory, and EMI/EMC compliance engineering constrains new product development and innovation across the industry.
- Safety Certification Timelines:Achieving certifications such as IEC 60601-1 for medical devices or ISO 26262 for automotive applications is a lengthy and expensive process, creating a high barrier to entry and delaying the introduction of new technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DC-DC Converter Market |
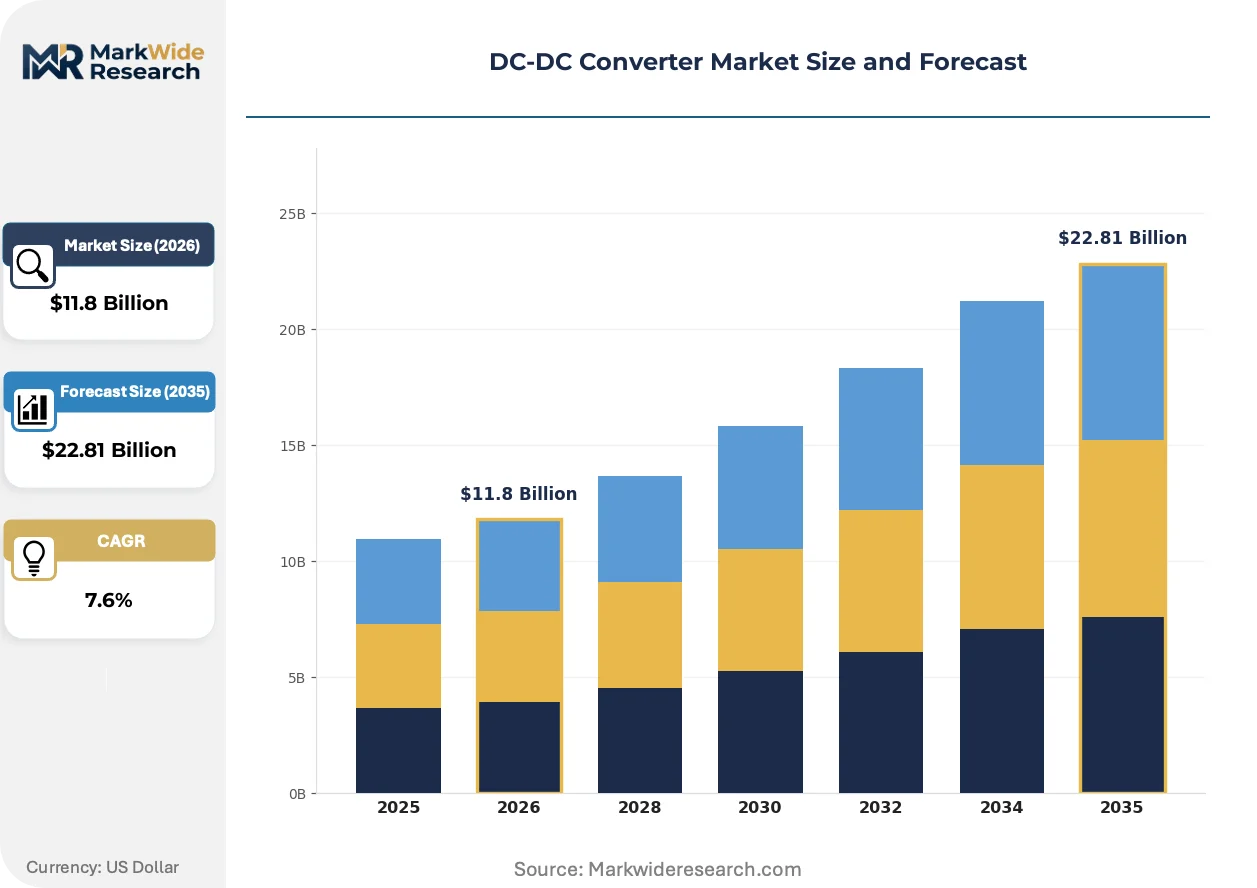
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $22.81 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolated Converter, Non-Isolated Converter, Adjustable Output Converter, Fixed Output Converter Technology: Buck Converter, Boost Converter, Buck-Boost Converter, Cuk Converter, SEPIC Converter Application: Consumer Electronics, Telecommunications Equipment, Industrial Control Systems, Aerospace & Defense, Renewable Energy Systems End User: OEMs, Electronic Manufacturing Services, Aftermarket Suppliers, Research & Development Labs |
| Companies Covered | Texas Instruments Incorporated, Delta Electronics, CET Technology, Vicor Corporation, TDK Lambda Corporation, Pico Electronics, Infineon Technologies AG, NXP Semiconductor, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DC-DC Converter Market Strategic Shifts & Innovations
The market's evolution is defined by the dual pursuit of greater power density and embedded intelligence. Converters are transitioning from simple power-conversion components into digitally controlled subsystems that are critical for overall system performance and efficiency.
Wide-bandgap materials like Gallium Nitride (GaN) are enabling breakthroughs in converter performance by allowing for much higher switching frequencies. System architects in the telecommunications and server industries are leading adoption to shrink power supply footprints. This technological shift is hybridizing traditional silicon MOSFET-based designs with new GaN components to achieve efficiency and density levels that were previously unattainable.
European Union Ecodesign requirements for external power supplies are compelling a move toward more sophisticated and efficient converter topologies. The regulation effectively mandates minimum efficiency levels and no-load power consumption, forcing the obsolescence of older, less efficient designs. This trend most directly impacts the high-volume consumer electronics and IT equipment segments, accelerating the adoption of synchronous rectification and quasi-resonant control ICs.
A notable behavioral shift involves system engineers increasingly opting for pre-certified, modular DC-DC converters over designing with discrete components. This approach outsources the complexity of power design, shortens product development cycles, and reduces compliance risks. This procurement pattern is most visible in the industrial controls and medical instrumentation sectors, where time-to-market and proven reliability outweigh the per-unit cost savings of a discrete design.
DC-DC Converter Market Segmentation
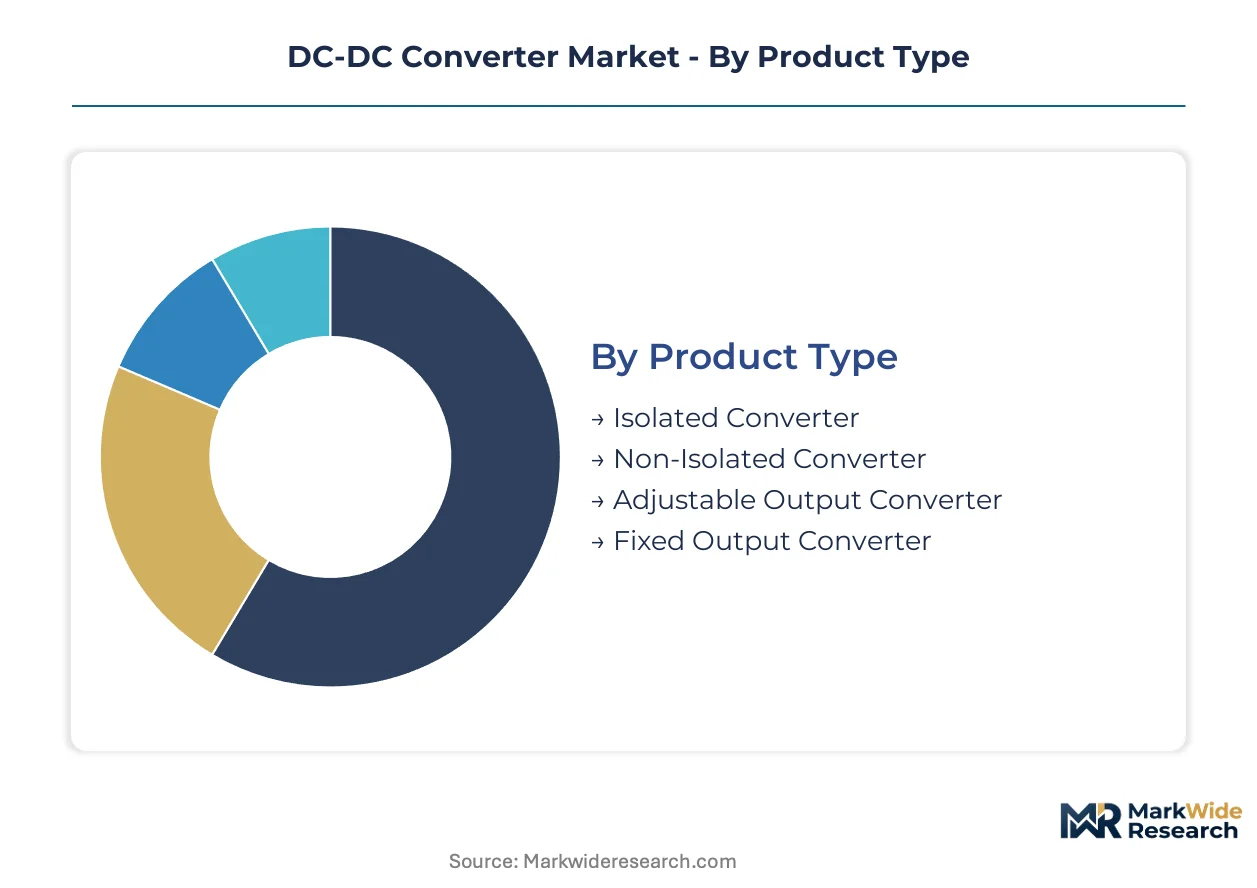
The segmentation of the DC-DC converter market offers a granular view of how different product characteristics and end-use requirements shape demand and supply dynamics. This detailed analysis is crucial for understanding the specific technological advancements and regulatory considerations impacting various market niches.
Product Type:
The product type segmentation highlights how after-sales service requirements vary significantly across different converter designs, influencing support structures and customer expectations for reliability and longevity.
- Isolated Converter:These converters provide galvanic isolation between input and output, preventing ground loops and enhancing safety in applications like medical devices and telecommunications equipment. Demand is concentrating in 5G infrastructure expansion, where safety and noise reduction are paramount for reliable operation.
- Non-Isolated Converter:These devices lack galvanic isolation, making them simpler and more cost-effective, primarily used where safety isolation is not a critical requirement. Volume demand remains high in consumer electronics, where space and cost efficiency drive widespread adoption.
- Adjustable Output Converter:These converters allow users to dynamically change the output voltage, offering flexibility for various load conditions and system requirements. Industrial control systems frequently utilize these for precise power delivery to diverse components.
- Fixed Output Converter:Offering a constant output voltage, these converters provide stable power for specific loads with predictable voltage needs. Automotive electrification applications use these extensively for consistent power to auxiliary systems.
Non-Isolated Converters hold the largest share; momentum sits with Isolated Converters.
Technology:
The technology classification reveals how specific converter topologies are optimized for distinct application demands, from voltage regulation in consumer devices to power delivery in industrial systems.
- Buck Converter:This step-down converter efficiently reduces a higher input voltage to a lower output voltage, commonly employed in point-of-load regulation within digital circuits. Data centers widely adopt buck converters for powering processors and memory, optimizing efficiency.
- Boost Converter:A step-up converter that increases a lower input voltage to a higher output voltage, essential for applications requiring voltage amplification. Electric vehicles utilize boost converters to manage power flow from batteries to higher voltage systems.
- Buck-Boost Converter:This versatile topology can either step up or step down the input voltage, maintaining a regulated output regardless of input fluctuations. Battery-powered portable devices often integrate buck-boost converters for consistent performance across battery discharge cycles.
- Cuk Converter:Known for its ability to produce an output voltage that can be greater or less than the input, this converter provides a negative output voltage. Specialized industrial power supplies sometimes use Cuk converters for their unique voltage inversion capabilities.
- SEPIC Converter:The Single-Ended Primary Inductor Converter offers a non-inverting output that can be higher or lower than the input, with true shutdown. LED lighting applications frequently benefit from SEPIC converters for flexible voltage control and efficiency.
Buck and Boost converters remain foundational technologies, while Buck-Boost designs are gaining traction for flexible voltage requirements.
Application:
Understanding the application segments provides insight into the varying volume requirements and performance specifications that drive DC-DC converter design and deployment.
- Consumer Electronics:This segment includes devices like smartphones, laptops, and home appliances, which demand compact, cost-effective, and highly efficient converters for battery management and internal power rails. Regulatory compliance with EU Ecodesign requirements directly impacts converter design in this high-volume segment.
- Telecommunications Equipment:Encompassing 5G base stations, network routers, and data center hardware, this application requires high-density, reliable, and often isolated converters to ensure continuous service and manage significant power loads. The global deployment of 5G infrastructure drives substantial demand for robust solutions.
- Industrial Control Systems:These systems, found in factory automation and process control, require rugged, highly reliable converters capable of operating in harsh environments with stringent safety and noise reduction standards. Certification such as CE marking is critical for these demanding industrial applications.
- Aerospace & Defense:This sector utilizes specialized, high-reliability converters designed to withstand extreme temperatures, vibrations, and radiation, meeting rigorous military and aviation specifications. Stringent qualification processes and long product lifecycles characterize procurement in this segment.
- Renewable Energy Systems:Solar inverters, wind turbines, and energy storage solutions integrate converters for maximum power point tracking and efficient power conversion from variable sources. Markets like India and Australia are seeing increased adoption for specialized battery management systems.
Telecommunications Equipment applications are expanding most quickly, though Consumer Electronics continues to represent substantial volume.
End User:
The end-user segmentation differentiates between the diverse customer types, each with unique procurement processes and technical support needs for DC-DC converter solutions.
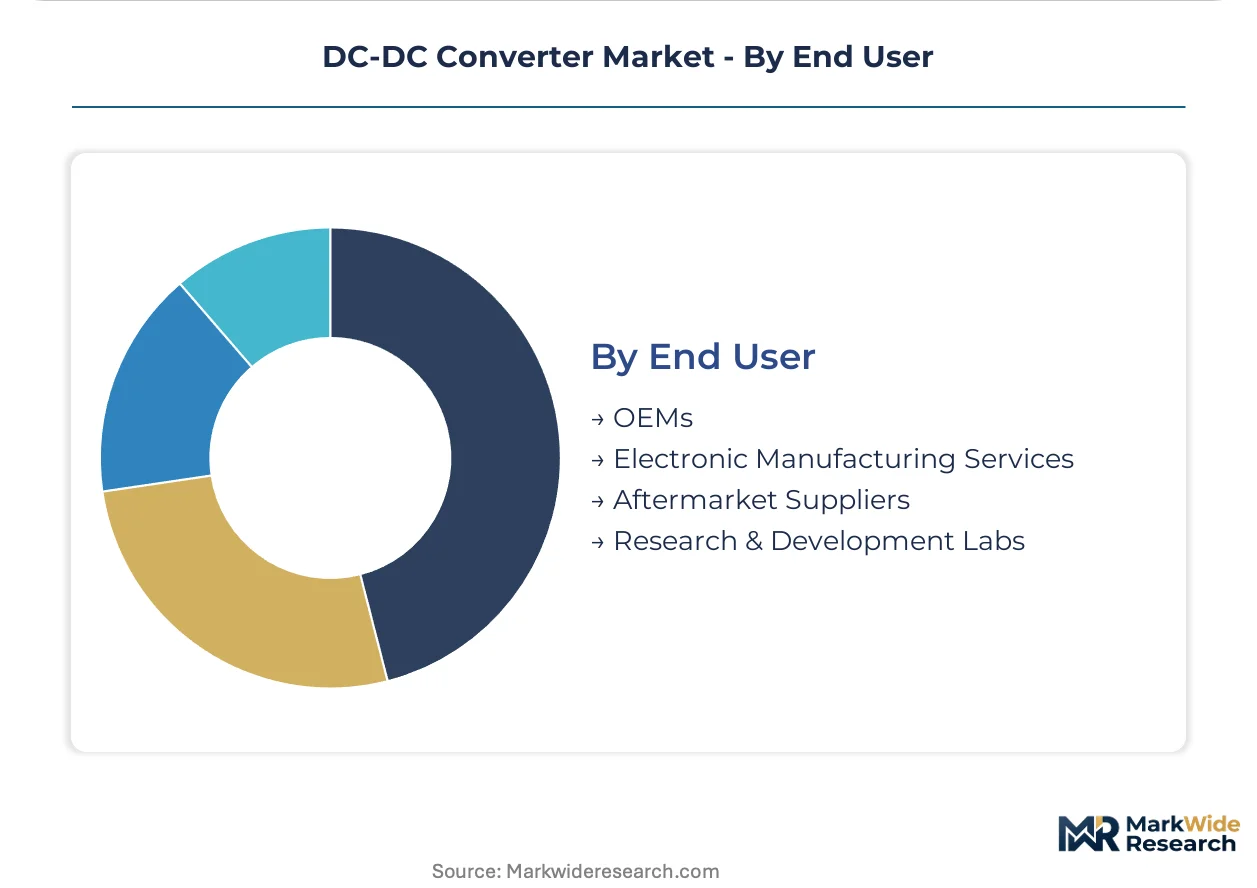
- OEMs:Original Equipment Manufacturers integrate DC-DC converters directly into their final products, requiring close collaboration with converter suppliers for custom designs and high-volume production. Automotive manufacturers and telecommunications equipment producers represent significant OEM demand.
- Electronic Manufacturing Services:EMS companies assemble products for OEMs, purchasing converters in bulk based on client specifications and often seeking standardized, readily available components. Their procurement patterns are influenced by efficiency and supply chain reliability.
- Aftermarket Suppliers:These entities provide replacement parts or upgrade components for existing systems, often requiring converters that are compatible with legacy designs or offer improved performance. Industrial maintenance and repair operations frequently source from aftermarket channels.
- Research & Development Labs:Academic institutions and corporate R&D centers procure converters for prototyping, testing new designs, and developing advanced power management solutions. Their demand often involves specialized, lower-volume components for experimental setups.
OEMs represent the primary customer base, with Electronic Manufacturing Services providers also holding significant purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR regulations, influencing market competition and product standards, anchor the significant demand for DC-DC converters in Asia. This region drives global production volume due to its extensive electronics manufacturing base. Key countries are expanding their infrastructure and automotive sectors, requiring advanced power solutions.
China
China's robust electronics manufacturing sector drives substantial demand for non-isolated DC-DC converters in consumer devices. The MIIT's industrial policies support domestic production and technological advancement in power components. The Yangtze River Delta region, a hub for electronics, sees intensive development of high-density converter solutions for export markets.
United States
The United States experiences strong demand for isolated DC-DC converters, particularly in data centers and telecommunications infrastructure. FCC regulations on electromagnetic interference mandate specific design considerations for power supply units. Silicon Valley continues to be a center for innovation, developing advanced power management ICs and high-frequency converter topologies.
Germany
German automotive electrification initiatives generate significant demand for fixed output DC-DC converters to manage electric vehicle auxiliary systems. CE marking requirements ensure product safety and compliance across the European market. Bavaria's industrial clusters, home to major automotive suppliers, are focusing on robust power solutions for high-voltage battery systems.
Japan
Japan's telecommunications sector, with its 5G infrastructure build-out, requires high-efficiency isolated DC-DC converters for base stations. METI policies encourage precision manufacturing and advanced material research in power electronics. The Tokyo metropolitan area, a hub for high-tech industries, leads in the development of compact and efficient power modules.
India
India's expanding renewable energy sector, especially solar installations, fuels demand for specialized DC-DC converters for maximum power point tracking. The PLI scheme encourages local manufacturing of electronic components and power modules. Bengaluru, a prominent tech city, is seeing increased activity in designing converters for grid-tied and off-grid energy solutions.
DC-DC Converter Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic competitive environment across the DC-DC converter market. The market structure exhibits a blend of specialized innovation from focused firms and high-volume production from diversified manufacturers. Strategic archetypes include integrated semiconductor giants, high-performance power module specialists, and large-scale electronics manufacturers. Portfolio diversification, strategic partnerships, and targeted geographic expansion represent dominant competitive moves across the industry.
Specialists in high-performance power solutions, such as Vicor Corporation, exemplify the focus on niche, demanding applications that require exceptional power density and reliability. Texas Instruments Incorporated represents the integrated semiconductor players, leveraging an extensive analog and embedded processing portfolio to offer comprehensive solutions. Delta Electronics, a Taiwan-based company, anchors the large-scale electronics manufacturing segment, providing system-level power solutions and competing on manufacturing scale for diverse applications. These companies collectively illustrate the varied approaches to market leadership within the DC-DC converter industry.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Delta Electronics |
| CET Technology |
| Vicor Corporation |
| TDK Lambda Corporation |
| Pico Electronics |
| Infineon Technologies AG |
| NXP Semiconductor |
| Murata Manufacturing |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta, a major electronics manufacturing hub, significantly influences DC-DC converter pricing through its vast production capacity and cost efficiencies. This concentration of supply directly impacts global price competitiveness for high-volume products.
Pricing Analysis
Geographic price spreads for DC-DC converters show significant variance, with Asian-manufactured units typically offering lower costs than European or North American counterparts. The dominant pricing model is per-unit transactional, influenced by manufacturing scale and material costs. Price differentiation stems from quality grade, particularly for certified industrial or medical applications, and volume scale for large OEMs. Pricing pressure intensifies due to raw material volatility and the sheer manufacturing capacity in China, with consumer electronics OEMs highly price-sensitive and Aerospace & Defense buyers less so.
Supply Chain Analysis
Upstream feedstock for DC-DC converters relies heavily on critical materials like copper for magnetic windings and specialized ceramics for capacitors. Supply concentration for these components and finished converters is high in China, Taiwan, and Japan. The supply chain faces structural risk from raw material price volatility, directly impacting manufacturer margins. Distribution primarily runs through direct sales channels to large OEMs, supplemented by electronic manufacturing services providers for high-volume, standardized components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DC-DC converter market is experiencing a shift in buyer power, driven by the increasing consolidation among telecommunications and automotive OEMs. This allows major purchasers to exert greater influence on pricing and product specifications.
For Market Incumbents:Harden intellectual property around advanced topologies and wide-bandgap semiconductor integration to counter emerging specialized firms. Invest in vertical integration for critical components like GaN and SiC to mitigate raw material volatility. The persistent talent gap in power electronics engineering poses a threat to continuous innovation. Focus on expanding certified product portfolios for high-margin segments like medical and automotive.
For New Entrants and Emerging Players:Build out modular, pre-certified DC-DC converter solutions targeting industrial controls and medical instrumentation. These sectors offer penetrable white space due to their high reliability requirements and preference for outsourced power design complexity. Focus on niche applications requiring extreme power density, such as specialized robotics or high-performance computing. A direct-to-developer sales model, emphasizing rapid prototyping and technical support, can provide a strong go-to-market angle.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized firms with deep expertise in wide-bandgap materials and digital power management. These companies offer significant long-term viability over the next 5-10 years, particularly those addressing 48V data center architectures or automotive electrification. Acquisition targets should be innovative mid-sized players demonstrating strong intellectual property in high-frequency magnetics or advanced control algorithms. The signal to watch is the acceleration of 48V adoption rates in data centers, indicating a broader market shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in GaN/SiC R&D | Accelerates power density and efficiency gains for data centers and electric vehicles. |
| Expand 48V Converter Portfolio | Captures growing demand from data center architectures for improved system efficiency. |
| Acquire Digital Power Specialists | Integrates real-time monitoring and optimization capabilities into advanced power systems. |
| Pursue Automotive ISO 26262 Certification | Unlocks high-value opportunities within the rapidly expanding electric vehicle market. |
| Develop Pre-Certified Modular Solutions | Reduces design complexity and shortens time-to-market for industrial and medical OEMs. |
Research Approach
Desk research of technical white papers, regulatory filings (FCC, CE marking, RoHS), and industry association reports preceded structured interviews with power electronics engineers, OEM procurement managers, and telecommunications infrastructure planners. This primary fieldwork validated secondary findings, combining insights from bottom-up market sizing with top-down industry trend analysis. The approach ensured a comprehensive understanding of DC-DC converter market dynamics.
Assumptions regarding 5G infrastructure deployment rates and electric vehicle adoption were held constant across the analysis window, while raw material price volatility was modeled as a variable. The analytical framework segmented the market by product type, technology, application, and end-user. Compound annual growth rates were derived from historical data and projected demand for high-efficiency power solutions. Key forecast inputs included projected unit shipments for consumer electronics and industrial control systems.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated semiconductor giants or specialized power module providers would shift outcomes. Raw material supply disruptions or unforeseen regulatory changes present specific risk factors. Cross-checking against industry-specific economic indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
South America Battery Management System Market
Power Systems
Global Plasma Generators Market
Power Systems
PV Inverter Market
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Solid State Transformer Market
Power Systems
Harmonic Generators Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Integrated UPS Market
Power Systems
Photovoltaic Inverters Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Battery Cyclers Market
Power Systems
Automotive Power Semiconductor Market
Power Systems
Global Excitation Systems Market