
 LED Solar Lighting Market | 2026-2036
LED Solar Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
LED Solar Lighting Market Insights
Chinese photovoltaic module production is hardening cost advantages for integrated LED solar lighting manufacturers. Signify Holding leverages its Philips lighting heritage to dominate European smart solar streetlight tenders. Sunna Design anchors its position in African and Caribbean off-grid deployments through durable tropicalized designs. SOKOYO Solar Lighting Co., Ltd. competes aggressively on manufacturing scale from its Jiangsu base.
LED solar lighting combines photovoltaic panels, solid-state luminaires, and battery storage into self-contained illumination systems operating independently of grid infrastructure, with typical configurations delivering 50-150 lumens per watt across 8-12 hour autonomous runtime cycles. The primary purpose is delivering reliable outdoor illumination in locations where grid extension proves economically unviable or physically impractical. Street lights occupy the largest revenue pool among product types due to municipal procurement scale, while smart control technology captures the fastest expansion trajectory as remote monitoring and adaptive dimming reduce operational expenditure. Residential applications remain fragmented across homeowner segments, whereas municipalities consolidate into larger contract volumes with stricter technical qualification requirements.
FCC certification governs radio-frequency enabled smart control units in US-bound products, while REACH compliance constrains substance composition for European market access, and India's BIS standards mandate specific performance benchmarks for solar photovoltaic street lighting systems. These regulatory frameworks collectively elevate technical barriers for non-compliant manufacturers while channeling procurement toward certified suppliers. Stakeholders must monitor evolving battery safety standards and circular economy mandates as these will reshape component sourcing decisions and product lifecycle obligations.
Market Dynamics
Lithium iron phosphate battery chemistry is displacing lead-acid storage across new installations, compressing total cost of ownership while extending system lifecycles beyond ten years in tropical climates.
Growth Catalysts
- India's off-grid solar program:Municipal procurement under Ministry of New and Renewable Energy mandates accelerates streetlight deployment in rural electrification corridors.
- Smart control integration:Remote monitoring and adaptive dimming capabilities reduce operational expenditure for municipal fleet operators managing distributed assets.
- Sub-Saharan Africa:Rural electrification initiatives concentrate demand in off-grid corridors where grid extension remains economically unviable.
Market Restraints
- Photovoltaic module supply concentration:Chinese manufacturing dominance creates input cost volatility and geopolitical sourcing risk for integrated system assemblers.
- Battery safety certification timelines:UN 38.3 lithium transport testing and IEC 62619 compliance extend product launch cycles by six to twelve months.
- Diesel generator substitution:Backup power alternatives persist in commercial applications where solar autonomy cannot guarantee continuous operation.
Strategic Opportunities
- Caribbean island nations:Hurricane-resistant tropicalized designs address resilience gaps in grid-fragile territories seeking energy independence.
- EU Green Deal public procurement:Circular economy mandates and embodied carbon disclosure requirements favor suppliers with verified lifecycle data.
- Pay-as-you-go financing:Mobile money-enabled distributed payment models unlock residential segments previously excluded by upfront capital barriers.
Industry Challenges
- Electrochemical engineering talent scarcity:Battery management system firmware development and thermal modeling expertise concentrates in automotive and consumer electronics sectors.
- Multi-certification complexity:FCC, REACH, and BIS standards require parallel testing streams, fragmenting engineering resources across compliance workstreams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Solar Lighting Market |
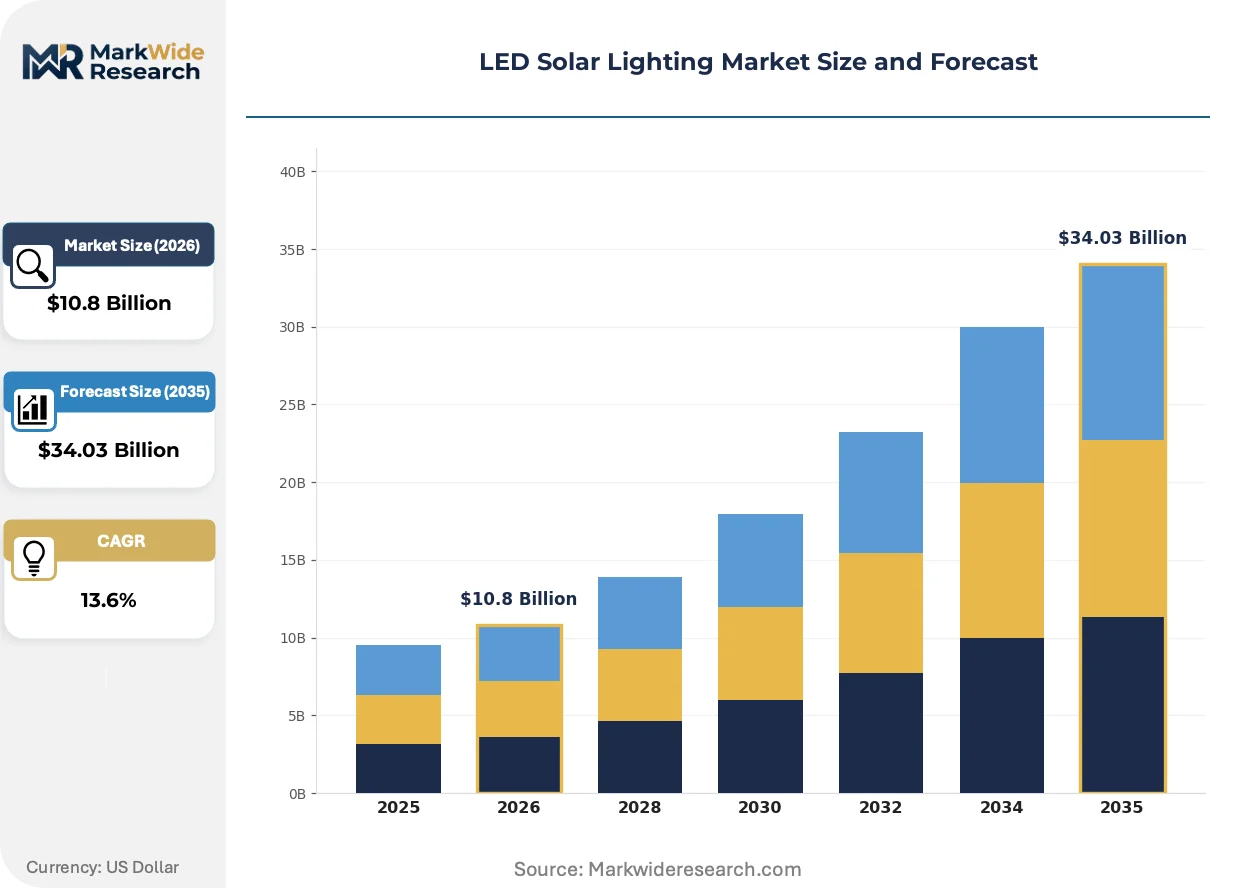
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $34.03 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Garden Lights, Flood Lights, Wall Lights Application: Residential, Commercial, Industrial, Agricultural Technology: Photovoltaic, Smart Control, Hybrid, Standalone End User: Homeowners, Municipalities, Businesses, Contractors |
| Companies Covered | Signify Holding, Sunna Design, SEPCO Solar Electric Power Company, Greenshine New Energy, Wipro Lighting, SOKOYO Solar Lighting Co., Ltd., LEADSUN, Polybrite - SBM NewTech Co., Ltd., Solar Street Lights USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Solar Lighting Market Trends and Innovations
Photovoltaic-LED-battery integration is evolving from commodity hardware toward intelligent, service-enabled platforms that monetize operational data and predictive maintenance capabilities.
Perovskite-silicon tandem solar cells are expanding into high-efficiency streetlight applications where wattage constraints limit panel surface area. German research institutes and Korean manufacturers pilot production lines targeting conversion efficiencies above thirty percent. This technology is expanding into premium municipal tenders where land availability restricts conventional mono-PERC deployment.
India's BIS standards for solar photovoltaic street lighting systems mandate specific performance benchmarks including lumen maintenance, battery cycle life, and ingress protection ratings. These technical barriers channel procurement toward certified domestic and foreign suppliers while elevating compliance costs for uncertified competitors. Municipal corporations in Maharashtra and Gujarat now require BIS certification as a mandatory bid qualification criterion.
Aggregated procurement consortia are consolidating fragmented municipal demand into larger contract volumes with stricter technical qualification requirements. State-level urban development authorities pool streetlight replacement programs, displacing individual municipal tendering. This concentration is most visible in India's Smart Cities Mission where nodal agencies negotiate framework agreements spanning multiple jurisdictions.
LED Solar Lighting Market Segmentation
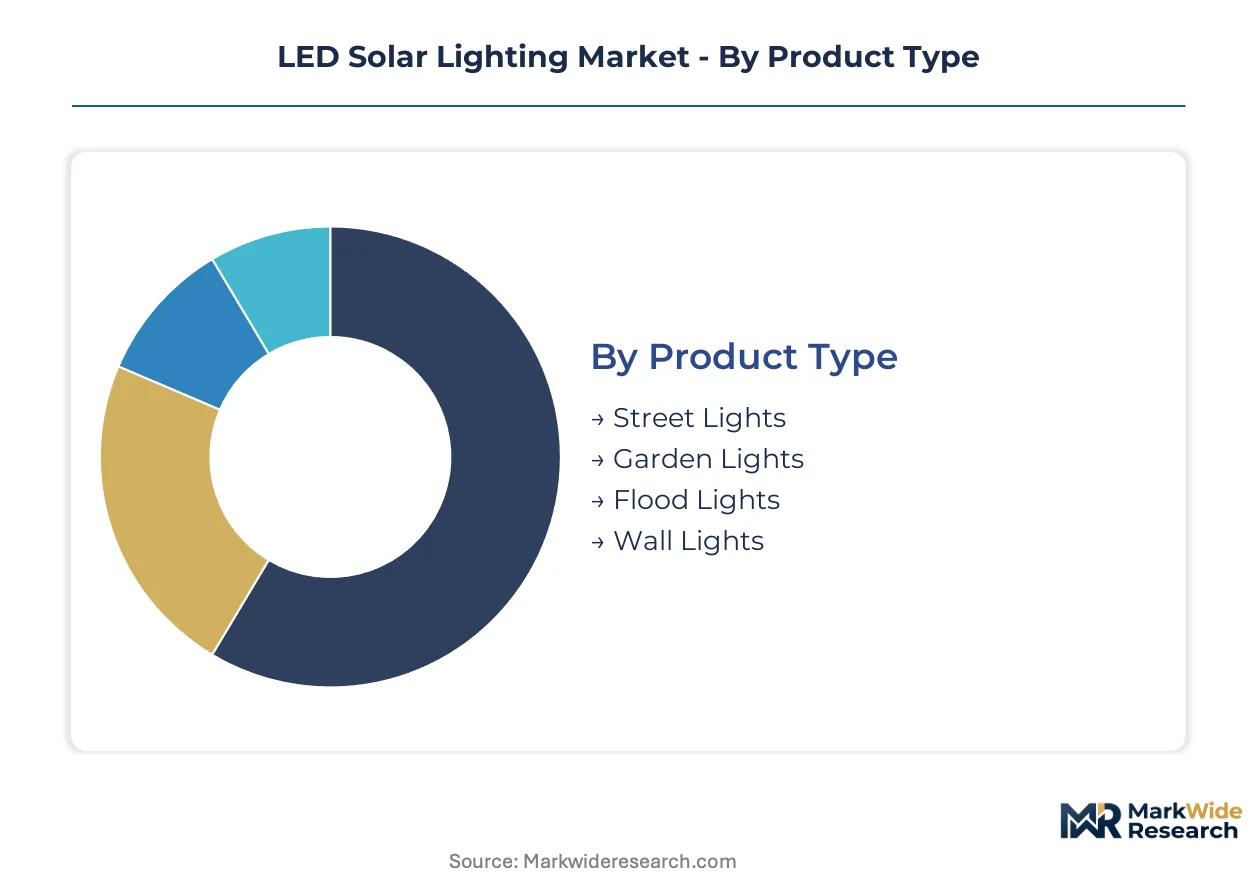
LED solar lighting markets fragment across hardware configurations, deployment contexts, and buyer sophistication levels. Procurement patterns diverge sharply between municipal scale contracts and distributed residential purchases. Technical architecture choices lock in decade-long operational trajectories.
Product Type:
Street lights dominate procurement volumes while garden lights capture premium margins through aesthetic differentiation.
- Street Lights:Integrated pole-mounted systems delivering 50-150 lumens per watt across 8-12 hour autonomous runtime cycles. Municipal procurement under India's Ministry of New and Renewable Energy concentrates demand in rural electrification corridors where grid extension proves economically unviable.
- Garden Lights:Low-wattage decorative luminaires emphasizing landscape integration over illumination intensity. European smart city tenders favor designs with adaptive dimming and remote monitoring capabilities that reduce operational expenditure.
- Flood Lights:High-output perimeter security applications requiring enhanced battery capacity for sustained lumen delivery.
- Wall Lights:Compact residential entry fixtures with limited photovoltaic surface area constraining runtime autonomy.
Today's leader: Street Lights. Tomorrow's challenger: Garden Lights.
Application:
Commercial deployments concentrate technical specification authority while residential demand fragments across individual purchase decisions.
- Residential:Homeowner-driven purchases of garden and wall-mounted fixtures with pay-as-you-go financing unlocking previously excluded segments through mobile money-enabled distributed payment models.
- Commercial:Businesses operating parking facilities, warehouses, and perimeter security requiring guaranteed illumination continuity where solar autonomy cannot substitute diesel backup.
- Industrial:Large-scale yard lighting with stringent lumen maintenance requirements over extended operational cycles.
- Agricultural:Irrigation path illumination and livestock facility lighting in remote farming operations across sub-Saharan Africa's rural corridors.
Commercial applications anchor current revenue. Residential segments expand most quickly through financing innovation.
Technology:
Smart control integration separates premium tier suppliers from commodity hardware assemblers.
- Photovoltaic:Conventional mono-PERC panel configurations facing wattage constraints where land availability restricts deployment surface area.
- Smart Control:Radio-frequency enabled units governed by FCC certification in US-bound products and REACH compliance for European market access, with remote monitoring reducing municipal fleet operational expenditure.
- Hybrid:Grid-tied backup systems addressing commercial applications requiring continuous operation guarantees.
- Standalone:Fully autonomous configurations dominating sub-Saharan African off-grid corridors and Caribbean island nations seeking hurricane-resistant energy independence.
Smart Control commands premium positioning. Standalone systems penetrate fastest in grid-fragile territories.
End User:
Municipal procurement scale consolidates contract volumes while homeowner demand remains structurally fragmented.
- Homeowners:Individual purchasers of residential-grade fixtures excluded by upfront capital barriers absent mobile money-enabled financing structures.
- Municipalities:Aggregated procurement consortia pooling streetlight replacement programs across India's Smart Cities Mission, with Maharashtra and Gujarat requiring BIS certification as mandatory bid qualification.
- Businesses:Commercial facility operators demanding UN 38.3 lithium transport testing and IEC 62619 compliance extending product launch cycles.
- Contractors:Installation and maintenance service providers navigating multi-certification complexity across FCC, REACH, and BIS parallel testing streams.
Municipalities consolidate purchasing power. Contractors face expanding technical qualification burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing cost advantages in Jiangsu Province attract integrated system assemblers seeking to arbitrage compliance burdens imposed by REACH in Europe and FCC certification in North America. Regulatory divergence between jurisdictions is channeling procurement toward certified suppliers while elevating barriers for uncertified competitors.
India
Municipal corporations in Maharashtra and Gujarat require BIS certification as mandatory bid qualification for solar streetlight tenders. The Ministry of New and Renewable Energy's off-grid solar program accelerates deployment across rural electrification corridors. State-level urban development authorities pool procurement volumes under the Smart Cities Mission framework.
United States
FCC certification governs radio-frequency enabled smart control units for municipal fleet operators managing distributed assets. Remote monitoring capabilities reduce operational expenditure for streetlight replacement programs. California and Texas municipalities consolidate contract volumes through aggregated procurement consortia.
Germany
EU Green Deal circular economy mandates and embodied carbon disclosure requirements favor suppliers with verified lifecycle data. Perovskite-silicon tandem solar cell research institutes pilot production lines targeting conversion efficiencies above thirty percent. Bavaria and North Rhine-Westphalia anchor premium municipal tender activity.
China
Photovoltaic module production concentrates in Jiangsu and Zhejiang provinces, hardening cost advantages for integrated LED solar lighting manufacturers. GB standards and MIIT regulations constrain domestic market access while export-oriented assemblers navigate multi-certification complexity. Yangtze River Delta industrial clusters supply sub-Saharan African and Caribbean export corridors.
Brazil
ANVISA and national energy regulator frameworks shape import compliance for lithium battery storage systems in off-grid applications. Rural electrification initiatives in Minas Gerais and São Paulo states concentrate demand where grid extension proves economically unviable. Mobile money-enabled financing structures unlock residential segments previously excluded by upfront capital barriers.
LED Solar Lighting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart control integration and tropicalized design specialization. The vendor base stratifies across three tiers: integrated manufacturers with captive photovoltaic supply, battery-agnostic assemblers sourcing cells from automotive suppliers, and regional fabricators serving single-country procurement frameworks. Dominant competitive moves include geographic expansion into African and Caribbean off-grid corridors and technology licensing for hurricane-resistant hardware platforms.
Among European heritage lighting specialists, Signify Holding exemplifies the premium-tier position through smart solar streetlight tender dominance. Sunna Design and SOKOYO Solar Lighting Co., Ltd. anchor the tropicalized design and manufacturing scale archetypes respectively, representing divergent strategic paths for serving grid-fragile territories. These three companies illustrate how competitive positioning fragments across certification depth, climatic durability engineering, and production cost structure rather than converging on a single winning formula.
| Leading Market Players |
|---|
| Signify Holding |
| Sunna Design |
| SEPCO Solar Electric Power Company |
| Greenshine New Energy |
| Wipro Lighting |
| SOKOYO Solar Lighting Co., Ltd. |
| LEADSUN |
| Polybrite - SBM NewTech Co., Ltd. |
| Solar Street Lights USA |
| Others |
Pricing and Supply Chain Analysis
Captive photovoltaic module production in Jiangsu and Zhejiang provinces anchors cost positioning for integrated LED solar lighting manufacturers, compressing input expenses while concentrating pricing power among vertically consolidated assemblers serving municipal procurement frameworks.
Pricing Analysis
Distributor margin layers compress as direct-to-municipality framework agreements displace fragmented retail channels. Three-tier pricing structure across premium smart-control, standard integrated, and economy standalone levels differentiates by certification depth and battery chemistry grade. Cost compression in the economy tier intensifies because Chinese module oversupply feeds downstream price erosion. Municipal buyers exhibit lowest price sensitivity due to total-cost-of-ownership procurement mandates, while residential segments remain highly elastic without mobile-money financing intermediation.
Supply Chain Analysis
Returns and refurbishment flows for lithium iron phosphate battery packs remain underdeveloped, constraining circular economy value recovery. Manufacturing concentrates in China, South Korea, and Vietnam, with Jiangsu Province hosting captive module-to-luminaire integration. Polysilicon ingots, lithium carbonate, and LED driver ICs constitute critical input dependencies. Single-source vulnerability in photovoltaic wafer supply creates tariff-exposure risk for non-Chinese assemblers. Distribution runs through state-level urban development authorities pooling aggregated procurement volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as municipal procurement shifts toward ten-year lifecycle guarantees and predictive maintenance specifications, displacing commodity hardware tenders.
For Market Incumbents: Anchor defensive positioning through backward integration into lithium iron phosphate cell production, eliminating third-party battery sourcing vulnerability. Deepen certification moats by securing UN 38.3 and IEC 62619 compliance ahead of evolving safety mandates. Prioritize captive supply of perovskite-silicon tandem cells to capture premium municipal tenders where surface area constraints dominate.
For New Entrants and Emerging Players: Capture white-space opportunity in Caribbean hurricane-resistant tropicalized designs, where incumbent coverage remains sparse and resilience premiums command pricing power. Target pay-as-you-go residential financing models enabled by mobile money infrastructure across sub-Saharan African corridors. Pursue technology licensing partnerships with established photovoltaic manufacturers to bypass capital-intensive module production.
For Investors and Strategic Acquirers: Roll-up economics work for battery-agnostic assemblers with established municipal channel relationships because procurement consolidation under Smart Cities Mission frameworks creates scalable contract platforms. Long-term viability hinges on smart-control software capabilities and lifecycle service revenue streams. Monitor BIS certification expansion beyond Maharashtra and Gujarat as the signal for regulatory barrier hardening.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Control Platform Integration | Remote monitoring capabilities reduce municipal operational expenditure while locking in recurring service revenue. |
| Backward Integration into Battery Cells | Captive lithium iron phosphate production eliminates supply volatility and compresses total system cost. |
| Perovskite-Silicon Tandem Cell Licensing | Conversion efficiency above thirty percent addresses premium tenders with severe wattage constraints. |
| Aggregated Procurement Consortium Participation | State-level urban development authority frameworks displace fragmented municipal tendering processes. |
| Mobile Money Financing Partnership | Distributed payment models unlock residential segments previously excluded by upfront capital barriers. |
Research Methodology
Bottom-up municipal procurement modeling reconciled against top-down photovoltaic module production tracking forms the analytical core of this study. Primary interviews with Ministry of New and Renewable Energy program officers, municipal corporation electrical engineers, lithium battery procurement managers, and smart control firmware developers were validated against secondary sources including SEC filings of listed lighting manufacturers, Indian Smart Cities Mission tender databases, and customs export records from Jiangsu Province. Triangulation between demand-side contract volumes and supply-side manufacturing capacity ensures statistical coherence.
Historical trendline analysis of streetlight deployment trajectories across rural electrification corridors informed projection frameworks. Segmentation dimensions modeled include product type, application context, technology architecture, and end-user procurement sophistication, with battery chemistry substitution rates and smart control penetration treated as industry-specific forecast inputs. CAGRs were derived through regression analysis of correlated macroeconomic and policy variables across the projection horizon.
Photovoltaic module tariff escalations, battery safety certification timeline extensions, and municipal fiscal constraint episodes are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding lithium iron phosphate cost decline curves and aggregated procurement framework adoption velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Lamps and Lighting Market
Lighting
Softbox Lighting Kit Market
Lighting
UAE Smart Lighting Market
Lighting
Industrial Lighting Market
Lighting
Architectural Lighting Market
Lighting
Studio Lighting Equipment Market
Lighting
Smart Street Lighting Systems Market
Lighting
Lighting Management System Market
Lighting
Lighting Control Components Market
Lighting
South America Outdoor LED Lighting Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
EV Lighting Market
Lighting
Photography Light Box Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
High-End Lighting Market
Lighting
Lighting Fixture Market