
 Shunt Capacitor Market | 2026-2036
Shunt Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Shunt Capacitor Market Analysis
Consolidation among electric utilities and independent power producers is repositioning procurement leverage toward fewer buyers with larger project pipelines. Hitachi Energy Ltd. leverages its high-voltage direct current heritage to dominate ultra-high-voltage shunt capacitor tenders across Asian markets. ABB Ltd. sustains competitive positioning through integrated power quality platforms that bundle capacitors with switching equipment. Siemens Energy AG anchors European utility relationships with reactor-integrated capacitor banks designed for offshore wind interconnection.
A shunt capacitor is a passive electrical component comprising dielectric-separated conductive plates, typically rated from hundreds of volts to extra-high-voltage classes exceeding 800 kV, which injects reactive power into AC networks to offset inductive loads and stabilize voltage profiles. Film capacitors using polypropylene dielectrics occupy the premium tier for outdoor substation installations due to superior thermal cycling endurance and self-healing properties. Power factor correction applications generate the largest revenue pool within the segment matrix, while harmonic filtering deployments for data center and renewable inverter integration represent the fastest-growing application trajectory.
IEC 60871 and IEEE 824 establish dielectric withstand and thermal performance benchmarks that determine product qualification for grid interconnection, effectively filtering out suppliers lacking certified testing infrastructure. FERC, China's National Energy Administration, and India's Central Electricity Authority each enforce distinct reactive power compensation obligations that shape regional product specifications and commissioning protocols. Stakeholders must monitor evolving grid code harmonization between IEC and national standards to anticipate design recertification cycles and qualification barriers.
Market Dynamics
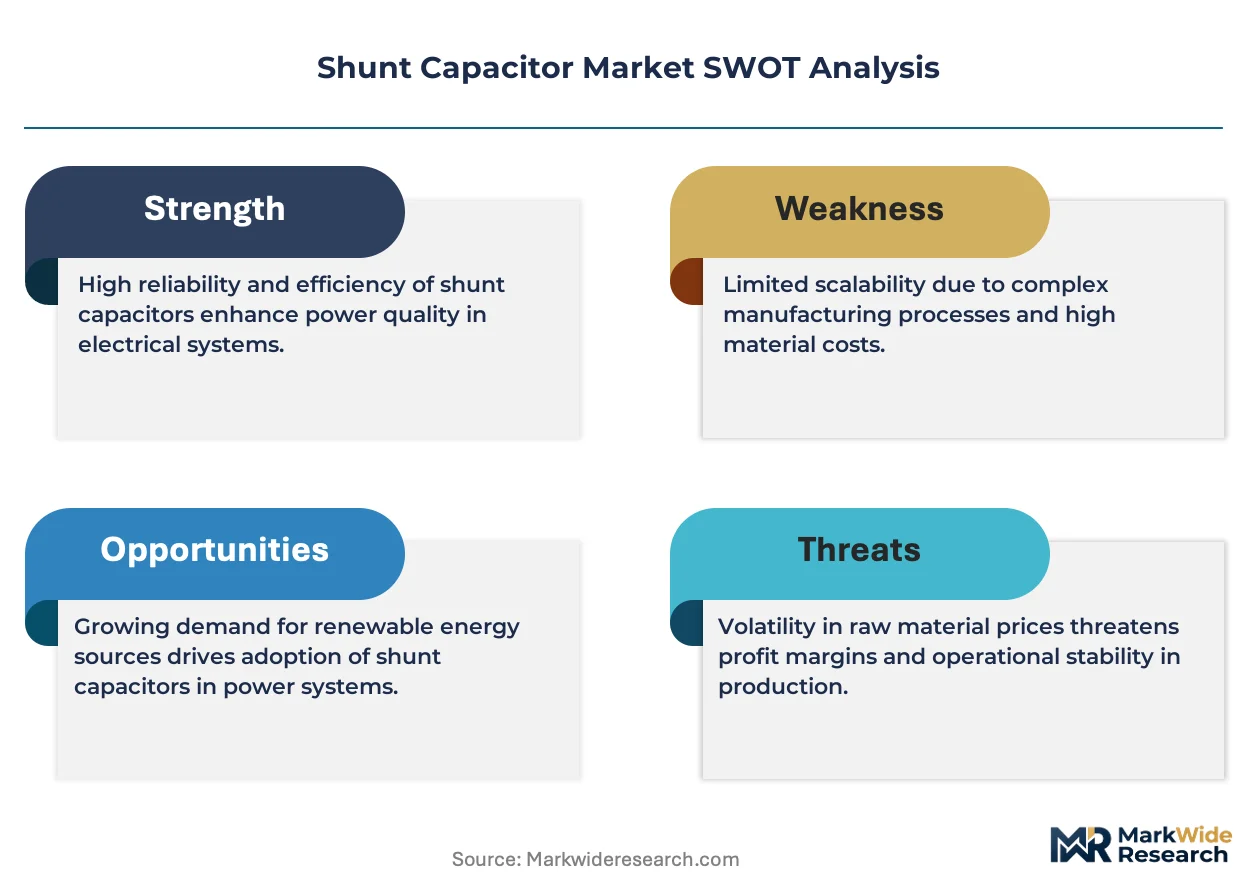
Grid interconnection standards are hardening across major power markets, forcing capacitor manufacturers to recertify designs for higher fault-current withstand and harmonic tolerance thresholds. This technical escalation filters supplier pools while accelerating replacement cycles in legacy substations.
Growth Catalysts
- Renewable integration mandates:FERC Order 2222 in the United States requires transmission operators to procure reactive power support for inverter-based resources, expanding shunt capacitor deployment at solar and wind interconnection points.
- Data center load expansion:Hyperscale facilities in Northern Virginia, Frankfurt, and Singapore are driving harmonic filtering demand to manage power quality from rectifier-heavy IT infrastructure.
- Polypropylene film advances:Metallized electrode technology with segmented self-healing patterns extends capacitor life cycles in desert and coastal environments, reducing maintenance intervals for Middle Eastern and Southeast Asian utilities.
Market Restraints
- Raw material concentration:Biaxially oriented polypropylene film supply concentrates among Japanese and German specialty chemical producers, creating input cost volatility during petrochemical feedstock disruptions.
- Ultra-high-voltage technical barriers:Dielectric stress management above 500 kV requires proprietary winding geometries and impregnation fluids that few manufacturers have qualified under IEC 60871.
- Reactor-compensator substitution:Static synchronous compensators (STATCOMs) displace shunt capacitors in dynamic voltage support applications requiring sub-cycle response times.
Strategic Opportunities
- Offshore wind interconnection:Germany's North Sea and China's Guangdong coastal zones need reactor-integrated capacitor banks for HVAC export cable compensation.
- Digital substation retrofit:IEC 61850 process bus integration creates demand for instrumented capacitor units with embedded temperature and partial discharge monitoring.
- India's green hydrogen corridors:The country's PLI scheme for electrolyzer manufacturing will require power factor correction at gigawatt-scale rectifier installations.
Industry Challenges
- High-voltage testing infrastructure scarcity:Few laboratories worldwide can execute full-load thermal cycle testing for 800 kV-class capacitor units, creating certification bottlenecks for new market entrants.
- Legacy asset integration complexity:Replacing oil-paper capacitors in 1960s-era substations requires custom bushing adaptations and seismic requalification that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shunt Capacitor Market |
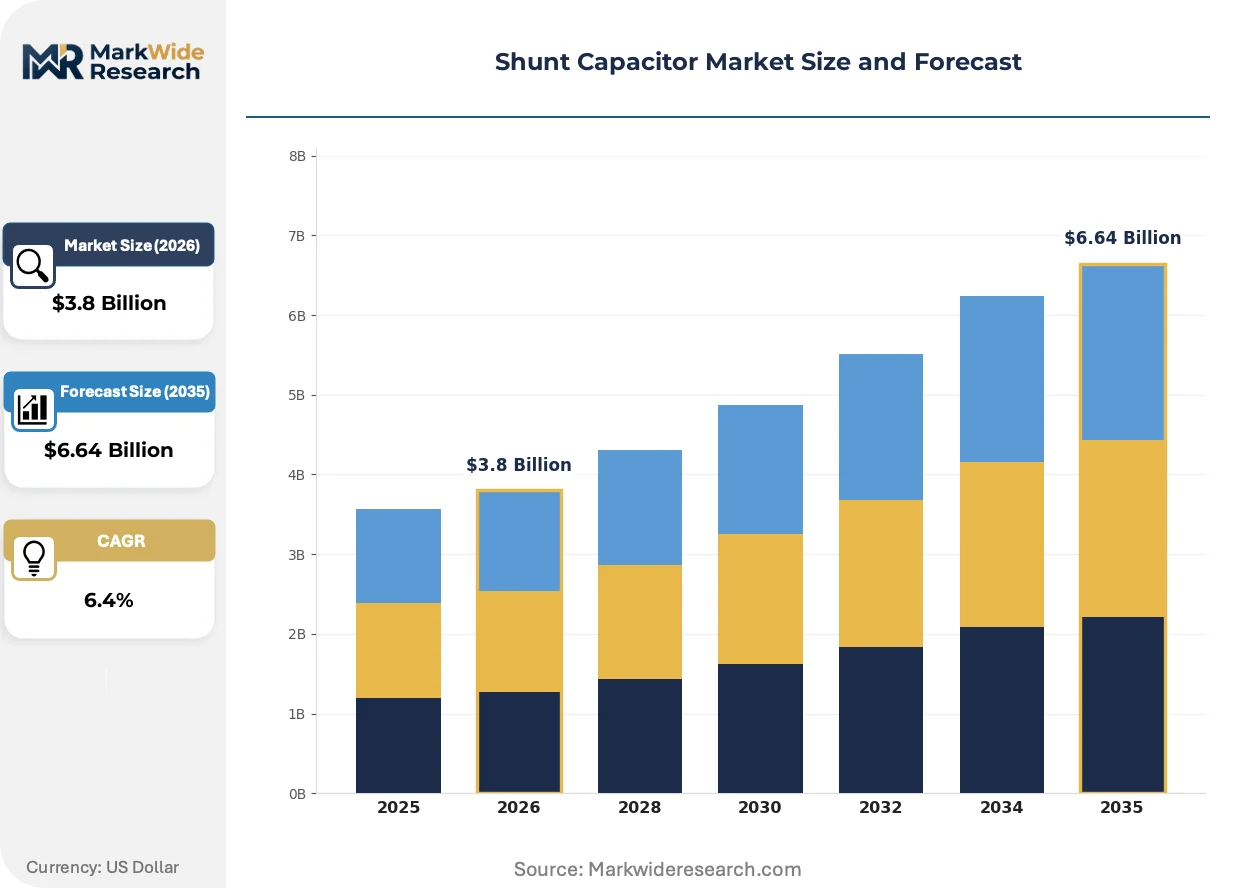
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil Capacitor, Polymer Capacitor, Ceramic Capacitor, Film Capacitor Application: Power Factor Correction, Voltage Stabilization, Energy Storage, Harmonic Filtering End User: Utilities, Manufacturing, Renewable Energy, Commercial Building Distribution Channel: Direct Sales, Wholesalers, Online Retail, Specialty Stores |
| Companies Covered | Eaton Corporation, Hitachi Energy Ltd., ABB Ltd., TDK Electronics AG, Larsen & Toubro Limited, Siemens Energy AG, General Electric Company, CIRCUTOR SA, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shunt Capacitor Market Emerging Trajectories
Capacitor technology is converging with power electronics and digital monitoring systems, transforming passive components into intelligent grid assets. This evolution redefines value capture models and supplier capability requirements.
Metallized polypropylene film with edge-disconnection patterns and optimized electrode segmentation is unifying reliability and energy density in a single dielectric platform. European transmission utilities are adopting these units for offshore converter stations where maintenance access is severely constrained. The technology is unifying what previously required separate standard and high-reliability product lines, compressing supplier SKU portfolios and simplifying procurement specifications.
China's National Energy Administration has tightened reactive power compensation obligations for renewable project grid codes, mandating dynamic voltage support capabilities that exceed static shunt capacitor performance. This regulatory pressure is accelerating hybrid compensator development combining capacitors with thyristor-switched reactors. Project developers in Xinjiang and Inner Mongolia are responding by specifying capacitor banks with pre-engineered STATCOM upgrade paths.
Utility procurement departments are consolidating capacitor purchases into multi-year framework agreements with integrated lifecycle service provisions. This behavioral shift displaces transactional spot-buying for individual substation projects. The pattern is most visible in Germany and Japan, where TenneT and TEPCO have moved to outcome-based contracts covering installation, commissioning, and predictive maintenance.
Shunt Capacitor Market Segmentation
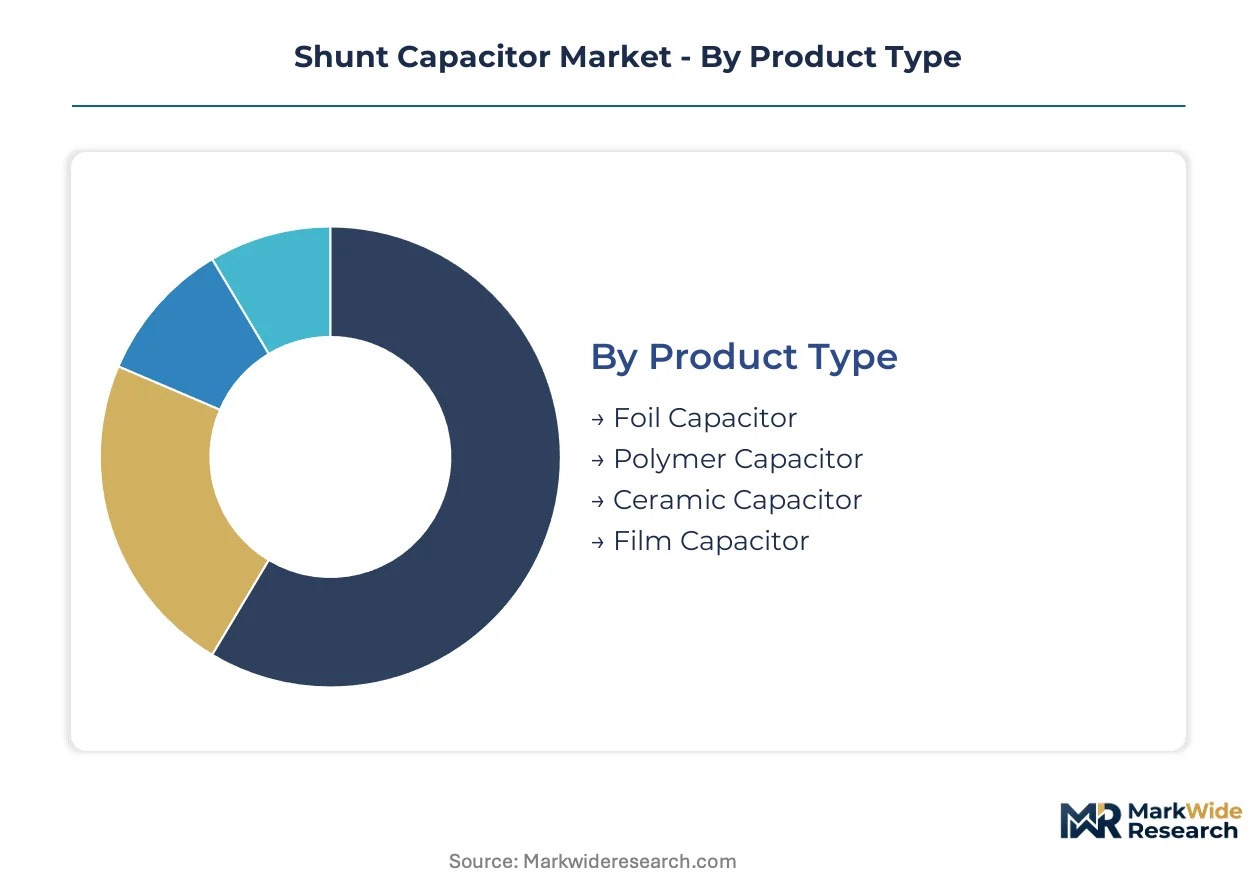
Segmentation in the shunt capacitor market reveals how dielectric technology, application intensity, and procurement channel economics create divergent margin structures across supplier portfolios. Understanding these splits enables targeted positioning against grid modernization mandates and renewable interconnection requirements.
Product Type:
Film capacitors command premium pricing for high-voltage substation deployments, while ceramic and polymer variants serve cost-sensitive industrial segments with shorter duty cycles.
- Film Capacitor:Metallized polypropylene dielectrics with self-healing electrode segmentation dominate extra-high-voltage classes above 500 kV. Demand concentrates in Chinese and German transmission utilities replacing oil-paper legacy assets, driven by IEC 60871 thermal cycling requirements for desert and offshore environments.
- Polymer Capacitor:Aluminum electrolytic and electric double-layer constructions deliver high capacitance density in compact footprints for data center power distribution units. Northern Virginia and Frankfurt hyperscale clusters are standardizing these for harmonic filtering at rectifier-heavy IT loads, constrained by shorter operational lifespans versus film alternatives.
- Foil Capacitor:All-film and mixed dielectric wound foil designs occupy mid-tier voltage classes for industrial motor compensation.
- Ceramic Capacitor:Multi-layer chip configurations address low-voltage power electronics and inverter DC-link applications.
Today's leader: Film Capacitor. Tomorrow's challenger: Polymer Capacitor.
Application:
Power factor correction generates baseline utility procurement volume, while harmonic filtering captures margin expansion from data center and renewable inverter integration.
- Power Factor Correction:Bulk reactive power injection for transmission and distribution voltage support remains the foundational deployment mode. India's Central Electricity Authority and FERC in the United States mandate these installations at renewable interconnection points, with procurement consolidating under multi-year framework agreements.
- Harmonic Filtering:Tuned and broadband filter banks suppress inverter switching frequencies and rectifier distortion. Singapore and Northern Virginia data center corridors are expanding these deployments fastest, responding to power quality specifications from hyperscale operators.
- Voltage Stabilization:Switched capacitor banks with thyristor control manage flicker and sag conditions in industrial feeders.
- Energy Storage:DC-link capacitors for battery energy storage system inverters and grid-forming applications.
Power factor correction anchors current procurement volumes. Harmonic filtering is climbing the fastest as inverter-based resources proliferate.
End User:
Utility procurement concentrates project scale and technical qualification barriers, while manufacturing and commercial segments fragment across distributor channels.
- Utilities:Transmission and distribution operators specify IEC 60871 and IEEE 824 certified units for outdoor substation installations. TenneT in Germany and TEPCO in Japan have shifted to outcome-based contracts covering predictive maintenance, displacing transactional spot-buying.
- Renewable Energy:Solar and wind project developers in Xinjiang and Inner Mongolia are specifying capacitor banks with pre-engineered STATCOM upgrade paths to meet tightened grid codes.
- Manufacturing:Automotive and steel producers deploy automatic power factor correction panels for tariff optimization.
- Commercial Building:Retail and office complexes utilize packaged capacitor banks for utility penalty avoidance.
Utilities dominate certified high-voltage procurement. Renewable Energy is gaining share fastest under tightening grid interconnection standards.
Distribution Channel:
Direct sales capture complex substation engineering with integrated service provisions, while wholesalers and online channels fragment below 50 kV classes.
- Direct Sales:Manufacturers engage transmission utilities and EPC contractors through dedicated account teams for specification-driven projects. This channel bundles installation supervision, commissioning support, and lifecycle service agreements.
- Wholesalers:Electrical distributors stock standard industrial capacitor units for manufacturing and commercial replacement demand.
- Online Retail:E-commerce platforms serve small-scale commercial and residential power factor correction with limited technical support.
- Specialty Stores:Regional electrical supply houses provide local inventory and basic application guidance.
Direct Sales commands premium positioning through service integration. Wholesalers maintain volume throughput in industrial aftermarket replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's electrical engineering workforce anchors the largest shunt capacitor fabrication cluster, with transmission infrastructure expansion driving procurement across multiple continents. German and Japanese specialists concentrate in high-reliability dielectric engineering for offshore and desert installations. India's power sector talent pool is scaling rapidly under renewable integration mandates.
China
State Grid Corporation's ultra-high-voltage transmission buildout and Inner Mongolia wind corridor integration propel demand. The National Energy Administration tightened reactive power compensation obligations for renewable grid codes in 2023. Xinjiang project developers now specify capacitor banks with pre-engineered STATCOM upgrade paths to meet dynamic voltage support requirements.
Germany
TenneT's North Sea offshore wind interconnection program and industrial electrification drive reactor-integrated capacitor procurement. FERC-equivalent grid modernization frameworks under the EU Green Deal accelerate replacement of oil-paper legacy assets. Bavarian transmission substations are standardizing metallized polypropylene units with embedded partial discharge monitoring for predictive maintenance contracts.
United States
FERC Order 2222 mandates reactive power procurement for inverter-based resources at solar and wind interconnection points. Northern Virginia's hyperscale data center corridor generates harmonic filtering demand for rectifier-heavy IT infrastructure. Texas ERCOT grid operators are expanding switched capacitor banks to manage voltage flicker from industrial load centers.
India
The Central Electricity Authority enforces power factor correction at renewable interconnection points under national grid code revisions. PLI scheme incentives for green hydrogen electrolyzer manufacturing will require gigawatt-scale rectifier compensation. Gujarat and Maharashtra industrial zones are deploying automatic capacitor panels for utility tariff optimization.
Japan
TEPCO's outcome-based procurement contracts covering installation through predictive maintenance displace transactional spot-buying. METI's carbon neutrality roadmap tightens efficiency requirements for legacy substation equipment. Tokyo and Osaka metropolitan grids are retrofitting 1960s-era oil-paper capacitors with seismic-requalified film dielectric units.
Shunt Capacitor Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered qualification barriers. Three structural archetypes dominate: integrated power quality platform providers bundling capacitors with switching equipment, high-voltage transmission specialists with proprietary winding geometries above 500 kV, and industrial aftermarket suppliers serving manufacturing power factor correction. Consolidation pressures intensify as utilities consolidate procurement into multi-year framework agreements, while certification bottlenecks at 800 kV-class testing laboratories filter new entrants.
Within the high-voltage transmission tier, Hitachi Energy Ltd. and Siemens Energy AG exemplify archetypes anchored in regional utility relationships. Hitachi Energy occupies a position tied to ultra-high-voltage tender dominance across Asian markets, while Siemens Energy represents reactor-integrated capacitor bank specialization for European offshore wind interconnection. ABB Ltd. sits within the integrated platform segment, bundling capacitors with broader power quality equipment portfolios. These three entities illustrate how heritage in adjacent electrical infrastructure segments shapes competitive positioning without requiring specific product or technology claims.
| Leading Market Players |
|---|
| Eaton Corporation |
| Hitachi Energy Ltd. |
| ABB Ltd. |
| TDK Electronics AG |
| Larsen & Toubro Limited |
| Siemens Energy AG |
| General Electric Company |
| CIRCUTOR SA |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Utility procurement consolidation into multi-year framework agreements is forcing capacitor manufacturers to absorb lifecycle service costs upfront while competing on total cost of ownership metrics rather than unit pricing alone.
Pricing Analysis
Capacity additions in China's polypropylene film sector are reshaping price floors for standard-grade capacitor units, though premium metallized dielectric segments retain margin insulation through IEC 60871 certification barriers. Three-tier pricing structure across premium, standard, and economy levels separates qualified transmission-grade suppliers from industrial aftermarket vendors. Pricing pressure stems from STATCOM substitution threats in dynamic compensation applications. Manufacturing segments exhibit highest price sensitivity due to distributor channel fragmentation, while transmission utilities prioritize reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for high-voltage substation deliveries, with project logistics feeding from fabrication clusters in China and India. Biaxially oriented polypropylene film supply draws from Japanese and German specialty chemical producers, with aluminum foil electrode materials sourced from Chinese and South Korean rolling mills. Single-source vulnerability concentrates in 800 kV-class testing laboratory access. Distribution runs through direct manufacturer-to-utility channels for complex substation projects, while wholesaler networks handle industrial replacement demand below 50 kV classes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FERC Order 2222 and China's tightened renewable grid codes mechanically expand addressable demand for reactive power compensation equipment.
For Market Incumbents: Lock in multi-year framework agreements with integrated predictive maintenance provisions before STATCOM hybridization accelerates. Prioritize certification investment for 800 kV-class testing qualification to filter emerging competitors. Defend against pure-play specialists by bundling capacitor banks with switching equipment and digital monitoring platforms. For New Entrants and Emerging Players: India's Central Electricity Authority mandates under green hydrogen corridor development open a window for gigawatt-scale rectifier compensation projects with lower incumbent saturation than transmission utility tiers. Target data center harmonic filtering in Northern Virginia and Singapore where procurement specifications favor modular, rapidly deployable units over legacy qualification depth. Pursue EPC contractor partnerships rather than direct utility certification pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier industrial capacitor specialists possessing captive polypropylene film supply and latent high-voltage testing relationships. Five-to-ten year viability hinges on STATCOM integration capability rather than pure passive component positioning. Monitor India's PLI scheme disbursement velocity as inflection indicator for electrolyzer manufacturing load growth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Film | Captive dielectric supply insulates margins against petrochemical feedstock volatility from Japanese and German specialty producers. |
| 800 kV Testing Laboratory Accreditation | Certification infrastructure scarcity creates qualification moats for ultra-high-voltage transmission tenders across Asian markets. |
| STATCOM Upgrade Path Engineering | Pre-engineered hybrid compensation capability addresses China's tightened dynamic voltage support mandates for renewable interconnection. |
| Outcome-Based Service Contracting | Predictive maintenance bundling aligns with TenneT and TEPCO procurement shifts away from transactional spot-buying patterns. |
| Digital Substation Protocol Integration | IEC 61850 process bus compatibility positions capacitor units as intelligent grid assets rather than passive components. |
Methodological Framework
Bottom-up utility procurement modeling reconciled against top-down capacitor manufacturing capacity tracking forms the analytical core of this study. Primary fieldwork encompassed transmission planning officers at State Grid and TenneT, EPC contractor procurement leads, and high-voltage equipment testing laboratory directors. Secondary validation drew from FERC interconnection filings, China's National Energy Administration grid code revisions, IEC 60871 certification registries, and utility capital expenditure disclosures.
Input-output matrices mapped dielectric technology adoption, voltage class requirements, and application intensity across the projection horizon. Segmentation dimensions spanned product type, end-use sector, and regional regulatory framework clusters. CAGRs were derived from installed base replacement cycles and renewable interconnection mandates rather than extrapolated historical trends. Forecast inputs incorporated polypropylene film supply elasticity and STATCOM substitution elasticity by voltage class.
Revisions become necessary when grid code harmonization between IEC and national standards accelerates design recertification cycles, or when green hydrogen manufacturing load growth materially exceeds PLI scheme projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Telecom Battery Market
Power Systems
Laptop Battery Market
Power Systems
Gan-Powered Chargers Market
Power Systems
North America Micro Inverter Market
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market
Power Systems
Electrical and Automation System Market
Power Systems
Global Data Center Transformer Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Automotive Power Electronics Market
Power Systems
South America Battery Management System Market
Power Systems
AC DC Power Adapter Market
Power Systems
South America DC Distribution Network Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market