
 Traction Inverter Market | 2026-2036
Traction Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Traction Inverter Market Outlook
The capability gap between captive semiconductor foundries and fabless inverter assemblers is bifurcating competitive returns across the supply base. Continental AG leverages in-house power module packaging to sustain margin capture from raw wafer to vehicle integration. Mitsubishi Electric anchors its position through dedicated silicon carbide substrate investments that insulate it from foundry allocation cycles. Robert Bosch GmbH competes by controlling inverter-software calibration loops that tie hardware performance to OEM-specific motor maps.
A traction inverter converts DC battery current into variable-frequency AC for electric motor propulsion, typically handling voltage rails from 400V to 800V and switching frequencies above 10 kHz to optimize torque response and thermal efficiency. Three-phase inverter architectures dominate automotive volumes, though multilevel topologies are gaining traction in rail transport where 3.3 kV and above insulation requirements demand stepped waveform synthesis. Silicon carbide technology leads growth trajectories across all end user categories, displacing IGBT modules in premium electric vehicles while gallium nitride MOSFETs penetrate auxiliary power conversion applications where lighter loads justify cost premiums.
FDA oversight of electromagnetic compatibility in medical-adjacent mobility devices, EPA tailpipe and upstream power-plant emissions rules, and NHTSA functional safety mandates under FMVSS collectively tighten inverter efficiency and reliability thresholds for US market access. EMA-equivalent transport regulators in Europe enforce parallel CE marking and F-Gas compliance for thermal management subsystems, while China's NMPA and MIIT coordinate GB standards for domestic new energy vehicle inverter certification. Stakeholders must monitor how divergent semiconductor export controls and subsidy eligibility rules reshape where captive versus merchant supply strategies prove sustainable.
Market Dynamics
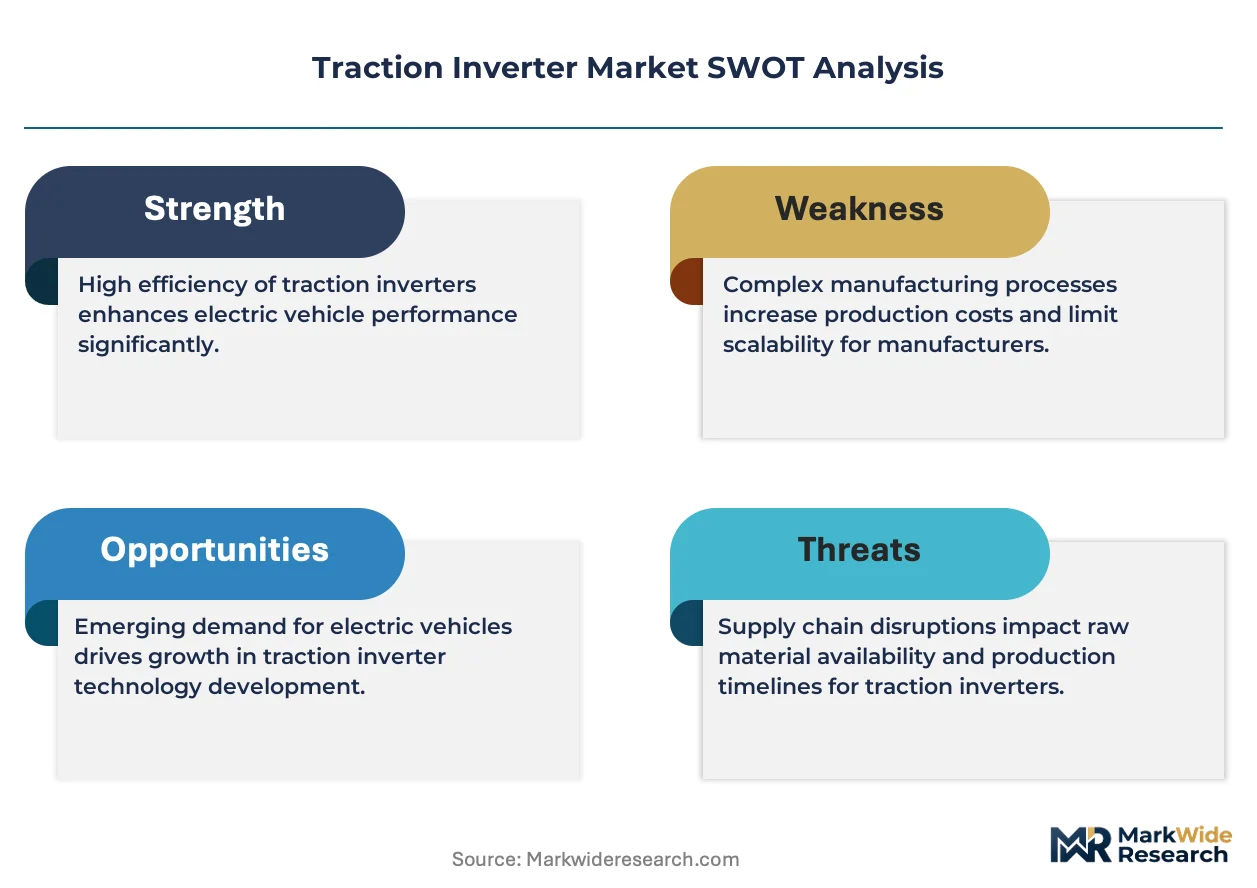
Silicon carbide semiconductor transitions are compressing switching losses and thermal budgets, forcing inverter assemblers to requalify entire powertrain architectures around 800V platforms while foundry allocation cycles constrain supply security.
Growth Catalysts
- EPA Vehicle Emissions Standards:Tightening tailpipe and upstream power-plant rules in the United States mandate higher inverter efficiency thresholds, accelerating OEM procurement of next-generation power electronics.
- 800V Powertrain Migration:Premium electric vehicle architectures are adopting higher voltage rails to reduce copper mass and enable faster charging, expanding addressable demand for high-voltage inverter modules.
- German Engineering Clusters:Concentrated automotive inverter R&D around Stuttgart, Munich, and Nuremberg shortens development cycles and deepens supplier-OEM co-design relationships.
Market Restraints
- Silicon Carbide Substrate Scarcity:Limited 150mm and 200mm SiC wafer capacity concentrates supply risk among three merchant substrate vendors, inflating input costs for fabless inverter assemblers.
- NHTSA Functional Safety Mandates:FMVSS compliance for ASIL-D rated systems extends validation timelines and freezes design specifications earlier in development cycles.
- IGBT Module Obsolescence Risk:Rapid displacement of silicon-based power modules strands capital equipment and engineering expertise at tier-two suppliers without SiC transition roadmaps.
Strategic Opportunities
- Rail Transport Electrification:Multilevel inverter topologies for 3.3 kV and above traction systems open adjacent demand beyond automotive, with European rail operators modernizing fleets under EU Green Deal timelines.
- Gallium Nitride Auxiliary Conversion:GaN MOSFETs penetrate onboard charger and DC-DC applications where lighter loads justify cost premiums, enabling platform-level semiconductor consolidation.
- India PLI Scheme:Production-linked incentives for domestic new energy vehicle component manufacturing attract inverter packaging investments to serve emerging South Asian EV demand.
Industry Challenges
- Power Electronics Talent Gap:Scarcity of engineers with combined SiC device physics and thermal management expertise extends hiring timelines and inflates compensation at inverter design centers.
- CE Marking and F-Gas Compliance:EMA-equivalent transport regulators enforce parallel certification tracks for thermal management subsystems, fragmenting validation resources across divergent standards.
- Semiconductor Export Control Navigation:Divergent dual-use technology restrictions between US, EU, and Chinese authorities complicate captive versus merchant supply strategy decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traction Inverter Market |
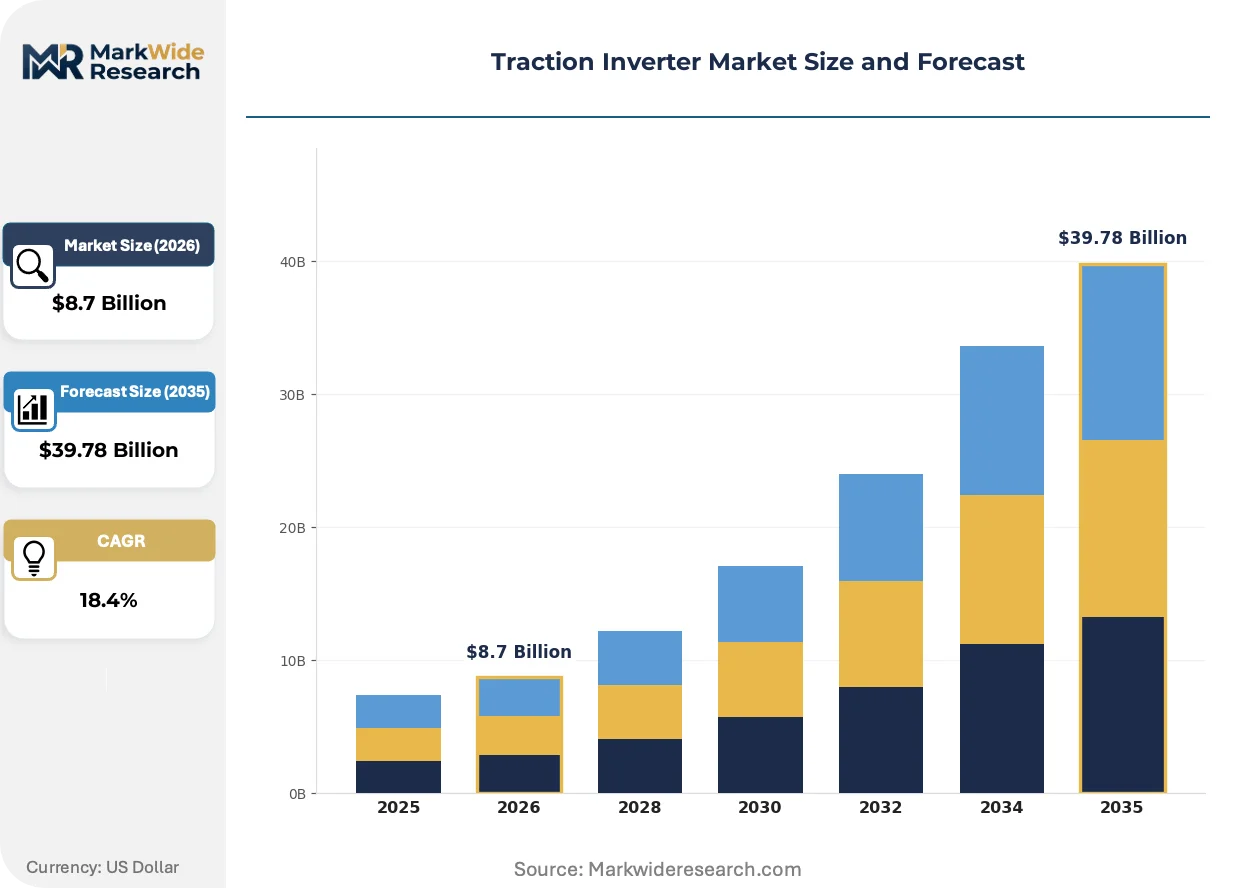
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bidirectional Inverters, Multilevel Inverters, Single-Phase Inverters, Three-Phase Inverters Technology: Silicon Carbide, IGBT, MOSFET, Gallium Nitride End User: Electric Vehicles, Rail Transport, Marine Vehicles, Aviation Application: Power Conversion, Motor Control, Battery Management, Regenerative Braking |
| Companies Covered | Continental AG, Mitsubishi Electric Corporation, Robert Bosch GmbH, Toshiba Corporation, Siemens AG, BorgWarner Inc., Hitachi Ltd., ZF Friedrichshafen AG, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traction Inverter Market Strategic Shifts
Power semiconductor packaging and thermal interface materials are undergoing simultaneous transformation, compressing form factors while elevating reliability thresholds for automotive qualification cycles.
Silicon carbide power modules handle voltage rails from 400V to 800V with switching frequencies above 10 kHz, optimizing torque response and thermal efficiency in three-phase inverter architectures. High-volume electric vehicle programs at premium OEMs are adopting these modules at accelerated qualification paces. This technology is miniaturizing inverter enclosures and enabling integrated motor-inverter-transmission assemblies that reduce vehicle packaging volume.
EPA tailpipe emissions rules and NHTSA functional safety mandates under FMVSS collectively tighten inverter efficiency and reliability thresholds for US market access. These regulatory pressures force redesigns of gate driver circuits and DC-link capacitors to meet combined electromagnetic compatibility and thermal cycling requirements. Heavy-duty electric truck platforms face the steepest compliance burden, with suppliers pre-qualifying hardware to locked 2027 EPA certification deadlines.
Fleet procurement of electric commercial vehicles is compressing supplier qualification cycles and unbundling hardware from software service agreements. Direct OEM relationships are displacing tier-one system integrator channels for inverter sourcing in North American and European heavy-duty segments. This pattern is most visible in California, where CARB fleet mandates concentrate buyer power among large logistics operators negotiating multi-year platform commitments.
Traction Inverter Market Segmentation
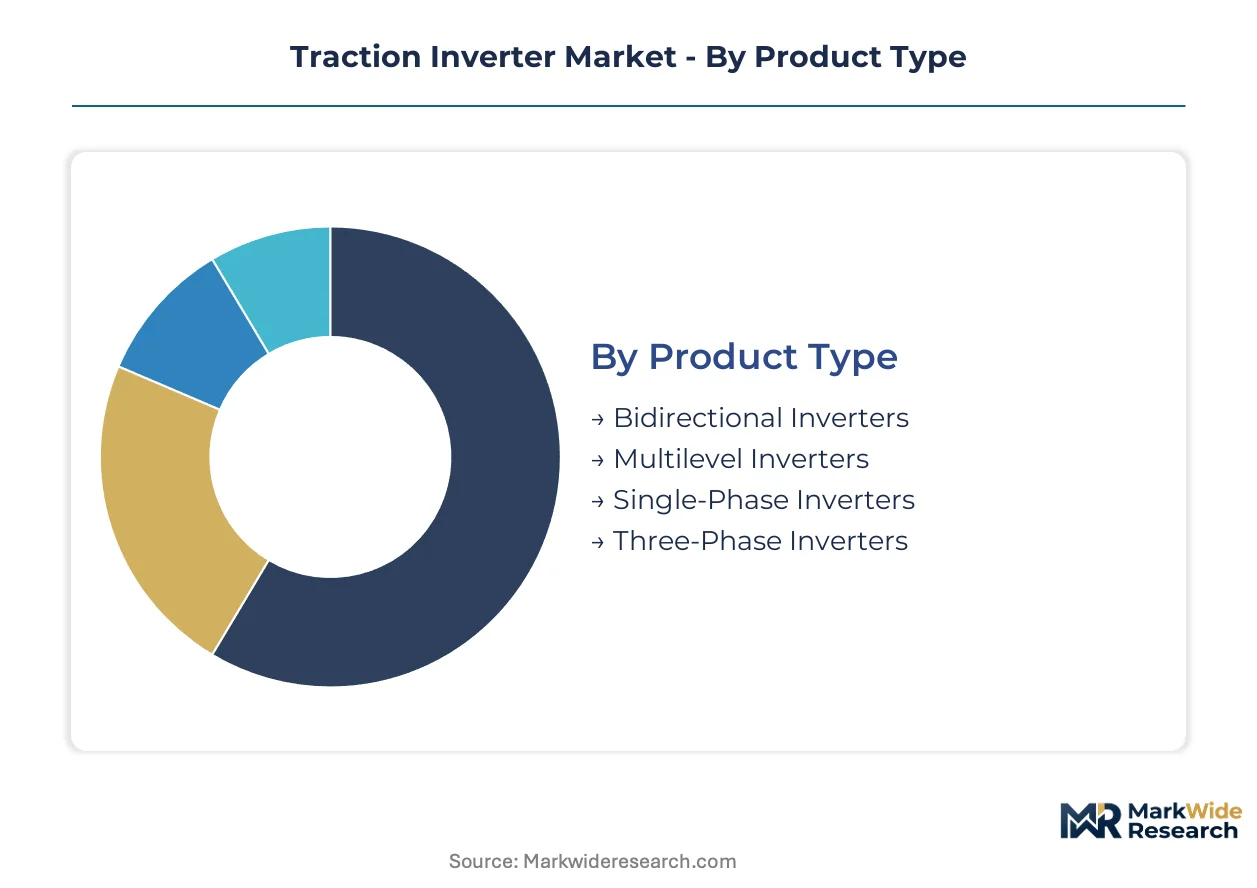
Traction inverter segmentation reveals distinct procurement channels and qualification requirements across powertrain architectures. Product type and technology choices determine whether supply flows through tier-one system integrators or direct OEM relationships, while end-user categories impose divergent voltage, reliability, and certification thresholds.
Product Type:
Channel mix varies sharply by topology complexity, with standard three-phase units moving through established automotive distributors while multilevel architectures increasingly bypass tier-one intermediaries for rail OEM direct negotiation.
- Three-Phase Inverters:Dominant automotive architecture handling 400V to 800V rails with switching frequencies above 10 kHz. Demand concentrates in premium electric vehicle platforms from Germany, where Stuttgart and Munich engineering clusters co-design integrated motor-inverter-transmission assemblies with Bosch and ZF.
- Multilevel Inverters:Stepped waveform synthesis enables 3.3 kV and above insulation for rail traction systems. European rail operators under EU Green Deal timelines are modernizing fleets, creating adjacent demand beyond automotive through direct procurement relationships with Mitsubishi Electric and Siemens.
- Bidirectional Inverters:Enable vehicle-to-grid power flow for stationary storage applications. Grid integration requirements from FERC-interfaced utilities in the United States are accelerating qualification of bi-directional capable hardware.
- Single-Phase Inverters:Limited to auxiliary power and low-voltage applications. Light commercial vehicle segments in India under PLI scheme incentives represent emerging volume for cost-optimized single-phase packaging.
Three-phase inverters dominate installed base. Multilevel topologies are where expansion concentrates.
Technology:
Cost tier stratification separates premium silicon carbide modules from legacy silicon alternatives, with margin capture shifting upstream to substrate and wafer suppliers.
- Silicon Carbide:Wide bandgap semiconductor compresses switching losses and thermal budgets, enabling 800V platform migration. Foundry allocation cycles among three merchant substrate vendors constrain supply security for fabless assemblers while rewarding captive producers like Mitsubishi Electric.
- IGBT:Silicon-based insulated gate bipolar transistors face obsolescence risk as EPA efficiency mandates accelerate displacement. Tier-two suppliers without SiC transition roadmaps strand capital equipment and engineering expertise.
- MOSFET:Silicon metal-oxide-semiconductor field-effect transistors persist in cost-sensitive 400V applications. Chinese domestic new energy vehicle programs under MIIT GB standards sustain volume for silicon MOSFET inverter certification.
- Gallium Nitride:GaN MOSFETs penetrate onboard charger and DC-DC auxiliary conversion where lighter loads justify cost premiums. Platform-level semiconductor consolidation enables single-supplier strategies for integrated power electronics.
IGBT modules retain legacy fleet replacement demand. Silicon carbide is climbing the fastest.
End User:
Application-specific reliability requirements create customer-type segmentation, with automotive ASIL-D functional safety mandates contrasting rail transport's emphasis on decades-long service intervals.
- Electric Vehicles:Passenger and commercial vehicle platforms drive volume, with NHTSA FMVSS compliance and EPA emissions rules tightening efficiency thresholds. Heavy-duty electric truck suppliers pre-qualify hardware to locked certification deadlines.
- Rail Transport:Multilevel inverter demand from European rail modernization programs under EU Green Deal timelines. 3.3 kV and above traction systems require stepped waveform synthesis and extended thermal cycling validation.
- Marine Vehicles:Hybrid and fully electric propulsion for harbor craft and short-sea shipping. IMO emissions regulations and port authority zero-emission mandates in California and Northern Europe shape procurement specifications.
- Aviation:Electric and hybrid-electric aircraft development programs at NASA and EU Clean Aviation initiatives. DO-160 environmental qualification and FAA airworthiness requirements extend development cycles for aerospace-grade power electronics.
Electric vehicles dominate installed base. Rail transport is where expansion concentrates.
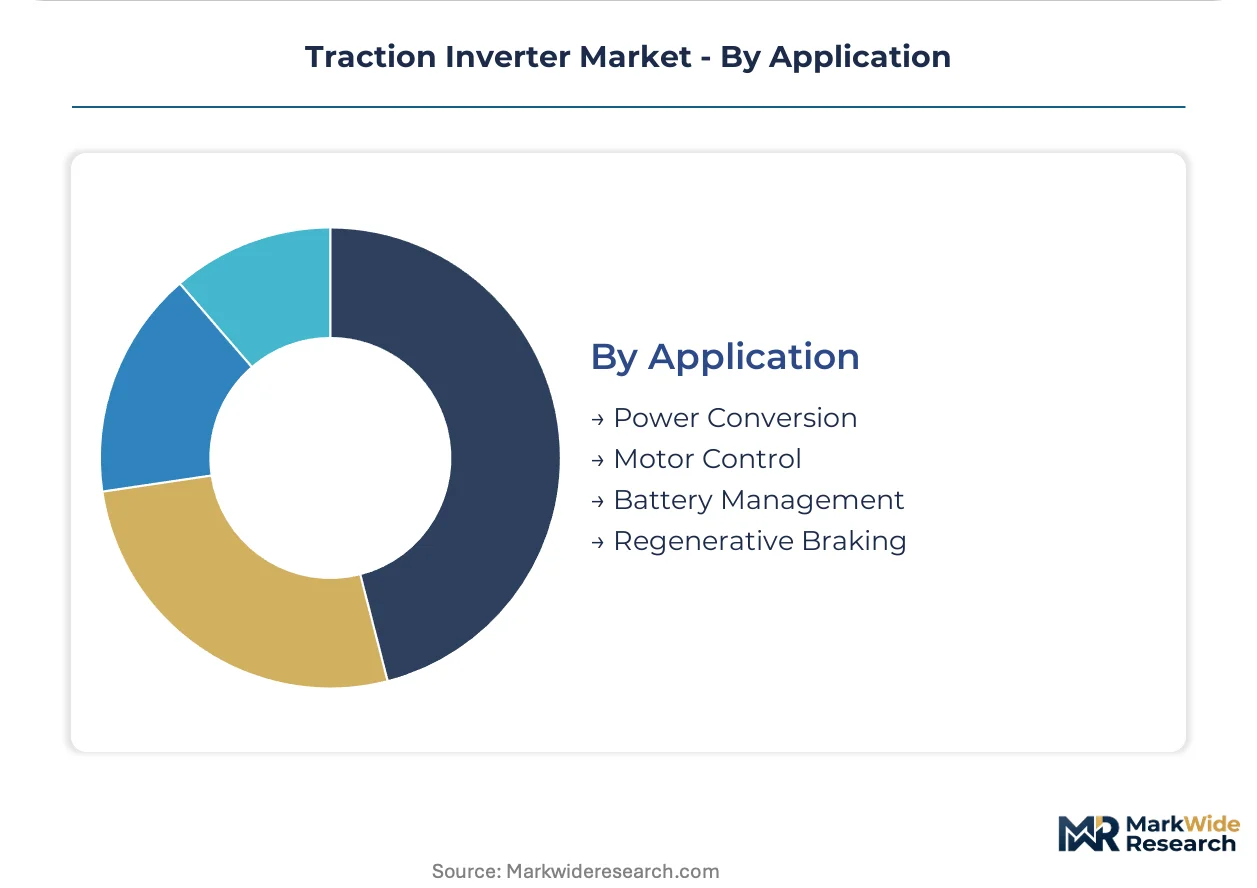
Application:
Volume concentration follows powertrain integration depth, with motor control functions capturing highest per-unit value while regenerative braking modules face commoditization pressure.
- Motor Control:Variable-frequency AC synthesis for torque response optimization demands tight software-hardware calibration loops. Bosch competes by controlling inverter-software calibration that ties hardware performance to OEM-specific motor maps.
- Power Conversion:DC-AC and AC-DC transformation for battery and grid interfaces. 800V platform migration expands addressable demand for high-voltage conversion modules in premium European and North American electric vehicles.
- Battery Management:Cell balancing and thermal monitoring integration with inverter thermal management subsystems. CE marking and F-Gas compliance for cooling circuits fragment validation resources across divergent EMA-equivalent standards.
- Regenerative Braking:Kinetic energy recovery systems with declining differentiation as standard equipment. Cost pressure from fleet procurement of electric commercial vehicles compresses margins for standalone regenerative braking module suppliers.
Motor control dominates installed base. Power conversion is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering clusters while cost-sensitive volume production migrates toward Asian manufacturing bases. This asymmetry reshapes where inverter suppliers capture margin versus scale.
United States
EPA tailpipe emissions rules and NHTSA FMVSS functional safety mandates tighten efficiency thresholds for electric commercial vehicles. Heavy-duty truck suppliers pre-qualify hardware to locked 2027 certification deadlines. California CARB fleet mandates concentrate buyer power among logistics operators in the Los Angeles Basin negotiating multi-year platform commitments.
Germany
Stuttgart, Munich, and Nuremberg engineering clusters anchor concentrated automotive inverter R&D with Bosch, Siemens, and ZF. EU Green Deal timelines accelerate rail fleet modernization, expanding multilevel inverter demand. EMA-equivalent transport regulators enforce parallel CE marking and F-Gas compliance for thermal management subsystems.
China
NMPA and MIIT coordinate GB standards for domestic new energy vehicle inverter certification. Dual carbon goals and MIIT production quotas drive procurement of high-voltage power electronics. Yangtze River Delta manufacturing bases concentrate cost-optimized inverter packaging for both domestic OEMs and export markets.
Japan
METI industrial policy supports silicon carbide substrate investments that insulate domestic suppliers from foundry allocation cycles. Automotive OEMs in the Nagoya and Tokyo corridors co-design integrated motor-inverter assemblies. JIS standards and PMDA-equivalent certification requirements extend validation timelines for medical-adjacent mobility applications.
India
PLI scheme production-linked incentives attract inverter packaging investments to serve emerging South Asian EV demand. BIS standards and CEA grid integration rules shape domestic qualification requirements. Tamil Nadu and Gujarat manufacturing corridors concentrate foreign direct investment in power electronics assembly.
Traction Inverter Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive returns across the supply base. Captive semiconductor foundries capture upstream margin while fabless assemblers face supply security constraints. Three strategic archetypes dominate: integrated power module producers controlling wafer-to-vehicle value chains, dedicated substrate investors insulating against foundry cycles, and software-calibration specialists tying hardware performance to OEM motor maps. Competitive moves concentrate on capacity expansion for wide bandgap semiconductors and strategic partnerships for 800V platform co-development.
Among German-based industrial conglomerates, Continental AG, Robert Bosch GmbH, and Siemens AG occupy positions spanning inverter hardware through vehicle integration. These Stuttgart and Munich-anchored players exemplify the integrated archetype, leveraging proximity to premium OEM engineering centers. Mitsubishi Electric Corporation represents the substrate-investment archetype, with Japanese industrial policy supporting dedicated silicon carbide capacity. Infineon Technologies AG anchors the semiconductor-specialist tier, supplying power modules across multiple inverter assemblers.
| Leading Market Players |
|---|
| Continental AG |
| Mitsubishi Electric Corporation |
| Robert Bosch GmbH |
| Toshiba Corporation |
| Siemens AG |
| BorgWarner Inc. |
| Hitachi Ltd. |
| ZF Friedrichshafen AG |
| Infineon Technologies AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German automotive OEMs and silicon carbide substrate producers lock in multi-year price visibility while constraining spot-market access for fabless assemblers. These arrangements concentrate pricing power among captive foundry operators in Stuttgart and Munich engineering clusters.
Pricing Analysis
Configured-to-order pricing for 800V silicon carbide modules commands substantial premiums over standard 400V IGBT configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by switching frequency certification and thermal cycling grade. Cost compression in standard-tier IGBT replacements is intensifying because tier-two suppliers liquidate stranded silicon inventory. Fleet procurement managers at California logistics operators exhibit highest price sensitivity, while premium European OEM platform engineers prioritize performance over unit cost.
Supply Chain Analysis
Germany and Japan anchor power module packaging and substrate production for automotive traction inverters. The supply chain draws from 150mm and 200mm silicon carbide wafers, copper thermal interface materials, and epoxy molding compounds. Single-source vulnerability concentrates among three merchant substrate vendors supplying wide bandgap semiconductors. Distribution runs through tier-one system integrator channels for standard three-phase units, while multilevel rail applications increasingly bypass intermediaries for direct OEM negotiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traction inverter supply constitutes a defensive-moat market where regulatory entrenchment around NHTSA FMVSS functional safety certification creates substantial switching costs for OEM procurement teams.
For Market Incumbents: Shield market position by accelerating captive silicon carbide substrate capacity additions in German manufacturing corridors and deepening software-calibration lock-in with OEM-specific motor maps. The threat of gallium nitride auxiliary conversion suppliers expanding into primary traction applications demands preemptive gate driver circuit R&D investment. For New Entrants and Emerging Players: Differentiate on thermal management subsystem integration for heavy-duty electric truck platforms facing locked EPA certification deadlines. White-space concentration sits with bidirectional inverter qualification for FERC-interfaced vehicle-to-grid applications in United States utility territories. A direct OEM co-development partnership model bypasses entrenched tier-one system integrator channels. For Investors and Strategic Acquirers: Fabless inverter assemblers with locked foundry allocation agreements represent the most attractive acquisition target archetype for portfolio exposure to 800V platform migration. Long-term viability hinges on five-to-ten year semiconductor supply security rather than near-term margin capture. The signal to watch is EPA pre-qualification announcement timing for 2027 heavy-duty certification deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Capacity Expansion | Captive substrate production insulates Mitsubishi Electric and Infineon from foundry allocation cycles. |
| 800V Platform Co-Development Partnership | Bosch and ZF deepen Stuttgart engineering cluster ties with premium European OEM engineering centers. |
| Software-Defined Inverter Investment | Calibration loop control ties hardware performance to OEM-specific motor maps and reduces substitution risk. |
| Rail Transport Multilevel Qualification | Siemens and Mitsubishi Electric capture EU Green Deal fleet modernization procurement outside automotive. |
| India PLI Manufacturing Footprint | Foreign direct investment in Tamil Nadu and Gujarat corridors accesses South Asian EV component demand. |
Study Parameters
A spread of perspectives from OEM platform engineers, tier-one procurement directors, power module packaging specialists, and thermal management subsystem designers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, EPA certification databases, MIIT GB standard publications, and IHS Markit vehicle production data. Bottom-up unit economics and top-down market sizing triangulated across the analysis window.
Segmentation dimensions modeled span product type topology, semiconductor technology tier, end-user application, and geographic production cluster. CAGRs were derived from installed base replacement cycles and new platform adoption curves across the projection horizon. Forecast inputs incorporated silicon carbide substrate capacity expansion timelines and NHTSA FMVSS pre-qualification completion rates.
Material uncertainties — silicon carbide wafer supply disruptions, EPA certification deadline shifts, and divergent semiconductor export control enforcement — sit outside the modeled envelope. Forecasts reflect documented assumptions about foundry allocation stability and OEM platform migration pacing. Recalibration cycles align with material shifts in substrate capacity announcements and regulatory pre-qualification milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Three-Phase String Inverter Market
Power Systems
AC DC Power Adapter Market
Power Systems
Harmonic Generators Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Synchrophasors Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Gan-Powered Chargers Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Shunt Voltage References Market
Power Systems
Series Reactor Market
Power Systems
South America DC Distribution Network Market