
 North America Electric Vehicle Power Inverter Market | 2026-2036
North America Electric Vehicle Power Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Power Inverter Market Analytics
Market Context
The North America electric vehicle power inverter market is rebalancing between premium silicon carbide architectures and commodity IGBT platforms as battery-electric truck volumes scale. Continental AG leverages its integrated power electronics manufacturing in Mexico to serve Detroit Three OEM programs. Robert Bosch GmbH anchors its North American inverter strategy through its Anderson, South Carolina facility focused on 800-volt architectures. Denso Corporation competes via its Tennessee operations supplying thermal-integrated inverter modules for hybrid and full-electric platforms.
Technical Definition and Structural Segments
An electric vehicle power inverter is a power electronics subsystem that converts direct current from traction battery packs into alternating current for electric motors, typically operating at switching frequencies between 10 kHz and 20 kHz with voltage classes spanning 400V to 800V. Silicon Carbide technology commands the fastest expansion trajectory due to reduced switching losses and thermal management advantages in high-power density applications. IGBT platforms retain volume dominance across mid-range passenger vehicles where cost optimization outweighs efficiency premiums. Bidirectional inverter configurations are gaining structural importance as vehicle-to-grid integration requirements tighten across utility interconnection standards.
Regulatory Frame and Outlook
The US EPA tailpipe emissions standards and NHTSA corporate average fuel economy frameworks mandate fleet-wide CO2 reductions that compel OEM inverter efficiency gains. The IRA clean vehicle tax credit structure and domestic content provisions shape supplier location decisions and technology qualification pathways. Stakeholders must monitor how California Air Resources Board advanced clean trucks rules cascade into procurement specifications for fleet operators across the Southwest freight corridor.
Market Dynamics
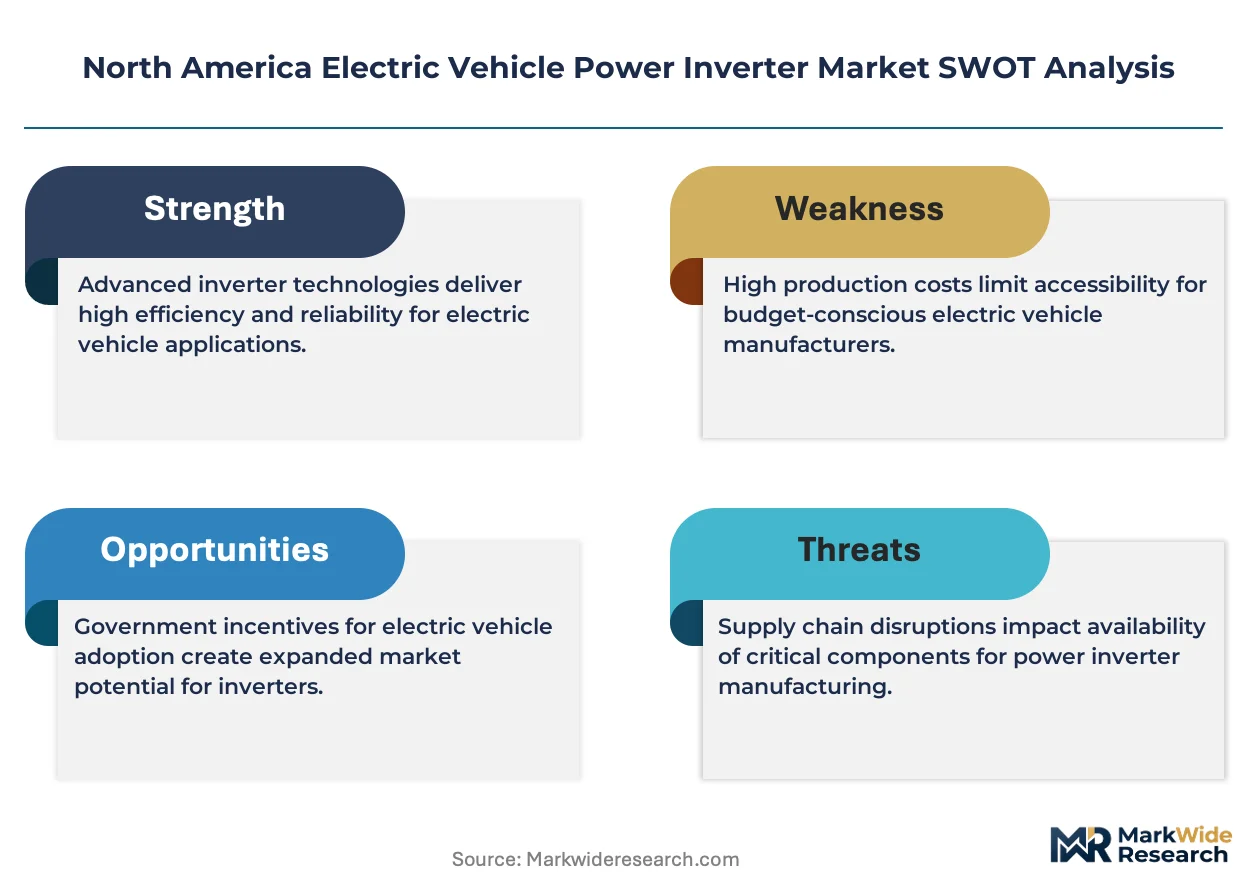
SiC substrate supply concentration and the IRA domestic content provisions are compressing inverter qualification timelines while fragmenting supplier tiers between captive OEM programs and independent module houses.
Growth Catalysts
- EPA tailpipe emissions standards:The US EPA mandates compel Class 8 truck OEMs to electrify powertrains, directly expanding addressable inverter capacity requirements across heavy-duty platforms.
- Freight corridor electrification:California's I-710 and I-80 freight corridors are deploying charging infrastructure that specifies 800V-compatible inverters for drayage and regional-haul battery-electric trucks.
- Silicon Carbide wafer scaling:Wolfspeed's Mohawk Valley fab and Coherent's substrate expansion are improving SiC die availability for traction inverters previously constrained by material bottlenecks.
Market Restraints
- Substrate cost volatility:150mm SiC wafer prices remain elevated versus silicon IGBT equivalents, compressing gross margins for mid-power inverter platforms serving price-sensitive passenger segments.
- Single-source packaging dependency:Direct-bonded copper substrate supply concentrates among Japanese and Korean metallization houses, exposing inverter module assemblers to geographic concentration risk.
- IGBT platform persistence:Mature IGBT inverter architectures retain cost advantages in 400V passenger applications, slowing SiC penetration where efficiency premiums fail to offset bill-of-materials deltas.
Strategic Opportunities
- Texas battery manufacturing clusters:Tesla's Gigafactory Texas and emerging cell plants in the state are creating localized demand for integrated inverter-battery pack assemblies with reduced logistics costs.
- Vehicle-to-grid bidirectional standards:IEEE 1547-2018 interconnection requirements and FERC Order 2222 are mandating bidirectional inverter capabilities, opening aftermarket retrofit and OEM qualification pathways.
- Thermal-integrated module convergence:Combining inverter power stages with refrigerant-based cooling loops enables power density improvements that discrete thermal management cannot match.
Industry Challenges
- Power electronics talent scarcity:The shortage of engineers with combined magnetics, thermal, and firmware expertise is extending inverter development cycles beyond platform launch deadlines.
- Functional safety certification timelines:ISO 26262 ASIL-D qualification for 800V architectures requires 18-24 month validation windows that misalign with accelerated vehicle program schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Power Inverter Market |
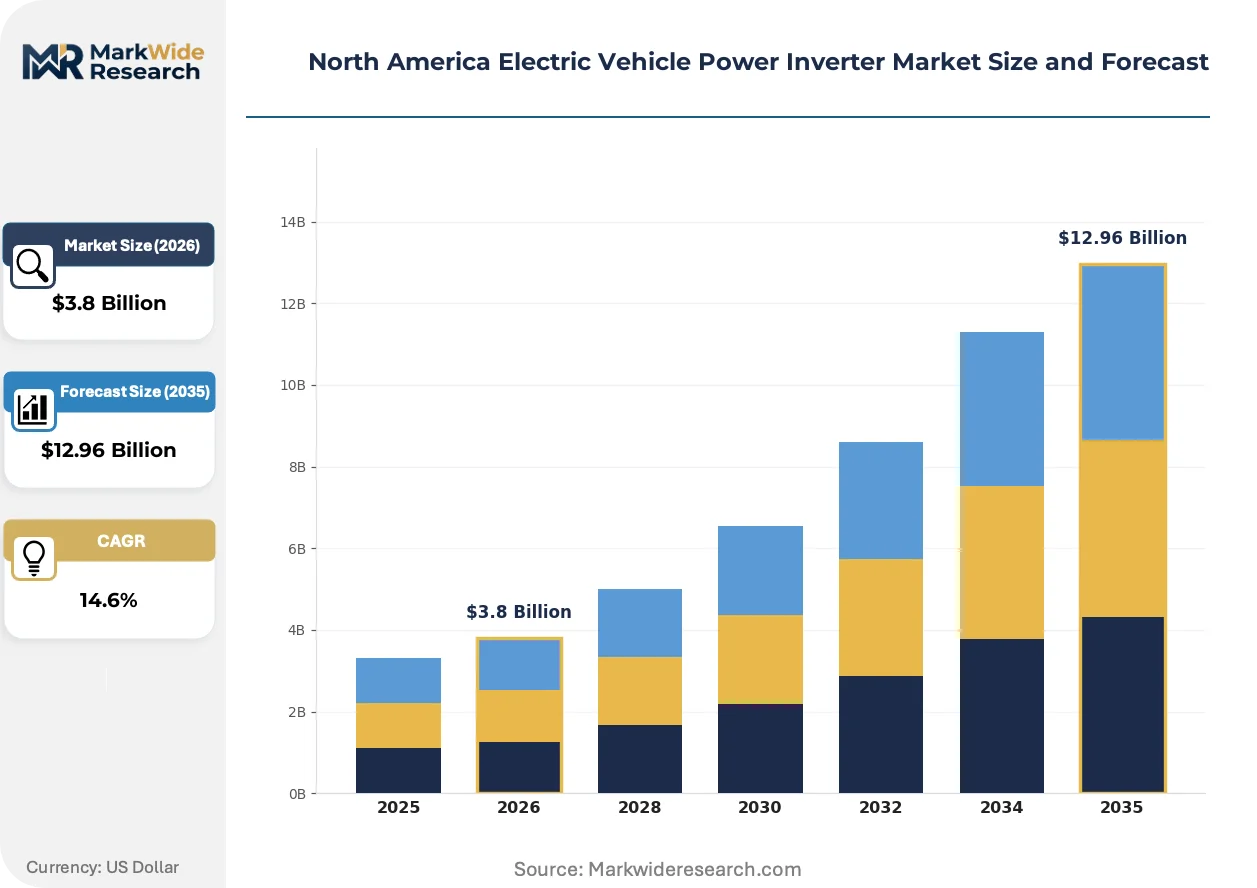
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bidirectional Inverter, DC-DC Converter, Onboard Charger, Offboard Charger Technology: Silicon Carbide, Gallium Nitride, IGBT, MOSFET End User: OEMs, Tier-1 Suppliers, Fleet Operators, Aftermarket Providers Capacity: Low Power, Medium Power, High Power, Ultra-High Power |
| Companies Covered | Toyota Industries Corporation, Aptiv PLC, Continental AG, Hitachi Automotive Systems Ltd, Valeo Group, Robert Bosch GmbH, Mitsubishi Electric Corporation, Vitesco Technologies, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Power Inverter Market Evolving Landscape
Power semiconductor packaging and thermal management architectures are converging to support continuous-duty cycles in commercial electrification, while regulatory pressure on supply chain provenance is reshaping qualification protocols.
Silicon Carbide MOSFETs in discrete and module configurations are electrifying traction inverter efficiency benchmarks. Class 8 truck powertrains from Detroit Three OEMs are adopting 1200V SiC platforms for 800V architectures. This electrifying technology is compressing thermal management system mass and enabling continuous-grade power output previously unattainable with silicon IGBTs.
The IRA clean vehicle tax credit domestic content provisions are restructuring supplier geography requirements. Inverter module assemblers must demonstrate North American wafer fabrication and packaging to qualify vehicles for consumer credits. Battery-electric truck programs targeting fleet tax credits under IRC Section 45W are prioritizing domestic-content-compliant inverter sourcing.
Fleet procurement is consolidating inverter specifications across mixed-duty vehicle portfolios. Large operators are mandating common 800V architectures across medium-duty delivery and heavy-duty regional-haul segments to simplify maintenance training and spare parts inventory. This specification convergence is most visible among California-based freight operators subject to CARB advanced clean trucks rules.
North America Electric Vehicle Power Inverter Market Segmentation
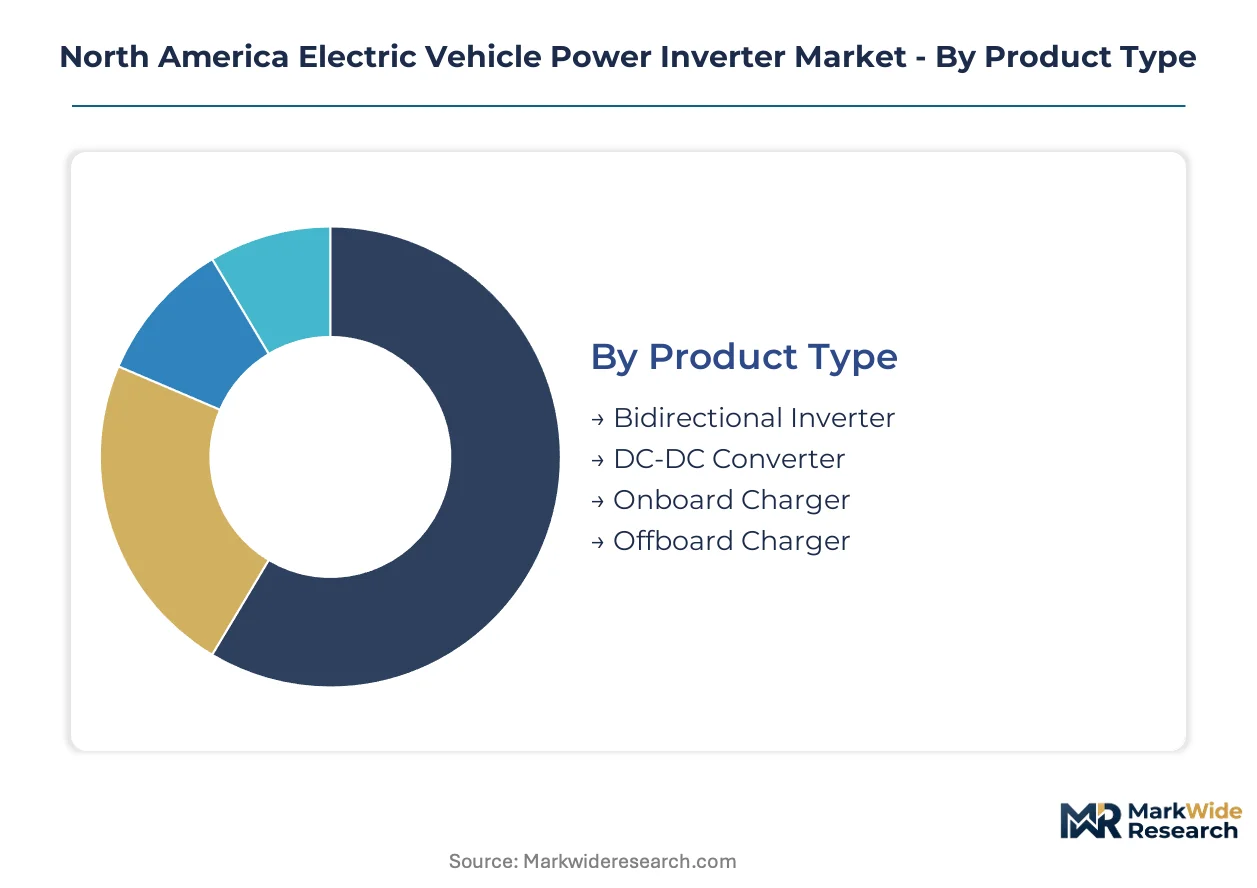
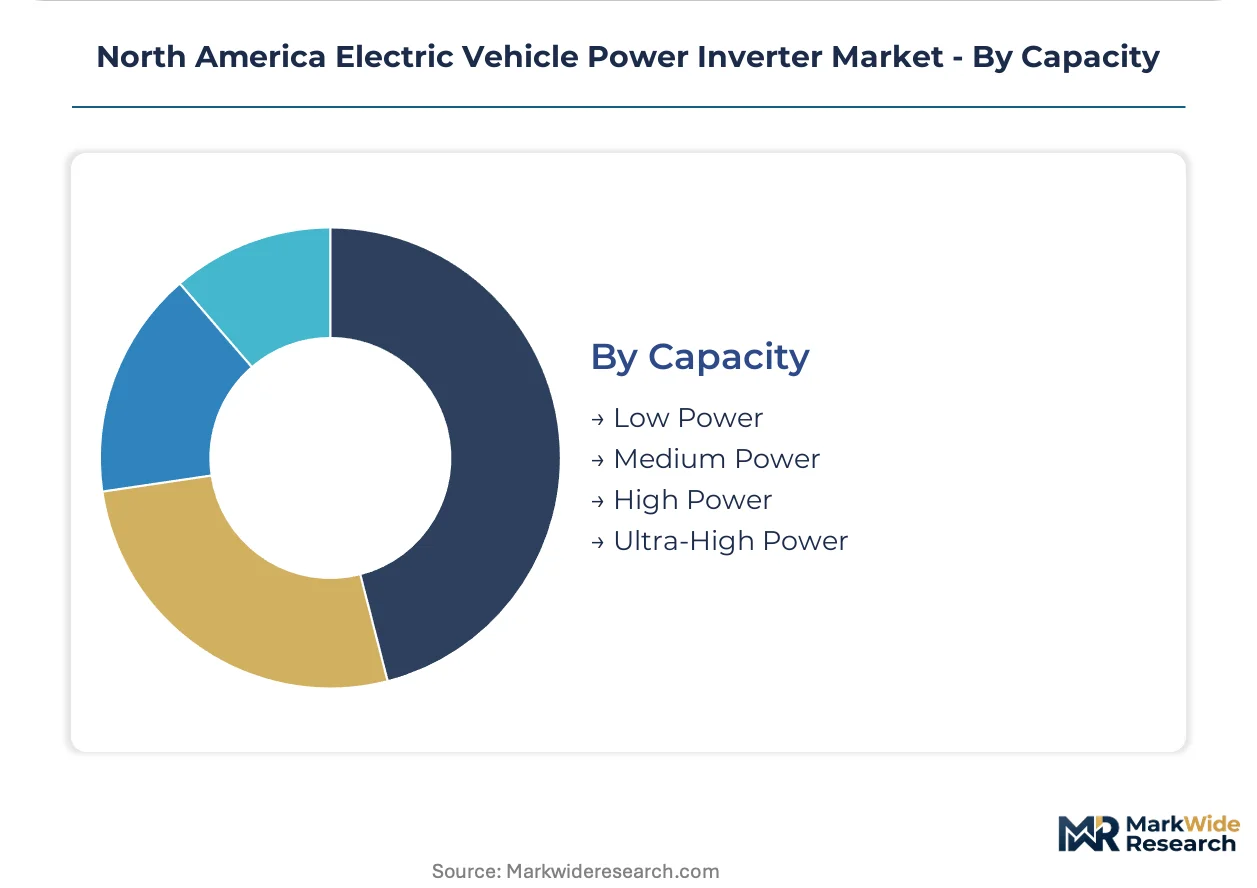
North American inverter procurement patterns fragment across power classes, semiconductor technologies, and supply chain tiers. Each segmentation dimension carries distinct qualification protocols, margin structures, and geographic sourcing requirements under IRA domestic content rules.
Product Type:
Supply concentration among integrated module houses shapes which product categories dominate procurement portfolios.
- Bidirectional Inverter:Enables vehicle-to-grid power flow through reversible DC-AC conversion architectures. Fleet operators in California's freight corridors specify bidirectional units for depot-based energy arbitrage under FERC Order 2222 compliance timelines.
- DC-DC Converter:Steps voltage between traction battery packs and auxiliary systems. Demand clusters around Texas battery manufacturing facilities where integrated converter-inverter assemblies reduce pack-to-powertrain interface complexity.
- Onboard Charger:Converts AC grid input to DC battery charging current. OEM programs prioritize 19.2 kW capable units for residential overnight charging compatibility.
- Offboard Charger:External DC fast charging infrastructure bypasses onboard conversion. Megawatt-scale corridor charging along I-80 and I-710 specifies standalone rectification systems.
Today's leader: DC-DC Converter. Tomorrow's challenger: Bidirectional Inverter.
Technology:
Cost tier differentiation separates premium efficiency platforms from commodity silicon architectures serving price-sensitive segments.
- Silicon Carbide:Wide-bandgap semiconductor delivering switching frequencies above 50 kHz with reduced thermal losses. Wolfspeed's Mohawk Valley fab and Coherent's substrate expansion are improving die availability for 800V Class 8 truck programs.
- IGBT:Insulated-gate bipolar transistor platforms retain cost advantages in 400V passenger applications where efficiency premiums fail to offset bill-of-materials deltas.
- Gallium Nitride:Emerging wide-bandgap alternative for sub-100 kW applications. Limited traction inverter deployment due to voltage rating constraints versus SiC.
- MOSFET:Silicon metal-oxide-semiconductor field-effect transistors serve auxiliary power modules and low-voltage DC-DC stages.
Silicon Carbide commands the steepest expansion trajectory as substrate scaling resolves previous material bottlenecks.
End User:
Customer type determines specification authority, with fleet operators consolidating procurement power across mixed-duty portfolios.
- Fleet Operators:Large freight purchasers mandate common 800V architectures across medium-duty delivery and heavy-duty regional-haul segments. CARB advanced clean trucks rules drive specification convergence among California-based operators.
- OEMs:Detroit Three manufacturers specify inverter modules through captive power electronics divisions or exclusive supplier programs.
- Tier-1 Suppliers:Independent module houses compete for platform-agnostic supply contracts outside OEM captive sourcing.
- Aftermarket Providers:Bidirectional retrofit specialists target vehicle-to-grid qualification pathways under IEEE 1547-2018 interconnection standards.
Fleet procurement consolidation is displacing OEM-centric specification patterns.
Capacity:
Volume concentration follows commercial electrification timelines, with heavy-duty platforms driving capacity scaling requirements.
- High Power:150-300 kW continuous output for Class 6-8 regional-haul battery-electric trucks. EPA tailpipe emissions standards compel OEM efficiency gains in this bracket.
- Ultra-High Power:Exceeds 300 kW for long-haul and vocational heavy-duty applications. Thermal-integrated module convergence enables continuous-grade power output.
- Medium Power:50-150 kW serving light commercial and medium-duty delivery segments. IGBT platforms retain share here.
- Low Power:Below 50 kW for passenger vehicle auxiliary systems and micro-mobility applications.
Ultra-High Power is gaining share fastest as freight corridor electrification accelerates drayage and regional-haul deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics engineering talent concentrates in Detroit's automotive corridor, Austin's semiconductor ecosystem, and Ontario's manufacturing belt, anchoring inverter design and production capacity across the continent.
United States
Class 8 truck electrification and freight corridor infrastructure deployment drive inverter demand. EPA tailpipe emissions standards compel Detroit Three OEMs to source high-capacity SiC platforms. Texas battery manufacturing clusters around Tesla's Gigafactory Texas and emerging cell plants generate localized demand for integrated inverter-battery assemblies.
Canada
Ontario's automotive supplier base retools for EV component production. Federal clean technology investment tax credits support domestic inverter manufacturing qualification. Windsor and Hamilton industrial corridors attract power electronics module assembly for cross-border OEM supply.
Mexico
Integrated power electronics manufacturing in Baja California and central Mexico serves US-bound OEM programs. Nearshoring momentum accelerates as IRA domestic content provisions reshape supplier geography. Querétaro and Aguascalientes host expanding inverter module operations for North American vehicle platforms.
North America Electric Vehicle Power Inverter Market Competitive Landscape
Top-tier vendors anchor captive OEM supply relationships, while independent module houses compete for platform-agnostic contracts. Market structure reflects a bifurcation between integrated automotive suppliers with power electronics divisions and specialized semiconductor packaging firms. Two strategic archetypes dominate: thermal-integrated system specialists and wide-bandgap semiconductor pure-plays. Capacity expansion and strategic partnerships constitute the primary competitive moves as substrate scaling resolves material bottlenecks.
Among German-based diversified automotive suppliers, Continental AG and Robert Bosch GmbH occupy positions exemplifying integrated power electronics manufacturing for 800-volt architectures. Japanese industrial conglomerates Denso Corporation and Mitsubishi Electric Corporation represent the thermal-integrated module convergence archetype, with Tennessee and North American operations supplying hybrid and full-electric platforms.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| Aptiv PLC |
| Continental AG |
| Hitachi Automotive Systems Ltd |
| Valeo Group |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| Vitesco Technologies |
| Denso Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up module specialists anchor inverter supply tiers, compressing margin structures through volume aggregation while IRA domestic content rules reshape geographic sourcing premiums. Their consolidation of mid-tier packaging operations tightens pricing discipline across 400V IGBT platforms serving price-sensitive passenger segments.
Pricing Analysis
Bundled inverter-battery pack assemblies command premiums over discrete module procurement, with Texas manufacturing clusters favoring integrated sourcing for logistics savings. Pricing stratifies across SiC premium tiers, ISO 26262 ASIL-D certification grades, and volume scale commitments from fleet operators. Cost compression in mid-power IGBT segments intensifies as captive OEM programs squeeze independent suppliers. Fleet operators exhibit highest price sensitivity through consolidated procurement mandates, while Detroit Three OEMs absorb efficiency premiums for Class 8 truck electrification.
Supply Chain Analysis
ISO 26262 ASIL-D and IEEE 1547-2018 certification gating restricts qualified suppliers to a narrow tier of thermal-integrated module houses. Raw material flows draw from Japanese direct-bonded copper substrate specialists, Korean metallization providers, and domestic Wolfspeed SiC wafer fabrication. Single-source packaging dependency in Asian metallization exposes assemblers to tariff exposure and logistics chokepoints. Distribution runs through captive OEM supply programs and independent Tier-1 module houses serving aftermarket retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America electric vehicle power inverter market functions as a stable compounder, with EPA tailpipe emissions standards and IRA clean vehicle provisions locking in decade-long procurement visibility for qualified suppliers.
For Market Incumbents: Cement thermal-integrated module capabilities through refrigerant-based cooling convergence, defending against pure-play SiC semiconductor entrants. Prioritize captive supply relationships with Detroit Three OEMs while extending ISO 26262 ASIL-D certification coverage to 800V architectures. Capacity addition in Tennessee and South Carolina operations secures IRA domestic content qualification timelines.
For New Entrants and Emerging Players: Begin with bidirectional inverter retrofit specialization targeting California fleet depots under FERC Order 2222 compliance windows. The aftermarket vehicle-to-grid segment offers lowest certification barriers and fastest qualification pathways. Pursue partnership-based go-to-market models with IEEE 1547-2018 interconnection specialists rather than direct OEM supply competition.
For Investors and Strategic Acquirers: Valuations sit cheapest among thermal-management-pure-play specialists lacking SiC die sourcing relationships. Long-term viability over the next decade rests on substrate supply security and captive OEM program wins. Monitor Wolfspeed Mohawk Valley fab utilization rates as the inflection signal for SiC die availability and pricing compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | 800V architecture convergence across medium and heavy-duty segments simplifies fleet maintenance training. |
| Battery Supply Agreement | Integrated inverter-pack assemblies with Texas Gigafactory operations reduce logistics costs for regional OEMs. |
| Software-Defined Vehicle Investment | Firmware-over-the-air capabilities extend inverter lifecycle value through performance optimization updates. |
| Geographic Manufacturing Footprint | Mexico nearshoring expansion serves IRA domestic content requirements for cross-border OEM programs. |
| Charging Infrastructure Partnership | Corridor charging alignment with I-80 and I-710 freight routes secures fleet specification mandates. |
Research Methodology
Bottom-up fleet procurement modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, thermal management specialists, and CARB regulatory affairs officers combined with secondary validation from EPA filings, FERC Order 2222 implementation records, SEC 10-K power electronics disclosures, and IHS Markit vehicle production databases. Triangulation across these sources ensures demand-side and supply-side estimates converge within acceptable variance bands.
Historical trendline analysis of SiC substrate scaling, IGBT platform persistence, and freight corridor electrification timelines informed projection frameworks across the analysis window. Segmentation dimensions span power capacity tiers, semiconductor technology nodes, vehicle class architectures, and end-user procurement authority. CAGRs derive from regression-adjusted growth curves incorporating IRA tax credit phase-out assumptions and EPA compliance deadline clustering. Industry-specific inputs include Wolfspeed fab capacity ramps and California Air Resources Board advanced clean trucks rule adoption rates.
Several conditions sit outside the modeled scope, including potential NHTSA rulemaking shifts, raw material export restrictions from substrate-producing jurisdictions, and breakthrough GaN voltage rating advances. Forecasts reflect documented assumptions regarding SiC die yield improvements and thermal interface material cost trajectories. A model refresh is warranted upon material change in IRA domestic content qualification thresholds or EPA tailpipe emissions standard stringency revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Telecom Tower Power System Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
PV Micro Inverters Market
Power Systems
Global Power Semiconductor Switches Market
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
Charge Controller System Market
Power Systems
Synchrophasors Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Harmonic Generators Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Battery Balancer Market
Power Systems
Japan Surge Protector Market
Power Systems
Synchronous Condenser Market