
 Hybrid Inverters Market | 2026-2036
Hybrid Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Inverters Market Analytics
Chinese power electronics manufacturing is consolidating as the dominant supply base for hybrid inverter components. Huawei leverages its integrated semiconductor and software stack to control costs across multi-mode inverter platforms. Sungrow anchors its position through captive production of IGBT modules and energy storage system bundling. Fronius competes from Europe with specialized high-frequency transformer architectures for residential battery-based systems.
A hybrid inverter converts DC power from solar arrays, wind turbines, or battery banks into AC power for grid injection or local consumption, typically operating at 3-20 kW residential and 50 kW+ commercial scales with MPPT voltage ranges of 150-1000VDC. Battery-based configurations command premium positioning as solar-plus-storage deployment accelerates. The residential end user segment leads volume absorption in Europe and Australia, while the utilities segment captures the deepest project values in North American and Middle Eastern markets. Multi-mode technology is displacing simpler grid-tied-only architectures as net metering policies tighten across multiple jurisdictions.
The EU Green Deal and F-Gas Regulation shape product design mandates for thermal management and refrigerant-based cooling systems in European-sold units. The IRA's domestic content bonus credits in the United States redirect procurement toward North American-assembled inverters with qualifying cell and module supply chains. India's BIS certification and PLI scheme for solar manufacturing create parallel compliance pathways for exporters targeting that market. Stakeholders must track how battery safety standards from IEC and evolving grid codes in major demand centers reshape certification requirements and factory location decisions.
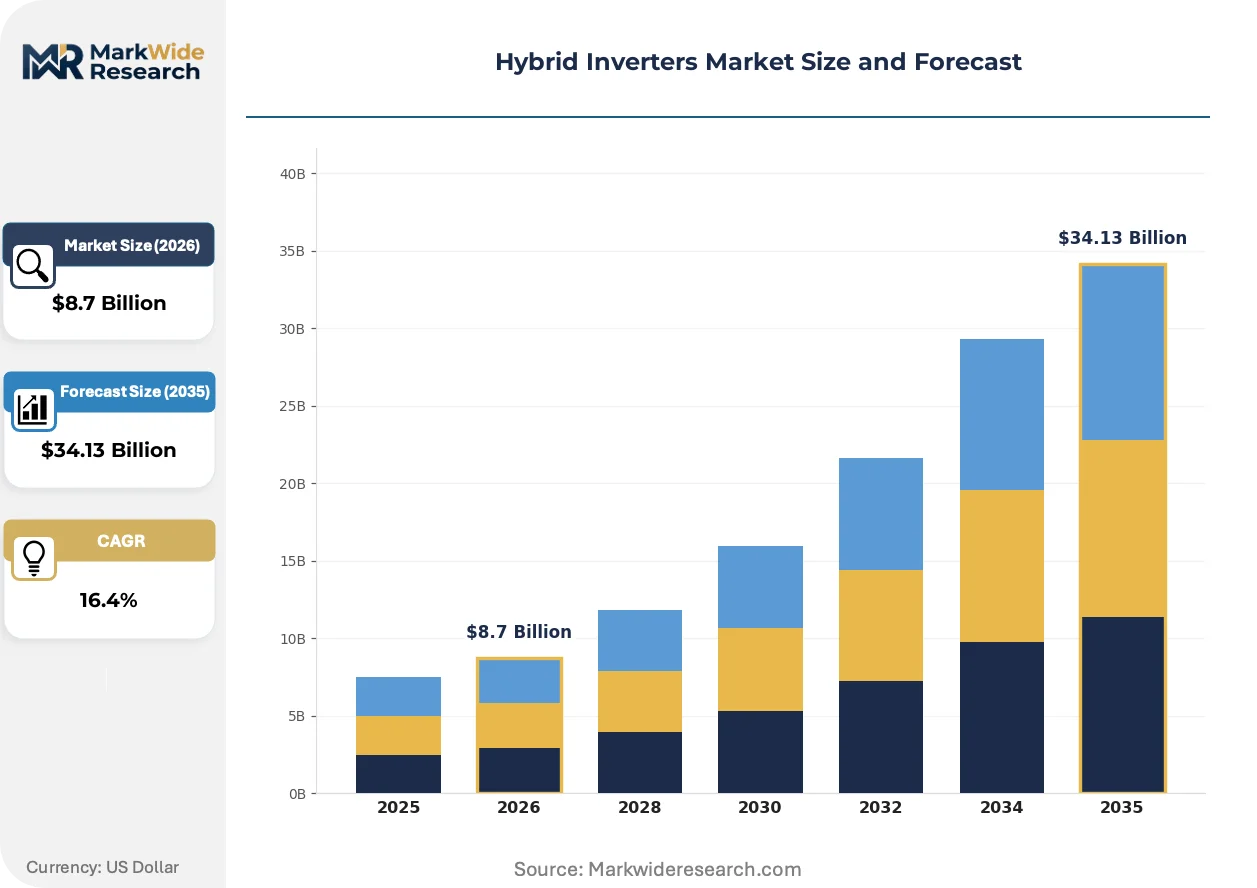
Market Dynamics
Multi-mode inverter architectures are compressing deployment timelines for solar-plus-storage systems as net metering policies tighten across Germany, California, and Australia. This technology transition is forcing recalibration of product roadmaps and factory location decisions among power electronics suppliers.
Growth Catalysts
- EU Green Deal building mandates:Germany's national subsidy frameworks for residential efficiency retrofits are pulling battery-ready inverters into renovation pipelines.
- Utility-scale procurement concentration:Independent power developers in Texas and Queensland are bundling 50 kW+ hybrid systems with grid-forming capabilities for frequency regulation contracts.
- Semiconductor integration advances:Silicon carbide power modules are reducing switching losses and thermal management costs in high-voltage string inverters.
Market Restraints
- IGBT supply concentration:Captive production of power modules concentrates among three Chinese manufacturers, creating single-source vulnerability for non-integrated assemblers.
- F-Gas Regulation compliance costs:The EU's phasedown of fluorinated refrigerants is forcing redesign of liquid-cooled commercial inverters for European certification.
- Lead-acid battery substitution:Legacy off-grid installations in Southeast Asia and sub-Saharan Africa delay lithium-ion hybrid adoption due to sunk capital in existing battery banks.
Strategic Opportunities
- India PLI scheme localization:The production-linked incentive for solar manufacturing creates tariff-advantaged assembly pathways for exporters targeting Indian residential and agricultural pump segments.
- V2H integration convergence:Bidirectional charging protocols for electric vehicles are opening retrofit markets for residential inverters with EV-ready AC coupling.
- Installer direct channels:Bypassing traditional electrical distributors through certified installer networks is capturing margin in Australian and Dutch residential markets.
Industry Challenges
- IEC 62485-3 certification timelines:Battery safety testing for hybrid systems adds 4-6 months to product launch schedules in European markets.
- Legacy SCADA integration:Utility-scale projects require custom protocol bridges to connect new hybrid inverters with existing plant control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Inverters Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid-Tied, Off-Grid, Battery-Based, Multi-Mode Technology: Solar, Wind, Diesel, Fuel Cell End User: Residential, Commercial, Industrial, Utilities Installation Type: Wall-Mounted, Rack-Mounted, Portable, Integrated |
| Companies Covered | Fronius, GoodWe, Huawei, Ginlong Solis, Deye, Sungrow, Delta, Growatt, SMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Inverters Market Evolving Landscape
Solid-state power conversion and intelligent thermal management are compressing inverter form factors while expanding operating voltage windows. These advances are enabling new installation geometries and reducing balance-of-system costs.
Silicon carbide MOSFETs are overtaking silicon IGBTs in 1000VDC residential string inverters by reducing switching losses and enabling higher switching frequencies. German and Australian installers are specifying SiC-based units for retrofit projects where space constraints limit heat sink sizing. This transition is compressing bill-of-material costs for premium-tier products while forcing legacy silicon suppliers into price defense in standard segments.
The IRA's domestic content bonus credits are redirecting procurement toward North American-assembled inverters with qualifying cell and module supply chains. Project developers in Texas and Arizona are restructuring offtake agreements to capture the 10 percentage point credit adder. This policy mechanism is accelerating factory announcements in Arizona and South Carolina while pressuring importers to establish tolling arrangements with domestic contract manufacturers.
Aggregator-mediated fleet control is displacing direct utility dispatch contracts for residential battery systems. Virtual power plant operators in California and South Australia are pooling thousands of behind-the-meter inverters to bid into frequency regulation markets. This procurement model shift is forcing inverter OEMs to embed standardized telemetry and control APIs rather than proprietary closed-loop systems.
Hybrid Inverters Market Segmentation
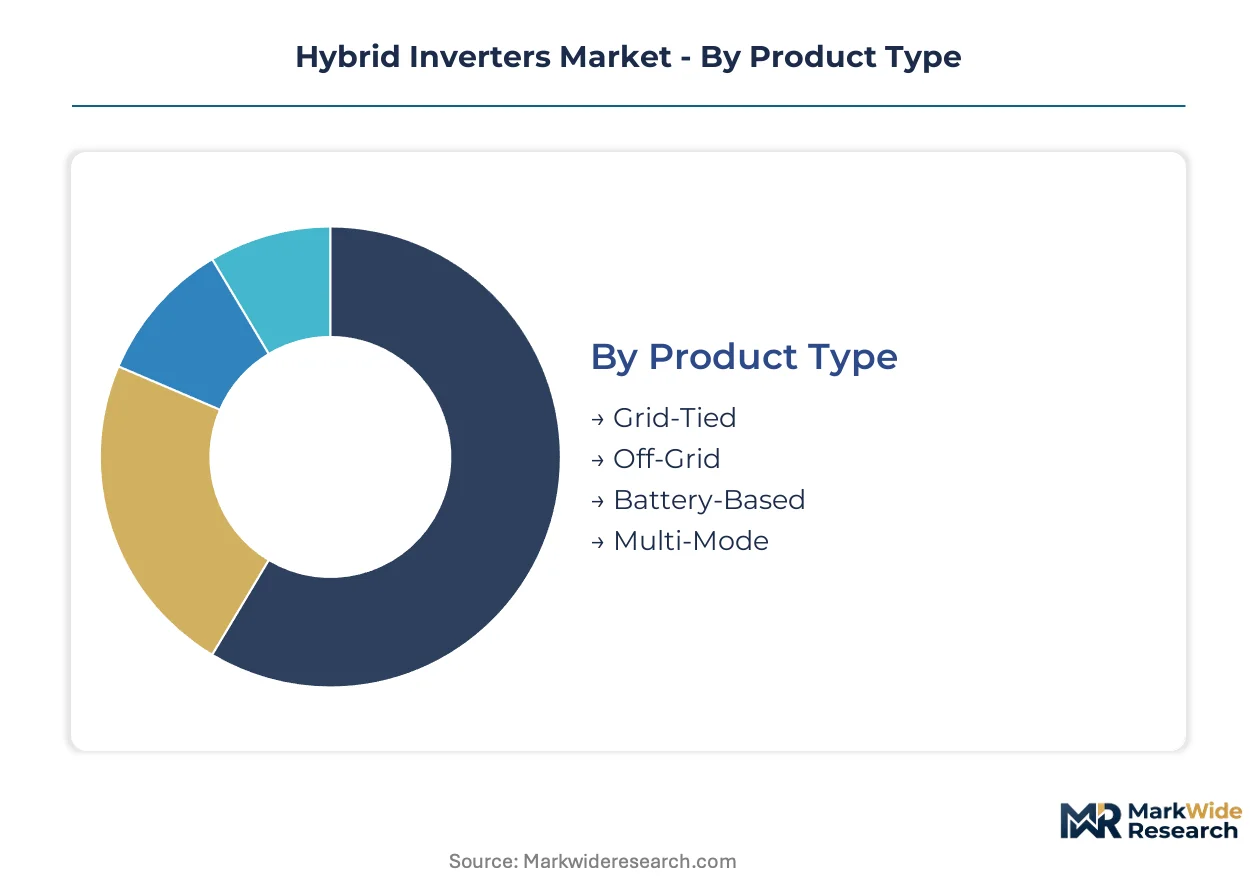
Product architecture determines capital deployment patterns across manufacturing, certification, and channel infrastructure. Segment boundaries in hybrid inverters reflect divergent power ratings, thermal management requirements, and software complexity that reshape supplier economics.
Product Type:
Capital intensity escalates with control system sophistication and battery integration depth. Multi-mode platforms demand redundant power stages and bidirectional conversion circuits that multiply R&D burn rates.
- Grid-Tied:Single-direction DC-to-AC conversion without storage coupling dominates legacy rooftop installations. Procurement concentrates in utility-scale solar farms across Texas and Arizona where net metering grandfathering still applies.
- Off-Grid:Standalone systems with integrated charge controllers serve remote mining camps and rural electrification projects in sub-Saharan Africa. Demand concentrates where grid extension costs exceed distributed generation economics.
- Battery-Based:DC-coupled architectures with dedicated battery management interfaces.
- Multi-Mode:Grid-forming inverters with seamless islanding capability.
Most installed capacity flows through Grid-Tied configurations. Expansion is steepest in Multi-Mode as California and Germany phase out net metering.
Technology:
Input source diversity determines semiconductor voltage ratings and MPPT algorithm complexity. Fuel cell and diesel hybrid systems command premium positioning through specialized waveform conditioning requirements.
- Solar:Photovoltaic string and central inverter platforms with 150-1000VDC input windows. Residential absorption in Germany and Australia drives volume, while utility procurement in Saudi Arabia and India reshapes supplier priorities.
- Wind:Variable frequency AC-to-AC conversion with active rectification stages. Demand clusters in coastal Denmark and onshore Texas corridors where distributed wind pairs with storage.
- Diesel:Legacy backup integration for hybrid minigrids.
- Fuel Cell:Low-voltage DC input with specialized boost stages.
Solar dominates current manufacturing volumes. Fuel Cell is gaining share fastest in South Korean and Japanese hydrogen demonstration zones.
End User:
Customer scale dictates service infrastructure, warranty duration, and software customization depth. Utility procurement runs through multiyear framework agreements with embedded performance guarantees.
- Residential:3-20 kW single-phase systems with plug-and-play commissioning. Australia's installer-direct channel and Germany's subsidy-stimulated renovation pipeline concentrate demand.
- Commercial:Three-phase string and small central inverters for C&I rooftops.
- Industrial:Megawatt-scale power conversion for manufacturing load management.
- Utilities:Containerized hybrid substations with grid-forming capability.
Residential captures the widest unit volumes. Utilities deliver the deepest project values through frequency regulation contracts.
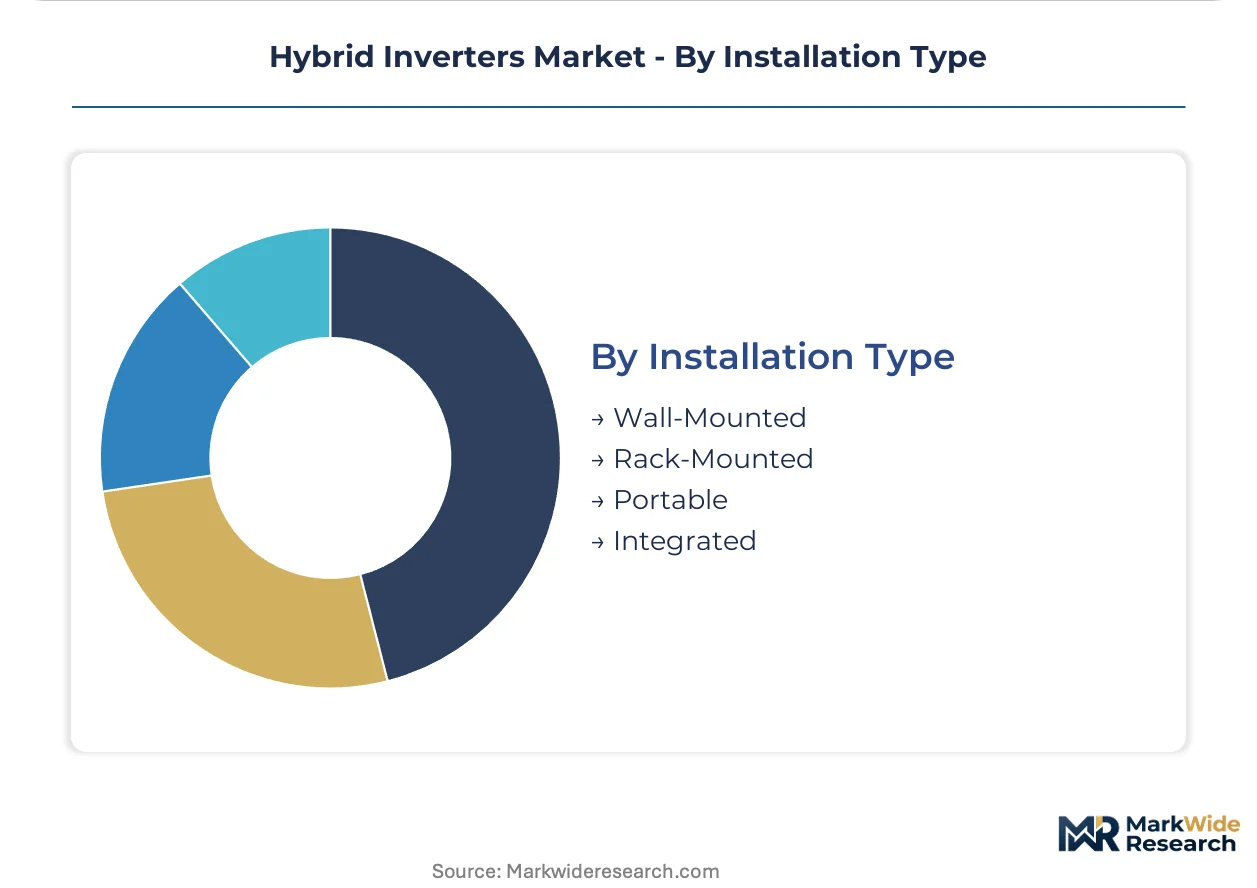
Installation Type:
Physical mounting geometry constrains thermal design, ingress protection ratings, and cabling topology. Integrated factory-built systems compress field labor but multiply transport costs.
- Wall-Mounted:Residential string inverters with IP65 enclosures for exterior placement. Dutch and Belgian installers specify slim form factors for narrow facade mounting.
- Rack-Mounted:Commercial and utility central inverters in climate-controlled enclosures.
- Portable:Mobile power units for construction and emergency response.
- Integrated:Factory-assembled storage-inverter combinations.
Wall-Mounted units move the highest volumes. Integrated systems are expanding most quickly as Australian and Californian developers pursue deployment speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with domestic content credits and streamlined certification pathways. Factory location decisions increasingly weigh compliance cost differentials against market access premiums.
United States
Texas and Arizona developers are restructuring offtake agreements to capture IRA domestic content bonus credits. FERC interconnection reforms are compressing queue timelines for utility-scale battery hybrid projects. Manufacturing announcements cluster in Arizona and South Carolina as suppliers establish tolling arrangements with domestic assemblers.
Germany
EU Green Deal building efficiency mandates are pulling battery-ready inverters into residential renovation pipelines. The F-Gas Regulation is forcing redesign of liquid-cooled commercial inverters for European certification. Industrial demand concentrates in Bavaria and North Rhine-Westphalia where manufacturing load management contracts proliferate.
China
Integrated semiconductor and power electronics manufacturing is consolidating as the dominant supply base for hybrid inverter components. MIIT dual carbon goals are accelerating silicon carbide module adoption in high-voltage string platforms. Production gravity centers on Yangtze River Delta and Pearl River Delta clusters serving export markets.
Australia
Queensland and South Australia are pooling behind-the-meter inverters into virtual power plant fleets bidding into frequency regulation markets. Installer-direct channels are capturing margin in residential markets bypassing traditional electrical distributors. TGA-equivalent grid code compliance is reshaping certification requirements for imported units.
India
Maharashtra and Gujarat are absorbing tariff-advantaged assembly from PLI scheme beneficiaries targeting agricultural pump and residential segments. BIS certification creates parallel compliance pathways for exporters. CEA technical standards for grid-connected solar systems are tightening inverter testing protocols.
Hybrid Inverters Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue silicon carbide integration and virtual power plant software stacks. The vendor base stratifies around captive semiconductor production, installer channel control, and grid-forming firmware capabilities. Three archetypes dominate: integrated power electronics conglomerates, specialized residential battery system suppliers, and utility-scale project developers with captive inverter sourcing. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure IGBT module supply and domestic assembly partnerships.
Among Chinese-integrated manufacturers, Huawei and Sungrow exemplify the conglomerate archetype through semiconductor stack control and energy storage bundling. Fronius represents the specialized European tier with high-frequency transformer architectures for residential battery systems. These anchors illustrate how geographic origin and vertical scope shape competitive positioning across certification-intensive markets.
| Leading Market Players |
|---|
| Fronius |
| GoodWe |
| Huawei |
| Ginlong Solis |
| Deye |
| Sungrow |
| Delta |
| Growatt |
| SMA |
| Others |
Value Network & Pricing Analysis
Silicon carbide MOSFET adoption in high-voltage string platforms is compressing switching losses while concentrating semiconductor procurement among Yangtze River Delta foundries. This technology transition simultaneously reduces bill-of-material costs for premium-tier products and amplifies pricing power for integrated manufacturers with captive SiC module production.
Pricing Analysis
Installer-direct channel margins in Australian and Dutch residential markets bypass traditional electrical distributor markups, compressing end-user pricing by 15-20 percentage points relative to wholesale routes. Pricing stratifies across premium SiC-based units, standard silicon IGBT architectures, and economy-tier legacy platforms with shorter warranty terms. Cost compression in standard segments is intensifying because Chinese integrated manufacturers are flooding export markets with bundled storage-inverter packages. Utility-scale developers in Texas exhibit the lowest price sensitivity due to IRA domestic content credit capture, while Southeast Asian off-grid installers remain most price-constrained by lead-acid battery substitution economics.
Supply Chain Analysis
IEC 62485-3 battery safety certification and F-Gas Regulation thermal management compliance create 4-6 month gating delays for European market entry, favoring suppliers with established testing relationships. IGBT module and silicon carbide wafer production concentrates in China, South Korea, and Japan, with Yangtze River Delta clusters serving as the dominant export hub. Raw material dependencies span high-purity silicon wafers, copper busbar stock, and aluminum heat sink extrusions. Single-source vulnerability concentrates among three Chinese power module manufacturers, exposing non-integrated assemblers to allocation risk during demand surges. Distribution runs through certified installer networks in Australia and Germany, direct OEM relationships for utility-scale developers, and traditional electrical distributors in legacy markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid inverters market functions as a geographic-arbitrage play where IRA domestic content credits in the United States create 10 percentage point effective cost advantages against imported alternatives, while EU F-Gas Regulation compliance costs erect protective moats for European-certified suppliers.
For Market Incumbents: Cement semiconductor stack control through backward integration into SiC module production or exclusive foundry partnerships, defending against emerging Chinese conglomerates with captive IGBT manufacturing. Prioritize certification investment in IEC 62485-3 battery safety and grid-forming firmware capabilities to maintain premium positioning as California and Germany phase out net metering. Capacity addition in Arizona and South Carolina captures IRA credit eligibility for North American utility-scale procurement.
For New Entrants and Emerging Players: Capture V2H bidirectional charging retrofit demand in residential markets where existing inverter installed bases lack EV-ready AC coupling. Agricultural pump segments in Maharashtra and Gujarat present the most penetrable white space under India's PLI scheme tariff advantages. A certified installer channel strategy bypasses entrenched distributor relationships in Australian and Dutch markets.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized European residential battery system suppliers with high-frequency transformer architectures but limited utility-scale exposure. Long-term viability over the projection horizon hinges on grid-forming firmware capabilities and virtual power plant software stack integration. The signal to watch is FERC interconnection reform implementation velocity in Texas and Arizona queue processing.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Integration | Reduces switching losses in Sungrow and Huawei high-voltage string platforms for German retrofit markets. |
| Domestic Content Assembly Partnership | Enables IRA credit capture for Texas utility-scale developers restructuring offtake agreements. |
| Virtual Power Plant Software Stack | Embeds standardized APIs for California and South Australia aggregator-mediated fleet control. |
| IEC 62485-3 Certification Investment | Accelerates European market entry for battery-based hybrid systems amid tightening safety mandates. |
| Installer-Direct Channel Expansion | Bypasses electrical distributor margins in Australian residential markets with slim wall-mounted form factors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and inverter OEM product managers with secondary validation against EIA project databases, IEA renewable technology reports, FERC interconnection filings, and customs trade records. Bottom-up installation data triangulated against top-down manufacturer shipment disclosures to reconcile volume estimates.
Segment-weighting approaches distributed value and unit forecasts across product architecture tiers, power rating bands, end-user categories, and regional regulatory clusters. CAGRs derived from fitted growth curves incorporating policy incentive phase-out schedules, net metering grandfathering cliffs, and semiconductor cost reduction trajectories. Key inputs included IRA domestic content credit interpretation, EU Green Deal building mandate implementation timelines, and silicon carbide penetration rate assumptions in residential string inverter platforms.
Underlying measurement precision varies by segment; utility-scale project pipelines carry tighter precision than distributed residential retrofit estimates due to disclosure requirements. Forecasts reflect assumptions regarding FERC queue reform velocity, BIS certification timeline stability, and IGBT supply allocation continuity. A model refresh is warranted upon material change in IRA domestic content bonus credit eligibility criteria or IEC battery safety standard revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
Modular Inverter Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
USB Power Adapters Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Power Electronics Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
South America Battery Management System Market
Power Systems
Battery Balancer Market
Power Systems
Battery Racks Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Shunt Capacitor Market
Power Systems
Thermal Management Systems Market
Power Systems
Global Next Generation Power Semiconductors Market