
 Grid Tie Inverter Market | 2026-2036
Grid Tie Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Grid Tie Inverter Market Analytics
Aftermarket service revenue is fragmenting between OEM captive programs and third-party inverter refurbishment networks. SMA Solar Technology sustains its European installed base through extended warranty and remote diagnostics services. Huawei Technologies leverages its domestic supply chain to dominate utility-scale deployments across Asia.
A grid tie inverter converts direct current from photovoltaic modules into alternating current synchronized with utility grid parameters, typically operating at efficiencies exceeding 98 percent and incorporating maximum power point tracking algorithms. Its primary commercial purpose is enabling solar generation facilities to export electricity without battery storage. String inverters occupy the largest product category by megawatt volume, while microinverters command premium pricing in residential rooftop applications where module-level monitoring adds value. Smart inverter technology is displacing conventional centralized architectures as grid codes in multiple jurisdictions mandate reactive power support and ride-through capabilities.
IEC 61727 and IEEE 1547 establish grid-interconnection standards that determine which inverter architectures qualify for installation permits, while UL 1741-SA in the United States and CE marking under Europe's EMC Directive shape product certification requirements. Germany's KBA and France's national energy regulator enforce compliance testing that filters non-conforming equipment from tender participation. Stakeholders must monitor evolving grid codes that progressively require synthetic inertia and voltage-forming capabilities as inverter-penetrated networks displace synchronous generation.
Market Dynamics
Utility-scale solar deployment is compressing inverter procurement cycles as project developers consolidate vendor relationships around string inverter architectures capable of grid-forming functionality.
Growth Catalysts
- UL 1741-SA Certification:Grid-supportive inverter requirements in the United States are mandating reactive power capability and voltage ride-through, disqualifying legacy equipment from interconnection queues.
- China's Utility Pipeline:Domestic manufacturers supply the preponderance of global utility-scale installations through vertically integrated cell-to-inverter production.
- Smart Inverter Technology:Module-level power electronics with embedded monitoring and rapid shutdown functionality are capturing residential rooftop share from conventional string architectures.
Market Restraints
- Semiconductor Input Volatility:IGBT and silicon carbide module pricing fluctuates with foundry capacity allocation, compressing OEM margin structures during supply tightness.
- Supply Concentration Risk:Power semiconductor fabrication concentrates in Taiwan and South Korea, creating single-source dependency for high-efficiency switching components.
- Grid Code Fragmentation:Jurisdiction-specific interconnection standards prevent product standardization, forcing redundant certification cycles for multi-market suppliers.
Strategic Opportunities
- India's Solar Parks:National targets for renewable capacity are attracting domestic inverter assembly investments under production-linked incentive schemes.
- Agrivoltaic Applications:Dual-use solar installations over agricultural land require elevated DC voltage handling and specialized environmental sealing.
- Vehicle-to-Grid Convergence:Bidirectional charging standards are creating shared inverter architectures between stationary solar and electric mobility infrastructure.
Industry Challenges
- Power Electronics Talent Scarcity:Design engineering for wide-bandgap semiconductor integration outpaces university program output in multiple manufacturing geographies.
- Certification Timeline Compression:Accelerated grid code revisions in Germany and France compress product validation windows before tender deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grid Tie Inverter Market |
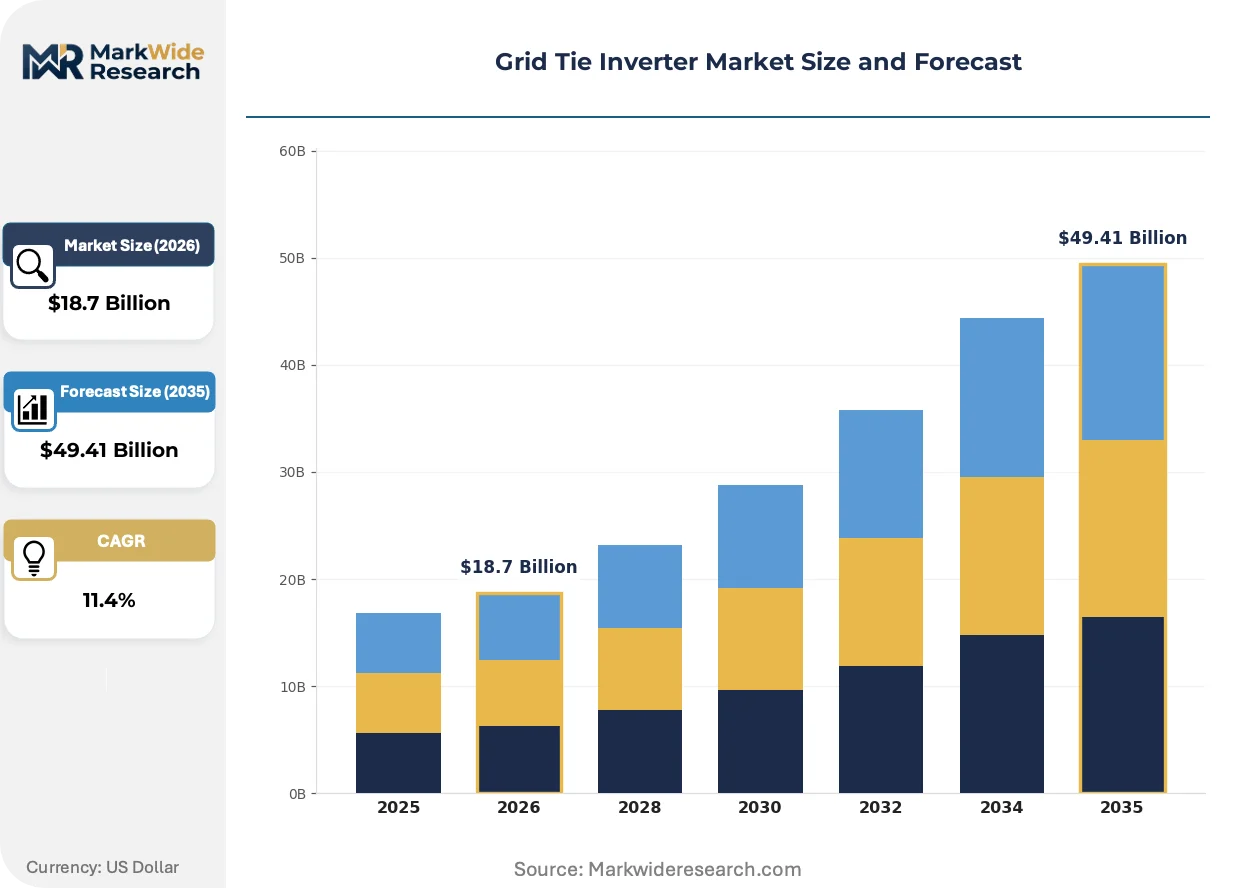
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Microinverters, String Inverters Technology: Centralized, Decentralized, Hybrid, Smart Installation: Residential, Commercial, Industrial, Utility End User: Homeowners, Businesses, Energy Providers, Installers |
| Companies Covered | Huawei Technologies, Sungrow Power Supply, SMA Solar Technology, Growatt, GoodWe, SolarEdge, Fronius, Delta Electronics, Ginlong Technologies (Solis), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grid Tie Inverter Market Evolving Landscape
Silicon carbide power semiconductors are restructuring inverter efficiency benchmarks while distributed energy resource management systems impose new communications requirements on hardware architectures.
Silicon carbide MOSFETs enable switching frequencies above 50 kHz with reduced thermal losses compared to silicon IGBTs. String inverter OEMs are adopting these devices for 1500-volt DC architectures in utility-scale projects. Higher frequency operation is rendering obsolete the bulky magnetic components that previously dominated inverter footprint and weight.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in liquid-cooled central inverters above 2.5 MW. Manufacturers are transitioning to dielectric fluid and air-cooled designs to maintain thermal management compliance. String inverter categories face lighter thermal loads and avoid this compliance burden entirely.
Asset owners are unbundling inverter maintenance from EPC contracts and negotiating direct service agreements with OEM diagnostic platforms. Remote monitoring subscriptions with predictive failure algorithms are displacing scheduled preventive maintenance in utility portfolios. This pattern is most pronounced in Germany where inverter fleet ages exceed ten years and warranty expirations concentrate.
Grid Tie Inverter Market Segmentation
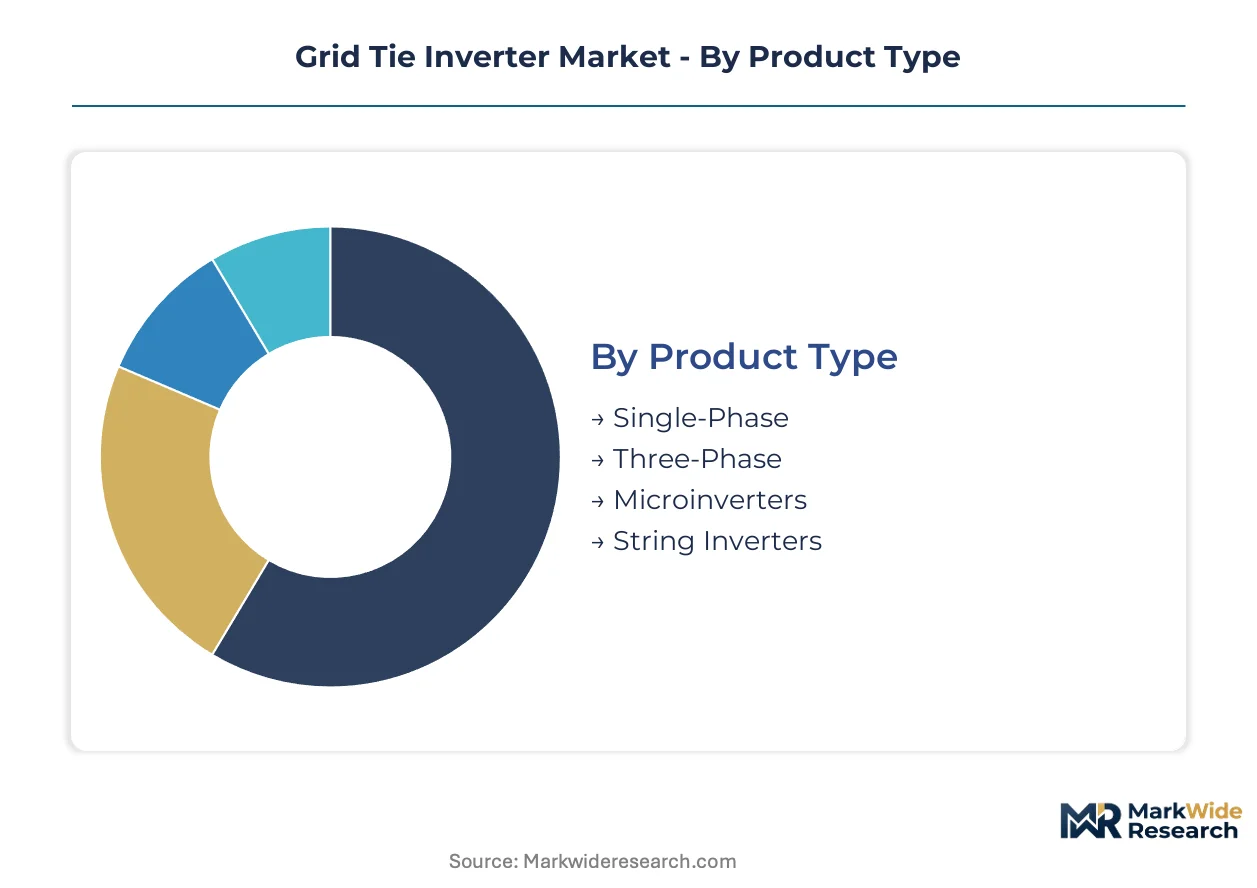
Segmentation in grid tie inverters determines procurement cycles, certification burdens, and margin structures across divergent application environments. Product architecture choices lock in thermal management requirements, voltage handling specifications, and grid-code compliance obligations that vary dramatically by installation scale.
Product Type:
String inverters turn over fastest in utility procurement cycles while microinverters sustain longest replacement intervals in residential rooftops.
- String Inverters:Modular DC-to-AC conversion units connect series-connected photovoltaic strings, typically handling 1500-volt DC inputs in utility configurations. Demand concentrates in China's utility-scale pipeline where domestic OEMs supply integrated cell-to-inverter systems through vertically integrated manufacturing. Procurement cycles compress as developers consolidate vendor relationships around grid-forming architectures.
- Microinverters:Module-level power electronics perform DC-to-AC conversion at individual panel level, enabling granular monitoring and rapid shutdown compliance. Residential rooftop deployments in Germany and the United States absorb premium pricing where module-level visibility and safety mandates justify per-watt cost premiums over string alternatives.
- Single-Phase:Compact units serve residential installations up to 10 kW, synchronizing output with split-phase or single-phase grid connections common in North American and Japanese distribution networks.
- Three-Phase:Industrial and commercial buildings deploy these units for balanced load distribution across utility phases, with power ratings scaling to several hundred kilowatts.
String inverters anchor the volume base while microinverters gain share at the steepest rate.
Technology:
Cost tiers separate legacy centralized architectures from premium smart inverter platforms commanding certification-driven price premiums.
- Smart Inverters:Grid-supportive platforms embed reactive power capability, voltage ride-through, and synthetic inertia functions mandated by IEEE 1547 and UL 1741-SA in the United States. Procurement in California and Texas prioritizes these units for interconnection queue qualification, with OEMs capturing margin premiums over conventional alternatives.
- Centralized:Large-format units exceeding 2.5 MW consolidate conversion for entire solar fields, requiring liquid cooling systems now constrained by Europe's F-Gas Regulation phasing hydrofluorocarbon refrigerants.
- Decentralized:Distributed string architectures reduce single-point failure risk and enable incremental capacity expansion without full plant shutdown.
- Hybrid:Bidirectional conversion platforms integrate battery storage dispatch, capturing demand from Germany's residential storage incentives and Australia's virtual power plant programs.
Smart inverters command the highest price tier while centralized units face regulatory headwinds in European markets.
Installation:
Volume concentration follows utility procurement scale, though margin profiles favor commercial and industrial mid-scale deployments.
- Utility:Gigawatt-scale solar parks drive procurement consolidation around 1500-volt string architectures, with China's domestic manufacturers supplying the majority of global installations through integrated production ecosystems.
- Commercial:Rooftop and carport installations from 100 kW to 2 MW absorb three-phase string inverters with embedded monitoring, particularly in India's solar park tenders under production-linked incentive schemes.
- Residential:Distributed rooftop systems below 20 kW deploy microinverters or single-phase string units, with rapid shutdown compliance driving module-level electronics adoption in the United States.
- Industrial:On-site generation for manufacturing facilities pairs three-phase inverters with behind-the-meter load management, common in Germany's industrial clusters seeking electricity cost hedging.
Utility installations anchor the volume base while commercial segments expand most quickly in emerging solar markets.
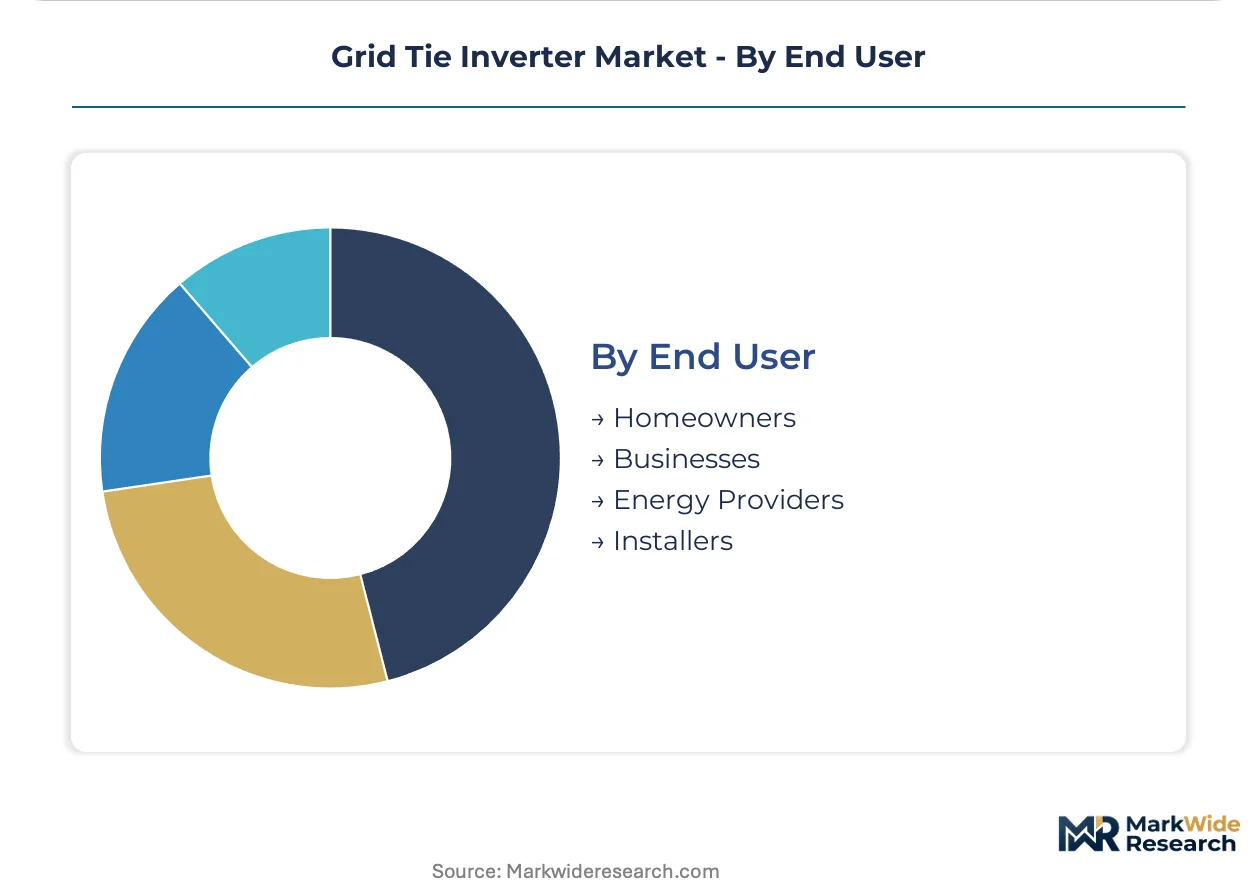
End User:
Customer type determines service bundling preferences and financing structures across divergent procurement capabilities.
- Energy Providers:Utility and independent power producers negotiate long-term service agreements unbundled from EPC contracts, with predictive maintenance subscriptions displacing scheduled interventions in German fleets exceeding ten years of operation.
- Installers:Channel partners prioritize inventory standardization and training support, consolidating around OEMs with simplified commissioning tools and remote diagnostic platforms.
- Homeowners:Residential purchasers emphasize warranty terms and monitoring app usability, with financing through solar loans or leases obscuring inverter selection in third-party ownership structures.
- Businesses:Commercial entities evaluate total cost of ownership including degradation curves and replacement reserves, with procurement teams increasingly direct-engaging OEM service platforms.
Energy providers anchor the volume base while installer channel consolidation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers control the preponderance of global utility-scale inverter supply through captive cell-to-inverter production ecosystems. Domestic demand concentration in China, Germany, and the United States shapes certification requirements and procurement patterns across three continents.
China
Utility-scale solar deployment absorbs the largest inverter procurement volumes globally through state-backed renewable capacity targets. The National Energy Administration coordinates grid-forming inverter mandates under GB/T standards for high-penetration renewable zones. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang provinces host vertically integrated production from wafer fabrication to final inverter assembly.
United States
Interconnection queue backlogs in California and Texas prioritize UL 1741-SA certified equipment with reactive power and voltage ride-through capabilities. FERC Order 2023 and state-level renewable portfolio standards reshape procurement specifications for utility-scale developers. Southwest solar corridors in Arizona and Nevada concentrate gigawatt-scale projects driving 1500-volt string inverter adoption.
Germany
Residential rooftop replacement cycles and agrivoltaic expansion sustain inverter demand amid Europe's most mature solar market. The Federal Network Agency enforces VDE-AR-N 4105 grid code compliance for distributed generation interconnection. Bavaria and Baden-Württemberg industrial clusters anchor inverter refurbishment networks serving aging fleet populations exceeding ten years of operation.
India
National solar park tenders under production-linked incentive schemes attract domestic inverter assembly investments. The Central Electricity Authority mandates CEA technical standards for grid connectivity and power quality compliance. Gujarat and Rajasthan state solar zones concentrate utility-scale deployment requiring three-phase string architectures.
Australia
Virtual power plant programs and residential storage incentives drive hybrid inverter adoption for behind-the-meter applications. The Australian Energy Market Commission regulates inverter standards through AS/NZS 4777 grid connection requirements. New South Wales and Queensland distributed solar penetration rates exceed 30 percent, forcing network operators to mandate advanced inverter functionality.
Grid Tie Inverter Market Competitive Landscape
Vertically integrated conglomerates and specialized power electronics firms split the market along capability and scale vectors. Three strategic archetypes dominate: Chinese state-linked manufacturers with captive semiconductor supply, European engineering specialists with long-cycle service platforms, and distributed power electronics innovators with module-level architectures. Competitive positioning hardens through backward integration into silicon carbide switching components and predictive maintenance service unbundling from equipment sales.
Within the integrated-manufacturer tier, Huawei Technologies and Sungrow Power Supply exemplify scale-driven positioning through domestic supply chain control. SMA Solar Technology anchors the European specialist archetype with extended warranty and remote diagnostics platforms serving aging installed bases. These three entities represent divergent strategic bets on vertical integration depth versus service revenue attachment.
| Leading Market Players |
|---|
| Huawei Technologies |
| Sungrow Power Supply |
| SMA Solar Technology |
| Growatt |
| GoodWe |
| SolarEdge |
| Fronius |
| Delta Electronics |
| Ginlong Technologies (Solis) |
| Others |
Value Network & Pricing Analysis
Foundry undercapacity in Taiwan and South Korea is compressing IGBT and silicon carbide module availability, forcing inverter OEMs to absorb input cost volatility while negotiating long-term offtake agreements that lock in pricing posture for utility-scale deployments.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture across inverter fleets, with predictive maintenance subscriptions and extended warranty tiers separating premium OEM offerings from economy alternatives. Price differentiation rests on certification grade—UL 1741-SA compliance commands substantial premiums over legacy equipment—and volume scale, with gigawatt-scale developers extracting procurement leverage. Pricing pressure stems from semiconductor input volatility, particularly silicon carbide MOSFET shortages. Utility-scale energy providers exhibit lowest price sensitivity, prioritizing grid-forming functionality and service bundling over per-watt cost.
Supply Chain Analysis
Power semiconductor fabrication concentrates at TSMC, Samsung Foundry, and GlobalFoundries, with Taiwan and South Korea anchoring high-efficiency switching component output. Raw material dependencies span silicon carbide wafers, copper busbars, and aluminum heat sinks. Single-source vulnerability in wide-bandgap semiconductor supply creates exposure to geopolitical disruption and foundry allocation decisions. Distribution runs through EPC contractor channels for utility projects and installer networks for residential deployments, with direct OEM engagement gaining share in commercial and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid tie inverter demand is accelerating under regulatory mandates for grid-supportive functionality, with IEEE 1547 and UL 1741-SA compliance requirements reshaping procurement specifications across multiple jurisdictions.
For Market Incumbents: Harden defensive positions by deepening captive semiconductor supply through foundry partnerships or in-house wafer processing, insulating margin structures from input volatility. Accelerate predictive maintenance platform deployment to capture unbundled service revenue from aging European fleets facing warranty expiration. Prioritize certification investment in emerging grid codes requiring synthetic inertia and voltage-forming capabilities.
For New Entrants and Emerging Players: Establish a beachhead in India's solar park ecosystem under production-linked incentive schemes, where domestic assembly requirements create procurement preference for local manufacturing footprints. Target agrivoltaic applications requiring elevated DC voltage handling and specialized environmental sealing, segments where incumbent coverage remains thin. Pursue channel partnerships with EPC contractors seeking second-source diversification beyond dominant Chinese suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon carbide power electronics integration, favoring scaled manufacturers with foundry access over capital-light assemblers. Long-term viability across the analysis window hinges on backward integration depth and service revenue attachment rates. Monitor foundry capacity allocation announcements as the primary inflection signal for margin compression or expansion cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Secures switching component supply for 1500-volt utility architectures ahead of allocation constraints. |
| Grid-Forming Certification Investment | Qualifies equipment for California and Texas interconnection queues under UL 1741-SA mandates. |
| Predictive Maintenance Platform Launch | Captures unbundled service revenue from German fleets exceeding ten years of operational age. |
| India Domestic Assembly Buildout | Accesses production-linked incentive schemes and satisfies local content requirements in national solar tenders. |
| Agrivoltaic Product Line Extension | Addresses dual-use solar installations requiring elevated DC voltage handling and environmental sealing compliance. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility planning officers, IPP project developers, EPC contractors, and inverter OEM product managers; and secondary validation through FERC interconnection filings, EIA generation statistics, IEA renewable deployment reports, and CEA technical standards documentation. Bottom-up triangulation across project development pipelines and top-down reconciliation against national renewable capacity targets ensured consistency.
Forecast inputs span product architecture evolution, grid code revision timelines, foundry capacity expansion, and regional procurement policy shifts across the projection horizon. Segmentation dimensions modeled include installation scale, technology tier, phase configuration, and end-user procurement capability. CAGRs were derived from fitted growth curves against historical deployment trajectories, with silicon carbide adoption rates and inverter replacement cycles as industry-specific modifiers.
Stress conditions across semiconductor supply availability, tariff regime changes, and grid code acceleration timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding foundry allocation, regulatory enforcement consistency, and technology substitution thresholds. Quarterly review of foundry utilization rates, interconnection queue backlogs, and inverter warranty expiration concentrations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Solid State Power Controller Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Global Chip Power Inductor Market
Power Systems
BCD Power IC Market
Power Systems
Bypass Thyristor Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
Buck-Boost Controller Market
Power Systems
Global Synchronous Motor Market
Power Systems
Electrical and Automation System Market
Power Systems
South America Battery Management System Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Global Inverter Market
Power Systems
South America DC Distribution Network Market