
 Europe Micro Inverter Market | 2026-2036
Europe Micro Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Micro Inverter Market Insights
Aftermarket service revenue is fragmenting across Europe as module-level monitoring subscriptions and extended warranty programs pull margin pools away from pure hardware sales. Enphase Energy leverages its installer certification network to capture recurring software revenue across France and the Netherlands. SMA Solar Technology AG anchors its position through backward integration into power semiconductor design, reducing dependency on Asian foundry capacity. Delta Electronics Inc competes on manufacturing scale, operating high-volume assembly lines that serve both European OEMs and its own branded micro inverter portfolio.
A micro inverter is a compact DC-to-AC power conversion device installed on individual solar panels, typically rated between 250 and 500 watts with peak efficiency exceeding 96.5% and integrated maximum power point tracking. Its primary purpose is to eliminate string-level mismatch losses, enable per-panel monitoring, and simplify rooftop designs with complex orientations or partial shading. Single-phase units dominate residential sales across Europe, though three-phase micro inverters are gaining share in small commercial installations where grid codes require balanced phase injection. Hybrid products that combine micro inversion with DC-coupled battery charging represent the fastest-growing margin pool, as installers in Italy and Spain bundle storage with new PV systems.
The EU Green Deal and REPowerEU framework mandate accelerated distributed renewable deployment, while CE marking and the F-Gas Regulation shape product efficiency and refrigerant standards for any integrated thermal management. Germany's Bundesnetzagentur enforces grid code requirements that favor module-level electronics in systems below 30 kW, effectively steering residential demand toward micro inverter architectures. Stakeholders must monitor how the EU AI Act and forthcoming cybersecurity standards for connected energy devices reshape firmware certification burdens and aftermarket service economics.
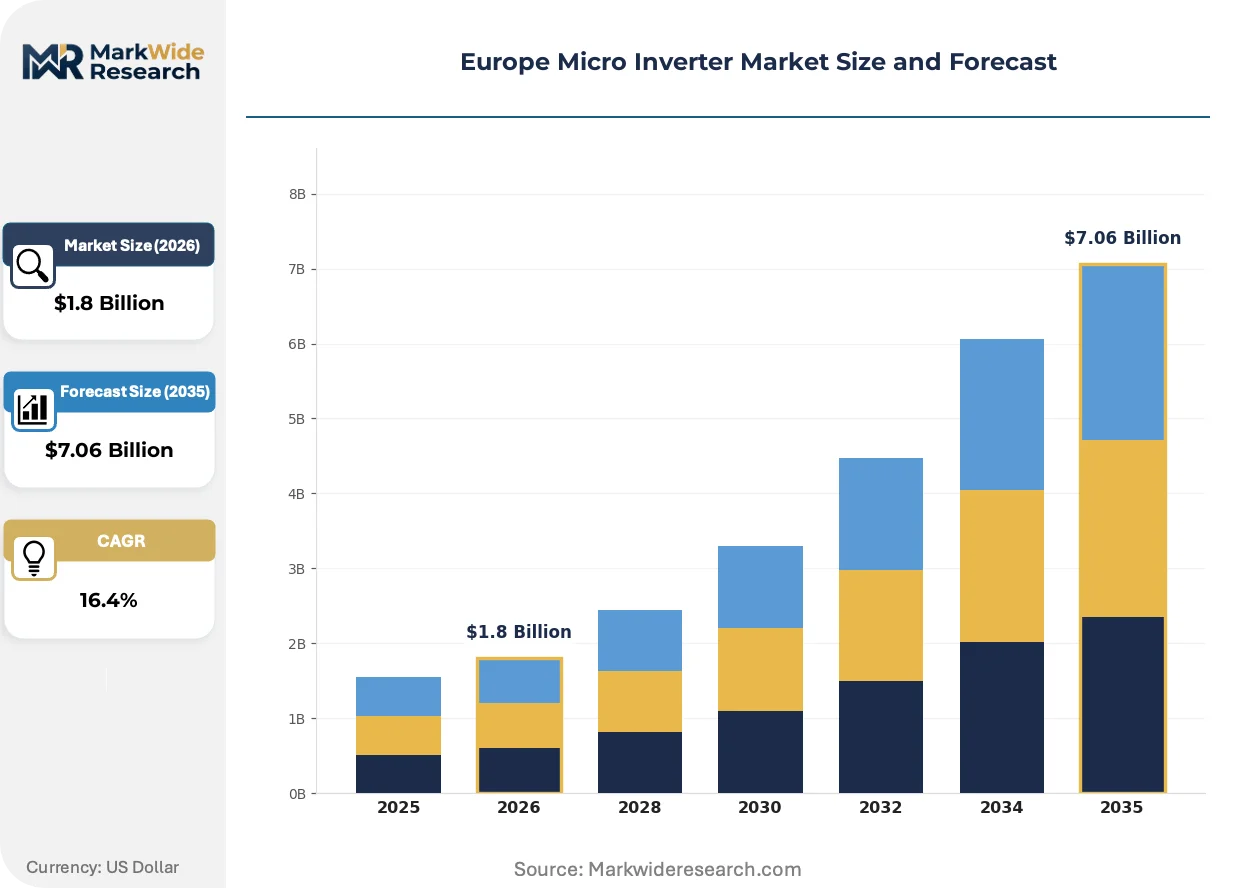
Market Dynamics
The EU Green Deal and REPowerEU framework are redirecting subsidy flows toward distributed solar generation, while module-level power electronics displace centralized string inverters in residential rooftops with complex geometries or partial shading conditions.
Growth Catalysts
- REPowerEU Acceleration:The framework mandates faster distributed renewable deployment across member states, with Germany's Bundesnetzagentur favoring module-level electronics below 30 kW through grid code requirements.
- Bavaria and Baden-Württemberg clusters:High electricity tariffs combined with favorable net metering rules in these German regions generate compelling payback periods for micro inverter installations.
- Hybrid storage bundling:DC-coupled battery charging integration creates margin expansion as installers in Italy and Spain package storage with new PV systems.
Market Restraints
- Power semiconductor supply concentration:Foundry capacity constraints in Asian manufacturing hubs create input bottlenecks for European assembly operations.
- F-Gas Regulation compliance costs:Integrated thermal management systems face refrigerant standard restrictions that add certification overhead and limit design flexibility.
- String inverter cost competition:Centralized alternatives maintain price advantages in unshaded, uniform rooftop configurations.
Strategic Opportunities
- France and Netherlands software subscriptions:Module-level monitoring services remain underpenetrated, creating recurring revenue potential beyond hardware margins.
- Three-phase commercial expansion:Small commercial installations requiring balanced phase injection represent an emerging application segment for micro inverter architectures.
- EU AI Act firmware certification:Early compliance with forthcoming cybersecurity standards for connected energy devices positions vendors for premium pricing.
Industry Challenges
- Installer certification scaling:Expanding qualified technician networks to match hardware deployment velocity strains training infrastructure across decentralized European markets.
- CE marking timeline compression:Evolving efficiency standards and grid code harmonization create certification backlog risks for product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Micro Inverter Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Hybrid, Optimizer End User: Residential, Commercial, Industrial, Utilities Technology: Grid-Tied, Off-Grid, Battery Storage, Remote Monitoring Installation Type: Roof-Mounted, Ground-Mounted, Building Integrated, Others |
| Companies Covered | Hoymiles Power Electronics, Delta Electronics Inc, SMA Solar Technology AG, ABB Ltd, SunPower Corp, Enphase Energy, APsystems, Darfon Electronics, SolarEdge Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Micro Inverter Market Trends and Innovations
Module-level power electronics are converging with digital energy management platforms, reshaping how residential solar systems interact with grid operators and home energy ecosystems.
Silicon carbide power semiconductors are replacing traditional silicon IGBTs in next-generation micro inverters, delivering higher switching frequencies and reduced thermal losses. Residential installers in Germany and Spain are specifying these units for premium retrofit projects. The technology is digitizing inverter control loops, enabling real-time grid interaction protocols that were previously impractical at module level.
The EU AI Act is imposing algorithmic transparency requirements on firmware that manages power conversion and grid injection. Equipment manufacturers must now document decision logic for automated shutdown and frequency-watt response functions. Micro inverter vendors serving the sub-30 kW residential segment face the steepest compliance burden, as their products lack the dedicated engineering resources of utility-scale inverter divisions.
Aftermarket service unbundling is separating hardware procurement from long-term monitoring contracts. Installers in the Netherlands and France are decoupling initial system sales from subscription-based performance analytics, creating dual revenue streams. This pattern is most visible in markets with mature rooftop solar penetration, where replacement cycles and system upgrades now rival new installations in volume.
Europe Micro Inverter Market Segmentation
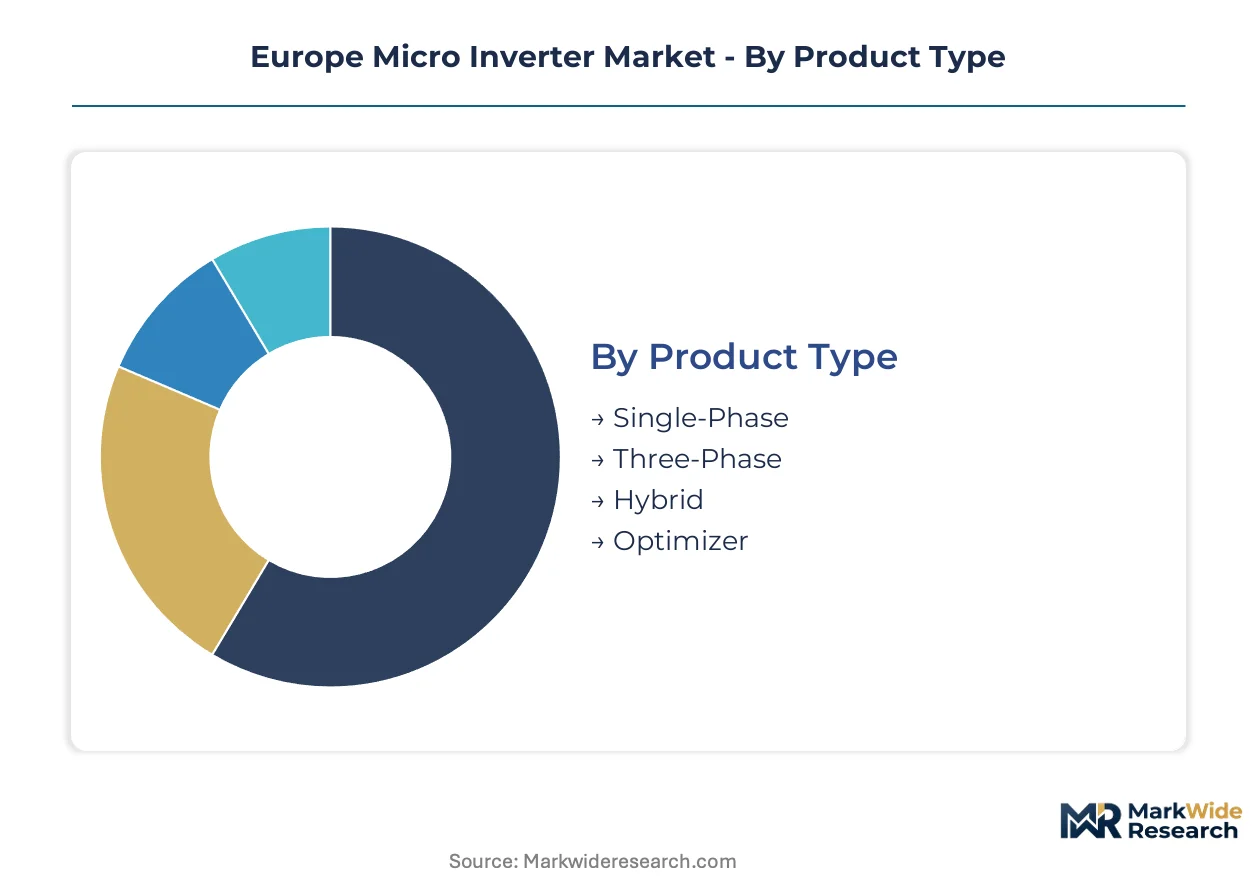
Module-level power electronics create distinct service intensity profiles across product architectures, with hybrid systems demanding ongoing firmware support while single-phase units concentrate replacement cycles in mature rooftop markets. Understanding these segmentation patterns clarifies where margin pools shift from hardware sales toward recurring software and warranty revenue.
Product Type:
After-sales service intensity varies sharply across product architectures, with hybrid and three-phase units requiring sustained technical support while single-phase systems dominate replacement-driven aftermarket activity.
- Single-Phase:Compact 250-500 watt units with peak efficiency exceeding 96.5% and integrated maximum power point tracking. Demand concentrates in Germany's Bavaria and Baden-Württemberg regions where residential rooftops with irregular geometries favor distributed conversion over string architectures.
- Hybrid:Products combining micro inversion with DC-coupled battery charging functionality. Installers in Italy and Spain bundle these with new PV systems, creating the steepest expansion trajectory for margin pools as storage attachment rates climb.
- Three-Phase:Balanced phase injection units serving small commercial installations where grid codes require symmetrical power distribution.
- Optimizer:Module-level DC power electronics that condition output before central inverter conversion.
By volume, Single-Phase leads. By growth pace, Hybrid is ahead.
End User:
Customer type determines procurement complexity, with residential buyers prioritizing payback period certainty while commercial and utility segments emphasize grid code compliance and monitoring integration.
- Residential:Homeowners in high-tariff regions seeking module-level monitoring and simplified rooftop designs. Germany's sub-30 kW installations favor this segment due to Bundesnetzagentur grid code requirements.
- Commercial:Small business installations requiring balanced phase injection and real-time performance analytics. France and the Netherlands show rising software subscription attachment as installers unbundle monitoring from hardware sales.
- Industrial:Larger rooftop and carport deployments with standardized orientations where string inverter competition intensifies.
- Utilities:Distributed generation assets integrating with grid operator frequency-watt response protocols under EU AI Act algorithmic transparency requirements.
Residential commands absolute shipment volume. Commercial generates the highest service revenue per installed kilowatt.
Technology:
Technology architecture governs regulatory exposure, with grid-tied and remote monitoring systems facing the steepest firmware certification burdens under emerging cybersecurity standards.
- Grid-Tied:Systems synchronizing with utility frequency and voltage parameters. CE marking and evolving efficiency standards create certification timeline pressure across product refresh cycles.
- Battery Storage:DC-coupled architectures enabling time-shifted energy delivery. Spain and Italy lead attachment as net metering evolution favors self-consumption optimization.
- Off-Grid:Standalone systems with integrated energy management for remote or backup power applications.
- Remote Monitoring:Cloud-connected platforms delivering per-panel performance analytics. The Netherlands and France show mature subscription unbundling as replacement cycles rival new installations.
Grid-Tied anchors current deployment. Battery Storage integration is climbing fastest as hybrid product adoption accelerates.
Installation Type:
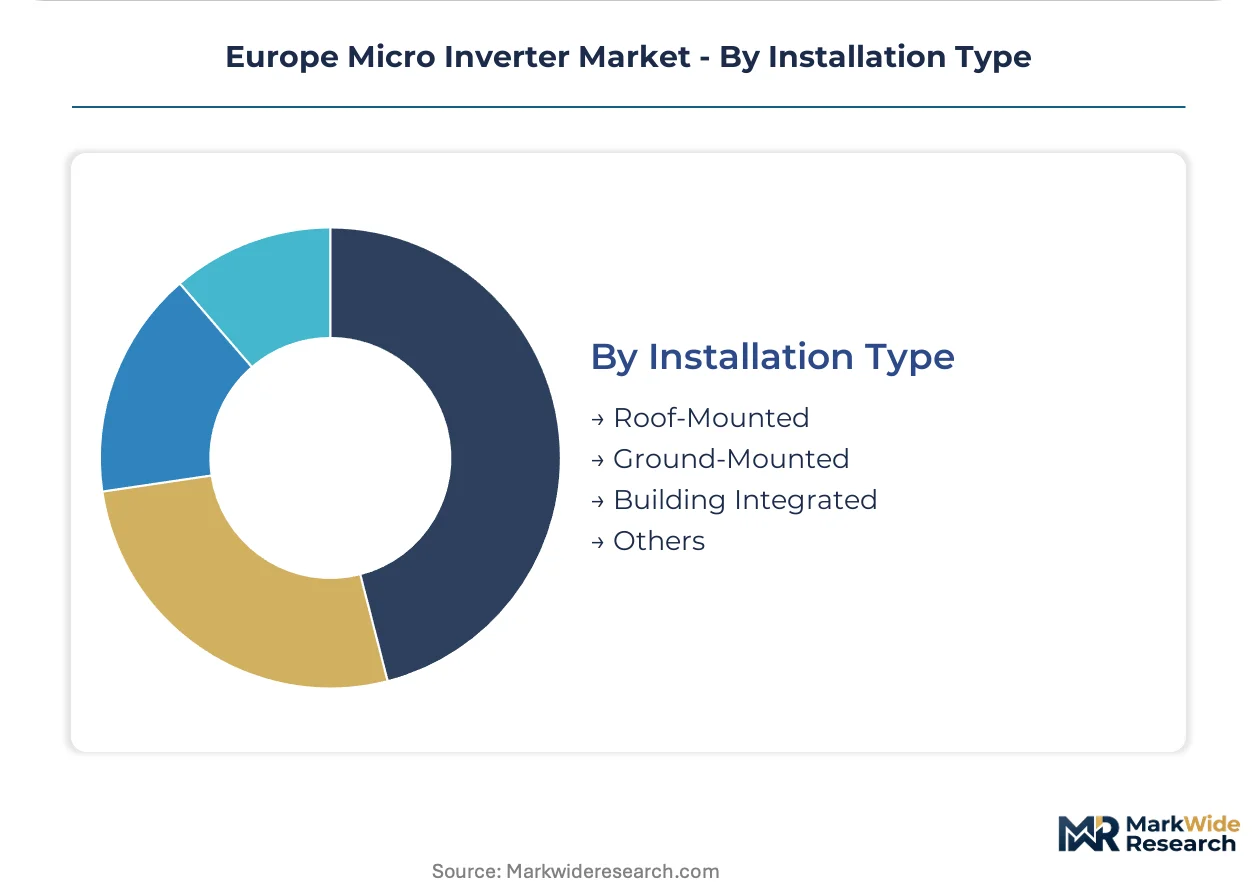
Mounting configuration shapes supply chain and labor economics, with roof-mounted systems dominating residential volume while building-integrated applications command premium positioning.
- Roof-Mounted:Retrofit and new-build residential installations across Germany, Spain, and Italy. Complex orientations and partial shading conditions favor micro inverter architectures over centralized alternatives.
- Building Integrated:Photovoltaic elements structurally incorporated into building envelopes. Premium positioning in architecturally sensitive European markets where aesthetic integration justifies higher system costs.
- Ground-Mounted:Free-field arrays with uniform tilt and orientation where string inverter cost competition limits micro inverter penetration.
- Others:Carport, facade, and specialized mounting configurations.
Roof-Mounted delivers the largest addressable volume. Building Integrated captures the highest margin per watt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly operations concentrate in Germany and the Netherlands, with component sourcing stretching across Asian foundries. Module-level power electronics demand clusters in high-tariff jurisdictions where rooftop solar economics favor distributed conversion architectures.
Germany
Homeowners in Bavaria and Baden-Württemberg drive residential deployment, drawn by elevated electricity tariffs and streamlined net metering frameworks. The Bundesnetzagentur mandates module-level electronics for sub-30 kW installations through grid code requirements. Munich and Stuttgart anchor installer certification networks that propagate technical standards across Central Europe.
Netherlands
Aftermarket service unbundling accelerates as Dutch installers separate hardware sales from subscription monitoring contracts. CE marking compliance timelines compress amid evolving efficiency standards. The Randstad corridor hosts distribution hubs serving Benelux retrofit markets where replacement cycles now rival new installations.
Italy
Hybrid micro inverter attachment climbs as installers bundle DC-coupled battery charging with new PV systems. The EU Green Deal redirects subsidy flows toward distributed generation and self-consumption optimization. Lombardy and Veneto industrial zones concentrate assembly partnerships between European brands and Asian component suppliers.
Spain
Net metering evolution favors module-level electronics that maximize yield from irregular rooftop geometries common in Mediterranean architecture. The REPowerEU framework accelerates permitting for residential solar across autonomous communities. Madrid and Barcelona anchor training infrastructure for installer certification programs.
France
Software subscription penetration lags hardware deployment, creating recurring revenue opportunities for monitoring platform vendors. The EU AI Act imposes firmware certification burdens on connected energy devices. Île-de-France and Auvergne-Rhône-Alpes concentrate commercial installations requiring balanced phase injection capabilities.
Europe Micro Inverter Market Competitive Landscape
Silicon carbide specialists and manufacturing-scale operators split the market between premium efficiency positioning and cost-driven volume capture. The vendor base organizes around three archetypes: vertically integrated power semiconductor designers, high-volume Asian assemblers, and software-centric platform vendors. Consolidation pressure intensifies as module-level monitoring subscriptions pull margin pools from pure hardware sales. Dominant competitive moves include backward integration into semiconductor design and geographic expansion of installer certification networks.
Within the integrated-design tier, SMA Solar Technology AG anchors German engineering positioning through captive power semiconductor capabilities. Delta Electronics Inc exemplifies scale-driven Asian manufacturing, operating high-volume assembly lines that serve both European OEMs and branded portfolio positions. Enphase Energy occupies the software-platform vector, leveraging installer certification networks to capture recurring monitoring revenue across France and the Netherlands.
| Leading Market Players |
|---|
| Hoymiles Power Electronics |
| Delta Electronics Inc |
| SMA Solar Technology AG |
| ABB Ltd |
| SunPower Corp |
| Enphase Energy |
| APsystems |
| Darfon Electronics |
| SolarEdge Technologies |
| Others |
Pricing and Supply Chain Analysis
Asian foundry undercapacity in power semiconductor fabrication is compressing margins for European micro inverter assemblers while simultaneously hardening pricing postures for silicon carbide wafers. This utilization squeeze forces vendors to absorb input cost volatility or pass through to installers, with CE marking and F-Gas Regulation compliance layers adding fixed certification overhead that stratifies pricing tiers by technical sophistication.
Pricing Analysis
CE marking dictates the pricing tier structure across European micro inverter deployment, separating premium silicon carbide units with integrated battery charging from standard silicon IGBT architectures and economy-grade single-phase alternatives. Price differentiation rests on certification grade and after-sales service bundling, with hybrid products commanding substantial premiums in Italy and Spain where storage attachment accelerates. Cost compression in the economy tier is intensifying because Delta Electronics and other high-volume Asian assemblers leverage manufacturing scale advantages. Residential installers in Germany's Bavaria region exhibit the highest price sensitivity due to payback period calculations, while commercial buyers in France prioritize monitoring integration over unit economics.
Supply Chain Analysis
Tariff exposure between Taiwan and Germany dominates supply chain risk calculus for European micro inverter vendors dependent on TSMC and UMC foundry capacity. Geographic supply concentration centers on Taiwan for silicon carbide wafer fabrication, China for passive component assembly, and Vietnam for final system integration. Raw material dependencies include gallium nitride substrates, aluminum heat dissipation housings, and rare-earth magnetic materials for inductive components. Single-source vulnerability persists at the power semiconductor tier where European brands lack captive foundry alternatives. Distribution runs through installer certification networks that Enphase Energy and SMA Solar Technology have cultivated across the Netherlands and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Micro Inverter Market is recovering from foundry capacity constraints that constrained deployment velocity through the early projection period. Module-level electronics demand is cyclically tied to residential solar permitting velocity under REPowerEU acceleration mandates.
For Market Incumbents: Insulate margin pools by backward integration into power semiconductor design, following SMA Solar Technology's captive wafer strategy to reduce dependency on Asian foundry pricing volatility. Expand installer certification networks in France and the Netherlands to capture recurring software subscription revenue before monitoring services commoditize. Defend against string inverter cost competition by emphasizing grid code compliance advantages under Bundesnetzagentur sub-30 kW requirements.
For New Entrants and Emerging Players: Pursue white-space opportunities in three-phase commercial installations across France's Île-de-France region, where balanced phase injection requirements create technical barriers to incumbent dominance. Target software subscription penetration in the Netherlands, where aftermarket service unbundling lags hardware deployment maturity. Enter through hybrid storage bundling partnerships with Italian installers seeking DC-coupled battery integration capabilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-centric platform vendors with established monitoring subscription bases across mature rooftop markets. Long-term viability over the next decade favors vendors with demonstrated EU AI Act firmware compliance capabilities and silicon carbide technology roadmaps. Acquisition target archetypes include hybrid micro inverter specialists with Italian or Spanish installer channel control. Watch silicon carbide substrate cost curves as the inflection indicator for premium tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Technology Transition | Next-generation micro inverters achieve higher switching frequencies that satisfy Bundesnetzagentur grid code requirements. |
| Installer Certification Network Expansion | Enphase Energy's training infrastructure in France and the Netherlands captures recurring monitoring subscription revenue. |
| Hybrid Storage Integration | DC-coupled battery charging functionality addresses Italian and Spanish self-consumption optimization demand. |
| EU AI Act Firmware Compliance | Algorithmic transparency documentation positions vendors for premium pricing under emerging cybersecurity standards. |
| Backward Integration into Semiconductor Design | SMA Solar Technology's captive power semiconductor capabilities reduce foundry dependency and input cost volatility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with residential solar installers in Germany's Bavaria and Baden-Württemberg regions, commercial EPC contractors in France and the Netherlands, power semiconductor procurement leads at European inverter assemblers, and grid interconnection officers at Bundesnetzagentur. Secondary validation drew from CE marking databases, F-Gas Regulation compliance filings, EU Green Deal implementation progress reports, and REPowerEU subsidy disbursement records. Bottom-up shipment estimates by product architecture were triangulated against top-down capacity assessments from Asian foundry disclosures.
Calibration against historical deployment patterns anchored volume projections across the analysis window without assuming technology substitution rates. Segmentation dimensions modeled include product type, end user category, technology architecture, and installation configuration, with hybrid storage attachment rates and three-phase commercial penetration treated as scenario-dependent variables. CAGRs were derived from fitted growth curves incorporating regulatory mandate timelines and net metering evolution trajectories. Industry-specific forecast inputs include silicon carbide substrate cost curves and installer certification scaling velocities.
Sensitivities concentrate around foundry capacity allocation decisions in Taiwan, REPowerEU subsidy continuity beyond current framework periods, and EU AI Act implementation timelines for firmware certification. Forecasts reflect documented assumptions regarding technology adoption rates and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Power Discrete and Modules Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Battery Balancer Market
Power Systems
Telecom Battery Market
Power Systems
Solid State Power Controller Market
Power Systems
Low Voltage Drives Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Smart Power Strips Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Global Gan Power Device Market
Power Systems
E-Axle Inverter and Control Unit Systems Market