
 Middle East and Africa Low Voltage Drives Market | 2026-2036
Middle East and Africa Low Voltage Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Low Voltage Drives Market Analysis
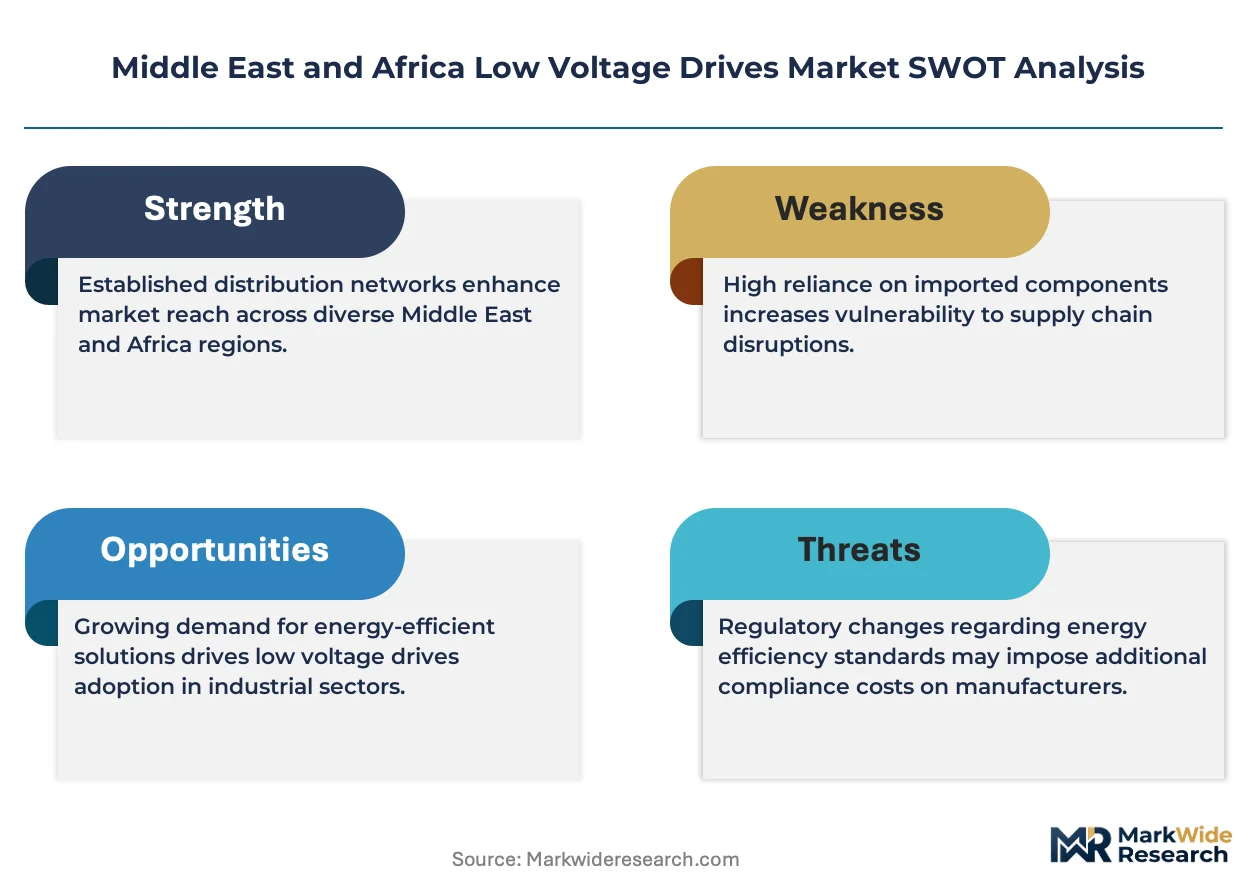
The EU Green Deal's extraterritorial carbon border adjustments are restructuring import competitiveness for energy-intensive goods manufactured in the Middle East and Africa, compelling regional industrial clusters to deploy precision motor control for Scope 2 emissions reductions. ABB leverages its Dubai-based regional headquarters to anchor aftermarket service contracts across Gulf petrochemical sites. Siemens competes through localized assembly partnerships in Egypt and Morocco that shorten lead times for variable frequency drive shipments.
Low voltage drives are power electronic devices that convert fixed-frequency, fixed-voltage AC input into variable-frequency, variable-voltage output to control AC motor speed and torque, typically operating below 690 volts and employing insulated-gate bipolar transistor switching with pulse width modulation carrier frequencies between 2-16 kHz. Their primary industrial purpose is to eliminate mechanical throttling in fluid handling systems and enable regenerative braking in material transport. Variable frequency drives occupy the dominant revenue position due to their universality across pumping and fan applications, while servo drives command premium positioning in precision manufacturing segments where vector control algorithms enable sub-rpm speed accuracy. Soft starters retain structural importance in mining conveyor deployments where direct online starting would cause mechanical shock and voltage sag.
Saudi Arabia's SFDA and the UAE's MOHAP enforce electrical safety certifications for industrial equipment deployed in pharmaceutical and food processing facilities, while Egypt's CEA mandates efficiency labeling for motors above 0.75 kW that indirectly governs drive pairing specifications. BIS-equivalent conformity assessment requirements in Gulf states are tightening electromagnetic compatibility testing protocols for imported drive systems. Stakeholders must monitor how Gulf standardization bodies harmonize efficiency tiers with EU Ecodesign regulations to avoid stranded inventory in cross-border trade corridors.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is forcing Middle Eastern and African industrial exporters to retrofit motor systems for Scope 2 emissions compliance, creating urgent demand for precision speed control in energy-intensive manufacturing clusters.
Growth Catalysts
- SABIC Efficiency Mandates:Saudi Arabia's petrochemical efficiency regulations compel fixed-speed motor retrofits across Jubail Industrial City complexes, accelerating variable frequency drive procurement.
- Water Scarcity Infrastructure:Gulf Cooperation Council desalination and wastewater utilities are deploying energy-efficient pumping systems with advanced motor control to reduce operational expenditure.
- Platinum Belt Electrification:South Africa's mining corridors around Johannesburg and Rustenburg are modernizing conveyor and ventilation systems with soft-start and variable-speed drives.
Market Restraints
- Copper and Rare Earth Volatility:Insulated-gate bipolar transistor modules and motor winding materials face price instability from concentrated Chinese rare earth processing and Chilean copper supply fluctuations.
- Import Dependency Concentration:Drive system assembly and semiconductor sourcing concentrates in East Asian manufacturing hubs, exposing Middle Eastern and African buyers to extended lead times and currency risk.
- Legacy Motor Park Inertia:Existing fixed-speed motor installations across North African textile and food processing plants lack compatible mounting configurations for retrofit variable frequency drives.
Strategic Opportunities
- Moroccan Automotive Integration:Renault-Nissan and Stellantis supplier parks in Tangier and Kenitra create demand for servo-grade precision drives in stamping and robotic assembly lines.
- Egyptian Renewable Pumping:New and Renewable Energy Authority incentives for solar-powered irrigation are pairing photovoltaic arrays with variable frequency drives in the Nile Delta agricultural belt.
- UAE Pharmaceutical Certification:MOHAP electrical safety mandates for cleanroom environments are creating specification pull for drives with embedded electromagnetic compatibility and sealed enclosures.
Industry Challenges
- Field Commissioning Expertise Gap:Vector control parameterization and harmonic mitigation tuning require specialized power electronics technicians scarce across Sub-Saharan African industrial zones.
- Multi-Standard Certification Burden:Harmonizing Gulf Cooperation Council electromagnetic compatibility testing with EU Ecodesign efficiency tiers forces manufacturers to maintain parallel product variants for cross-border trade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Low Voltage Drives Market |
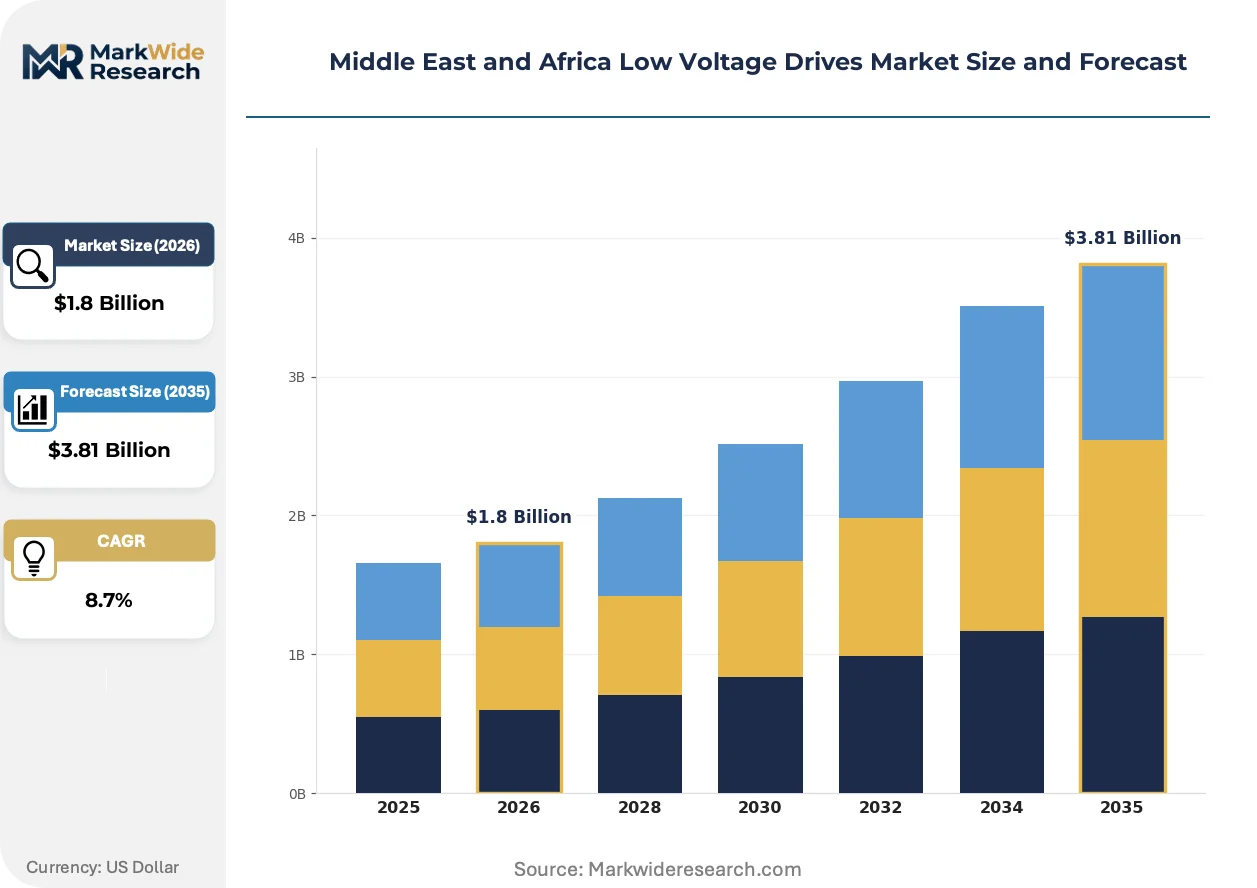
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Frequency Drives, Servo Drives, Soft Starters, DC Drives End User: Manufacturing, Oil & Gas, Water Treatment, Mining Technology: Scalar Control, Vector Control, Direct Torque Control, Pulse Width Modulation Application: Pumping Systems, Conveyor Systems, HVAC, Fans |
| Companies Covered | ABB, Siemens, Danfoss, Schneider Electric, Mitsubishi Electric Corporation, Fuji Electric, Rockwell Automation, Eaton, Yaskawa Electric Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Low Voltage Drives Market Emerging Trajectories
Predictive maintenance integration and edge computing capabilities are transforming drive systems from passive motor controllers into data-rich industrial assets, compressing service margins for traditional aftermarket providers.
Silicon carbide power semiconductors are rewriting thermal and switching performance benchmarks for low voltage drives. Petrochemical complexes in Jubail and Yanbu are piloting these modules for regenerative braking applications in material handling. The technology is compressing heat sink volumes and enabling cabinet-size reductions that challenge incumbent insulated-gate bipolar transistor product architectures.
Egypt's CEA efficiency labeling mandate for motors above 0.75 kW is tightening drive pairing specifications across Cairo and Alexandria industrial zones. Manufacturers must now certify integrated motor-drive systems rather than standalone components. Food processing and packaging machinery builders are responding with pre-engineered matched sets that simplify procurement compliance.
Service unbundling is fragmenting traditional vendor-captive maintenance relationships. Mining operators in South Africa's platinum group metals corridors are sourcing third-party drive refurbishment and spare inverter module replacement through independent automation distributors. This pattern is most visible in the Rustenburg and Limpopo mining belts where equipment uptime premiums outweigh brand loyalty considerations.
Middle East and Africa Low Voltage Drives Market Segmentation
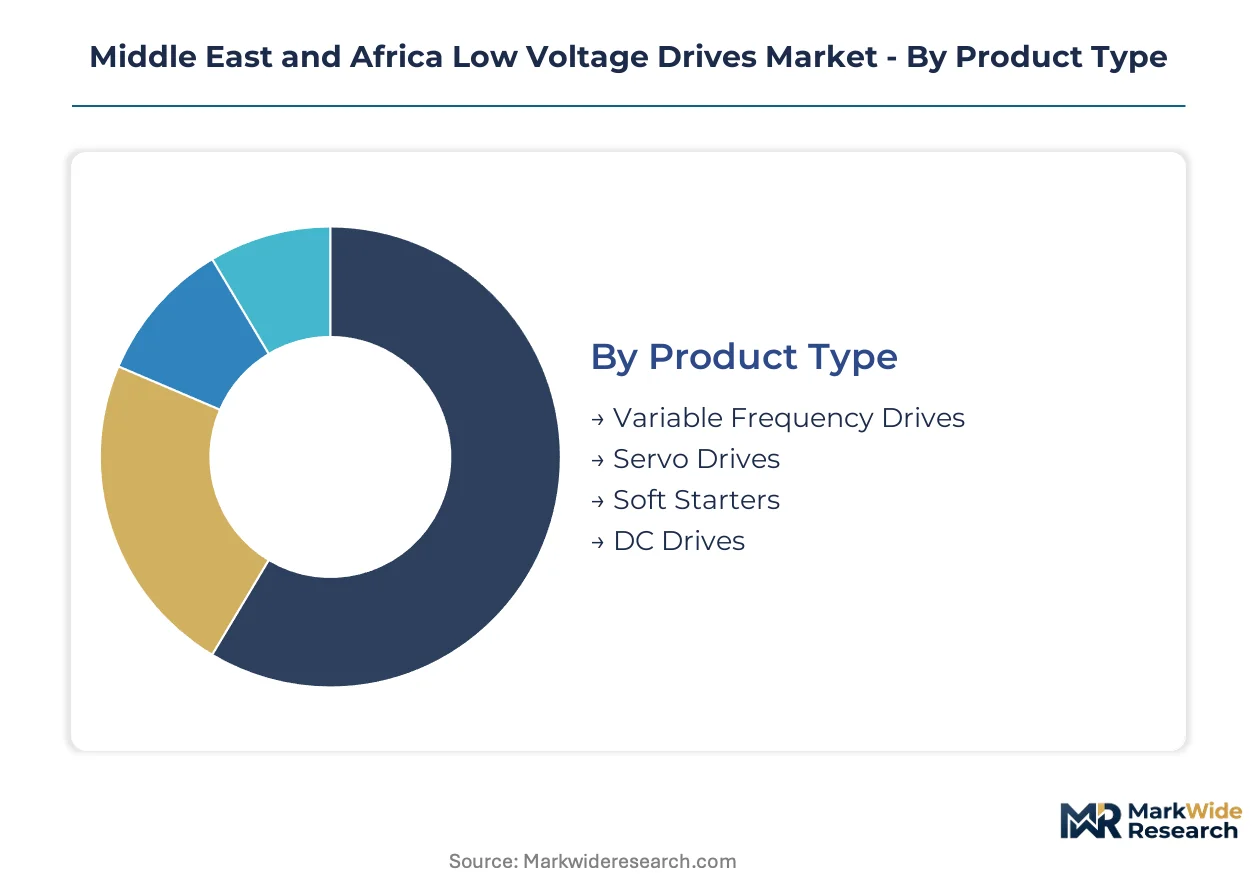
Retrofit cycles and efficiency mandates across Middle Eastern and African industrial corridors are reshaping segment demand patterns. Procurement specifications now prioritize interoperability with aging motor parks and compatibility with emerging silicon carbide architectures.
Product Type:
Replacement timelines for legacy fixed-speed motor systems are compressing as Gulf petrochemical efficiency regulations harden compliance deadlines.
- Variable Frequency Drives:These systems convert fixed-frequency AC input into variable-frequency output through IGBT switching with 2-16 kHz PWM carrier frequencies. Demand concentrates across Jubail Industrial City pumping retrofits where SABIC mandates eliminate mechanical throttling. Procurement volumes track water scarcity infrastructure buildouts across GCC desalination utilities.
- Servo Drives:Vector control algorithms enable sub-rpm speed accuracy for precision positioning applications. Moroccan automotive supplier parks in Tangier and Kenitra are specifying these for robotic stamping and assembly lines serving Renault-Nissan and Stellantis production networks.
- Soft Starters:Limit starting current and mechanical shock in heavy-inertia loads. Rustenburg platinum belt mining operators deploy these on conveyor systems where direct online starting would trigger voltage sag.
- DC Drives:Retain niche relevance in legacy mining hoists and older materials handling infrastructure across South Africa's Limpopo corridor.
Variable Frequency Drives sits at the top of the volume ranking, with Servo Drives climbing the fastest.
End User:
Cost tier differentiation separates premium-specification deployments in regulated process industries from price-sensitive bulk procurement in mature extraction sectors.
- Manufacturing:Food processing and packaging machinery in Egypt's Cairo-Alexandria corridor require CEA-certified motor-drive matched sets above 0.75 kW. SFDA and MOHAP electrical safety mandates in pharmaceutical cleanrooms pull sealed-enclosure specifications.
- Oil & Gas:Petrochemical complexes across Yanbu and Jubail retrofit fixed-speed motors under Saudi efficiency regulations. Silicon carbide module pilots for regenerative braking are compressing heat sink volumes in material handling applications.
- Water Treatment:GCC desalination and wastewater utilities prioritize energy-efficient pumping systems. Operational expenditure reduction drives dominate procurement criteria over capital cost minimization.
- Mining:Platinum group metals corridors around Johannesburg modernize ventilation and conveyor systems. Third-party refurbishment and spare inverter sourcing through independent distributors is fragmenting traditional vendor-captive relationships.
Water Treatment captures the steepest expansion trajectory as scarcity pressures accelerate utility capital deployment.
Technology:
Application complexity determines control algorithm selection, with precision manufacturing demanding closed-loop vector architectures unavailable in simpler scalar implementations.
- Scalar Control:Open-loop V/Hz regulation suits pump and fan applications without demanding torque response. Nile Delta solar-powered irrigation arrays pair photovoltaic generation with these economical control schemes.
- Vector Control:Field-oriented architectures enable independent torque and flux control for servo-grade positioning. Moroccan automotive lines and UAE pharmaceutical cleanrooms specify these for sub-rpm accuracy requirements.
- Direct Torque Control:Fast torque response without modulator delays benefits mining conveyor dynamics. South African platinum belt operators value the reduced parameterization burden against classical vector alternatives.
- Pulse Width Modulation:Carrier frequency selection between 2-16 kHz balances acoustic noise against switching losses. Gulf state electromagnetic compatibility harmonization with EU Ecodesign is tightening specification windows.
Vector Control dominates premium positioning, while Direct Torque Control gains share fastest in heavy-industry retrofit applications.
Application:
Geographic clustering aligns application demand with regional industrial specialization — mining corridors, petrochemical zones, and agricultural belts each concentrate distinct motor control requirements.
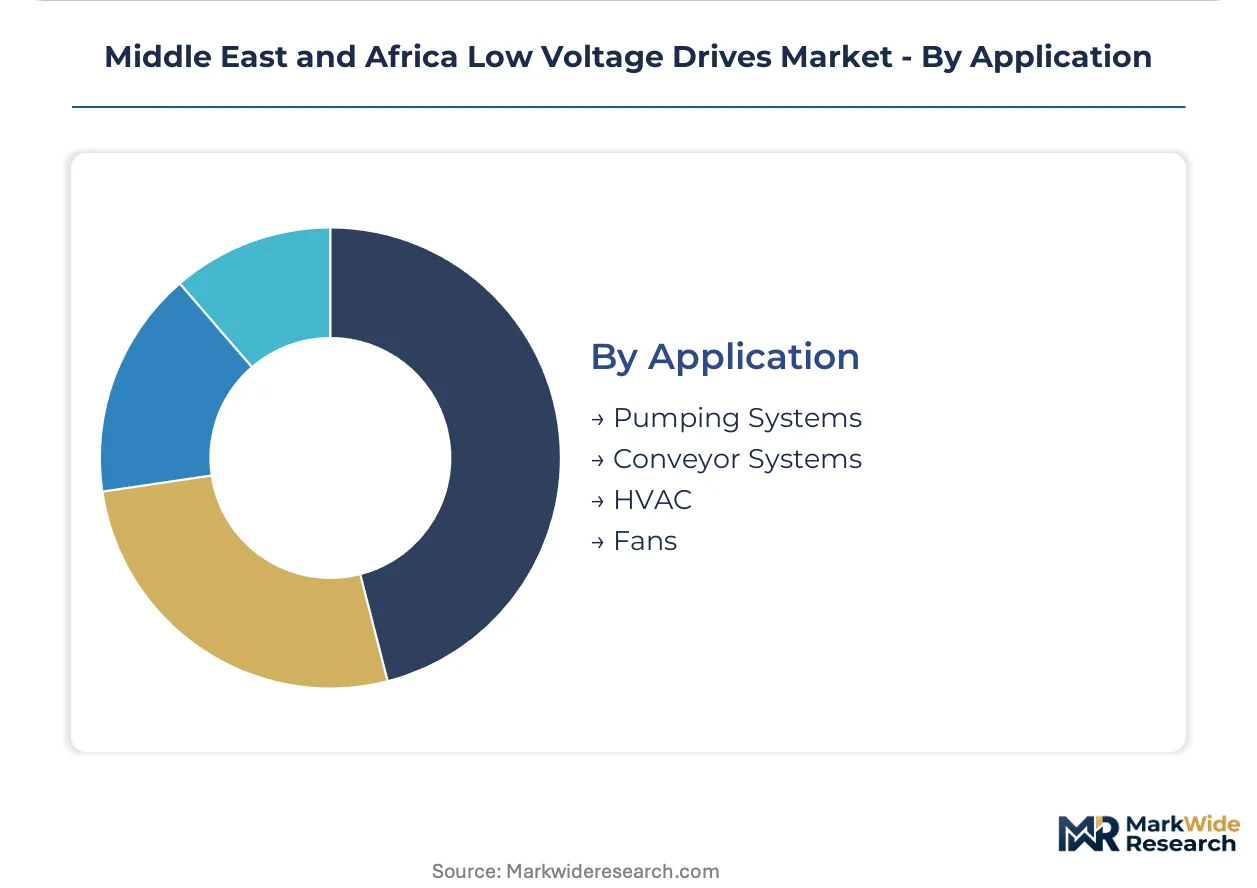
- Pumping Systems:Desalination intake, wastewater lift stations, and solar irrigation across GCC and Nile Delta territories. Energy efficiency metrics dominate procurement scoring against first-cost considerations.
- Conveyor Systems:Soft-start and variable-speed configurations in Rustenburg and Limpopo mining belts. Equipment uptime premiums override brand loyalty in aftermarket sourcing decisions.
- HVAC:Commercial and institutional building automation across Gulf urban centers. MOHAP cleanroom mandates pull specialized sealed-enclosure drives for pharmaceutical manufacturing environments.
- Fans:Mining ventilation and process cooling in petrochemical complexes. Retrofit compatibility with existing motor mounting configurations constrains specification flexibility.
Pumping Systems leads absolute volume, with Conveyor Systems expanding most quickly on mining modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized power electronics technicians cluster around Jubail Industrial City and Dubai's Jebel Ali corridor, anchoring field commissioning capacity for complex vector control deployments across Gulf petrochemical and desalination infrastructure.
Saudi Arabia
SABIC efficiency mandates are compelling fixed-speed motor retrofits across Jubail and Yanbu petrochemical complexes. The Saudi Food and Drug Authority enforces electrical safety certifications for pharmaceutical cleanroom equipment. Variable frequency drive procurement concentrates in Eastern Province industrial zones where energy-intensive process plants face carbon border adjustment exposure.
United Arab Emirates
Water scarcity pressures are accelerating desalination and wastewater utility capital deployment across Dubai and Abu Dhabi. The Ministry of Health and Prevention mandates electromagnetic compatibility standards for pharmaceutical manufacturing environments. MOHAP-certified sealed-enclosure drives are specified for cleanroom HVAC and pumping systems in Jebel Ali pharmaceutical clusters.
South Africa
Platinum group metals mining corridors around Johannesburg and Rustenburg are modernizing conveyor and ventilation systems. The country's national mining regulator oversees equipment safety standards for underground electrification. Third-party drive refurbishment through independent distributors is fragmenting traditional vendor-captive relationships in the Limpopo and North West Province belts.
Egypt
Solar-powered irrigation expansion in the Nile Delta agricultural belt is pairing photovoltaic arrays with variable frequency drives. The Central Energy Administration mandates efficiency labeling for motors above 0.75 kW that governs drive pairing specifications. Cairo-Alexandria industrial zones are certifying integrated motor-drive matched sets for food processing and packaging machinery compliance.
Morocco
Automotive supplier parks in Tangier and Kenitra serving Renault-Nissan and Stellantis networks are specifying servo-grade precision drives. The country's national industrial development agency oversees foreign investment incentives for component localization. Robotic stamping and assembly lines in northern Morocco are pulling vector control architectures for sub-rpm positioning accuracy.
Middle East and Africa Low Voltage Drives Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the Middle East and Africa low voltage drives market. European and Japanese industrial conglomerates with captive semiconductor fabrication anchor premium-tier positioning through localized assembly partnerships. The vendor base separates into three archetypes: integrated automation conglomerates with regional headquarters, specialized drive manufacturers with sector-specific expertise, and emerging Asian suppliers competing on cost. Dominant competitive moves include strategic partnerships to shorten lead times and portfolio diversification into silicon carbide architectures.
Within the integrated automation tier, ABB leverages its Dubai-based regional headquarters to anchor aftermarket service contracts across Gulf petrochemical sites. Siemens competes through localized assembly partnerships in Egypt and Morocco that compress shipment lead times for variable frequency drives. Schneider Electric occupies a position bridging European engineering standards with Gulf state certification requirements.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Danfoss |
| Schneider Electric |
| Mitsubishi Electric Corporation |
| Fuji Electric |
| Rockwell Automation |
| Eaton |
| Yaskawa Electric Corporation |
| Others |
Supply Flow & Price Mechanics
IGBT module costs cascade from East Asian semiconductor fabrication through three distinct pricing tiers for Gulf petrochemical buyers, with silicon carbide premiums compressing standard-product margins across Egyptian and Moroccan assembly partnerships.
Pricing Analysis
Bundled aftermarket service contracts versus unbundled equipment-only procurement splits the Middle East and Africa low voltage drives market into divergent value capture models. Three-tier pricing structure across premium, standard, and economy levels separates ABB and Siemens service-integrated offerings from Asian suppliers competing on first-cost. Pricing pressure stems from rare earth processing concentration in China and copper volatility from Chilean supply fluctuations. Mining operators in South Africa's platinum belt exhibit highest price sensitivity, prioritizing uptime premiums over brand loyalty, while UAE pharmaceutical cleanrooms accept sealed-enclosure premiums for MOHAP electromagnetic compatibility certification.
Supply Chain Analysis
Power electronics technician scarcity across Sub-Saharan African industrial zones constrains field commissioning capacity for complex vector control deployments. Semiconductor fabrication concentrates in China, Taiwan, and South Korea, with rare earth magnet processing anchored in Chinese refining complexes. Drive system assembly draws from Malaysian and Thai manufacturing hubs for Gulf state shipments. Single-source vulnerability in IGBT module supply exposes Middle Eastern and African buyers to extended lead times. Distribution runs through Dubai's Jebel Ali corridor for regional warehousing and Egyptian-Moroccan assembly partnerships for North African market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa low voltage drives market represents a late-cycle quality story as EU carbon border adjustments force Scope 2 compliance investments toward premium precision motor control specifications.
For Market Incumbents: Cement aftermarket service lock-in through predictive maintenance platform deployment across Jubail and Yanbu petrochemical sites. Deepen silicon carbide module partnerships to defend against emerging Asian suppliers competing on IGBT cost. Vector control parameterization expertise scarcity in Sub-Saharan Africa creates defensive moat for established service networks.
For New Entrants and Emerging Players: Enter via Nile Delta solar-powered irrigation arrays where Egyptian CEA motor-drive pairing mandates create specification pull for integrated matched sets. Target Moroccan automotive supplier parks in Tangier and Kenitra where Renault-Nissan and Stellantis networks demand servo-grade precision drives. Lead with localized assembly partnerships that compress shipment lead times against Dubai-based regional headquarters models.
For Investors and Strategic Acquirers: Consolidation pressure builds where service unbundling fragments traditional vendor-captive relationships in South African mining belts. Long-term viability favors vertically integrated players with captive semiconductor sourcing or backward integration into rare earth magnet supply. Acquisition target archetype: specialized drive manufacturers with sector-specific expertise in mining or water treatment applications. Monitor harmonization progress between Gulf Cooperation Council electromagnetic compatibility standards and EU Ecodesign efficiency tiers as inflection indicator for stranded inventory risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Transition | Petrochemical complexes in Jubail pilot regenerative braking applications with compressed heat sink volumes. |
| Localized Assembly Partnership | Egyptian and Moroccan facilities shorten lead times for variable frequency drive shipments to North African markets. |
| Predictive Maintenance Platform | Edge computing integration transforms drive systems into data-rich assets for aftermarket service contracts. |
| Integrated Motor-Drive Certification | CEA-mandated matched sets above 0.75 kW simplify procurement compliance for Cairo-Alexandria food processing. |
| Third-Party Refurbishment Channel | Independent distributors in Rustenburg and Limpopo mining belts fragment traditional vendor-captive relationships. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with maintenance directors at Gulf petrochemical complexes, plant engineers across South African mining corridors, OEM procurement teams in Moroccan automotive supplier parks, and aftermarket service heads in Egyptian industrial zones combined with secondary validation. Secondary sources included customs and trade data for IGBT module shipments, SEC filings from listed automation conglomerates, Gulf Cooperation Council standardization body publications, and national energy administration reports from Egypt and Saudi Arabia.
Historical trendline analysis established baseline penetration rates for variable frequency drives across pumping, conveyor, and HVAC applications. The projection framework models demand across product type, end-use industry, control technology, and application segments throughout the forecast period. CAGRs derive from regression analysis against industrial electricity pricing trajectories, efficiency mandate implementation timelines, and water scarcity infrastructure investment patterns. Industry-specific inputs include SABIC retrofit cycle data, GCC desalination capacity expansion plans, and platinum group metals mining modernization schedules.
Inputs from national statistical agencies and regional standardization bodies were available through the study window; gaps in Sub-Saharan African field commissioning capacity data introduce uncertainty bands around vector control deployment forecasts. Forecasts reflect documented assumptions regarding EU carbon border adjustment implementation scope and Gulf state regulatory harmonization progress. Practitioners should monitor rare earth export policy shifts from Chinese processing complexes and copper concentrate supply disruptions from Chilean mining operations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
EV Power Module Market
Power Systems
Thyristor Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
AC DC Power Adapter Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Space DC-DC Converters Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Voltage Stabilizer System Market