
 Global DC Power Supply Module Market | 2026-2036
Global DC Power Supply Module Market Size, Share, and Industry Trends Forecast 2026-2036
Global DC Power Supply Module Market Analysis
Multi-source procurement is expanding across the Global DC Power Supply Module Market as OEMs diversify away from single-vendor dependencies. Delta Electronics leverages captive semiconductor fabrication to secure component availability during supply tightness. TDK Corporation anchors its position through ferrite core and magnetic component vertical integration. Vicor Corporation specializes in high-density factorized power architectures for aerospace and defense applications.
A DC power supply module converts alternating current or unregulated DC input into precisely controlled direct current output, typically achieving efficiency thresholds above 90% in modern switch-mode designs through active power factor correction and synchronous rectification. These modules serve as foundational building blocks in telecommunications base stations, automated factory floors, and patient-connected medical equipment where voltage stability directly affects system reliability. Modular and encapsulated product types command premium positioning due to their conformal coating protection and field-replaceable architecture, while open frame variants dominate high-volume consumer electronics integration on cost grounds. Rack mounted installations lead in data center and telecommunications deployments, though embedded configurations are gaining traction in robotics and autonomous systems where space constraints override service accessibility.
The US Department of Energy enforces minimum efficiency standards through its external power supply program, directly shaping product design requirements for modules sold into North American consumer electronics and IT equipment. Ecodesign regulations under the EU Green Deal mandate standby power limits and active-mode efficiency tiers, compelling manufacturers to redesign legacy platforms for European market access. China's GB standards and MIIT directives govern electromagnetic compatibility and energy efficiency labeling for domestically manufactured and imported power modules. Stakeholders must monitor evolving efficiency tier thresholds and carbon-border adjustment mechanisms as these frameworks increasingly determine market eligibility rather than merely product differentiation.
Market Dynamics
Hyperscale data center operators are consolidating procurement volumes around high-efficiency rack-mounted modules, compressing vendor margins while accelerating the displacement of legacy open-frame designs across telecommunications and cloud infrastructure deployments.
Growth Catalysts
- EU Green Deal Ecodesign Tiers:Mandatory standby power limits and active-mode efficiency thresholds are forcing module redesigns that favor premium encapsulated architectures over legacy open-frame alternatives in European-bound shipments.
- Guangdong Manufacturing Clusters:Electronics assembly concentration in China's southern province creates localized ecosystem efficiencies that reduce lead times for telecommunications and medical equipment OEMs sourcing high-volume DC modules.
- Factorized Power Architecture:High-density modular designs enabling 48V direct conversion are displacing intermediate bus architectures in aerospace and defense applications where weight and thermal constraints dominate specification requirements.
Market Restraints
- Ferrite Core Supply Concentration:Magnetic component feedstock depends on rare earth processing concentrated in China's Jiangxi and Inner Mongolia regions, exposing module assemblers to input cost volatility and export quota uncertainties.
- GaN Semiconductor Cost Premium:Gallium nitride switching devices deliver efficiency gains but remain priced at multiples of silicon MOSFET equivalents, limiting penetration in cost-sensitive consumer electronics integration despite performance advantages.
- US DOE External Power Supply Standards:Minimum efficiency enforcement creates compliance friction for legacy platform manufacturers serving North American IT equipment channels, requiring costly redesign cycles for market access retention.
Strategic Opportunities
- India Electronics Manufacturing Incentives:PLI scheme subsidies and tariff structures are attracting module assembly capacity to Tamil Nadu and Karnataka, creating alternative supply origins for OEMs diversifying beyond China-centric procurement.
- Autonomous Robotics Embedded Integration:Space-constrained mobile platforms in warehouse automation and last-mile delivery are specifying embedded DC modules with conformal coating, opening volume channels distinct from rack-mounted data center dominance.
- China Dual Carbon Policy:National carbon neutrality mandates are accelerating domestic demand for 94%+ efficiency modules in state-backed telecommunications infrastructure tenders, privileging suppliers with advanced synchronous rectification capabilities.
Industry Challenges
- Magnetic Design Engineering Scarcity:Specialized expertise in planar magnetics and integrated magnetics for high-frequency switch-mode designs concentrates among a narrow cohort of senior engineers, constraining product development velocity at mid-tier suppliers.
- Medical IEC 60601-1 Certification Timelines:Patient-connected equipment safety standards require extended validation cycles for leakage current and isolation testing, delaying revenue recognition for modules targeting diagnostic and therapeutic device OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DC Power Supply Module Market |
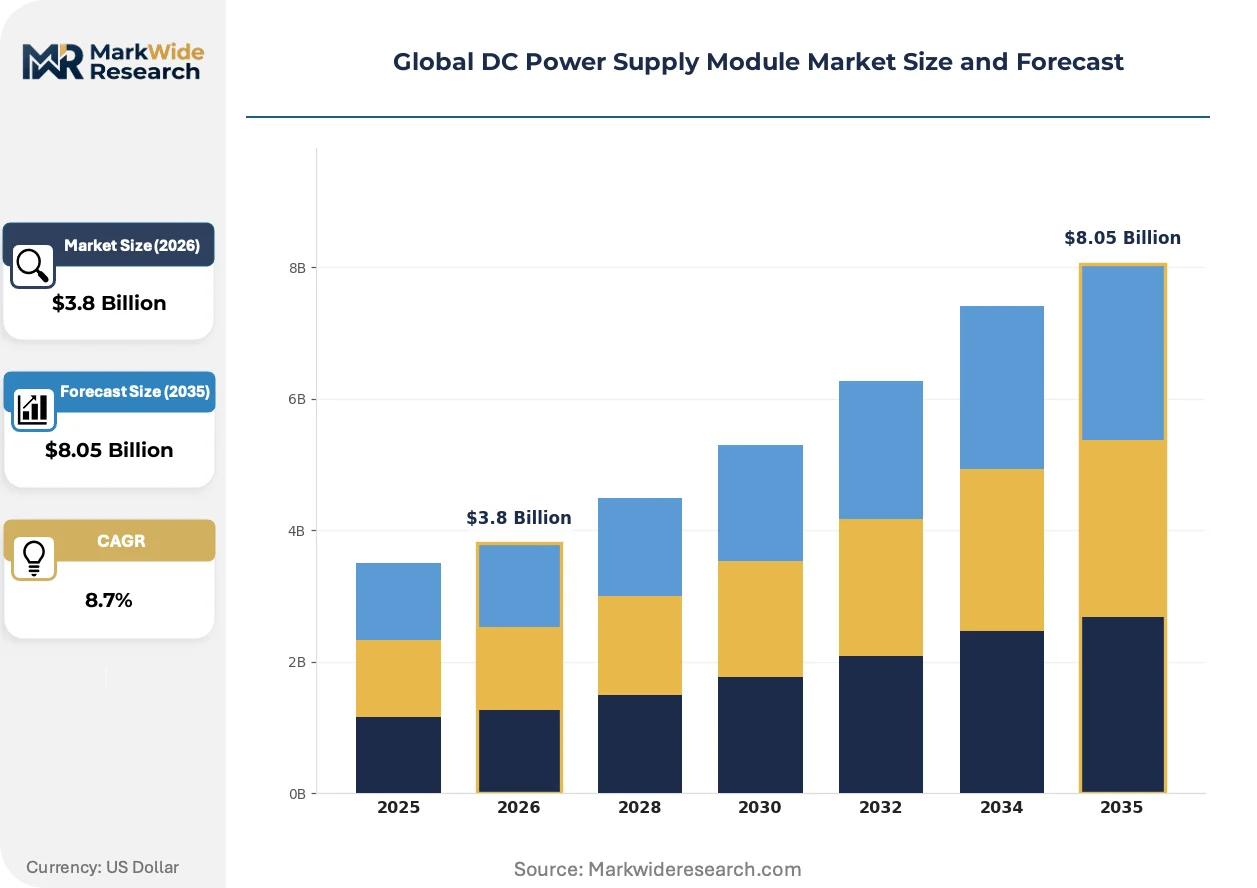
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Encapsulated, Modular, Desktop End User: Telecommunications, Industrial Automation, Medical Devices, Consumer Electronics Installation: Rack Mounted, Wall Mounted, Benchtop, Embedded Application: Testing Equipment, Power Distribution, Renewable Energy, Robotics |
| Companies Covered | Delta Electronics, TDK Corporation, Murata Manufacturing, MEAN WELL Enterprises, XP Power, Texas Instruments, Vicor Corporation, Infineon Technologies, Chroma ATE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DC Power Supply Module Market Emerging Trajectories
Power density compression and thermal management innovation are redefining competitive differentiation, with silicon carbide and gallium nitride wide-bandgap semiconductors enabling frequency increases that shrink magnetics volume while efficiency regulations harden across major demand centers.
Silicon carbide MOSFETs enable switching frequencies above 100kHz in server power supplies, cutting magnetic component mass by half compared to silicon superjunction alternatives. Hyperscale operators in Virginia and Frankfurt data center clusters are specifying these architectures for 48V rack-level distribution. The technology is electrifying competitive positioning around thermal design power per cubic inch rather than cost-per-watt alone.
EU F-Gas Regulation phase-down schedules are pressuring cooling-dependent power electronics toward higher-temperature operation capabilities. Module manufacturers serving European telecommunications and industrial automation channels are redesigning thermal interfaces and substrate materials to maintain reliability without refrigerant-based cooling. Medical equipment OEMs in Germany and the Netherlands face compressed qualification timelines as 2027 restriction thresholds approach.
Direct procurement relationships between hyperscale cloud operators and module suppliers are displacing traditional distribution channels for volumes above 50,000 units annually. Tier-one assemblers in China's Guangdong province now maintain dedicated account engineering teams for Amazon, Microsoft, and Google specifications. This concentration is most visible in Singapore and Dublin data center corridors where procurement centralization matches infrastructure investment intensity.
Global DC Power Supply Module Market Segmentation
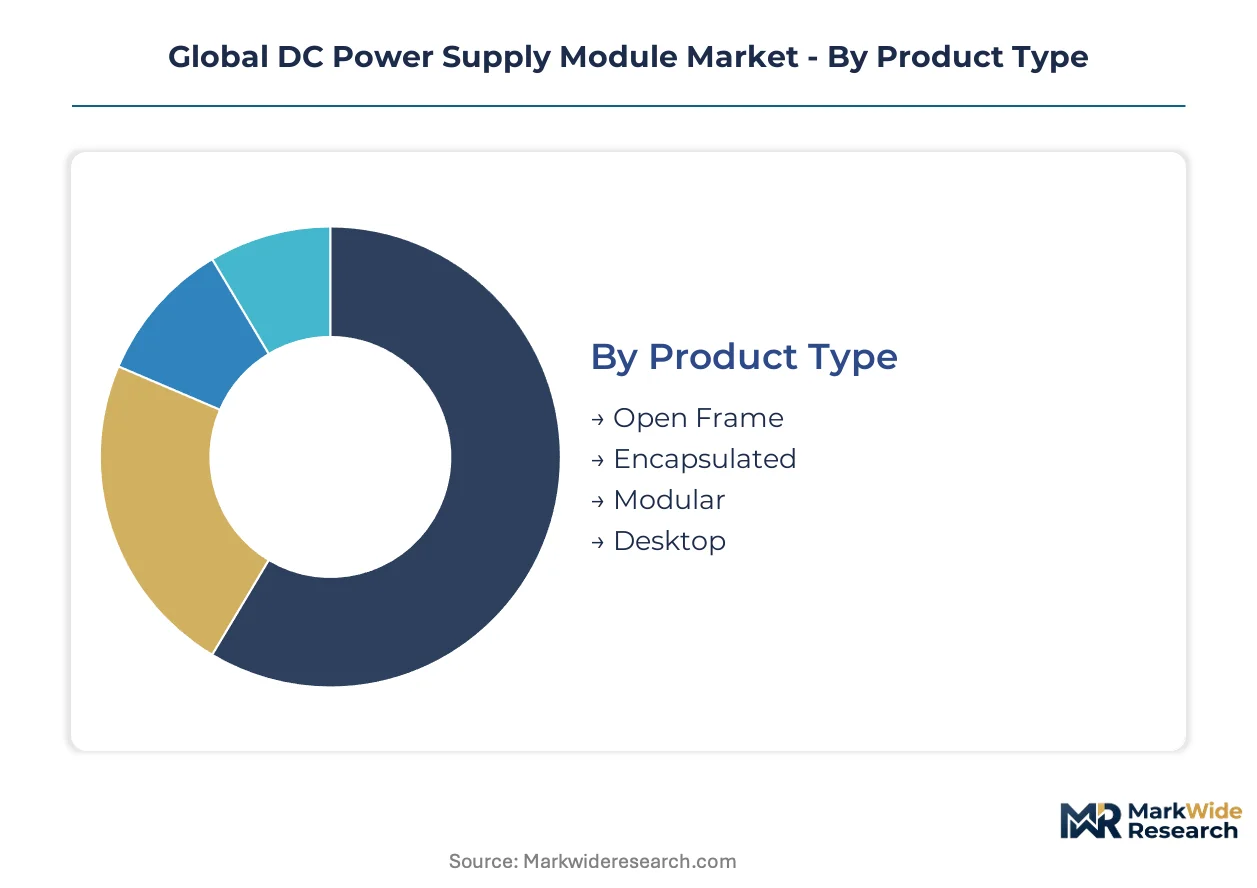
DC power supply module segmentation reflects divergent integration depths across end-use environments. Standalone rack-mounted systems serve centralized infrastructure, while embedded configurations penetrate mobile robotics and distributed automation nodes.
Product Type:
Integration depth varies sharply: open-frame modules dominate board-level embedding, while encapsulated and modular architectures serve field-serviceable standalone installations.
- Open Frame:Exposed PCB assemblies without enclosure housings achieve lowest unit cost through minimized material overhead. Consumer electronics OEMs in China's Guangdong province specify these for television and appliance internal power stages where external shielding is provided by host equipment chassis.
- Encapsulated:Potting compounds and conformal coatings seal components against moisture, dust, and thermal cycling. Medical device manufacturers in Germany and the Netherlands require these for patient-connected diagnostic equipment where IEC 60601-1 isolation standards demand environmental protection.
- Modular:Hot-swappable units with standardized form factors enable field replacement without system shutdown. Data center operators in Virginia and Singapore specify these for 48V rack-level power distribution where uptime requirements override capital cost sensitivity.
- Desktop:Self-contained external units with AC line cords serve laboratory and light industrial bench applications. Test equipment OEMs specify these for programmable DC sources in electronics manufacturing quality control.
Volume placements concentrate in open-frame modules for high-volume consumer integration; the faster expansion belongs to encapsulated architectures driven by medical and industrial reliability requirements.
End User:
Customer type determines specification rigor: telecommunications and medical verticals enforce stringent efficiency and safety certifications, while consumer electronics prioritizes cost minimization.
- Telecommunications:Base station power supplies and network infrastructure demand 94%+ efficiency under China's dual carbon policy mandates. State-backed tenders for 5G macro sites specify synchronous rectification and active power factor correction.
- Industrial Automation:Programmable logic controllers, motor drives, and sensor networks require wide input voltage tolerance and electromagnetic compatibility. Factory floor deployments in Germany and Japan specify these for robotic workcell power distribution.
- Medical Devices:Patient-connected diagnostic and therapeutic equipment mandates leakage current below 10 microamps and reinforced isolation per IEC 60601-1. Extended certification timelines in the EU and US constrain supplier qualification.
- Consumer Electronics:High-volume integration into televisions, gaming systems, and personal computing peripherals drives procurement scale. US DOE external power supply efficiency standards and EU Ecodesign tiers shape minimum performance thresholds.
Procurement scale concentrates in consumer electronics; the steepest expansion trajectory belongs to medical devices as diagnostic equipment electrification accelerates.
Installation:
Physical mounting configuration dictates thermal design and service accessibility tradeoffs, with rack-mounted systems optimized for maintainability and embedded units for spatial efficiency.
- Rack Mounted:19-inch standard chassis with front-panel accessibility serve data center and telecommunications central office environments. Hyperscale operators in Dublin and Singapore consolidate procurement around these for 48V distribution architectures.
- Wall Mounted:Bracket-attached enclosures for industrial and building automation applications where floor space is constrained. Security and access control system integrators specify these for distributed power distribution.
- Benchtop:Portable units with carrying handles and front-panel controls for laboratory and field service applications. Electronics manufacturing test engineers use these for diagnostic and calibration procedures.
- Embedded:Compact modules integrated directly into host equipment with no independent enclosure. Autonomous mobile robots and warehouse automation platforms specify these where volumetric constraints dominate.
Revenue concentration sits with rack-mounted installations; embedded configurations are gaining share fastest in robotics and autonomous systems.
Application:
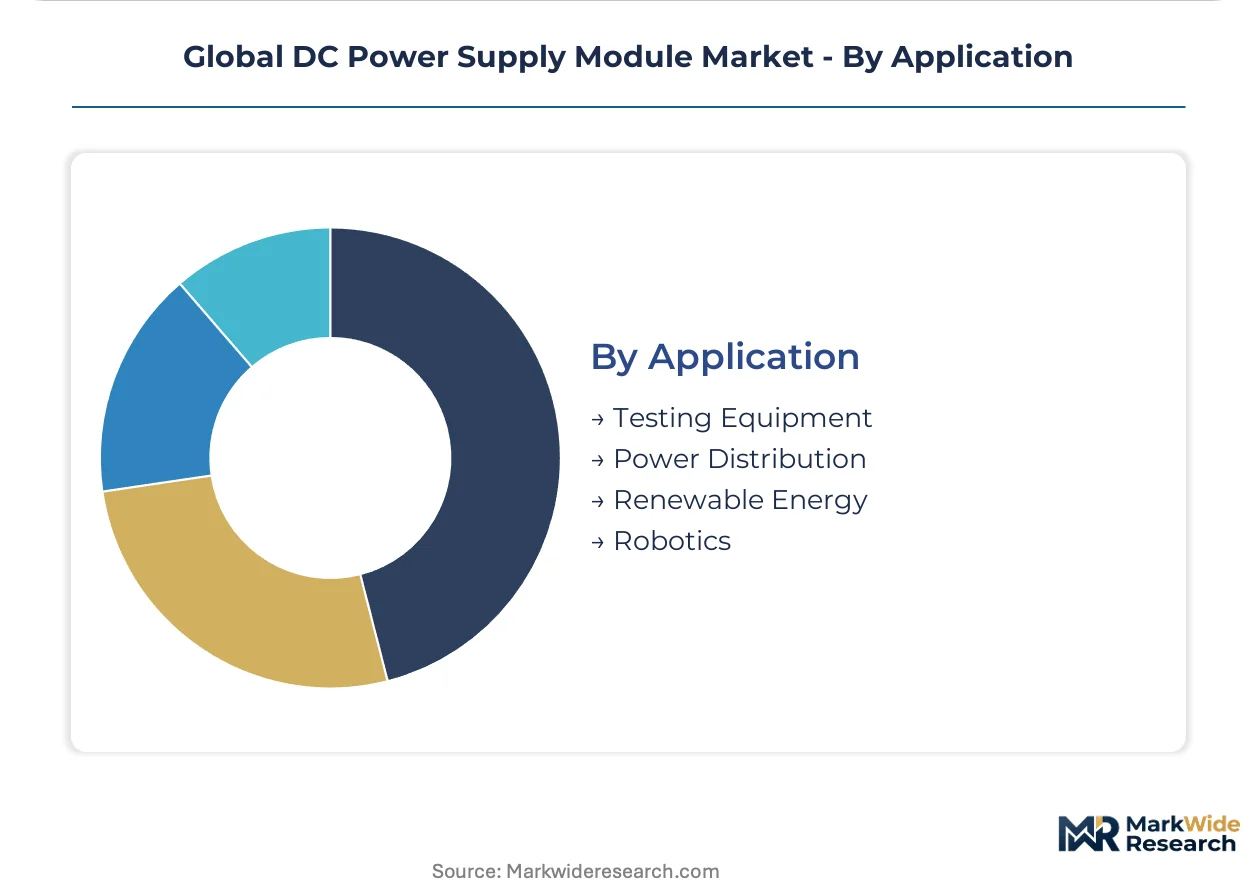
Use-case context determines electrical specification priorities: testing equipment demands precision and programmability, while renewable energy integration emphasizes wide input range tolerance.
- Testing Equipment:Programmable voltage and current sourcing with remote sensing and measurement feedback. Semiconductor device characterization laboratories specify these for wafer-level parametric testing.
- Power Distribution:Intermediate voltage conversion and load regulation in multi-stage power architectures. Data center busway and power shelf implementations in Frankfurt and Northern Virginia deploy these for 48V to 12V conversion.
- Renewable Energy:Maximum power point tracking and battery charge control for solar and energy storage integration. String inverter manufacturers specify wide-input-range modules for photovoltaic system DC coupling.
- Robotics:Compact, high-reliability power conversion for joint motors and control electronics in mobile platforms. Warehouse automation OEMs specify these for autonomous guided vehicles and articulated manipulators.
Deployment scale concentrates in power distribution applications; robotics is climbing the fastest as warehouse automation and last-mile delivery systems electrify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ferrite core processing concentrates in China's Jiangxi and Inner Mongolia regions, anchoring magnetic component feedstock for module assemblers worldwide. This raw-material locality shapes procurement patterns across major demand centers.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives rack-mounted module procurement at scale. DOE external power supply efficiency standards enforce minimum thresholds for consumer electronics and IT equipment channels. Module suppliers maintain dedicated account engineering teams for cloud operator specifications in these corridors.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg specify wide-input-range modules for robotic workcell power distribution. EU F-Gas Regulation phase-down schedules pressure cooling-dependent electronics toward higher-temperature operation capabilities. Medical equipment manufacturers in the Netherlands and Germany face compressed qualification timelines as restriction thresholds approach.
China
Dual carbon policy mandates accelerate domestic demand for 94%+ efficiency modules in state-backed telecommunications tenders. MIIT directives and GB standards govern electromagnetic compatibility and energy efficiency labeling for domestically manufactured units. Electronics assembly clusters in Guangdong province reduce lead times for telecommunications and medical equipment OEMs sourcing high-volume DC modules.
India
PLI scheme subsidies and tariff structures attract module assembly capacity to Tamil Nadu and Karnataka. The country's national electronics manufacturing incentives create alternative supply origins for OEMs diversifying procurement beyond China-centric sources. State-level industrial corridors in these southern states host emerging power electronics fabrication facilities.
Japan
Factory floor deployments in the Chubu and Kansai regions demand wide input voltage tolerance and electromagnetic compatibility for programmable logic controllers and motor drives. METI efficiency guidelines shape domestic procurement specifications for industrial automation power supplies. Precision manufacturing clusters in these industrial zones specify modules with reinforced isolation for diagnostic equipment integration.
Global DC Power Supply Module Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers respond to hyperscale procurement consolidation. The vendor base organizes around three tiers: integrated semiconductor-device suppliers, specialized magnetic component fabricators, and modular power system assemblers. Two strategic archetypes define competitive positioning: captive semiconductor fabrication for supply security, and ferrite core vertical integration for magnetic component control. Geographic expansion into India and Southeast Asia accompanies technology licensing agreements for wide-bandgap semiconductor integration.
Among Taiwan and Japan-based fabricators, Delta Electronics, TDK Corporation, and Murata Manufacturing exemplify distinct strategic postures. Delta Electronics occupies a position emphasizing captive semiconductor fabrication capabilities. TDK Corporation anchors the magnetic component integration archetype through in-house ferrite core production. Murata Manufacturing represents the high-frequency ceramic and passive component specialization tier. These three entities collectively illustrate the geographic and capability diversity structuring competitive dynamics in module supply.
| Leading Market Players |
|---|
| Delta Electronics |
| TDK Corporation |
| Murata Manufacturing |
| MEAN WELL Enterprises |
| XP Power |
| Texas Instruments |
| Vicor Corporation |
| Infineon Technologies |
| Chroma ATE |
| Others |
Supply Flow & Price Mechanics
EU Green Deal ecodesign tiers gate both qualified supply and premium-tier pricing access, as manufacturers redesigning for 94%+ efficiency standards capture margin premiums while legacy open-frame assemblers face exclusion from European-bound shipments. This regulatory filter concentrates pricing power among encapsulated and modular architecture suppliers who have absorbed compliance costs, compressing margins for cost-optimized competitors dependent on consumer electronics volumes.
Pricing Analysis
Warranty and field-service bundling separate rack-mounted modular systems from unbundled open-frame alternatives, with data center operators paying premiums for hot-swappable replacement guarantees. Three-tier pricing structure across premium encapsulated, standard modular, and economy open-frame levels reflects certification grade differentiation, with IEC 60601-1 medical compliance adding substantial cost overhead. Pricing pressure stems from hyperscale procurement consolidation around 50,000+ unit annual contracts, with Amazon and Microsoft specifications compressing vendor margins. Consumer electronics OEMs in Guangdong exhibit highest price sensitivity, while aerospace and defense contractors prioritize performance density over unit cost.
Supply Chain Analysis
Reverse-logistics flows for rack-mounted modular systems create aftermarket service revenue streams, with refurbishment programs extending product lifecycles in data center deployments. Ferrite core processing concentrates in China's Jiangxi and Inner Mongolia regions, while semiconductor device fabrication anchors in Taiwan and South Korea. Module assemblers draw from rare earth feedstock, silicon carbide substrates, and copper winding materials, exposing production to commodity price volatility. Single-source vulnerability in magnetic component supply creates structural risk, as export quota uncertainties from Chinese rare earth processors disrupt input availability. Distribution runs through direct procurement relationships for hyperscale volumes above 50,000 units annually, with traditional distribution channels serving sub-scale industrial and medical customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU Ecodesign tiers and US DOE external power supply standards erect barrier-to-entry moats favoring manufacturers with capital reserves for platform redesign cycles.
For Market Incumbents: Cement supply security through captive semiconductor fabrication or ferrite core backward integration, insulating against rare earth export volatility. Prioritize certification investment for IEC 60601-1 medical pathways and EU F-Gas Regulation thermal compliance, as these credentials lock out capital-constrained challengers. Defend against GaN semiconductor cost-premium erosion by accelerating synchronous rectification R&D for 94%+ efficiency benchmarks. For New Entrants and Emerging Players: Begin with India's PLI scheme subsidized assembly capacity in Tamil Nadu and Karnataka, exploiting tariff structures that disadvantage China-centric incumbents. Target embedded configurations for autonomous robotics and warehouse automation, where space constraints and conformal coating requirements favor specialized entrants over rack-mounted specialists. Pursue go-to-market partnerships with warehouse automation OEMs seeking alternatives to data center-dominated supplier portfolios. For Investors and Strategic Acquirers: Hyperscale direct procurement announcements exceeding 50,000 units annually is the leading indicator that vendor consolidation is accelerating and margin compression is nearing its floor. Frame long-term viability around five-to-ten year positioning for wide-bandgap semiconductor integration and carbon-border adjustment mechanism compliance. Acquisition targets should emphasize planar magnetics engineering capabilities and medical certification track records, as magnetic design expertise scarcity constrains product development velocity across the competitive landscape.| Strategic Initiative | Industry Significance |
|---|---|
| Wide-Bandgap Semiconductor Integration | GaN and SiC device adoption enables frequency increases that shrink magnetics volume for aerospace applications. |
| Medical Certification Pathway Investment | IEC 60601-1 validation accelerates revenue recognition for patient-connected diagnostic equipment modules. |
| India Manufacturing Footprint Expansion | PLI scheme subsidies in Tamil Nadu reduce tariff exposure for OEMs diversifying beyond Guangdong sourcing. |
| Magnetic Component Backward Integration | In-house ferrite core production insulates against Jiangxi rare earth export quota uncertainties. |
| Hyperscale Direct Procurement Partnership | Dedicated account engineering teams for Amazon and Microsoft specifications secure volume commitments above 50,000 units. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted among power electronics procurement managers at telecommunications OEMs, data center infrastructure planners, medical device regulatory affairs leads, and magnetic component engineering directors. SEC 10-K disclosures from listed power supply manufacturers, MIIT directive publications, EU Ecodesign implementing measures, and US DOE external power supply compliance databases provided validation benchmarks. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment disclosures from hyperscale operators.
Product type, end user vertical, installation configuration, and application use-case were modeled at segment-level granularity across the projection horizon, with efficiency tier thresholds and geographic regulatory clusters as cross-cutting dimensions. CAGRs derived from shipment volume trajectories indexed to named infrastructure investment corridors in Northern Virginia, Frankfurt, Singapore, and Dublin. Forecast inputs incorporated semiconductor device roadmaps from wide-bandgap foundries and rare earth export quota schedules from Chinese regulatory authorities.
Underlying measurement precision varies by segment; rack-mounted data center and telecommunications modules carry tighter precision than emerging embedded robotics applications given established procurement reporting channels. Forecasts reflect assumptions about hyperscale construction timelines, EU F-Gas Regulation phase-down adherence, and dual carbon policy enforcement intensity in Chinese state tenders. Practitioners should monitor hyperscale direct procurement contract announcements, ferrite core export quota adjustments, and GaN semiconductor cost curve trajectories for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
US Variable Frequency Drive Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Global Fault Current Limiter Market
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Global Gan Power Device Market
Power Systems
Global Inverter Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Bypass Thyristor Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
Global Rectifier Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Solid State Power Controller Market