
 Power Electronics for Electric Vehicle Market | 2026-2036
Power Electronics for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Power Electronics for Electric Vehicle Market Outlook
The gap between premium silicon carbide traction inverters and commodity silicon-based power modules is broadening as OEMs split procurement strategies by vehicle class. Infineon Technologies AG leverages its Fab capacity in Dresden to sustain supply commitments for 800-volt architectures. Robert Bosch GmbH anchors its position through in-house production of power semiconductors for hybrid and battery-electric platforms. Continental AG competes by extending its vertically integrated module assembly across European and North American plants.
Power electronics for electric vehicles comprises semiconductor-based systems that convert, regulate, and distribute electrical energy between battery packs and traction motors, typically operating at switching frequencies above 10 kHz and voltage classes spanning 400V to 800V. These systems govern torque response, regenerative braking capture, and onboard charging efficiency across passenger and commercial electrified platforms. Inverters command the largest value share within product type segmentation due to their central role in motor drive control, while silicon carbide technology is displacing conventional silicon insulated-gate bipolar transistors in premium platforms where thermal efficiency and power density carry premium pricing. OEM end users dominate volume offtake as they internalize powertrain electrification roadmaps, though Tier-1 Suppliers retain critical design influence through co-development contracts for platform-specific module integration.
The EPA enforces fleet-average emissions standards that effectively mandate power electronics efficiency gains for compliance, while the EU Green Deal and F-Gas Regulation constrain refrigerant and thermal management choices in European-designed systems. China's MIIT issues GB standards for new energy vehicle power consumption that directly shape inverter efficiency targets for domestic and export-bound manufacturers. Stakeholders must monitor substrate supply concentration, qualification timelines for next-generation wide-bandgap devices, and evolving interoperability standards for bidirectional charging infrastructure.
Market Dynamics
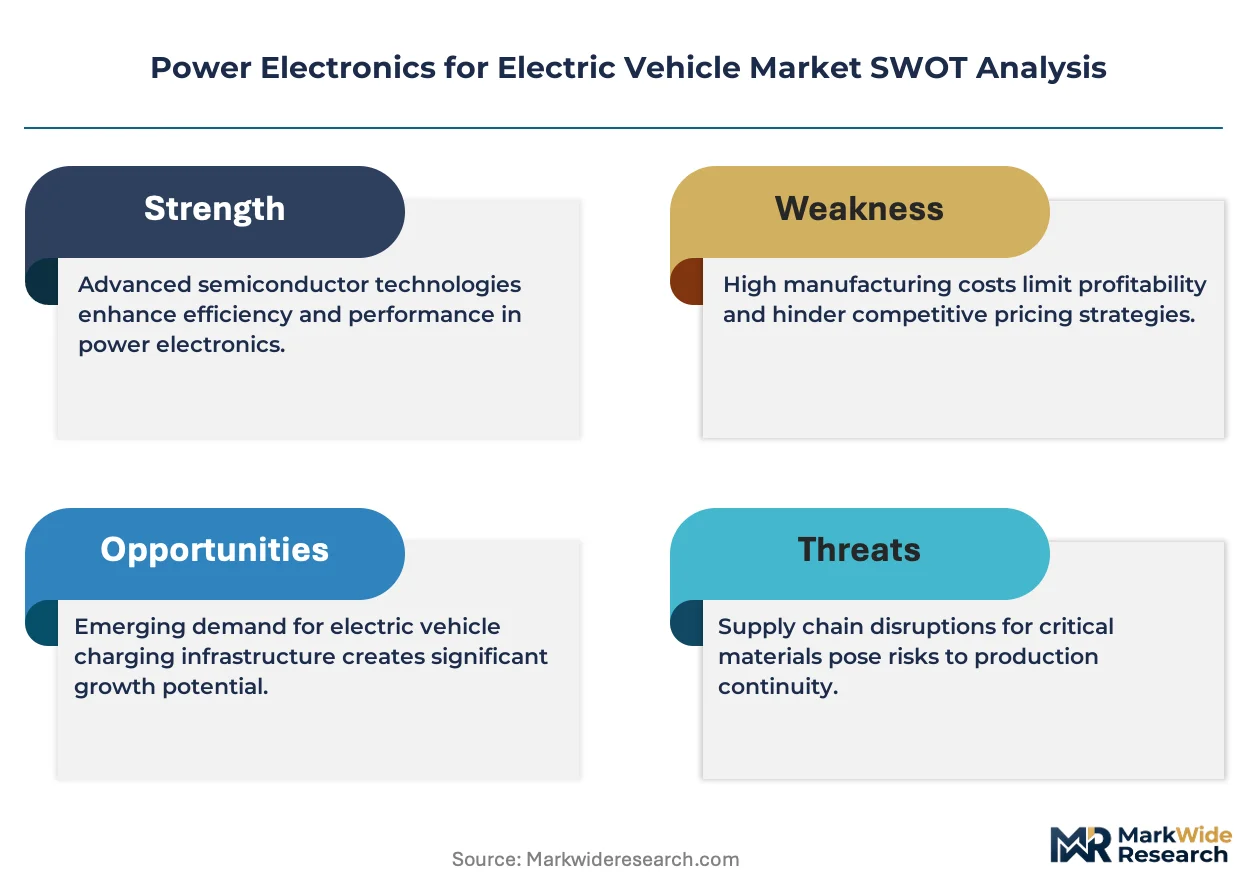
Silicon carbide substrate adoption is bifurcating procurement strategies across passenger and commercial vehicle platforms, forcing power semiconductor suppliers to qualify dual-source architectures while managing wafer supply concentration in East Asian foundries.
Growth Catalysts
- EPA Fleet Standards:The EPA's tightening tailpipe emissions mandates compel OEMs to deploy higher-efficiency inverter architectures, directly accelerating wide-bandgap semiconductor procurement for 800-volt traction systems.
- China MIIT GB Standards:China's Ministry of Industry and Information Technology issues mandatory new energy vehicle power consumption benchmarks that reshape inverter efficiency targets for domestic manufacturers and export-bound suppliers.
- Silicon Carbide Substrates:Wafer processing advances at 150mm and 200mm formats are compressing cost premiums against silicon IGBTs, unlocking adoption in mid-market battery-electric platforms previously restricted to premium segments.
Market Restraints
- Substrate Supply Concentration:Silicon carbide wafer production concentrates among a handful of East Asian and US substrate growers, creating qualification bottlenecks for second-source strategies.
- EU F-Gas Regulation:The EU's fluorinated gas restrictions constrain refrigerant choices in integrated thermal management systems, complicating inverter packaging for European-designed platforms.
- Silicon IGBT Commoditization:Mature silicon-based power modules retain cost advantages in economy vehicle classes, limiting pricing power for advanced wide-bandgap alternatives.
Strategic Opportunities
- Bidirectional Charging Infrastructure:Vehicle-to-grid interoperability standards are creating aftermarket retrofit demand for bidirectional-capable onboard chargers across residential and commercial energy storage applications.
- US IRA Manufacturing Credits:The Inflation Reduction Act's clean energy production incentives are attracting power semiconductor fab investments to Arizona and Texas, reshaping regional supply chain geography.
- Commercial Vehicle Electrification:Heavy-duty truck and bus platforms represent underpenetrated demand for integrated inverter-converter modules, with fleet operators specifying 10-year lifecycle durability requirements.
Industry Challenges
- Wide-Bandgap Talent Scarcity:Power electronics engineering expertise in silicon carbide device characterization and gate driver design remains concentrated among a limited pool of specialists, extending recruitment timelines for module development teams.
- Qualification Timeline Compression:Automotive AEC-Q101 certification cycles for new semiconductor packages now overlap with platform launch schedules, forcing parallel validation workflows that elevate failure-mode analysis costs.
- Legacy 400V System Integration:Established battery-electric architectures resist 800-volt migration due to connector standardization and service network retooling requirements, fragmenting module design roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Electronics for Electric Vehicle Market |
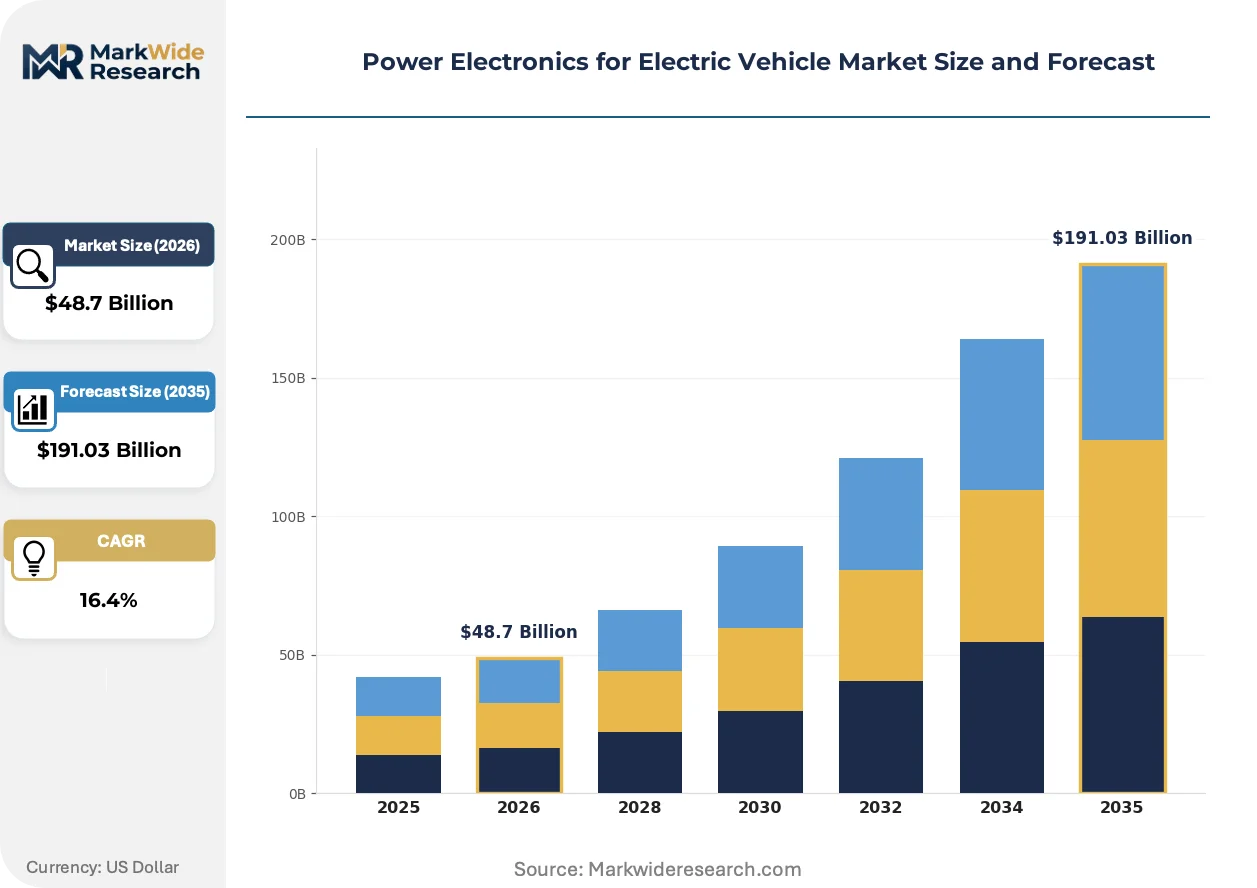
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverters, Converters, Power Regulators, Controllers End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: Silicon, SiC, GaN, Integrated Circuits Functionality: Energy Management, Thermal Management, Drive Control, Charging |
| Companies Covered | Continental AG, Hitachi Astemo, Infineon Technologies AG, Valeo, Delphi Technologies, Denso Corporation, Mitsubishi Electric Corporation, Panasonic Corporation, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Electronics for Electric Vehicle Market Strategic Shifts
Power electronics architecture is consolidating around integrated multi-function modules that merge traction inverters, DC-DC converters, and onboard chargers into single thermal management domains, compressing packaging volume and assembly cost structures simultaneously.
Silicon carbide MOSFET technology is converging with advanced sintered silver die-attach processes to enable junction temperatures above 175°C, a thermal envelope that OEM powertrain engineers are adopting aggressively for next-generation 800-volt platforms. Tier-1 module suppliers are scaling double-sided cooling architectures to exploit this headroom. The structural consequence is converging with opportunities to downsize passive components and extend driving range without battery pack expansion.
The EU Green Deal's embedded carbon disclosure requirements are forcing power electronics manufacturers to document Scope 3 emissions across substrate mining, wafer fabrication, and module assembly stages. Supply chain visibility mandates are compelling Tier-1 suppliers to audit foundry energy sources. European-designed inverter platforms are responding by prioritizing European-sourced silicon carbide substrates where qualification timelines permit.
Fleet procurement teams are consolidating supplier relationships around platform-agnostic module families that span multiple vehicle classes, displacing historical single-platform custom development contracts. This concentration is compressing engineering service margins for Tier-1 integrators while elevating volume commitments for qualified semiconductor suppliers. The shift is most visible in Germany and the United States, where commercial fleet electrification timelines are accelerating faster than passenger EV replacement cycles.
Power Electronics for Electric Vehicle Market Segmentation
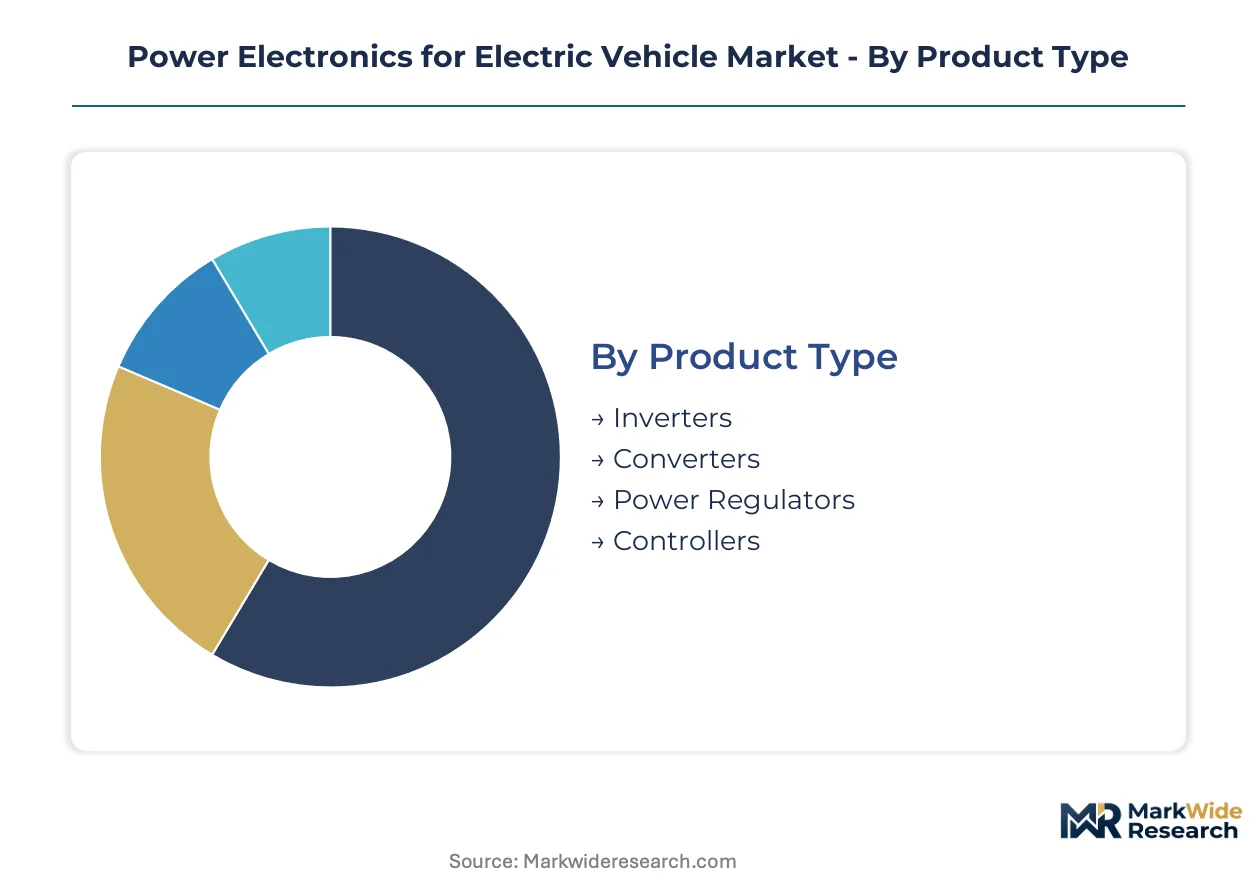
Power electronics procurement in electric vehicles fragments across technical specifications, supply chain roles, and semiconductor architectures. Each segmentation axis reveals distinct margin structures and qualification barriers that shape vendor selection criteria.
Product Type:
Customization intensity varies from platform-specific inverter designs to commodity converter modules, with thermal integration requirements driving standardization at the high-voltage end.
- Inverters:DC-to-AC conversion systems governing traction motor torque delivery, switching at frequencies above 10 kHz. Demand concentrates in 800-volt passenger EV platforms from Germany and China as EPA efficiency mandates tighten. Silicon carbide MOSFET displacement of silicon IGBTs accelerates procurement timelines for premium vehicle classes.
- Converters:DC-to-DC voltage step-down modules feeding auxiliary systems from the high-voltage battery bus. Fleet operators in the United States specify integrated converter-inverter assemblies for heavy-duty electrified trucks, compressing supplier qualification cycles.
- Power Regulators:Voltage stabilization circuits protecting sensitive control electronics from battery load transients.
- Controllers:Gate driver and logic modules coordinating switching sequences across power semiconductor arrays.
Most installed capacity flows through Inverters. Expansion is steepest in Converters as commercial vehicle electrification accelerates.
End User:
Volume concentration tilts toward captive manufacturing versus outsourced procurement, with lifecycle service obligations fragmenting the aftermarket channel.
- OEMs:Automakers internalizing powertrain electrification roadmaps and qualifying proprietary inverter architectures. China's MIIT GB standards directly shape their efficiency targets for domestic and export-bound production.
- Tier-1 Suppliers:Module integrators co-developing platform-specific assemblies with design influence over semiconductor selection. Their engineering margins compress as fleet procurement consolidates around agnostic module families.
- Aftermarket Providers:Retrofit specialists targeting bidirectional charging upgrades and warranty replacement demand.
- Fleet Operators:Commercial buyers specifying decade-long durability requirements and consolidated supplier relationships.
Procurement volume concentrates with OEMs. Tier-1 Suppliers face the steepest margin pressure from standardization mandates.
Technology:
Substrate economics create a three-tier cost-performance ladder, with wide-bandgap materials commanding qualification premiums against mature silicon.
- Silicon:Mature IGBT and MOSFET devices retaining cost advantages in economy vehicle classes. Silicon IGBT commoditization limits pricing power for suppliers serving 400-volt legacy architectures.
- SiC:Silicon carbide substrates enabling junction temperatures above 175°C and downsized thermal management. Wafer supply concentration among East Asian and US growers creates qualification bottlenecks for second-source strategies.
- GaN:Gallium nitride devices suited to lower-voltage onboard charging and DC-DC conversion.
- Integrated Circuits:Control and sensing die packaged with power semiconductors in multi-chip modules.
Silicon retains the largest installed base. SiC is gaining share fastest as 800-volt platforms scale.
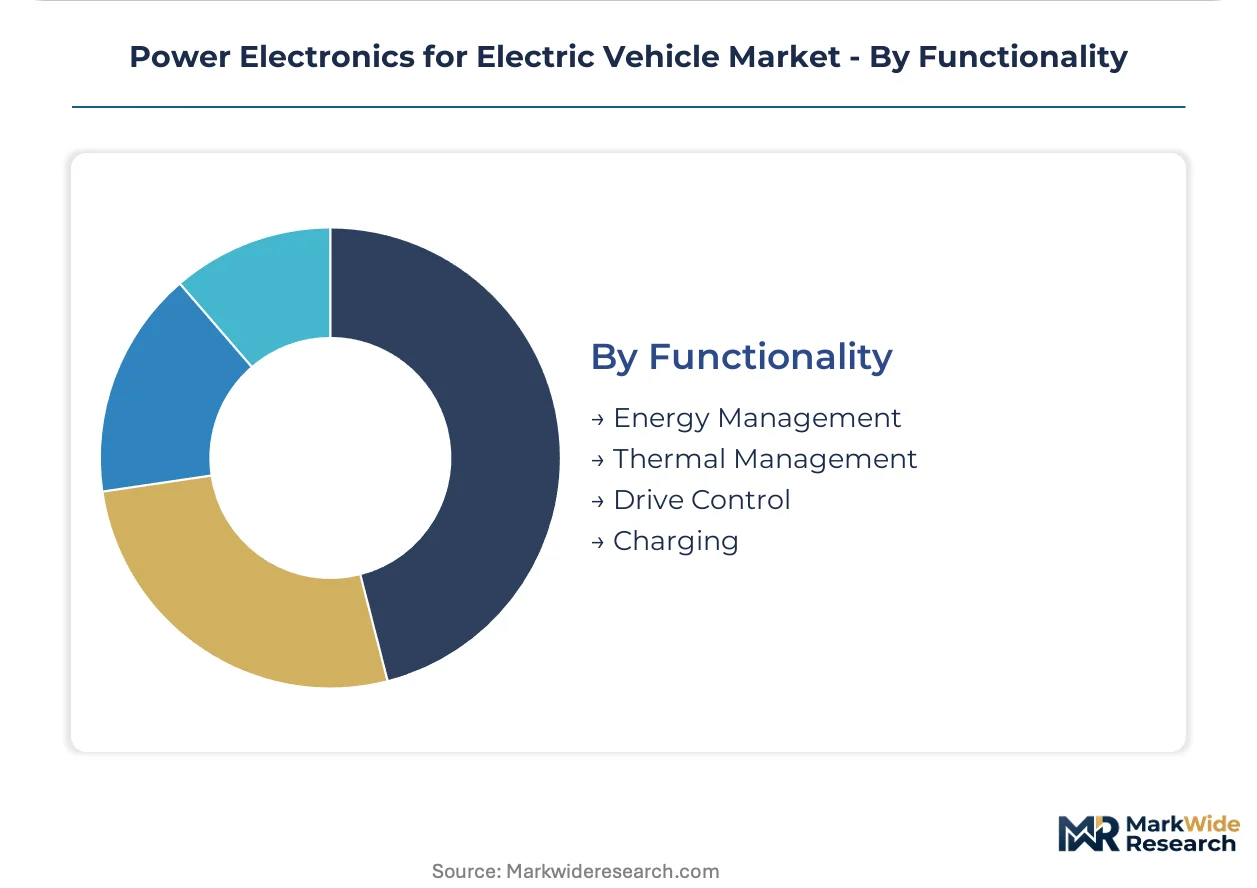
Functionality:
System integration trends compress discrete functional boundaries into consolidated thermal domains, reshaping supplier competitive boundaries.
- Energy Management:Battery state-of-charge optimization and regenerative braking capture algorithms. EU Green Deal embedded carbon disclosure requirements force documentation across substrate mining and wafer fabrication stages.
- Thermal Management:Cooling system integration governing inverter packaging and refrigerant selection. EU F-Gas Regulation constrains refrigerant choices for European-designed platforms.
- Drive Control:Traction motor torque vectoring and efficiency mapping.
- Charging:Onboard and off-board power conversion for AC and DC infrastructure.
Energy Management commands the deepest design integration. Charging functionality is expanding most quickly with bidirectional standards deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest procurement volumes for EV power electronics, while Germany's engineering-intensive supplier ecosystem captures premium-tier module development contracts. The United States, Japan, and South Korea round out the five-country concentration where substrate qualification, inverter manufacturing, and fleet electrification timelines intersect.
China
Domestic battery-electric vehicle output scales faster than any other market, with MIIT GB standards mandating efficiency benchmarks that reshape inverter procurement. The country's dual carbon goals accelerate 800-volt platform adoption across passenger and commercial segments. Yangtze River Delta clusters in Shanghai and Suzhou concentrate wafer fabrication and module assembly capacity for export-bound manufacturers.
Germany
OEM powertrain electrification roadmaps internalize inverter design for premium passenger platforms, while commercial fleet operators specify decade-long durability requirements. EU F-Gas Regulation constrains refrigerant choices in thermal management integration. Bavaria's Munich-Ingolstadt corridor anchors power semiconductor R&D and high-voltage module qualification labs.
United States
IRA manufacturing credits attract power semiconductor fab investments to Arizona and Texas, reshaping regional supply chain geography. EPA fleet-average emissions standards compel higher-efficiency inverter architectures for compliance. Detroit-area engineering centers and California's Silicon Valley design clusters split between legacy automotive integration and next-generation wide-bandgap device development.
Japan
Automotive suppliers leverage precision manufacturing heritage to qualify silicon carbide modules for hybrid and battery-electric platforms. METI industrial policy directs funding toward substrate processing and advanced packaging technologies. Nagoya's Chubu region concentrates Tier-1 module assembly for domestic OEMs and Southeast Asian export markets.
South Korea
Battery cell manufacturers vertically integrate into power electronics to secure pack-level system optimization. The Seoul Capital Area hosts design centers for 800-volt inverter architectures targeting premium EV exports. Busan-Ulsan industrial corridors specialize in high-volume converter module production for commercial vehicle electrification programs.
Power Electronics for Electric Vehicle Market Competitive Environment
Top-tier vendors anchor high-voltage inverter development, while mid-tier module integrators compete on cost engineering for 400-volt legacy platforms. The market structures around three archetypes: captive semiconductor producers serving affiliated OEMs, independent module specialists qualifying multi-customer platforms, and substrate growers supplying wafer to external foundries. Competitive moves concentrate on backward integration into substrate supply and geographic diversification of packaging capacity.
Among German-based diversified suppliers, Continental AG and Robert Bosch GmbH occupy positions spanning semiconductor production through module assembly. Infineon Technologies AG exemplifies the captive-foundry archetype with dedicated fab capacity for automotive qualification. These three entities represent distinct strategic postures: full vertical integration, Tier-1 module supply, and merchant semiconductor provision.
| Leading Market Players |
|---|
| Continental AG |
| Hitachi Astemo |
| Infineon Technologies AG |
| Valeo |
| Delphi Technologies |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Panasonic Corporation |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide device characterization specialists concentrated in Germany's Bavaria corridor and Japan's Nagoya region command wage premiums that widen spreads between premium 800-volt inverter modules and commodity 400-volt silicon assemblies. Labor-cost differentials between these engineering clusters and mass-assembly operations in China's Yangtze River Delta feed directly into three-tier pricing structures that OEM procurement teams navigate across vehicle classes.
Pricing Analysis
Bundled engineering services for platform-specific inverter co-development separate from unbundled spot procurement of qualified converter modules. Three-tier pricing structure across premium, standard, and economy levels reflects silicon carbide wafer grade, AEC-Q101 certification tier, and thermal management integration depth. Cost compression in mid-market silicon IGBT assemblies is intensifying because Chinese substrate growers are expanding 150mm wafer capacity. Fleet operators specifying decade-long durability requirements exhibit lowest price sensitivity, while economy passenger EV platforms demonstrate highest sensitivity to per-unit module costs.
Supply Chain Analysis
Reverse-logistics flows for warranty replacement inverters and remanufactured power modules are concentrating refurbishment capacity near Detroit-area engineering centers and Stuttgart's aftermarket clusters. Raw material supply draws from silicon carbide substrate growers in the United States and Japan, rare earth processing facilities in China, and copper busbar fabricators in Germany. Single-source vulnerability concentrates in 200mm silicon carbide wafer qualification timelines. Distribution runs through captive OEM supply chains for high-voltage architectures and independent Tier-1 module integrators for commercial vehicle platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA fleet-average emissions standards and China MIIT GB efficiency mandates mechanically expand addressable demand for wide-bandgap inverter architectures regardless of underlying vehicle sales cyclicality.
For Market Incumbents: Cement substrate supply commitments through long-term offtake agreements with East Asian and US wafer growers before qualification bottlenecks tighten. Expand in-house production of gate driver ICs to defend margin position against fabless module specialists exploiting silicon carbide MOSFET commoditization. Prioritize Arizona and Texas fab investments to capture IRA manufacturing credits and reduce tariff exposure on imported substrates. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass entrenched OEM-Tier-1 procurement relationships and enable aftermarket bidirectional charging retrofit offerings. Target commercial heavy-duty truck electrification programs in the United States where decade-long durability specifications and consolidated supplier relationships remain underpenetrated. Lead with vehicle-to-grid interoperability certification as the primary go-to-market wedge against legacy inverter suppliers. For Investors and Strategic Acquirers: Battery cell manufacturers are the most active acquirer in this space, pursuing pack-level system optimization through vertical integration into power electronics. Five-to-ten year viability hinges on substrate supply security rather than module assembly scale. Watch for 200mm silicon carbide wafer qualification milestones at second-source foundries as the critical inflection signal for margin expansion in premium inverter tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | Captive wafer supply secures allocation priority during East Asian foundry capacity constraints. |
| 800-Volt Platform Standardization | OEM consolidation around common inverter architectures compresses engineering service margins for Tier-1 integrators. |
| Bidirectional Charging Infrastructure Partnership | Vehicle-to-grid interoperability standards create aftermarket retrofit demand across residential energy storage applications. |
| Arizona-Texas Manufacturing Footprint Expansion | IRA clean energy production credits reshape regional supply chain geography for power semiconductor fabrication. |
| Commercial Fleet Electrification Supply Agreement | Heavy-duty truck and bus operators specify decade-long lifecycle durability requirements that favor qualified module suppliers. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down semiconductor shipment tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 supplier procurement directors, silicon carbide substrate growers, and fleet operator technical specification teams combined with secondary validation from EPA regulatory filings, China MIIT GB standard disclosures, IHS Markit vehicle registration databases, and SEC 10-K semiconductor segment reports. Triangulation between demand-side build-ups and supply-side capacity assessments resolves discrepancies in wide-bandgap device penetration assumptions.
Input-output matrices map inverter content per vehicle across passenger and commercial electrified platforms, with segmentation dimensions spanning propulsion architecture, voltage class, semiconductor technology tier, and regional production cluster. CAGRs derive from modeled adoption curves for silicon carbide MOSFET displacement of silicon IGBTs, calibrated against substrate supply expansion timelines and automotive qualification cycle durations. Forecast inputs include EPA fleet compliance trajectory scenarios and China dual carbon policy implementation intensity.
The model assumes a particular technology adoption path; alternative pathways for gallium nitride intrusion into onboard charging applications would alter the outlook for silicon carbide market share capture. Forecasts embed assumptions regarding 200mm wafer yield improvements and AEC-Q101 certification timeline compression that could revise volume projections. Practitioners should monitor EPA rulemaking announcements, China MIIT standard revision schedules, and second-source silicon carbide substrate qualification milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Ultrafast Rectifiers Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Electrical and Automation System Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Embedded Power Generation Market
Power Systems
Shunt Reactor Market
Power Systems
Thermoelectric Coolers Market
Power Systems
Synchrophasors Market
Power Systems
Flyback Transformer Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market
Power Systems
Europe Micro Inverter Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market