
 Global Flexible Batteries Market | 2026-2036
Global Flexible Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Batteries Market Analysis
A capital-intensity divergence between thin-film deposition specialists and commodity lithium-ion incumbents is reorganizing competitive tiers in flexible power. Samsung SDI leverages its display-panel heritage to dominate roll-to-roll electrode manufacturing for curved applications. LG Energy Solution anchors its position through captive polymer electrolyte development, while Enfucell Oy Ltd. specializes in printed zinc-based microcells for disposable medical patches where low energy density suffices.
Flexible batteries are electrochemical energy storage devices engineered on compliant substrates—typically polymer or metallic foils below 0.5 mm thick—that maintain electrochemical performance under mechanical deformation such as bending, twisting, or stretching; their primary commercial purpose is to power electronics where rigid cylindrical or prismatic cells geometrically fail. Thin-film lithium-polymer variants occupy the premium tier, serving medical implants and military wearables where cycle stability commands margin pools. Printed electronics-based microbatteries represent the fastest-expanding technology segment, driven by IoT sensor networks requiring sub-millimeter form factors. Solid-state flexible architectures remain pre-commercial but attract disproportionate R&D allocation due to their theoretical energy density advantage and elimination of flammable liquid electrolytes.
FDA device classifications for implantable power sources and EU MDR conformity requirements govern market access for medical-grade flexible cells, while REACH restrictions on cobalt and nickel compounds compel cathode material reformulation across European supply chains. China's GB standards for lithium-ion safety and Japan's METI recycling directives add compliance layers for manufacturers serving Asia-Pacific medical and consumer electronics channels. Stakeholders must monitor solid-state electrolyte breakthrough timelines against polymer-gel incumbent cost curves to time capacity commitments.
Market Dynamics
Roll-to-roll electrode manufacturing is compressing unit economics for curved-form-factor cells while REACH cobalt restrictions force cathode chemistry redesigns across European supply chains. Samsung SDI and LG Energy Solution anchor concentrated R&D clusters in South Korea, creating procurement bottlenecks for conformal power solutions.
Growth Catalysts
- Wearable form-factor constraints:Consumer electronics manufacturers are accelerating procurement of sub-millimeter cells as smartwatch and fitness tracker designs eliminate rigid battery cavities.
- EU Battery Regulation:Recyclability mandates for thin-film producers are creating compliant material ecosystems that reduce long-term supply risk for medical-grade applications.
- Printed zinc microcells:Disposable medical patch manufacturers are adopting printed electronics-based architectures where low energy density suffices and disposability is paramount.
Market Restraints
- Cobalt and nickel compound restrictions:ECHA REACH limitations compel cathode material reformulation, raising qualification timelines for European market entry.
- Polymer electrolyte supply concentration:Captive development programs at Korean energy conglomerates limit third-party access to high-performance gel electrolyte formulations.
- Solid-state pre-commercial gap:Theoretical energy density advantages remain unrealized as ceramic electrolyte manufacturing yields stall below commercial thresholds.
Strategic Opportunities
- India medical device localization:PLI scheme incentives for electronics manufacturing are attracting thin-film cell assembly investments serving domestic diagnostic patch producers.
- Solid-state electrolyte convergence:Ceramic-polymer composite architectures promise simultaneous mechanical compliance and thermal stability for implantable applications.
- Direct-to-OEM distribution:Bypassing traditional battery distributor networks allows flexible cell specialists to capture design-in premiums from wearable startups.
Industry Challenges
- Roll-to-roll technician scarcity:Thin-film deposition specialists command compensation premiums that strain mid-cap producer operating models.
- FDA 510(k) timeline compression:Implantable power source classifications require extended clinical validation that delays revenue recognition for medical-grade product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Batteries Market |
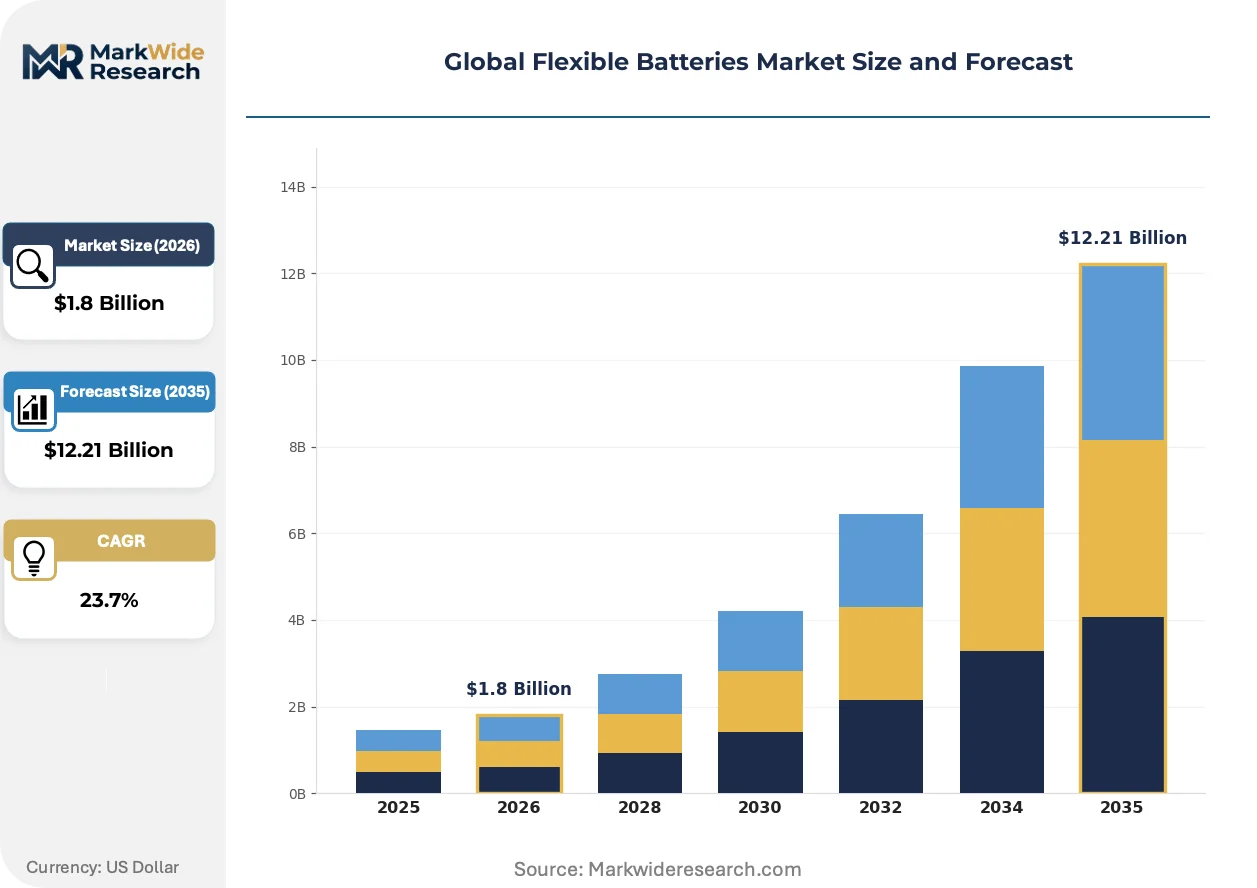
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film, Organic, Solid-State, Lithium-Ion End User: Consumer Electronics, Wearable Devices, Automotive, Medical Devices Technology: Printed Electronics, Microbattery, Energy Harvesting, Flexible Solar Cells Application: Flexible Displays, Smart Textiles, Internet of Things, Wireless Sensors |
| Companies Covered | Samsung SDI Co., Ltd., LG Energy Solution Ltd., Panasonic Corporation, Contemporary Amperex Technology Co., Limited (CATL), STMicroelectronics N.V., Murata Manufacturing Co., Ltd., Enfucell Oy Ltd., BrightVolt Inc., SK On Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Batteries Market Emerging Trajectories
Electrode manufacturing processes are fragmenting into display-panel-derived roll-to-roll methods versus printed electronics approaches, with each path optimizing for distinct deformation tolerance and energy density trade-offs. This divergence is reshaping equipment supplier relationships and cleanroom capital allocation across the value chain.
Thin-film lithium-polymer architectures are bifurcating into premium medical tiers serving implantable neurostimulators versus cost-optimized consumer variants for disposable skin patches. Medtronic and Abbott procurement teams specify cycle stability above five hundred cycles for cardiac rhythm management devices, while cosmetic wearable buyers prioritize sub-dollar bill-of-materials targets. This split is compressing mid-range product positioning and forcing suppliers to declare specialization early in development roadmaps.
EU MDR conformity requirements for active implantable medical devices are tightening post-market surveillance obligations for power source manufacturers. Battery producers must now maintain device history records traceable to individual electrode deposition batches, raising quality management system costs. German notified bodies are processing certification renewals with extended timelines, pushing non-European suppliers toward authorized representative partnerships.
Buyer concentration among top-five wearable OEMs is consolidating procurement leverage and compressing supplier margins through multi-year volume commitments. Direct sourcing teams at Apple and Samsung are bypassing traditional cell distributors to negotiate electrode formulation exclusivity. This channel disintermediation is most visible in South Korea, where domestic energy conglomerates maintain captive supply relationships with affiliated electronics divisions.
Global Flexible Batteries Market Segmentation
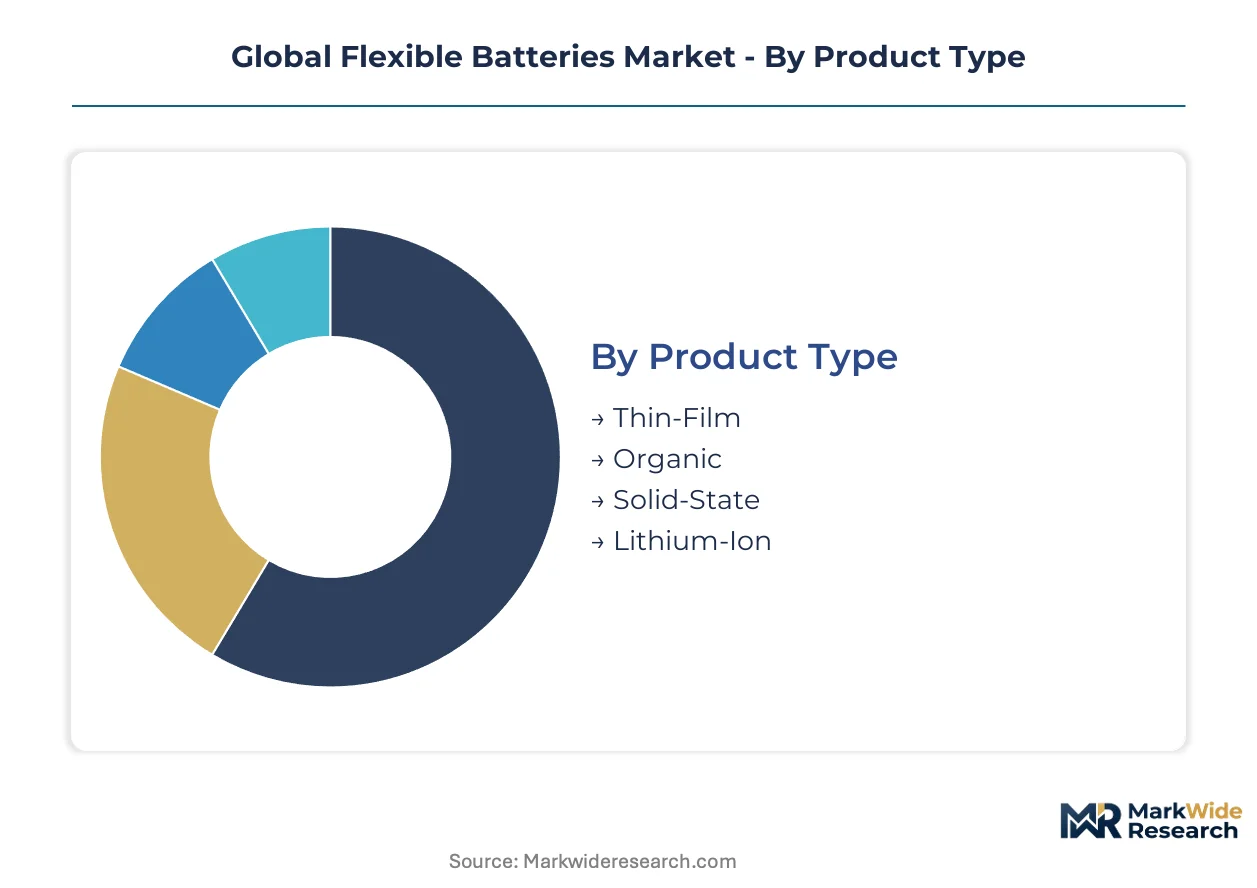
Flexible battery architectures fragment across substrate chemistry, end-use compliance regimes, and manufacturing process compatibility. Each segmentation axis carries distinct margin profiles and qualification barriers that determine supplier positioning.
Product Type:
FDA 510(k) pathways and EU MDR conformity requirements create divergent approval timelines across electrochemical architectures, concentrating procurement leverage among pre-qualified suppliers.
- Thin-Film:Polymer or metallic foil substrates below 0.5 mm thickness enable conformal integration with curved device housings. Demand concentrates in South Korea's display panel supply chain, where Samsung SDI leverages roll-to-roll electrode heritage to serve smartwatch manufacturers eliminating rigid battery cavities. FDA device classifications for implantable neurostimulators and cardiac rhythm management devices command cycle stability above five hundred cycles, creating premium tier pricing.
- Solid-State:Ceramic-polymer composite electrolytes eliminate flammable liquid components while promising theoretical energy density advantages. Manufacturing yields for ceramic electrolyte deposition remain below commercial thresholds, delaying revenue recognition despite disproportionate R&D allocation from medical-grade suppliers seeking thermal stability for implantable applications.
- Organic:Conductive polymer electrodes fabricated through solution processing offer biodegradability pathways for disposable medical patches. REACH restrictions on cobalt and nickel compounds compel cathode material reformulation across European supply chains.
- Lithium-Ion:Gel polymer electrolyte variants dominate current commercial volume through established winding and stacking equipment compatibility. China's GB standards for lithium-ion safety and Japan's METI recycling directives add compliance layers for Asia-Pacific channel access.
Established volume favors Lithium-Ion; emerging adoption favors Solid-State.
End User:
Customer procurement patterns split between multi-year volume commitments from concentrated OEM buyers and fragmented spot purchasing from specialized device startups.
- Consumer Electronics:Smartwatch and fitness tracker manufacturers are accelerating procurement of sub-millimeter cells as industrial design teams eliminate rigid battery cavities entirely. Direct sourcing teams at Apple and Samsung negotiate electrode formulation exclusivity, bypassing traditional cell distributors to compress supplier margins.
- Wearable Devices:Cosmetic wearable buyers prioritize sub-dollar bill-of-materials targets over cycle stability metrics. This cost pressure forces suppliers to declare specialization early in development roadmaps, compressing mid-range product positioning.
- Automotive:Interior sensing applications and structural battery integration concepts drive exploratory procurement from tier-one seating and dashboard suppliers. Regulatory frameworks for automotive battery safety remain unsettled for flexible architectures.
- Medical Devices:Implantable power source classifications require extended clinical validation that delays revenue recognition. EU MDR conformity requirements tighten post-market surveillance obligations, forcing battery producers to maintain device history records traceable to individual electrode deposition batches.
Procurement leverage concentrates in Consumer Electronics; qualification barriers protect Medical Devices.
Technology:
Manufacturing equipment requirements fragment the supplier base between display-panel-derived roll-to-roll methods and printed electronics approaches.
- Printed Electronics:Screen and inkjet deposition of functional materials onto polymer substrates enables sub-millimeter form factors for IoT sensor networks. Disposable medical patch manufacturers adopt printed zinc-based microcells where low energy density suffices and disposability is paramount.
- Microbattery:Stacked or wound architectures below 10 mm² footprint serve hearing aids and continuous glucose monitors. Enfucell Oy Ltd. specializes in this segment for single-use diagnostic applications.
- Energy Harvesting:Thermoelectric and piezoelectric generators paired with thin-film storage extend operational life in remote sensor deployments. Integration complexity limits current commercial scale.
- Flexible Solar Cells:Perovskite and organic photovoltaic layers laminated with storage cells create self-powered wearables. Efficiency degradation under mechanical deformation constrains outdoor application viability.
Printed Electronics climbs the fastest; Energy Harvesting awaits systems integration maturation.
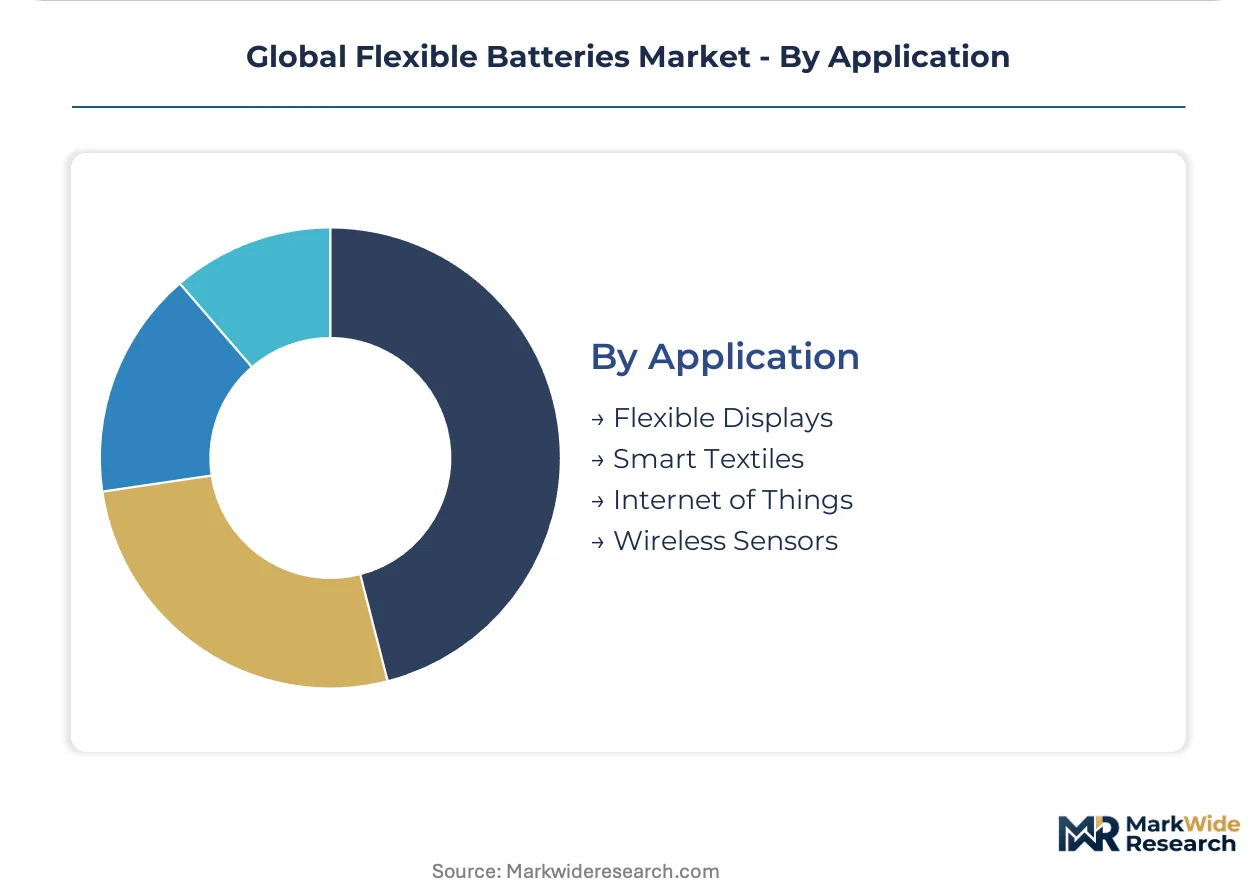
Application:
Deformation tolerance requirements and energy density trade-offs determine substrate and electrolyte selection across use cases.
- Flexible Displays:Curved OLED panels in smartphones and automotive dashboards require conformal power solutions matching display curvature radii. Samsung SDI dominates this segment through captive supply relationships with affiliated electronics divisions.
- Smart Textiles:Conductive yarn integration and wash-cycle durability specifications drive polymer electrolyte selection toward gel formulations with mechanical compliance. LG Energy Solution anchors position through captive polymer electrolyte development.
- Internet of Things:Distributed sensor networks requiring sub-millimeter form factors expand printed microbattery demand. India's PLI scheme incentives for electronics manufacturing attract thin-film cell assembly investments serving domestic diagnostic patch producers.
- Wireless Sensors:Industrial asset monitoring and environmental tracking applications prioritize extended shelf life over cycle stability. Disposable architectures reduce maintenance logistics in hazardous or remote installations.
Flexible Displays command current revenue concentration; Smart Textiles offer steepest expansion trajectory as fashion-technology convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of thin-film electrode materials concentrate in South Korean and Japanese manufacturing corridors, while import dependence for polymer electrolyte precursors shapes European and North American procurement strategies. Trade balances reflect captive supply relationships between battery conglomerates and affiliated electronics divisions.
United States
Medtronic and Abbott procurement teams drive demand for implantable-grade thin-film cells serving cardiac rhythm management devices. FDA 510(k) pathways for active implantable medical devices extend qualification timelines beyond eighteen months. Greater Boston and Minneapolis-St. Paul anchor medical device manufacturing clusters where battery producers maintain device history records traceable to individual electrode batches.
South Korea
Samsung SDI and LG Energy Solution anchor concentrated R&D clusters for roll-to-roll electrode manufacturing serving curved smartwatch applications. The Ministry of Trade, Industry and Energy (MOTIE) directs national battery competitiveness initiatives through the K-Battery Development Strategy. Seoul Capital Area and Busan-Ulsan corridor host vertically integrated production from electrolyte formulation through final cell assembly.
Germany
Automotive interior sensing applications from tier-one seating suppliers drive exploratory procurement of conformal power solutions. ECHA REACH restrictions on cobalt and nickel compounds compel cathode material reformulation across European supply chains. Bavaria and Baden-Württemberg concentrate printed electronics equipment suppliers serving medical diagnostic patch producers.
China
CATL and domestic electronics OEMs accelerate procurement of sub-millimeter cells for fitness tracker designs eliminating rigid battery cavities. GB standards for lithium-ion safety administered by SAMR add compliance layers for medical and consumer electronics channels. Yangtze River Delta and Pearl River Delta manufacturing corridors integrate flexible cell assembly with display panel production.
Japan
Murata Manufacturing and Panasonic Corporation leverage ceramic capacitor heritage for solid-state electrolyte development targeting implantable thermal stability. METI recycling directives shape end-of-life obligations for thin-film producers serving domestic wearable markets. Kansai region around Osaka anchors polymer electrolyte precursor chemical production.
Global Flexible Batteries Market Vendor Landscape
Concentration sits with Korean energy conglomerates possessing captive electrolyte development programs and display-panel-derived manufacturing heritage. The supplier base fragments between thin-film deposition specialists commanding technician premiums and commodity lithium-ion incumbents repurposing winding equipment. Three archetypes dominate: vertically integrated electronics conglomerates, printed electronics microcell specialists, and solid-state ceramic electrolyte developers. Capacity commitments follow multi-year volume agreements with top-five wearable OEMs, while technology licensing partnerships accelerate ceramic-polymer composite electrolyte maturation.
Among Korean conglomerates, Samsung SDI Co., Ltd. and LG Energy Solution Ltd. exemplify the integrated archetype combining electrode manufacturing with captive polymer electrolyte supply. Enfucell Oy Ltd. occupies a distinct position within the printed microcell tier, representing specialists serving disposable medical patch applications where low energy density suffices. These three anchors illustrate the competitive divergence between scale-driven roll-to-roll production and solution-processed microfabrication approaches.
| Leading Market Players |
|---|
| Samsung SDI Co., Ltd. |
| LG Energy Solution Ltd. |
| Panasonic Corporation |
| Contemporary Amperex Technology Co., Limited (CATL) |
| STMicroelectronics N.V. |
| Murata Manufacturing Co., Ltd. |
| Enfucell Oy Ltd. |
| BrightVolt Inc. |
| SK On Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Sixty-day electrode precursor lead times from South Korean suppliers compress procurement flexibility for European and North American thin-film assemblers, concentrating pricing power with vertically integrated conglomerates that internalize polymer electrolyte formulation and roll-to-roll deposition capacity.
Pricing Analysis
The customization-premium spread between FDA-qualified implantable-grade cells and standard consumer variants exceeds three-to-one, with cycle stability certification and EU MDR traceability requirements commanding substantial premiums from Medtronic and Abbott procurement teams. Three-tier pricing structure across premium, standard, and economy levels stratifies by qualification tier rather than energy density alone. Cost compression in the consumer wearable tier intensifies because Apple and Samsung direct-sourcing teams negotiate electrode formulation exclusivity, stripping distributor margins. Medical device OEMs exhibit least price sensitivity due to regulatory switching costs, while cosmetic wearable startups prioritize sub-dollar bill-of-materials targets.
Supply Chain Analysis
Inventory concentration for high-purity lithium salts and cobalt-free cathode precursors rests on South Korea, Japan, and China's Yangtze River Delta manufacturing corridors, where Samsung SDI and LG Energy Solution maintain captive electrolyte development programs. Raw material dependencies center on polymer substrates from Japanese chemical conglomerates, ceramic electrolyte precursors from German specialty materials suppliers, and roll-to-roll deposition equipment from Bavaria-based vendors. Single-source vulnerability for gel polymer electrolyte formulations limits third-party access as Korean energy conglomerates internalize formulation IP. Distribution runs through direct OEM procurement teams bypassing traditional cell distributors, compressing channel margins across all tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales revenue from device history record maintenance and batch-traceability compliance services expands faster than hardware unit sales as EU MDR post-market surveillance obligations deepen recurring revenue streams for qualified suppliers.
For Market Incumbents: Compound defensive moats by deepening backward integration into polymer electrolyte precursor production and securing exclusive roll-to-roll technician training pipelines. Solid-state ceramic electrolyte developers threaten premium-tier positioning, necessitating accelerated R&D allocation to ceramic-polymer composite architectures. Capacity addition in India's PLI-subsidized electronics manufacturing corridors captures localization premiums from domestic diagnostic patch producers.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for predicate-device-equivalent thin-film architectures offer expedited market entry timelines beneath eighteen months. White-space concentrates in printed zinc microcells for disposable medical patches where Enfucell Oy Ltd.'s specialist model proves replicable, and in solid-state electrolyte components for implantable thermal stability applications. Direct-to-OEM distribution bypassing Korean-affiliated channel networks captures design-in premiums from wearable startups in Greater Boston and Minneapolis-St. Paul medical device clusters.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because qualification barriers for FDA and EU MDR implantable-grade certifications compound incumbent advantages over five-to-ten-year horizons. Acquisition targets should display ceramic-polymer composite electrolyte IP portfolios or established notified body relationships with German conformity assessment organizations. Watch solid-state manufacturing yield breakthroughs against polymer-gel incumbent cost curves as the inflection signal for capacity commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Polymer Electrolyte Convergence | Combines mechanical compliance with thermal stability for implantable neurostimulator applications. |
| Roll-to-Roll Capacity Expansion | Compresses unit economics for curved smartwatch cells serving Samsung Display and LG Electronics. |
| EU MDR Authorized Representative Partnerships | Accelerates German notified body certification timelines for non-European thin-film suppliers. |
| India PLI Localization Investment | Captures domestic diagnostic patch demand from CDSCO-registered medical device manufacturers. |
| Direct-to-OEM Channel Bypass | Eliminates distributor margins and secures electrode formulation exclusivity with Apple procurement. |
Methodological Framework
Desk research of SEC 10-K filings from energy conglomerates, SAMR GB standard documentation, and ECHA REACH restriction databases preceded structured interviews with thin-film deposition equipment engineers, polymer electrolyte R&D directors, and FDA regulatory affairs specialists at active implantable medical device manufacturers. Primary fieldwork with hospital purchasing committees and GPO contracts managers validated secondary estimates of procurement volume concentration. Bottom-up cell shipment aggregation across South Korean and Chinese manufacturing corridors triangulated against top-down wearable OEM bill-of-materials analysis.
Variance decomposition across product type, end user, and technology segmentation dimensions isolated growth contribution by electrochemical architecture over the projection horizon. CAGRs derived from logistic adoption curves fitted to medical device qualification timelines and consumer electronics design cycle compression. Forecast inputs incorporated solid-state electrolyte manufacturing yield trajectories, REACH cobalt substitution rates, and PLI scheme incentive disbursement schedules.
Underlying assumptions cover stable FDA 510(k) review timelines and continued EU MDR notified body capacity, with deviation risk concentrated in ceramic electrolyte deposition yield breakthroughs and Korean conglomerate vertical integration decisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Rugged Power Supply Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Voltage Regulators Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Space DC-DC Converters Market
Power Systems
Integrated UPS Market
Power Systems
Battery Racks Market
Power Systems
Global Frequency Converter Market
Power Systems
Thermal Management Systems Market
Power Systems
Shunt Reactor Market
Power Systems
Series Reactor Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Laptop Battery Market
Power Systems
Traction Inverter Market