
 Medium Voltage Transformer Market | 2026-2036
Medium Voltage Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Voltage Transformer Market Analysis
Software-defined monitoring and predictive maintenance is consolidating around transformer fleets, shifting vendor economics from hardware-only sales toward lifecycle service contracts. Siemens Energy leverages its digital twin platform to anchor long-term utility relationships. Hammond Power Solutions sustains competitive positioning through specialized dry-type manufacturing scale. ABB differentiates via integrated power-electronics control extending into medium-voltage distribution networks.
A medium voltage transformer converts electrical power between voltages typically ranging from 2.4 kV to 69 kV, utilizing laminated silicon-steel cores and either mineral oil or cast-resin insulation systems to manage thermal loads and dielectric stress. These units serve as critical nodes in distribution grids, stepping down transmission voltages for industrial plants, commercial complexes, and municipal utilities. Oil-immersed technology dominates installed base volumes due to cost efficiency and thermal performance, while dry-type systems lead growth trajectories in indoor commercial and urban underground installations where fire safety and environmental containment constrain liquid-filled alternatives. Three-phase configurations command the largest share of utility procurement, with single-phase units occupying niche rural and residential feeder applications.
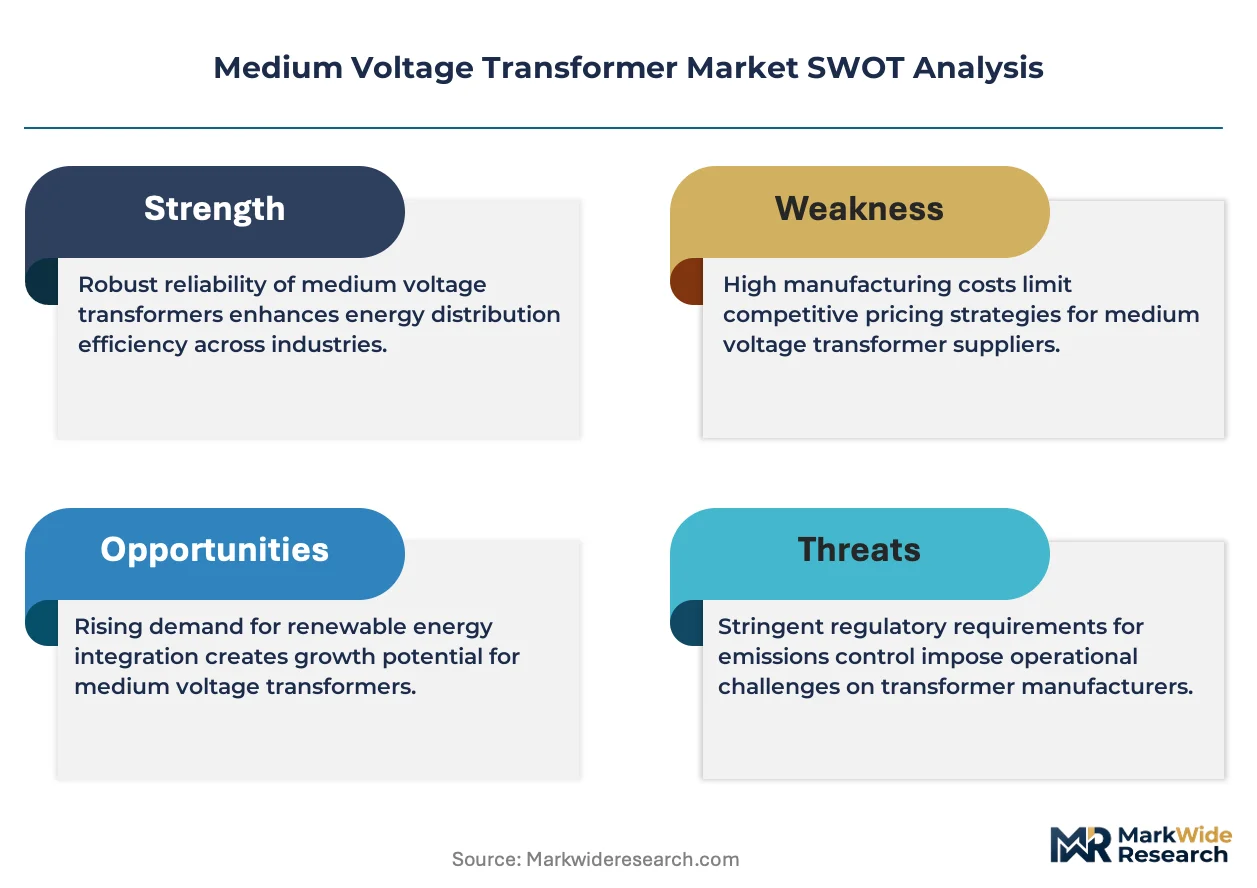
IEC 60076 and IEEE C57 standards govern efficiency tiers and test protocols, while EPA regulations in the United States restrict polychlorinated biphenyl contamination in legacy oil-filled units, accelerating replacement cycles. Ecodesign directives in Europe mandate minimum performance indices for new installations, channeling demand toward amorphous-core and high-grade grain-oriented steel designs. China's GB standards and dual carbon targets enforce efficiency benchmarks that reshape export manufacturing requirements. Stakeholders must weigh stranded-asset risk in conventional oil-immersed portfolios against the capital intensity of gas-insulated and vacuum-technology transitions.
Market Dynamics
Utility-scale grid modernization across the United States, Germany, and India is compressing transformer replacement cycles while IEC 60076 efficiency mandates force core material upgrades and thermal design overhauls.
Growth Catalysts
- Grid hardening investments:United States utilities under FERC Order 2222 are procuring three-phase medium voltage transformers for distributed energy resource integration at substation nodes.
- IEC 60076-20 efficiency tiers:European Ecodesign directives mandate minimum performance indices that channel demand toward amorphous-core and high-grade grain-oriented steel designs.
- Cast-resin insulation systems:Dry-type technology captures procurement share in indoor commercial and urban underground installations where fire safety codes restrict liquid-filled alternatives.
Market Restraints
- Grain-oriented electrical steel concentration:Supply concentrates among Japanese and European specialty steel producers, exposing transformer OEMs to input cost volatility and allocation constraints.
- Mineral oil containment liability:EPA polychlorinated biphenyl regulations impose remediation burdens on legacy oil-immersed installations, accelerating stranded-asset risk for utility fleets.
- Amorphous metal core fabrication scale:Limited production capacity for non-crystalline alloy cores constrains rapid substitution of conventional silicon-steel laminations despite efficiency advantages.
Strategic Opportunities
- India rural electrification:The country's central electricity authority procurement targets for single-phase distribution transformers create volume openings for cost-optimized designs.
- Digital twin integration:Software-defined monitoring platforms enable lifecycle service contracts that extend vendor economics beyond hardware-only sales to utility fleet operators.
- Gas-insulated technology:Vacuum interrupter and SF6-alternative designs penetrate space-constrained urban substations where fire codes and environmental containment limit conventional oil-filled units.
Industry Challenges
- Transformer design engineering scarcity:Specialized electromagnetic modeling and thermal management expertise concentrates among aging workforce cohorts in Europe and North America.
- Multi-standard certification timelines:Simultaneous IEEE C57, IEC 60076, and GB standard compliance extends product validation cycles for manufacturers serving export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Voltage Transformer Market |
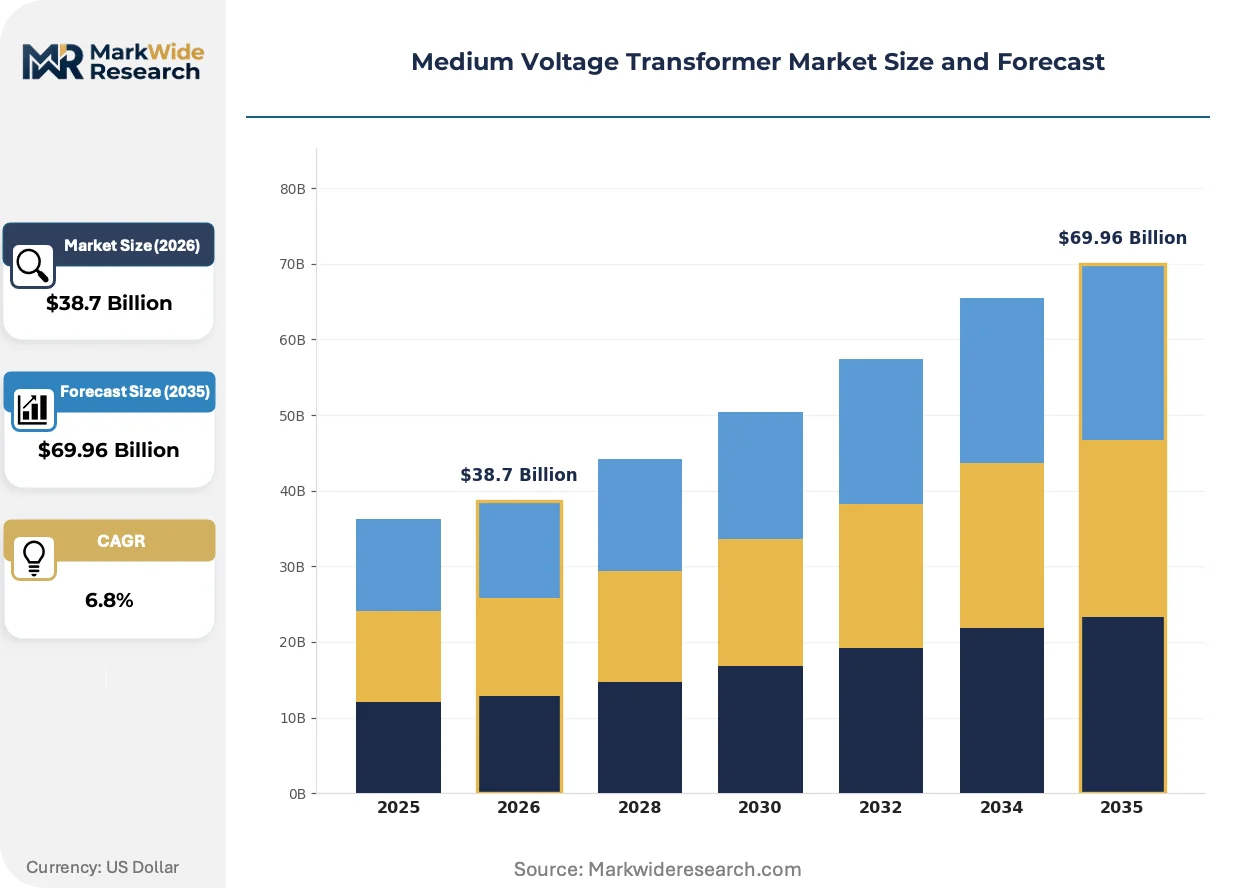
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-Phase, Single-Phase, Auto-Transformer, Distribution Transformer End User: Residential, Commercial, Industrial, Utilities Installation: Indoor, Outdoor, Underground, Above Ground Technology: Oil-Immersed, Dry-Type, Vacuum, Gas-Insulated |
| Companies Covered | Hammond Power Solutions, Virginia Transformer Corporation, ELSCO Transformers, ABB, Siemens Energy, Prolec GE Waukesha, MGM Transformer Company, JSHP Transformer, Olsun Electrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Voltage Transformer Market Emerging Trajectories
Dry-type insulation systems and predictive analytics platforms are redefining transformer lifecycle economics while material science advances compress core losses and thermal footprints.
Cast-resin vacuum-pressure impregnation technology is modularizing medium voltage transformer architectures for indoor commercial installations. Property developers in Germany and Japan specify these units for high-rise electrical rooms where fire codes prohibit mineral oil. The technology is modularizing procurement patterns by enabling prefabricated substation skids that reduce on-site assembly labor and commissioning time.
EPA restrictions on polychlorinated biphenyl contamination in legacy oil-filled units are accelerating replacement cycles across United States municipal utility fleets. Industrial consequence includes forced early retirement of serviceable transformers and capital reallocation toward dry-type or ester-fluid alternatives. Rural electric cooperatives in the Midwest and Southeast face the steepest compliance burdens as they manage dispersed populations of pre-1979 installations.
After-sales service unbundling is fragmenting traditional OEM-customer relationships in the utility segment. Independent predictive maintenance providers equipped with dissolved gas analysis and thermal imaging capabilities are displacing manufacturer-anchored service contracts. This pattern concentrates in North American investor-owned utilities seeking operational expenditure flexibility over capital-intensive fleet replacement programs.
Medium Voltage Transformer Market Segmentation
Transformer procurement patterns diverge sharply across product architectures and deployment contexts. Utility planners weigh thermal performance against fire safety codes, while industrial buyers prioritize load-cycle flexibility. Understanding these segment boundaries clarifies where technology transitions disrupt incumbent supply relationships.
Product Type:
Standalone substation installations favor bulk-power handling capacity, while embedded distribution networks require compact, modular configurations.
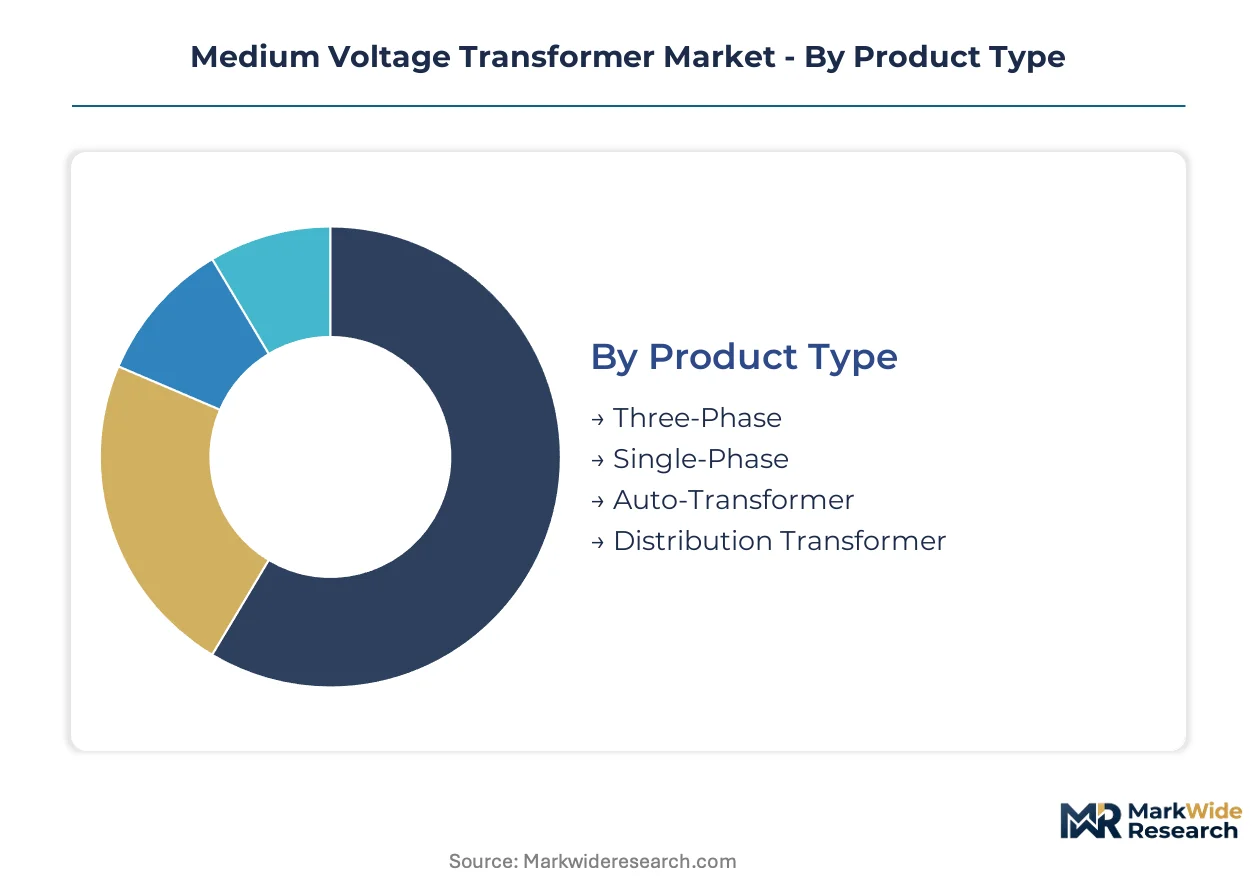
- Three-Phase:Core-and-coil assemblies rated 2.4 kV to 69 kV handle bulk power transfer at utility substations and industrial plants. Procurement concentrates in United States, Germany, and India grid modernization programs under FERC Order 2222 and IEC 60076-20 efficiency mandates. FERC Order 2222 accelerates distributed energy resource integration at substation nodes.
- Single-Phase:Pole-mounted or pad-mounted units serve rural distribution feeders and residential tap-offs. India's Central Electricity Authority procurement targets for rural electrification create volume openings for cost-optimized designs. CEA procurement schedules favor compact, lightweight constructions for last-mile deployment.
- Auto-Transformer:Single-winding designs reduce copper mass for voltage ratios under 3:1 in interconnected grid applications.
- Distribution Transformer:Step-down units at 11 kV to 33 kV interface between primary distribution and low-voltage secondary networks.
Three-Phase leads volumes today; Single-Phase is gaining share fastest.
End User:
Capital intensity and load predictability separate price-sensitive residential procurement from performance-critical industrial specifications.
- Industrial:Heavy manufacturing, data centers, and mining operations specify cast-resin or ester-fluid units for fire safety compliance and load-cycle resilience. German chemical parks and Japanese automotive clusters specify dry-type technology for indoor electrical rooms where mineral oil is prohibited.
- Utilities:Transmission and distribution operators manage fleet replacement cycles under EPA polychlorinated biphenyl regulations and EU Ecodesign directives. United States municipal utilities face stranded-asset risk from pre-1979 oil-immersed installations requiring forced retirement.
- Commercial:High-rise developments and retail complexes specify modular, prefabricated substation skids with reduced commissioning time.
- Residential:Single-phase pad-mounted units serve suburban developments and individual dwellings with standardized, price-sensitive procurement.
Utilities dominate capital deployment today; Industrial buyers are expanding procurement fastest.
Installation:
Environmental exposure and fire code constraints determine insulation system selection and thermal management architecture.
- Indoor:Cast-resin dry-type units occupy electrical rooms in German high-rises and Japanese commercial complexes where fire codes prohibit liquid-filled alternatives. Vacuum-pressure impregnation technology enables modular, prefabricated substation skids.
- Underground:Space-constrained urban substations in Tokyo and Singapore deploy gas-insulated or vacuum interrupter designs where oil containment is impractical.
- Outdoor:Conventional oil-immersed units in substation yards and industrial sites leverage natural convection and mineral oil thermal performance.
- Above Ground:Elevated platforms and rooftop installations in dense Asian megacities require compact, lightweight dry-type constructions.
Outdoor installations retain the largest installed base; Underground configurations show the steepest expansion trajectory.
Technology:
Core material efficiency and dielectric medium selection separate mature cost-optimized designs from emerging premium architectures.
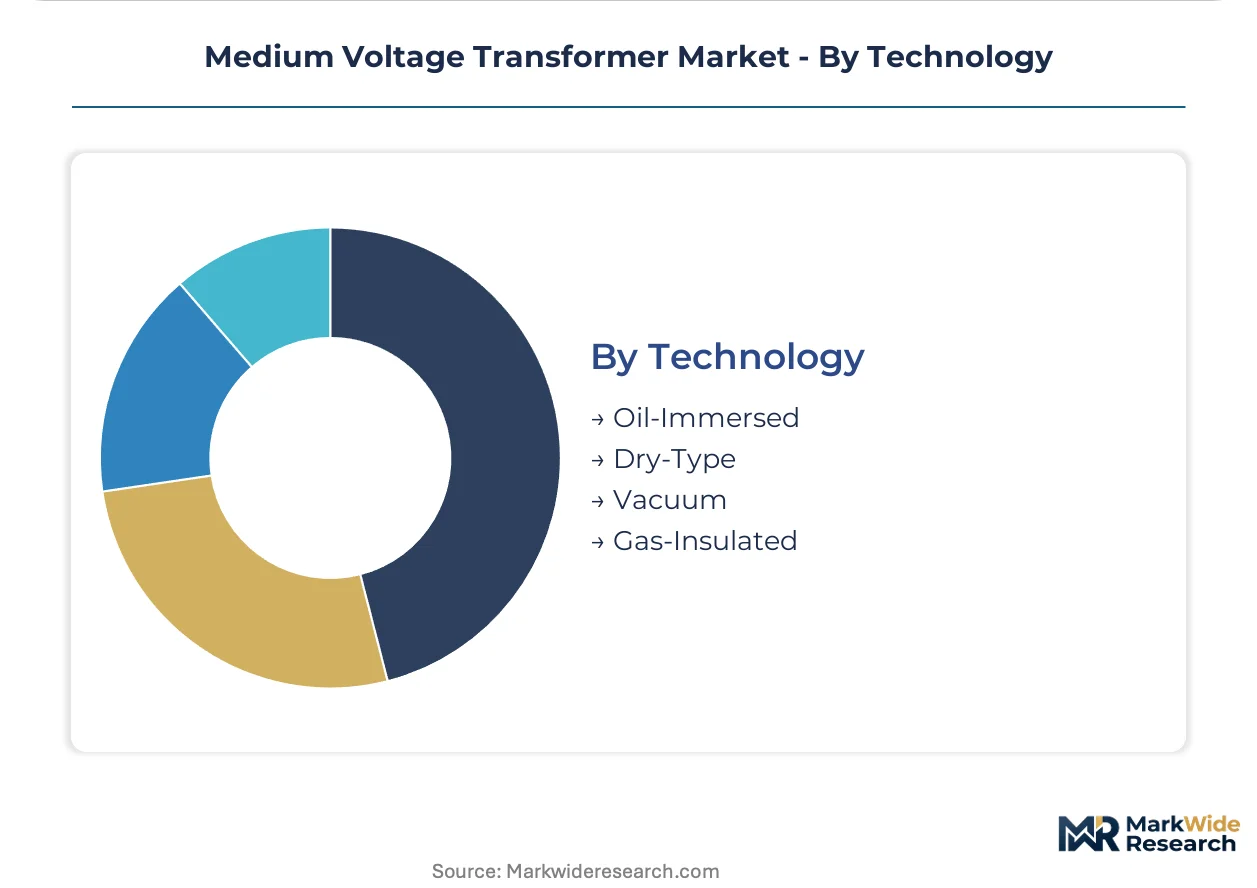
- Oil-Immersed:Mineral oil or natural ester fluid provides superior thermal conductivity and dielectric strength for high-load-cycle applications. EPA polychlorinated biphenyl regulations in the United States accelerate replacement cycles across municipal utility fleets.
- Dry-Type:Cast-resin or vacuum-pressure impregnated insulation eliminates fire and spill risks for indoor commercial and urban underground installations. European Ecodesign directives channel demand toward amorphous-core and high-grade grain-oriented steel variants.
- Vacuum:Interrupter technology penetrates space-constrained substations where maintenance access is limited and environmental containment is mandatory.
- Gas-Insulated:SF6-alternative designs address urban density constraints in Tokyo and Singapore substations with reduced footprint requirements.
Oil-Immersed technology holds the dominant installed base; Dry-Type systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grid modernization trajectories diverge sharply between mature economies prioritizing fleet replacement and emerging markets expanding access networks. Investment intensity in the United States and Germany centers on efficiency upgrades and digital integration, while India and China channel capital toward rural electrification and urban density solutions.
United States
FERC Order 2222 accelerates distributed energy resource integration at substation nodes across Texas and California. EPA polychlorinated biphenyl regulations force early retirement of pre-1979 oil-immersed units in Midwest municipal fleets. Rural electric cooperatives in the Southeast face concentrated compliance burdens as they manage dispersed legacy installations.
Germany
Chemical parks in North Rhine-Westphalia specify cast-resin dry-type technology for indoor electrical rooms where mineral oil is prohibited. EU Ecodesign directives mandate minimum performance indices that channel procurement toward amorphous-core designs. High-rise developments in Frankfurt and Munich drive modular prefabricated substation demand.
India
The Central Electricity Authority procurement targets for rural electrification create volume openings for cost-optimized single-phase distribution transformers. State utilities in Maharashtra and Gujarat deploy compact lightweight constructions for last-mile deployment. Grid expansion in Telangana and Karnataka concentrates three-phase procurement at industrial corridor substations.
China
Dual carbon targets and GB standards enforce efficiency benchmarks that reshape export manufacturing requirements. Yangtze River Delta megacities deploy compact dry-type units in underground substations where space constraints limit conventional oil-filled alternatives. State Grid procurement prioritizes high-grade grain-oriented steel cores for urban network upgrades.
Japan
METI efficiency guidelines drive adoption of vacuum-pressure impregnated insulation in Tokyo commercial high-rises. Underground substations in Osaka and Nagoya deploy gas-insulated designs where fire codes and environmental containment restrict liquid-filled alternatives. Automotive clusters in Aichi Prefecture specify specialized units for manufacturing facility electrical rooms.
Medium Voltage Transformer Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy conglomerates anchoring utility-scale procurement while regional fabricators capture industrial retrofit volumes. The vendor base organizes around three strategic archetypes: full-service power-electronics integrators, dry-type manufacturing specialists, and scale-driven distribution transformer producers. Consolidation pressures concentrate among mid-tier oil-immersed specialists facing stranded-asset risk from environmental regulations. Dominant competitive moves include backward integration into core material supply and technology licensing partnerships for digital monitoring platforms.
Among North American specialists, Hammond Power Solutions and Virginia Transformer Corporation exemplify the dry-type manufacturing archetype, occupying positions in commercial and industrial segments where fire safety codes drive technology selection. Siemens Energy anchors the integrated power-electronics tier, representing the full-service model that extends from hardware supply through lifecycle service contracts. These three companies illustrate how vendor economics shift from transactional equipment sales toward recurring revenue streams anchored by predictive maintenance platforms and long-term utility fleet relationships.
| Leading Market Players |
|---|
| Hammond Power Solutions |
| Virginia Transformer Corporation |
| ELSCO Transformers |
| ABB |
| Siemens Energy |
| Prolec GE Waukesha |
| MGM Transformer Company |
| JSHP Transformer |
| Olsun Electrics |
| Others |
Supply Flow & Price Mechanics
Electromagnetic design engineering scarcity in Europe and North America widens labor-cost differentials between premium-tier amorphous-core units and economy-grade silicon-steel alternatives, compressing mid-market pricing bands as buyers arbitrage specifications across sourcing regions.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard distribution transformers, forcing incumbent OEMs in Germany and the United States to defend margins through digital-service bundling. Pricing stratifies across IEC 60076-20 certified premium tiers, utility-grade standard specifications, and cost-optimized economy units for rural electrification. Cost compression in the economy tier intensifies because Indian CEA procurement mandates favor lightweight single-phase designs with minimized copper mass. Investor-owned utilities in Texas and California exhibit lowest price sensitivity due to FERC Order 2222 integration timelines, while rural electric cooperatives in the US Southeast face acute budget constraints.
Supply Chain Analysis
Direct-to-utility channels handle bulk procurement for grid modernization programs, with distributor networks serving industrial retrofit and commercial replacement volumes. Grain-oriented electrical steel production concentrates in Japan, South Korea, and select European specialty mills, exposing transformer OEMs to allocation constraints during demand surges. Raw material dependencies center on laminated silicon-steel cores, copper winding conductors, and cast-resin epoxy compounds. Single-source vulnerability in amorphous metal ribbon supply constrains rapid scaling of ultra-high-efficiency designs despite IEC 60076-20 tier pull-through.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA polychlorinated biphenyl remediation mandates in the United States create a fifteen-year replacement cycle arbitrage against EU Ecodesign efficiency tiers, rewarding manufacturers with dual-certification capabilities and transatlantic production footprints.
For Market Incumbents: Lock in long-term grain-oriented steel offtake agreements with Japanese and European mills to insulate against input cost volatility during IEC 60076-20 compliance ramps. Prioritize backward integration into amorphous metal core fabrication or captive resin-compounding capacity to defend margin position against dry-type specialists. The stranded-asset risk from pre-1979 oil-immersed fleets accelerates replacement demand but compresses pricing power for conventional technology portfolios. For New Entrants and Emerging Players: Digital-twin-as-a-service platforms offer a channel route around capital-intensive manufacturing scale, enabling predictive-maintenance revenue streams without core-material exposure. Target India's rural electrification procurement schedules for single-phase distribution transformers, where CEA volume mandates and lightweight design specifications favor agile fabricators over integrated conglomerates. Lead with lifecycle service contracts rather than equipment-only positioning to circumvent incumbent utility relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier oil-immersed specialists facing EPA compliance cliffs and limited dry-type transition capabilities. The five-to-ten-year viability window favors targets with established cast-resin manufacturing lines and digital-monitoring platform partnerships. Watch FERC Order 2222 implementation velocity in Texas and California as the inflection signal for distributed energy resource integration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Core Manufacturing Scale-Up | Captures IEC 60076-20 tier premiums as EU Ecodesign mandates tighten efficiency floors. |
| Digital Twin Platform Integration | Extends Siemens Energy's lifecycle service contracts beyond hardware-only utility procurement. |
| Backward Integration into Core Steel Supply | Reduces exposure to Japanese and European grain-oriented electrical steel allocation constraints. |
| Cast-Resin Dry-Type Capacity Expansion | Addresses German chemical park and Japanese high-rise demand where fire codes prohibit mineral oil. |
| India Rural Electrification Partnership | Aligns with CEA single-phase procurement targets for cost-optimized last-mile distribution. |
Methodological Framework
Bottom-up utility and industrial procurement modeling reconciled against top-down transformer manufacturing capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, industrial maintenance directors, OEM procurement teams, and aftermarket service heads were cross-validated against secondary sources including FERC filings, EIA grid infrastructure databases, IEC standard documentation, and SEC 10-K disclosures from listed electrical equipment manufacturers. This triangulation approach ensures demand-side assumptions align with supply-side constraints across voltage class and insulation technology segments.
Historical shipment trendlines by product architecture and end-use segment were projected forward across the modeling period using efficiency-mandate adoption curves and grid-investment cycle analysis. Segmentation dimensions include phase configuration, insulation technology, installation environment, and regional regulatory framework. CAGRs were derived from weighted average of utility capital expenditure forecasts and industrial replacement cycle timing, with specific inputs from FERC Order 2222 implementation schedules and EPA polychlorinated biphenyl retirement deadlines.
Commodity price volatility in electrical steel and copper, regulatory timeline delays, and technology substitution rates for gas-insulated alternatives are the dominant revision risks to the forecast framework. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
Insulator Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Lighting Contactor Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market