
 Phosphate Fertilizers Market | 2026-2036
Phosphate Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphate Fertilizers Market Intelligence
High-purity, low-cadmium phosphate formulations are unwinding the traditional commodity-grade market structure. The Mosaic Company leverages its large-scale production and integrated supply chain to serve key agricultural markets. Office Chérifien des Phosphates (OCP) dominates the global rock phosphate supply, controlling a critical raw material input. Nutrien Ltd. competes through its extensive retail distribution network, offering a broad portfolio directly to farmers.
Phosphate fertilizers are chemical substances containing phosphorus in a form accessible to plants, primarily measured by their phosphorus pentoxide (P2O5) content. They are essential for fundamental plant processes, including energy transfer through ATP, photosynthesis, and the development of roots and seeds. Diammonium Phosphate (DAP) and Monoammonium Phosphate (MAP) constitute the largest product segments due to their high nutrient concentration and water solubility. Application in cereals represents the largest end-use, driven by the crop's significant phosphorus uptake requirements for grain development.
Regulatory frameworks, such as the EU's REACH and new fertilizer regulations limiting cadmium content, directly influence product specifications and market access. In parallel, environmental standards from bodies like the US EPA and China's MEE govern nutrient runoff and production emissions, impacting manufacturing costs. Producers must navigate these divergent environmental and food safety regulations to maintain a competitive position.
Market Dynamics
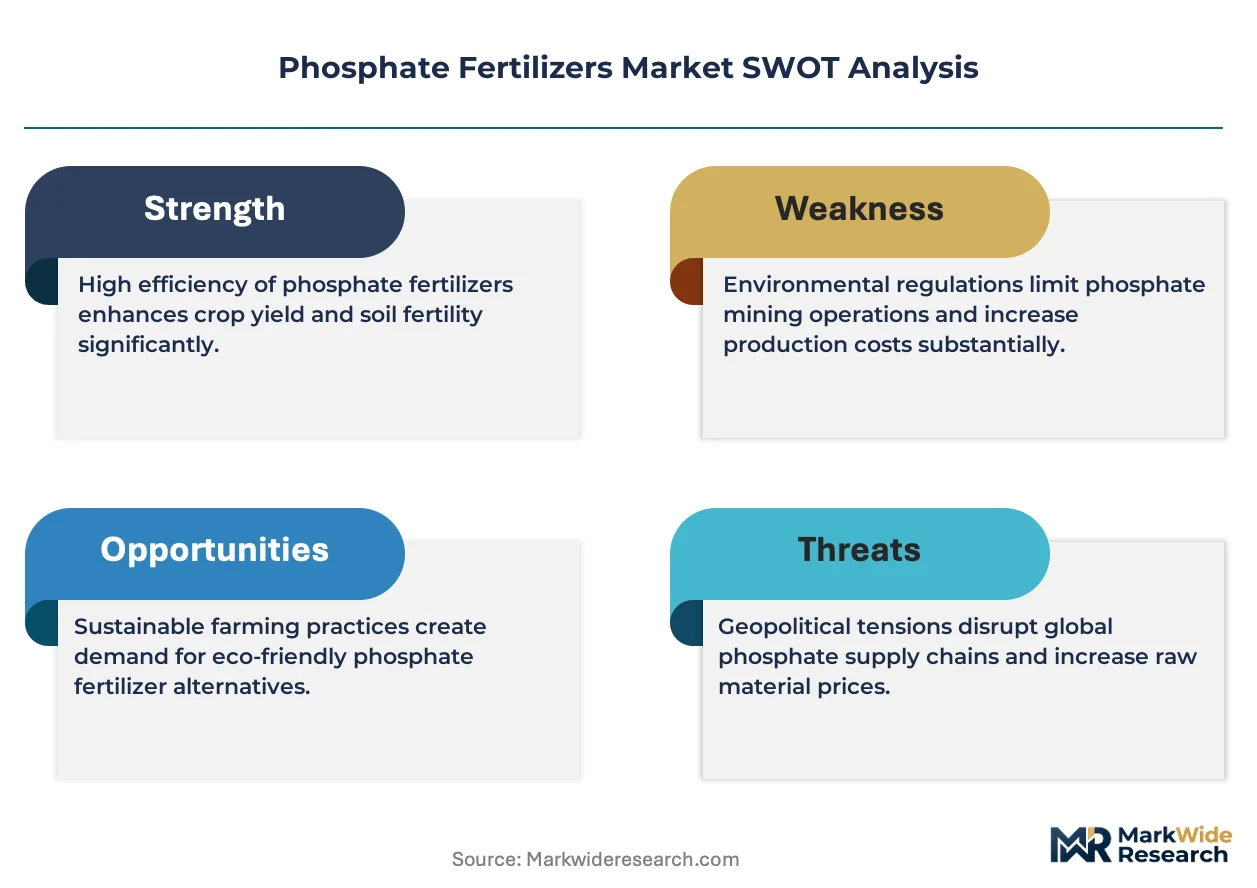
Intensifying regulatory pressure on heavy metal content and nutrient runoff is the central force shaping the phosphate fertilizer market. This creates a fundamental tension between the need for increased agricultural productivity and the demand for environmental compliance.
Growth Catalysts
- Precision Agriculture:Variable rate technology optimizes P2O5 delivery, driving demand for specialized formulations and improving efficiency in large-scale farming.
- Indian Policy Support:Government subsidies in India directly stimulate consumption to enhance food security for staple crops like rice and wheat.
- Cereal Production:Global cultivation of cereals with high phosphorus uptake needs for grain development sustains baseline demand for DAP and MAP.
Market Restraints
- Input Cost Volatility:Price fluctuations in natural gas and sulfur, key phosphoric acid feedstocks, directly impact producer margins and pricing.
- Geopolitical Supply Risk:Heavy concentration of rock phosphate reserves in Morocco creates supply chain vulnerabilities tied to regional stability.
- EU Cadmium Limits:European Union regulations on cadmium content increase processing costs and restrict market access for certain rock sources.
Strategic Opportunities
- Fertigation Systems:Developing high-purity, fully water-soluble phosphates for use in drip irrigation and hydroponics opens new high-value market segments.
- African Market Entry:Addressing severe soil phosphorus deficiencies in Sub-Saharan Africa represents a major long-term volume growth opportunity for producers.
- Microbial Enhancement:Formulating products with phosphate-solubilizing bacteria can increase nutrient bioavailability, offering a clear path for product differentiation.
Industry Challenges
- Capital Intensity:Building new phosphoric acid plants and beneficiation facilities requires massive, long-term capital investment.
- Logistics Management:The global bulk transport of raw materials and finished products presents significant operational and cost hurdles.
- Divergent Regulations:Navigating differing rules on nutrient runoff from bodies like the US EPA and China's MEE complicates global compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphate Fertilizers Market |
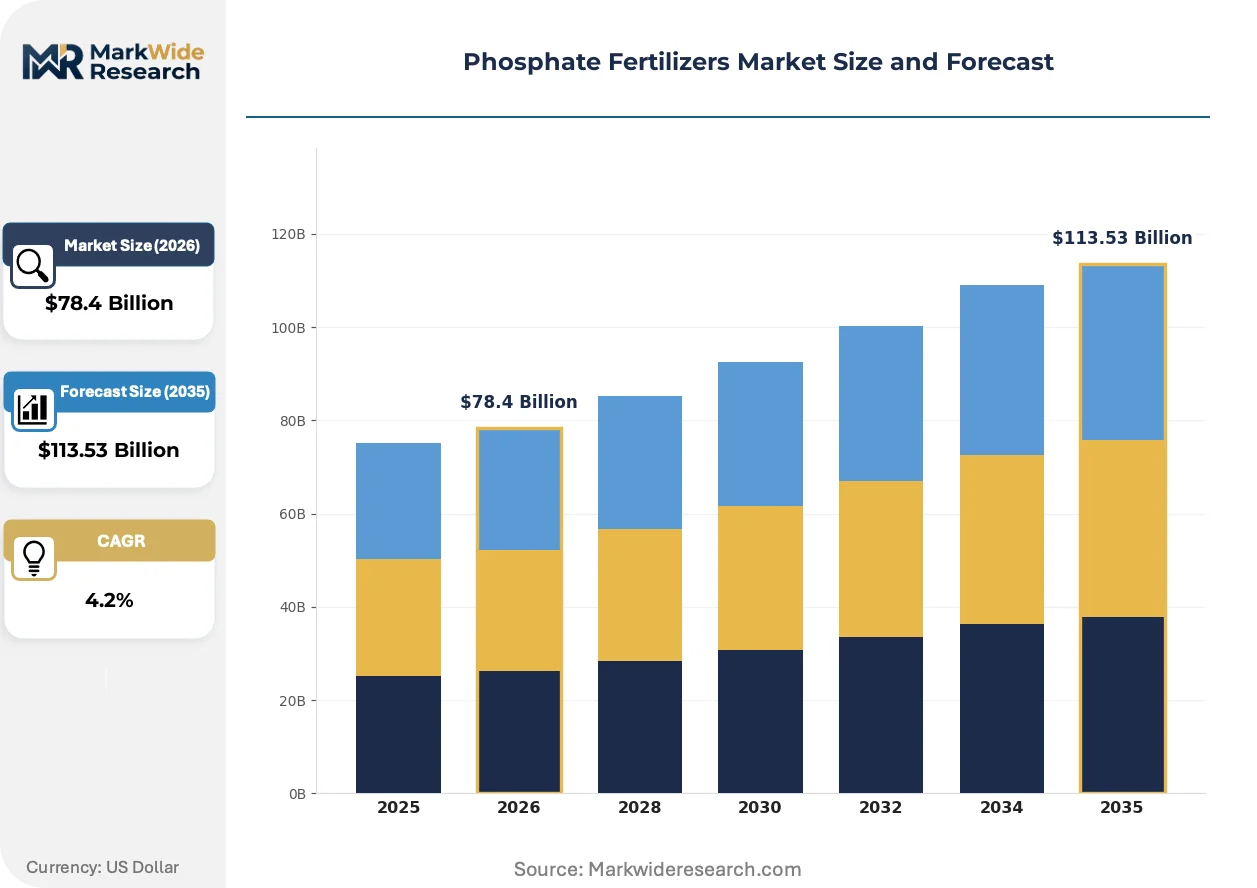
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $113.53 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoammonium Phosphate, Diammonium Phosphate, Superphosphate, Other Phosphates Application: Cereals, Oilseeds, Fruits, Vegetables End User: Agricultural Producers, Horticulturists, Farmers, Crop Producers Packaging Type: Bags, Bulk, Drums, Sacks |
| Companies Covered | Yara International ASA, EuroChem Group AG, Office Chérifien des Phosphates (OCP), CF Industries, Coromandel International Ltd, The Mosaic Company, PhosAgro PJSC, Israel Chemicals Ltd. (ICL), Nutrien Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphate Fertilizers Market Strategic Shifts & Innovations
Product development is shifting from a focus on bulk commodity grades toward specialized, efficient, and environmentally compliant formulations. This evolution is a direct response to agronomic and regulatory demands for more precise nutrient delivery.
Enhanced efficiency fertilizers, including controlled-release and slow-release products, use polymer coatings to meter nutrient availability. Growers of high-value crops are adopting these technologies to maximize nutrient uptake and minimize environmental losses. This development is fragmenting the traditional market for commodity DAP by creating premium, application-specific product tiers.
The European Union’s Fertilizer Products Regulation (FPR) imposes strict new limits on cadmium and other contaminants in phosphate fertilizers. This rule mandates significant investment in purification technologies for producers wishing to access the EU market. Consequently, companies that rely on high-cadmium rock sources face increased processing costs or exclusion from a key agricultural region.
A clear behavioral shift is occurring towards integrated nutrient management plans over single-product purchases. This change favors agronomic service models that bundle soil testing, custom blending, and application support, disrupting traditional distributor channels. The trend is most visible in the precision agriculture sectors of North America and Western Europe.
Phosphate Fertilizers Market Segmentation
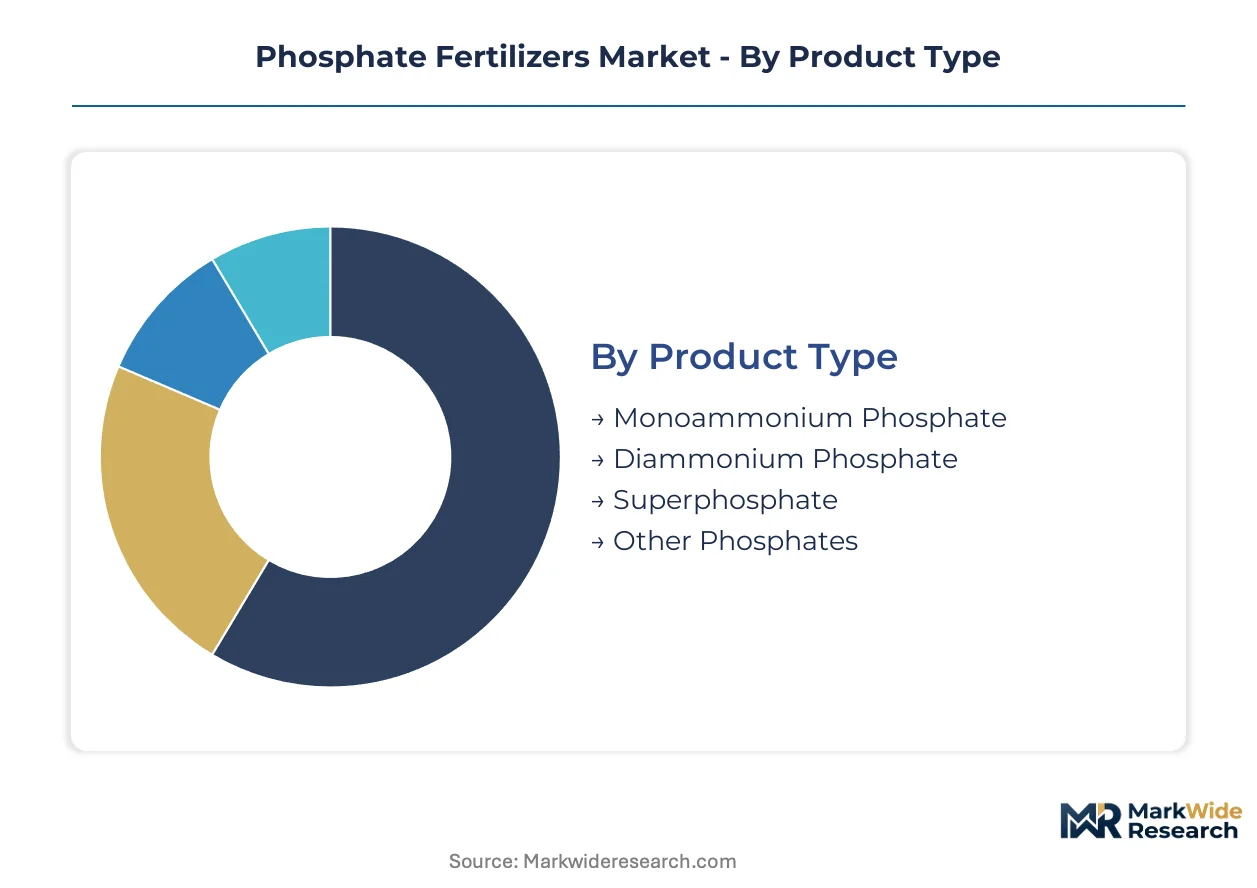
The phosphate fertilizers market segments clarify how different product forms, applications, and user types influence demand dynamics. Understanding these distinctions helps producers tailor offerings to specific agricultural needs and regulatory environments. Market segmentation provides insight into where value is created and how supply chains are structured.
Product Type:
The composition of phosphate fertilizer product types often dictates their suitability for domestic consumption versus export-oriented agricultural economies.
- Monoammonium Phosphate:This product contains a high concentration of phosphorus pentoxide (P2O5) and is fully water-soluble, making it highly efficient for plant uptake. Demand concentrates in regions like India, where precision agriculture technologies optimize nutrient delivery for cereal crops.
- Diammonium Phosphate:Representing the highest concentration of phosphorus and nitrogen, DAP is a widely used granular fertilizer with excellent water solubility. Global cereal production, particularly in large agricultural economies, drives significant demand due to its impact on grain development and yield.
- Superphosphate:This traditional phosphate fertilizer offers a lower P2O5 content compared to ammonium phosphates and is often used for foundational soil enrichment.
- Other Phosphates:This category includes various specialized formulations such as triple superphosphate (TSP) and liquid phosphate fertilizers designed for specific crop requirements or application methods.
Diammonium Phosphate holds the largest share; momentum sits with Monoammonium Phosphate.
Application:
Demand for phosphate fertilizers stratifies across various agricultural applications, reflecting differing crop nutrient requirements and cultivation volumes.
- Cereals:Cereal crops like wheat, rice, and corn have significant phosphorus uptake requirements, especially during early growth and grain development stages. Global food security initiatives and large-scale cultivation sustain a high baseline demand for phosphate fertilizers in this segment.
- Fruits:Fruit cultivation requires precise nutrient management to optimize yield, quality, and fruit development, often utilizing high-purity, water-soluble phosphate formulations. Precision agriculture practices in regions with intensive horticulture drive demand for specialized products.
- Oilseeds:Crops such as soybeans, canola, and sunflower require consistent phosphorus supply to support oil production and overall plant vigor.
- Vegetables:Vegetable growers apply phosphate fertilizers to support root development, flowering, and overall plant health in diverse horticultural systems.
Cereal cultivation drives the largest consumption volume; specialized horticulture applications are expanding quickly.
End User:
End-user segments differentiate by operational scale and agronomic sophistication, influencing product choice and distribution channels.
- Agricultural Producers:These are large-scale commercial farming operations purchasing phosphate fertilizers in significant bulk quantities for extensive crop cultivation. Their demand is driven by maximizing efficiency and yield across vast acreages for commodity crops.
- Farmers:This broad category encompasses a range of farm sizes, from small family farms to medium-sized enterprises, often relying on local distributors for product supply and agronomic advice. Yield optimization and soil health improvements are primary concerns for these users.
- Horticulturists:Specialized growers of fruits, vegetables, and ornamental plants often require customized, high-purity phosphate fertilizers for controlled environments or specific crop cycles.
- Crop Producers:This segment includes any entity involved in growing crops for commercial purposes, spanning various scales and crop types.
Large-scale agricultural producers account for the bulk of demand.
Packaging Type:
The choice of packaging reflects logistical efficiencies and end-user storage capabilities, impacting transport costs and application methods.
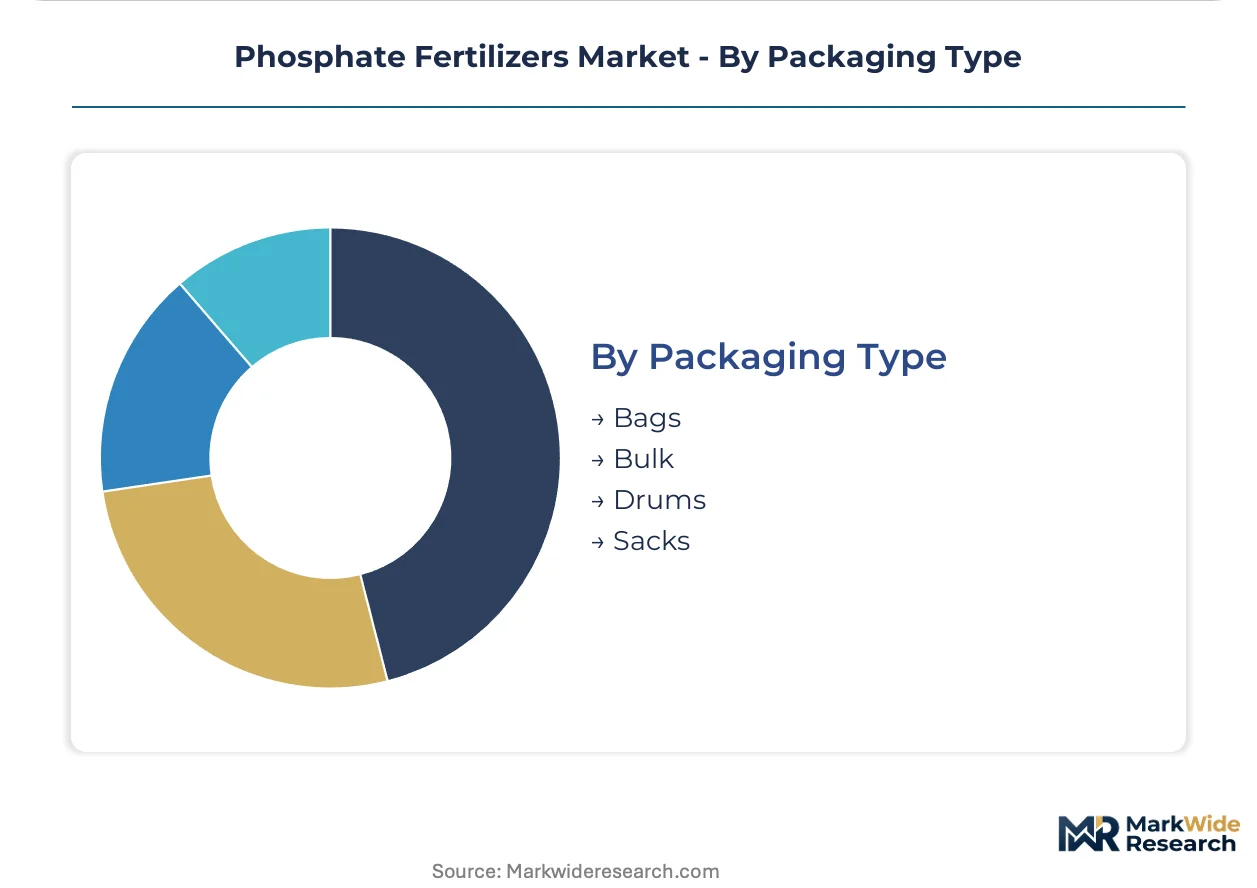
- Bulk:Phosphate fertilizers transported and stored in bulk quantities are typically destined for large commercial farms or blending facilities. This method minimizes packaging costs and facilitates efficient handling for large-scale application.
- Bags:Fertilizers packaged in bags offer convenience for smaller farms, retail distribution, and situations requiring easier manual handling and storage. This format supports diverse customer bases and varied application scales.
- Drums:Drums are primarily used for liquid phosphate formulations or highly specialized products, ensuring secure transport and precise dispensing.
- Sacks:Similar to bags but often larger, sacks provide a balance between bulk efficiency and manageable unit sizes for a range of agricultural operations.
Bulk packaging dominates for large-scale operations; bags serve a broader customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global phosphate fertilizer trade balances between major producing and consuming nations. Key agricultural economies often rely on imports to meet domestic food security goals. Export-oriented countries leverage abundant raw materials for international supply.
India
India exhibits substantial demand for phosphate fertilizers, driven by its expansive cereal production and food security initiatives. Government subsidies directly stimulate consumption to enhance agricultural output for staple crops. Large agricultural regions like Punjab and Uttar Pradesh concentrate significant fertilizer application. This supports intensive cultivation practices across the country.
United States
Commercial farming operations in the United States require large volumes of phosphate fertilizers for commodity crops. The US EPA governs nutrient runoff, impacting manufacturing costs and application methods. Midwest agricultural states like Iowa and Illinois widely adopt precision agriculture technologies. This optimizes P2O5 delivery across vast acreages.
Brazil
Brazil's expansive agricultural sector, particularly for soybeans and corn, sustains significant phosphate fertilizer demand. Environmental regulations influence sustainable farming practices and fertilizer application methods. States such as Mato Grosso and Goiás represent major agricultural hubs. These regions drive high consumption volumes for crop development.
China
China's vast cereal production and ongoing soil enrichment programs generate considerable phosphate fertilizer demand. The MEE sets environmental standards for production emissions and nutrient runoff, influencing manufacturing processes. Shandong and Sichuan provinces are major agricultural areas. These regions demonstrate high fertilizer consumption for staple crops.
Morocco
Morocco dominates the global rock phosphate supply, controlling a critical raw material input for phosphate fertilizers. National policies prioritize the extraction and export of these vital resources. The Khouribga and Gantour basins are central to the country's phosphate mining operations. This position anchors Morocco's influence in the global market.
Phosphate Fertilizers Market Key Industry Players
Listed leaders compete with private specialists across the global phosphate fertilizer market. The market structure exhibits consolidation among large-scale producers, while niche players address specialized formulations. Archetypes include integrated raw material suppliers, diversified agricultural input providers, and regional manufacturers focusing on specific crop needs. Dominant competitive moves involve capacity expansion and strategic partnerships for technology development.
Office Chérifien des Phosphates (OCP) exemplifies the integrated raw material supplier archetype, leveraging its dominant position in global rock phosphate reserves. The Mosaic Company occupies a similar position as a large-scale producer with an integrated supply chain, serving key agricultural markets. Nutrien Ltd. represents the diversified agricultural input provider, offering a broad portfolio directly to farmers through an extensive retail distribution network. These entities anchor different segments of the value chain, driving innovation and market access strategies.
| Leading Market Players |
|---|
| Yara International ASA |
| EuroChem Group AG |
| Office Chérifien des Phosphates (OCP) |
| CF Industries |
| Coromandel International Ltd |
| The Mosaic Company |
| PhosAgro PJSC |
| Israel Chemicals Ltd. (ICL) |
| Nutrien Ltd |
| Others |
Cost & Logistics Intelligence
High-purity phosphate formulations, substituting traditional commodity grades, simultaneously reshape supply geography and pricing economics by demanding specialized raw materials and processing.
Pricing Analysis
Agricultural producers anchor contract-based long-term offtake agreements for bulk phosphate fertilizers. Price differentiation stems from P2O5 content purity and application-specific formulation. Input cost volatility from natural gas and sulfur feedstocks creates margin compression for producers. Large-scale agricultural producers exhibit high price sensitivity, while horticulturists prioritize specialized product performance.
Supply Chain Analysis
Strategic stockpiling of raw materials and finished products is common due to bulk transport logistics and geopolitical risks. Global supply concentration centers on Morocco for rock phosphate, with significant production also in China and the United States. The market relies on rock phosphate, natural gas, and sulfur as primary inputs, creating single-source vulnerability from Morocco's dominance. Distribution runs through local distributors for smaller farmers and direct sales channels for large agricultural producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phosphate fertilizers market presents an early-cycle expansion story, driven by increasing penetration of precision agriculture technologies optimizing nutrient delivery. Significant opportunities exist for volume growth in underpenetrated agricultural regions.
For Market Incumbents: Shield core market share by investing heavily in purification technologies to meet evolving cadmium limits, mitigating regulatory threats. Expand capacity for high-purity, water-soluble formulations to counter fragmentation from enhanced efficiency fertilizers. Leverage vertical integration into rock phosphate supply chains to stabilize input costs. Control distribution channels directly to large agricultural producers.
For New Entrants and Emerging Players: Lead with differentiated products addressing specific agronomic needs, targeting the underpenetrated Sub-Saharan African market for long-term volume growth. Develop high-purity, water-soluble phosphates for fertigation systems in high-value horticulture as a white-space opportunity. A go-to-market angle involves bundling soil testing with custom blending services to disrupt traditional distributor channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional manufacturers focusing on specific crop needs and specialized formulation providers. This market demonstrates long-term viability over the next decade, underpinned by global food security imperatives. Target acquisition archetypes include companies with proprietary low-cadmium purification technologies or established distribution in high-growth regions like India. The signal to watch is an uptick in strategic partnerships for microbial enhancement technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding low-cadmium production capacity secures market access in regions with strict regulatory frameworks like the EU. |
| Green Manufacturing Transition | Adopting sustainable production processes addresses environmental standards from bodies like the US EPA, reducing long-term operational risks. |
| Long-term Supply Agreement | Securing multi-year rock phosphate supply agreements mitigates geopolitical supply risk from concentrated reserves in Morocco. |
| Joint Venture | Collaborating on microbial enhancement technologies accelerates product differentiation, improving nutrient bioavailability for diverse crop requirements. |
| Distribution Channel Expansion | Building out distribution networks in Sub-Saharan Africa captures long-term volume growth opportunities addressing severe soil phosphorus deficiencies. |
Research Approach
The analysis maps phosphate fertilizer product types, application segments, and end-user categories, each validated through primary interviews with plant managers, procurement leads, and agronomists. Secondary validation utilized customs data, government agricultural reports, and environmental agency publications. This approach combined bottom-up market sizing with top-down triangulation across all identified segments.
Market outputs were validated against historical growth trends and external regulatory impact assessments. The analytical framework integrated supply-demand models across the analysis window. Modeled segmentation dimensions included product type, application, end-user, and regional regulatory environment. Compound annual growth rates were derived from historical data and projected inputs like crop acreage and government subsidies.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material price volatility. Forecasts reflect these assumptions, but new environmental regulations also pose a risk. Revision becomes warranted when raw material prices or major regulatory changes cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Micronutrient Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Fertilizer Tester Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Chelate Fertilizer Market