
 Vegetable Chutney Market | 2026-2036
Vegetable Chutney Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Chutney Market Analysis
Organic and non-GMO certification cycles are redrawing competitive boundaries in the vegetable chutney sector. The Virginia Chutney Company leverages its Appalachian sourcing network to sustain premium positioning in specialty retail. Patak's anchors its portfolio through deep British-Indian recipe heritage and broad supermarket penetration across the United Kingdom.
Vegetable chutney denotes a cooked or raw condiment prepared from chopped vegetables, vinegar or citrus, sugar, and spice blends, typically processed to a pH below 4.6 for ambient shelf stability and employed to add acidity, heat, or sweetness to prepared dishes. The ingredient dimension shows tomato-based formulations dominating volume due to year-round raw material availability, while mixed-vegetable variants capture faster growth in health-positioned retail. Pouch packaging is displacing glass jars in foodservice channels where portion control and reduced shipping weight command priority.
FDA acidified food regulations and EFSA food additive frameworks govern permissible preservatives and labeling claims, directly influencing which formulations qualify for clean-label positioning in North American and European retail. India's FSSAI mandates nutritional disclosure and manufacturing facility licensing, tightening market access for unorganized producers. Stakeholders must monitor evolving sodium and added-sugar thresholds across multiple jurisdictions to anticipate reformulation requirements and preserve shelf placement.
Market Dynamics
Clean-label mandates from FDA and EFSA are forcing wholesale reformulation of vegetable chutney recipes, compressing permissible preservative palettes and elevating acidification costs for ambient-stable products.
Growth Catalysts
- Restaurant chain expansion:North American and European foodservice operators are broadening chutney SKUs on limited-service and full-service menus, creating pull-through demand for bulk formats and portion-controlled packaging.
- FSSAI facility licensing:India's tightening manufacturing standards are consolidating unorganized production into licensed processing clusters, improving quality consistency and export-readiness for value-added vegetable chutneys.
- Pouch packaging migration:Lightweight flexible formats are displacing glass in foodservice channels, cutting shipping weights and enabling single-serve portion control for institutional buyers.
Market Restraints
- Tomato input volatility:Year-round availability masks price swings from climate stress in Andhra Pradesh and California processing tomato belts, squeezing margin predictability for volume producers.
- Acidification compliance costs:FDA acidified food regulations mandate pH monitoring and process filing for shelf-stable formulations, raising fixed costs for small-batch entrants.
- Fresh condiment substitution:Refrigerated salsa and refrigerated pickle segments capture health-positioned consumers seeking minimal processing, pressuring ambient chutney growth in premium retail.
Strategic Opportunities
- Urban Indian retail penetration:Organized grocery expansion in Bengaluru, Mumbai, and Delhi NCR creates shelf space for branded chutney SKUs previously confined to traditional trade.
- EU organic certification:EFSA-aligned organic standards open premium positioning in German and French retail, rewarding Appalachian and Himalayan sourcing networks with clean-label narratives.
- E-commerce direct-to-pantry:Subscription and specialty food platforms bypass conventional distributor markups, enabling artisan chutney makers to capture full margin on heritage recipes.
Industry Challenges
- Acidified food process authority:FDA requires trained process authorities to validate pH control methods, creating talent scarcity as food science programs lag chutney-specific thermal processing expertise.
- Clean-label reformulation cycles:Removing potassium sorbate and sodium benzoate while maintaining shelf stability demands extended R&D timelines, compressing product refresh cadence against private label speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Chutney Market |
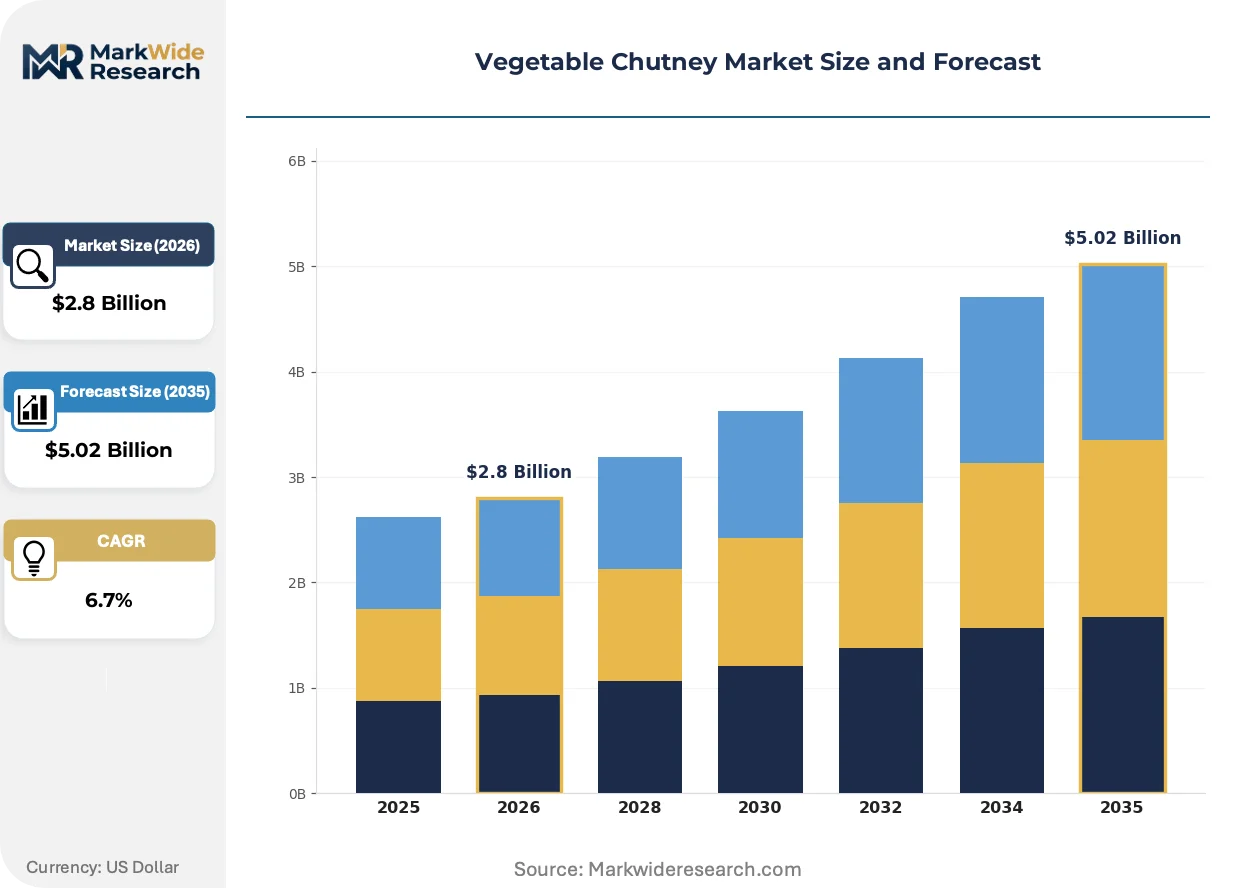
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Chutney, Spicy Chutney, Savory Chutney, Tangy Chutney Ingredient Type: Tomato, Mango, Mixed Vegetables, Coriander Packaging Type: Bottle, Jar, Pouch, Tub Distribution Channel: Online Store, Supermarket, Specialty Store, Local Market |
| Companies Covered | The Virginia Chutney Company, The Brooklyn Delhi, Stonewall Kitchen, Wild Thymes Farm, Swad, Patak's, Sukhi's Indian Food, Busha Browne Company, Priya Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Chutney Market Emerging Trajectories
Processing technology and packaging format evolution are redrawing cost structures and shelf-positioning rules across vegetable chutney production, with regulatory compliance costs now embedded in capital planning.
High-pressure processing is fragmenting traditional thermal pasteurization's dominance in premium vegetable chutney segments. Cold-pressed chutney producers in California and Maharashtra are adopting HPP to preserve raw flavor profiles and extend refrigerated shelf life. This technology is fragmenting the market into pasteurized-ambient and cold-chain-refrigerated tiers with diverging margin structures.
EFSA food additive frameworks are tightening permissible preservative lists across European retail, directly constraining benzoate and sorbate deployment in tomato-based formulations. Manufacturers are responding with accelerated vinegar and citrus acidification programs that meet pH thresholds without synthetic preservatives. German and Dutch supermarket chains are now demanding full ingredient transparency that exceeds baseline EU labeling requirements.
Foodservice procurement is consolidating chutney purchasing through broadline distributors with private-label capabilities, compressing branded supplier margins. Institutional buyers in US K-12 and healthcare channels are shifting from jarred formats to portion cups and squeeze pouches that reduce waste and labor. This pattern is most visible in Texas and Florida school districts where commodity programs now specify chutney as a vegetable crediting option.
Vegetable Chutney Market Segmentation
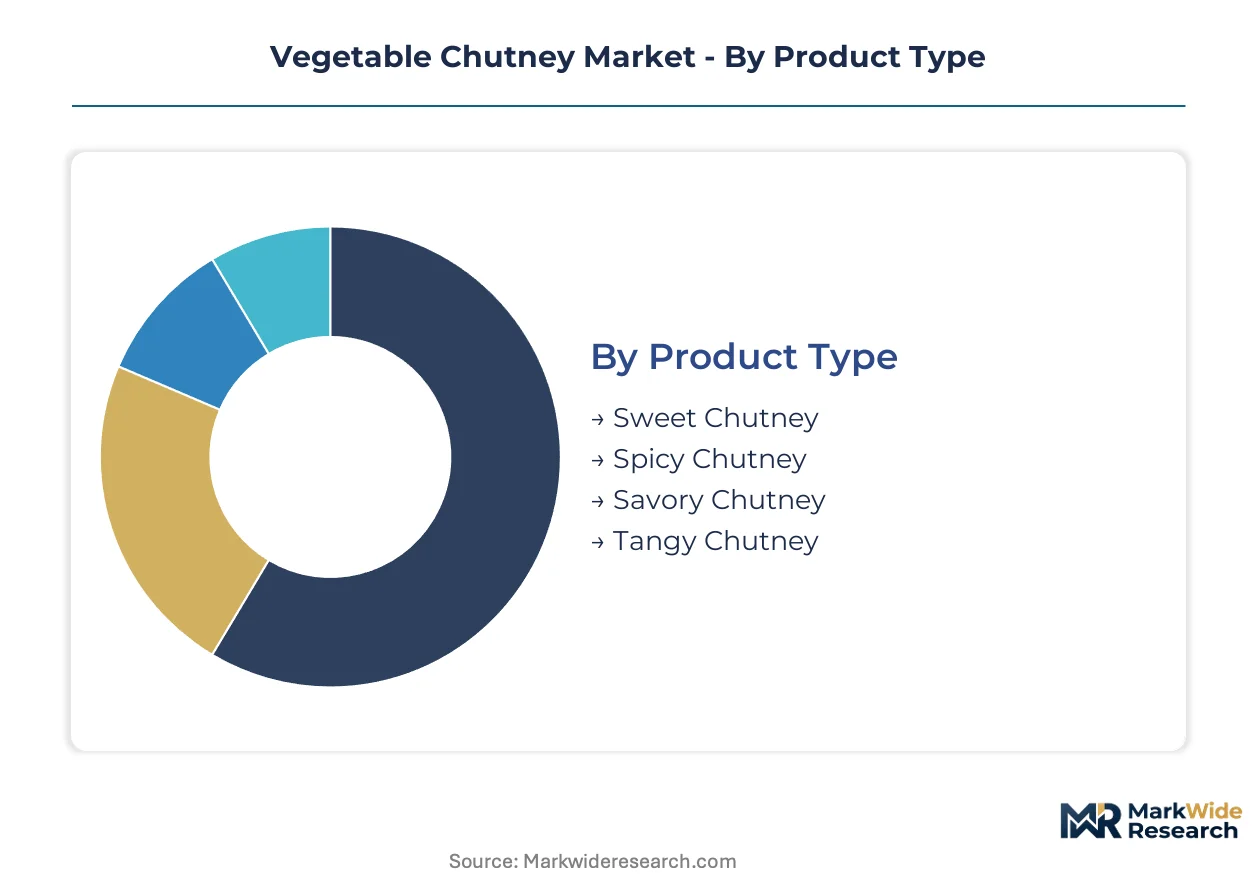
Vegetable chutney segmentation reveals how flavor positioning, ingredient sourcing, and packaging economics split demand across retail and foodservice channels. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio strategy.
Product Type:
Sweet chutney dominates domestic consumption across Indian households and diaspora communities, while spicy variants anchor export-led growth into North American and European specialty retail.
- Sweet Chutney:Formulated from jaggery or cane sugar bases with tamarind or date pulp, achieving pH stability through natural acidification. Concentrated demand in Mumbai, Delhi NCR, and Chennai household pantries where traditional meal accompaniment drives repeat purchase frequency.
- Spicy Chutney:Chili-forward profiles with Scoville-calibrated heat levels, processed under FDA acidified food regulations for shelf-stable export. Restaurant chains in Texas and Florida specify bulk formats for fusion menu applications, creating pull-through from institutional procurement.
- Savory Chutney:Umami-dense formulations incorporating fermented vegetable bases, gaining traction in German and Dutch clean-label retail as sodium-reduced alternatives.
- Tangy Chutney:Citrus and vinegar-forward acidity profiles targeting health-positioned consumers seeking minimal preservative content.
Sweet chutney holds the largest share; momentum sits with spicy chutney as export channels expand.
Ingredient Type:
Cost tier stratification separates commodity tomato bases from premium mixed-vegetable positioning, with sourcing geography determining margin capture.
- Tomato:Year-round processing tomato supply from Andhra Pradesh and California Central Valley enables volume production at compressed cost structures. Price volatility from climate stress in both belts squeezes margin predictability for ambient-stable formulations.
- Mango:Seasonal Alphonso and Kesar pulp availability from Maharashtra and Gujarat creates supply-constrained premium positioning. Export demand from UK and Gulf Cooperation Council markets concentrates during harvest windows, requiring inventory build strategies.
- Mixed Vegetables:Carrot, beetroot, and bell pepper combinations commanding health-premium positioning in French and German organic retail, climbing the fastest as EFSA-aligned certification expands addressable shelf space.
- Coriander:Fresh herb-based raw formulations with limited thermal processing, targeting refrigerated premium segments in California and Maharashtra metro markets.
Tomato commands volume leadership; mixed vegetables are expanding most quickly on clean-label premiums.
Packaging Type:
Customer type divergence splits household pantry stock-up behavior from foodservice portion-control requirements, with format selection directly determining shipping economics.
- Bottle:PET and glass formats dominating Indian urban retail and export supermarket placement, with FSSAI-mandated nutritional labeling real estate driving label size specifications.
- Jar:Traditional glass preserving heritage positioning in UK specialty retail and US farmers market channels, though shipping weight disadvantages pressure share.
- Pouch:Flexible laminate formats displacing glass in Texas and Florida school district commodity programs, cutting shipping weights and enabling single-serve portion control for institutional buyers.
- Tub:Refrigerated deli-style containers targeting foodservice bulk dispensing and European retail fresh condiment adjacencies.
Bottle formats retain the largest share; pouches gain share fastest on foodservice procurement consolidation.
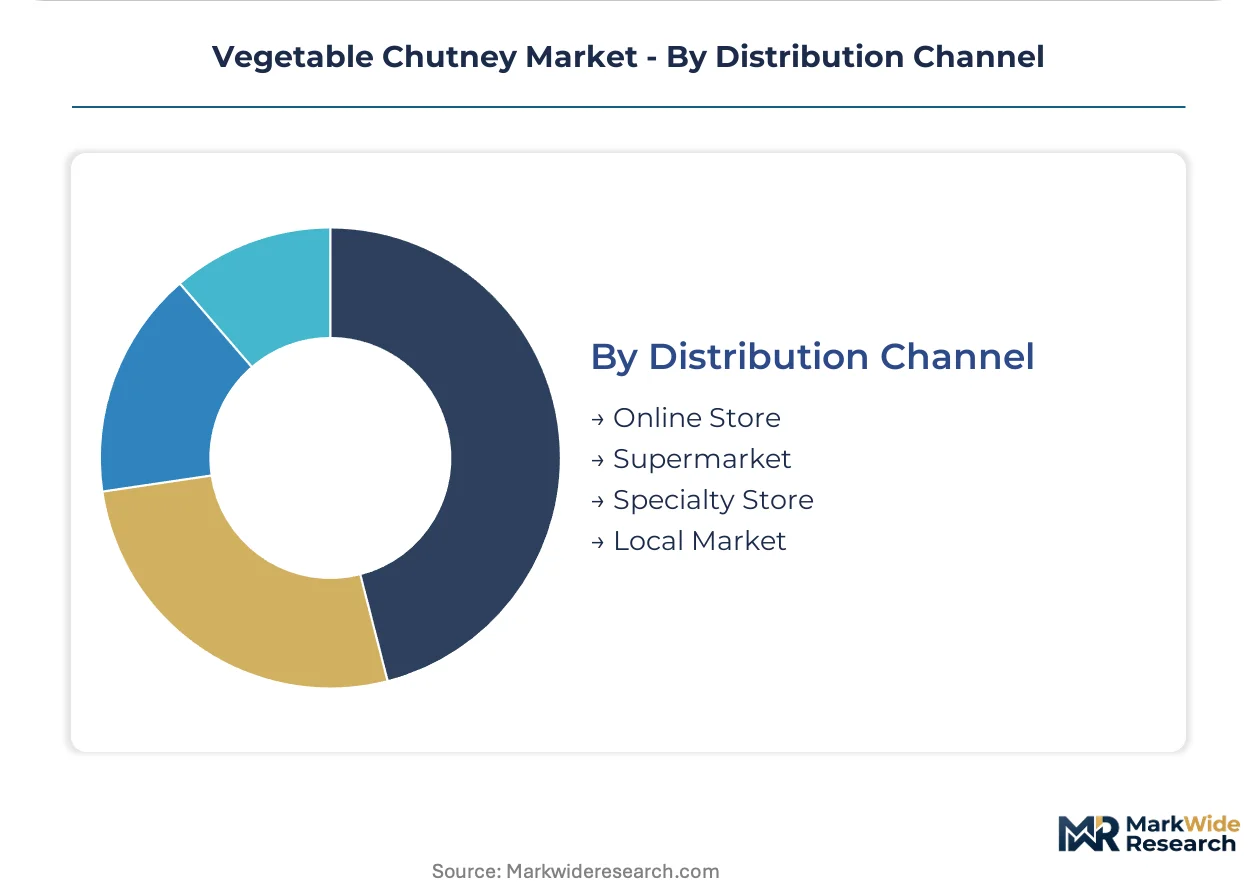
Distribution Channel:
Supply concentration in organized retail clusters versus fragmented traditional trade determines brand building investment requirements and margin capture.
- Online Store:Subscription and specialty food platforms enabling direct-to-pantry distribution, bypassing conventional distributor markups for heritage recipe artisans.
- Supermarket:Organized grocery expansion in Bengaluru, Mumbai, and Delhi NCR creating branded SKU shelf space previously confined to traditional trade, with planogram negotiations determining visibility.
- Specialty Store:Ethnic grocery and gourmet food retailers in UK and US metropolitan areas commanding premium positioning for Appalachian and Himalayan sourcing narratives.
- Local Market:Unorganized traditional trade in Indian tier-2 and tier-3 cities, facing consolidation pressure from FSSAI facility licensing requirements.
Supermarket channels hold the largest share; online stores show steepest expansion trajectory as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export incentive programs and facility licensing mandates are reshaping production geography across major vegetable chutney manufacturing clusters. Regulatory tightening in developed markets is filtering trade flows toward certified processing hubs.
United States
Restaurant chain procurement in Texas and Florida drives institutional demand for bulk chutney formats. FDA acidified food regulations mandate pH monitoring and process authority validation for shelf-stable imports. California's Central Valley processing tomato belt supplies raw material to ambient-stable formulation plants near Sacramento.
India
Urban organized retail expansion in Mumbai, Bengaluru, and Delhi NCR creates branded SKU shelf space previously confined to traditional trade. FSSAI manufacturing facility licensing consolidates unorganized production into licensed processing clusters. Maharashtra's Alphonso and Kesar mango harvests concentrate export-oriented pulp processing near Ratnagiri.
United Kingdom
Supermarket private-label penetration and British-Indian recipe heritage sustain premium positioning for ethnic condiment ranges. EFSA food additive frameworks constrain benzoate and sorbate deployment in tomato-based formulations. West Midlands packaging hubs service both domestic retail and re-export channels into Continental Europe.
Germany
Clean-label retail demands exceed baseline EU labeling requirements across German supermarket chains. EFSA-aligned organic certification opens premium shelf space for Appalachian and Himalayan sourcing narratives. Hamburg and Rotterdam port logistics clusters handle bulk import and distribution into Central European markets.
Netherlands
Foodservice procurement consolidation through broadline distributors creates volume demand for portion-controlled flexible packaging. EFSA preservative tightening accelerates vinegar and citrus acidification programs. Rotterdam's re-export infrastructure positions Dutch handlers as distribution gateways for ambient chutney entering Continental and Nordic markets.
Vegetable Chutney Market Vendor Landscape
Player mix skews toward heritage recipe artisans and regional sauce specialists rather than multinational condiment conglomerates. Market structure remains fragmented across geographic taste preferences, with limited cross-border brand concentration. Two strategic archetypes dominate: Appalachian and Himalayan sourcing networks leveraging clean-label narratives, and British-Indian recipe heritage houses with deep supermarket penetration. Competitive moves center on organic certification acquisition and foodservice format innovation.
Within the heritage-positioned tier, The Virginia Chutney Company and Patak's occupy distinct geographic anchoring positions. The Virginia Chutney Company exemplifies Appalachian sourcing network leverage for premium specialty retail placement. Patak's represents British-Indian recipe heritage consolidation across UK supermarket channels. The Brooklyn Delhi and Stonewall Kitchen sit within the artisan-scale segment, with Brooklyn Delhi signaling urban craft positioning and Stonewall Kitchen indicating New England specialty food corridor concentration.
| Leading Market Players |
|---|
| The Virginia Chutney Company |
| The Brooklyn Delhi |
| Stonewall Kitchen |
| Wild Thymes Farm |
| Swad |
| Patak's |
| Sukhi's Indian Food |
| Busha Browne Company |
| Priya Foods |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Andhra Pradesh tomato processors and North American foodservice distributors lock in both raw material access and eighteen-month price visibility against climate-driven harvest volatility. These arrangements compress spot market exposure while embedding acidification compliance costs into baseline pricing structures.
Pricing Analysis
Certification level creates the primary spread between FSSAI-licensed export-grade production and unorganized domestic supply. Three-tier pricing structure across premium organic, standard licensed, and economy traditional tiers reflects EFSA-aligned clean-label premiums versus commodity positioning. Pricing pressure stems from refrigerated salsa substitution in US premium retail, squeezing ambient chutney margins. Foodservice buyers exhibit highest price sensitivity due to broadline distributor consolidation, while UK specialty retail shows lowest sensitivity on heritage recipe positioning.
Supply Chain Analysis
India and the United States anchor vegetable chutney manufacturing through complementary processing clusters. India draws from Maharashtra mango pulp and Andhra Pradesh tomato concentrate, while California Central Valley feeds Sacramento-area formulation plants. Raw material dependencies rest on seasonal Alphonso harvests and year-round processing tomato supply. Single-source vulnerability concentrates in Maharashtra's monsoon-exposed mango belt. Distribution runs through organized retail chains in Mumbai and Bengaluru, plus broadline foodservice distributors in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained process authority scarcity under FDA acidified food regulations constrains formulation innovation velocity, creating competitive moats for incumbents with established food science capabilities.
For Market Incumbents: Compound certification advantages by accelerating EFSA organic acquisition for German and French retail penetration. Deepen backward integration into Appalachian and Himalayan sourcing networks to secure clean-label narrative control against private label replication. Defensive priority rests on locking pouch packaging capacity ahead of Texas and Florida school district procurement waves. For New Entrants and Emerging Players: Differentiate on cold-pressed HPP technology to capture California and Maharashtra refrigerated premium segments underserved by ambient-stable incumbents. White-space targets include direct-to-pantry subscription models bypassing distributor markups, and coriander-based raw formulations for health-positioned urban Indian households. Go-to-market angle should leverage e-commerce platform infrastructure to capture full margin on heritage recipes. For Investors and Strategic Acquirers: Heritage-recipe artisans with established Appalachian sourcing networks represent the most defensible acquisition profile. Long-term viability frames around clean-label certification durability and foodservice format innovation capacity. Signal to watch is FSSAI enforcement intensity consolidating unorganized production into licensable assets.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acquisition | EFSA-aligned standards unlock premium shelf space in German and Dutch retail chains. |
| Pouch Packaging Migration | Flexible formats cut shipping weights for Texas and Florida institutional procurement programs. |
| Backward Integration into Sourcing | Appalachian and Himalayan networks secure clean-label ingredient traceability narratives. |
| HPP Technology Adoption | Cold-pressed processing preserves raw flavor profiles for California refrigerated premium segments. |
| E-commerce Direct-to-Pantry Launch | Subscription platforms bypass conventional distributor markups for heritage recipe artisans. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FSSAI facility licensing records, FDA acidified food process filings, and EFSA food additive framework updates. Primary interviews engaged processing plant managers at Andhra Pradesh and Maharashtra clusters, category buyers at Bengaluru and Mumbai organized retail chains, procurement officers at Texas and Florida school district commodity programs, and regulatory affairs leads navigating FDA process authority requirements. Secondary validation drew from customs export data, supermarket planogram audit records, and foodservice distributor contract disclosures. Bottom-up production capacity modeling triangulated against top-down consumption estimates across the analysis window.
Segmentation dimensions modeled include product type stratification across sweet, spicy, savory, and tangy formulations; ingredient sourcing tier from commodity tomato through premium mixed-vegetable positioning; packaging format evolution from glass jar through flexible pouch; and distribution channel split between organized retail, traditional trade, and direct-to-pantry e-commerce. CAGRs derived from trend extrapolation of urban Indian retail expansion rates, foodservice SKU broadening patterns, and clean-label certification adoption curves. Industry-specific inputs incorporated acidification cost trajectories under FDA compliance and EFSA preservative tightening schedules.
The analysis sits within stated boundaries; outcomes outside sustained FSSAI enforcement intensity, stable tomato input pricing, or continued restaurant chain chutney menu expansion would require recalibration. Forecasts reflect assumptions on regulatory compliance cost pass-through and foodservice format innovation adoption. Recalibration cycles align with material shifts in FDA process authority availability, EFSA additive framework revisions, and climate stress patterns in Andhra Pradesh and California processing belts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Global Mushroom Market
Vegetables
IQF Vegetables Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Yams Market
Vegetables
Ghana Fruit and Vegetable Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Yarrow Market
Vegetables
Peas Market
Vegetables
Vegetable Grader Market
Vegetables
Spain Greenhouse Horticulture Market
Vegetables
Sprouts Market
Vegetables
Dried Vegetable Market
Vegetables
Dried Mushroom Market
Vegetables
South America Peas Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Dehydrated Vegetables Market