
 Global Micronutrient Fertilizer Market | 2026-2036
Global Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micronutrient Fertilizer Market Foresight
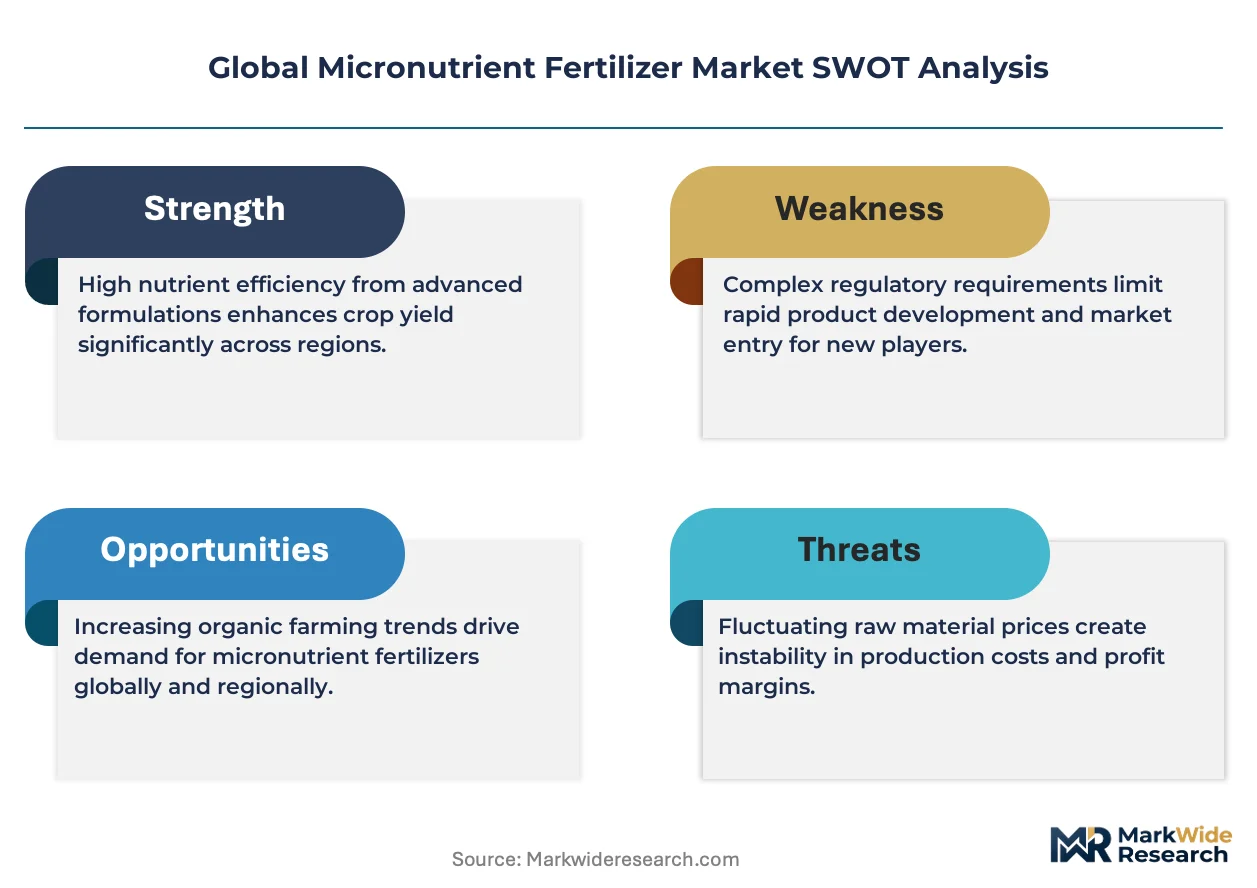
Consolidation among large-scale farm operators and greenhouse consortia is expanding the addressable base for precision micronutrient applications. Yara International ASA leverages its controlled-release coating technology to sustain premium positioning in liquid micronutrient formulations across Nordic and North American distribution channels. The Mosaic Company anchors its competitive stance through captive phosphate-micronutrient blending capacity and deep backward integration into mining assets. ICL Group Ltd differentiates via specialty water-soluble micronutrient compounds tailored for fertigation systems in protected agriculture.
Micronutrient fertilizers deliver essential trace elements—iron, zinc, manganese, copper, boron, and molybdenum—in quantities typically measured in grams per hectare to correct plant physiological disorders and optimize enzymatic functions. These products are manufactured through acidulation of ores, chelation with EDTA or lignosulfonate carriers, or crystallization into water-soluble salts for foliar and soil application. Zinc and boron formulations generate the deepest margin pools due to acute deficiency prevalence in calcareous soils and high replacement frequency in intensive cereal rotations. Liquid and chelated forms are capturing disproportionate growth as drip irrigation and drone-based foliar spraying displace traditional granular broadcasting in precision agriculture systems.
The EPA governs micronutrient product registration and label claims under FIFRA in the United States, while REACH and the EU Fertilizing Products Regulation impose strict contaminant limits and biodegradability criteria on chelating agents sold across European member states. China's MEE enforces discharge standards on micronutrient manufacturing facilities under dual carbon goals, elevating compliance costs for sulfate-based processes. India's FSSAI and state-level agriculture departments coordinate soil health card distribution that directly recommends micronutrient doses, creating institutional demand pull. Stakeholders must monitor evolving chelation chemistry standards and carbon-intensity benchmarks to preserve market access across jurisdictions.
Market Dynamics
Precision agriculture systems are compressing application windows and demanding micronutrient formulations compatible with variable-rate equipment and fertigation infrastructure, forcing manufacturers to reformulate granular products into liquid and water-soluble salts.
Growth Catalysts
- India's Soil Health Card Scheme:State agriculture departments in Gujarat and Maharashtra distribute site-specific micronutrient recommendations, institutionalizing demand among smallholder cooperatives cultivating horticulture crops.
- EDTA Chelation Chemistry:Enhanced bioavailability of zinc and iron formulations in calcareous soils drives replacement of conventional sulfate salts among specialty crop producers in California's Central Valley.
- Brazil's Cerrado Intensification:Soybean and corn rotations deplete soil boron reserves, compelling large-scale operators to adopt annual micronutrient programs as standard practice.
Market Restraints
- Sulfuric Acid Feedstock Volatility:Sulfate-based micronutrient production faces input cost pressure from phosphate fertilizer sector competition for sulfuric acid supply.
- REACH Chelating Agent Restrictions:ECHA biodegradability mandates on EDTA and DTPA carriers force European manufacturers toward higher-cost lignosulfonate alternatives.
- Granular Broadcasting Displacement:Drip irrigation and drone-based foliar application erode addressable volume for traditional granular zinc and boron products.
Strategic Opportunities
- Protected Agriculture Expansion:Greenhouse consortia in Almeria, Spain and the Netherlands seek water-soluble micronutrient compounds tailored for closed-loop fertigation systems.
- Carbon-Intensity Benchmarking:China's MEE discharge standards under dual carbon goals create first-mover advantage for manufacturers deploying low-emission crystallization processes.
- Drone Application Infrastructure:Aerial spraying service providers in Australia's wheat belt require ultra-low-volume foliar formulations with optimized droplet adhesion properties.
Industry Challenges
- Formulation Compatibility Engineering:Micronutrient chemists must validate stability of chelated compounds across diverse pH ranges and tank-mix pesticide combinations without precipitation.
- Multi-Jurisdiction Label Registration:EPA FIFRA requirements, EU Fertilizing Products Regulation CE marking, and China's GB standards impose divergent purity thresholds and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micronutrient Fertilizer Market |
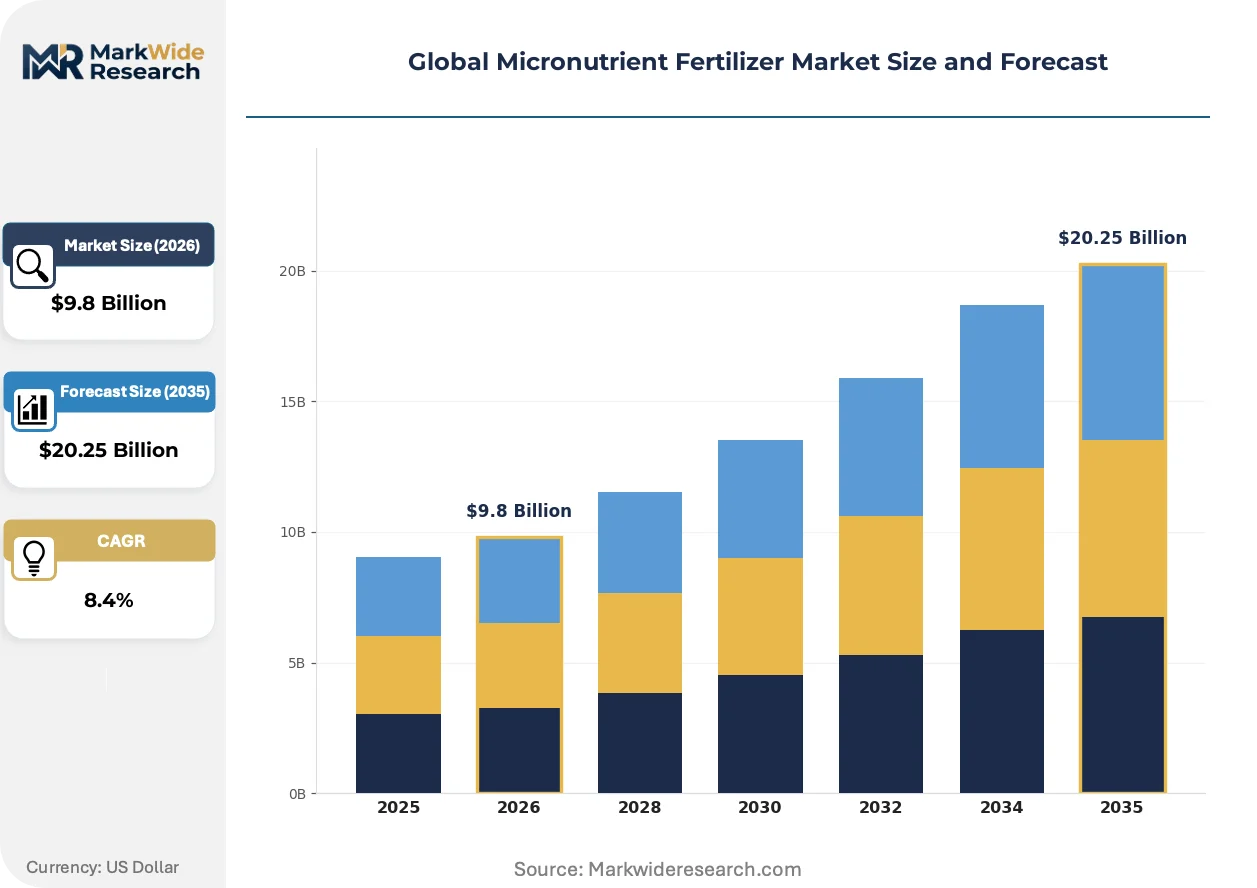
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron, Zinc, Manganese, Copper, Boron, Molybdenum Form: Liquid, Granular, Chelated, Powder, Water Soluble Application: Cereal Crops, Oilseeds, Horticulture, Pulses, Plantation Crops End User: Large Scale Farms, Small Holders, Organic Farming, Greenhouses |
| Companies Covered | Yara International ASA, The Mosaic Company, ICL Group Ltd, K+S Aktiengesellschaft, Coromandel International Ltd, Koch Agronomic Services, BASF SE, Nutrien Ltd, Haifa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micronutrient Fertilizer Market Shifts & Advancements
Controlled-release coating technologies and biological chelation alternatives are reshaping product architecture, while regulatory pressure on synthetic chelating agents accelerates chemistry substitution cycles across major producing regions.
Nano-encapsulated micronutrient delivery systems are integrating lignin-based carriers with sulfur coatings to synchronize nutrient release with crop phenological stages. Large-scale corn and soybean operations in Iowa and Illinois pilot these formulations to reduce leaching losses in sandy soils. The technology is integrating precision timing with variable-rate application equipment, compressing the performance gap between conventional and specialty fertilizer margins.
REACH restrictions on non-biodegradable chelating agents tighten purity thresholds for EDTA and DTPA products sold across European member states. Manufacturers face reformulation costs or market withdrawal for non-compliant legacy product lines. Specialty crop sectors in Italy and Greece accelerate adoption of IDHA and GLDA biodegradable alternatives despite 15-20% price premiums.
Cooperative procurement consortia among California specialty crop growers consolidate micronutrient purchasing through shared agronomic advisory services. These aggregators negotiate volume contracts with formulation specialists, displacing traditional distributor markups. The consolidation concentrates buying power in Fresno and Kern county production clusters, pressuring national distributor margins.
Global Micronutrient Fertilizer Market Segmentation
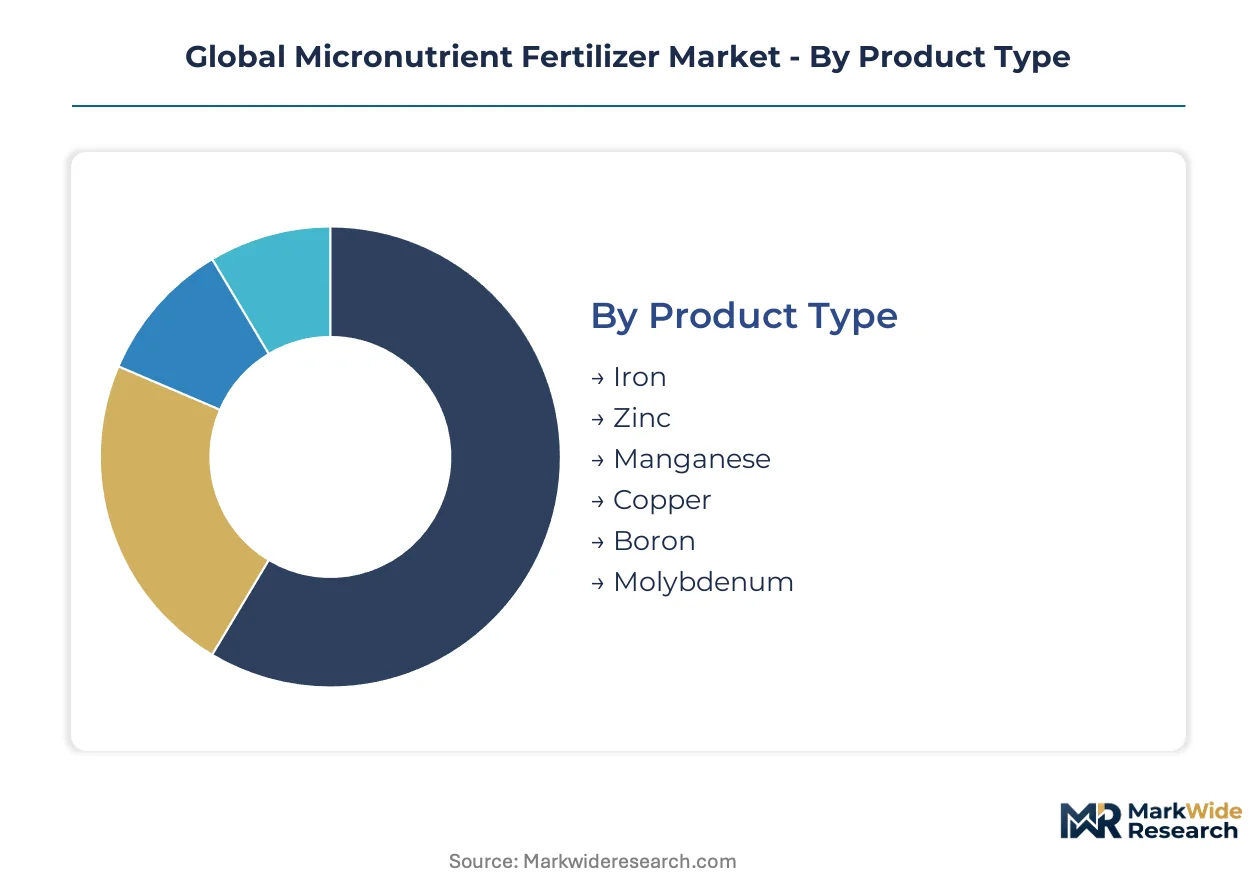
Micronutrient fertilizer segmentation reveals how formulation chemistry and application infrastructure shape procurement patterns across diverse cropping systems. Product specifications determine compatibility with precision equipment, while end-user scale dictates volume and service requirements.
Product Type:
Zinc and iron formulations anchor the technology spectrum through distinct chelation requirements and soil interaction profiles.
- Zinc:Sulfate and oxide forms dominate basal applications, though EDTA-chelated variants command premium positioning in India's calcareous Gujarat soils where alkaline pH locks conventional salts. Zinc deficiency correction drives the highest replacement frequency in intensive cereal rotations.
- Boron:Solubor and borax compounds serve foliar and soil correction roles, with demand concentrating in Brazil's Cerrado where soybean-corn rotations deplete reserves fastest. Annual application programs are becoming standard practice among large-scale operators.
- Iron:Ferrous sulfate and Fe-EDTA chelates address chlorosis in high-pH vineyard and orchard soils; foliar spraying displaces soil application in drip-irrigated California Central Valley operations.
- Manganese:Sulfate salts and chelated forms correct deficiency in cereal flag leaves and legume nodulation zones, with uptake concentrated in Australia's wheat belt.
- Copper:Sulfate and oxide formulations serve woody perennial and cereal requirements, with smaller volume pools tied to specific soil parent materials.
- Molybdenum:Sodium molybdate serves legume-specific nodulation needs in pulse-growing regions of India and Canada at gram-per-hectare application rates.
Zinc leads on scale; boron leads on momentum.
Form:
Physical specification determines equipment compatibility and labor economics across divergent farm scales and irrigation infrastructures.
- Liquid:Ready-to-apply concentrates integrate with variable-rate injection systems and drone spraying platforms, gaining share fastest in California specialty crop and Midwest corn-soy operations where labor constraints favor tank-mix efficiency.
- Chelated:EDTA, DTPA, and emerging biodegradable carriers deliver protected micronutrient ions in high-pH soils, with IDHA and GLDA alternatives expanding in REACH-regulated European markets despite cost premiums.
- Water Soluble:Crystalline salts dissolve for fertigation in protected agriculture, serving Netherlands and Almeria greenhouse consortia with closed-loop recirculation compatibility.
- Granular:Traditional broadcasting forms face volume pressure as precision application displaces blanket spreading, though residual demand persists in smallholder markets with limited equipment access.
- Powder:Dry flowable grades serve custom blending operations and aerial application in Australia's extensive wheat systems.
Liquid forms concentrate investment; chelated variants concentrate margin.
Application:
Crop-specific physiological demands and harvest value determine micronutrient program intensity and formulation selection.
- Horticulture:High-value fruit and vegetable operations in California, Spain, and India's Maharashtra justify premium chelated and foliar programs with multiple seasonal applications tied to phenological stages.
- Cereal Crops:Wheat, rice, and corn rotations in India and Brazil generate volume demand for zinc and boron correction, with soil health card recommendations institutionalizing micronutrient use in Gujarat and Punjab.
- Oilseeds:Soybean and canola production in Brazil's Mato Grosso and Canada's prairies drives boron and manganese demand for reproductive stage optimization.
- Pulses:Legume rotations in India's Madhya Pradesh and Australia's grain belt require molybdenum and iron for nitrogen fixation efficiency.
- Plantation Crops:Oil palm, rubber, and coffee estates in Indonesia and Vietnam apply micronutrient blends through foliar programs in mature tree maintenance cycles.
Cereal crops anchor volume; horticulture anchors value.
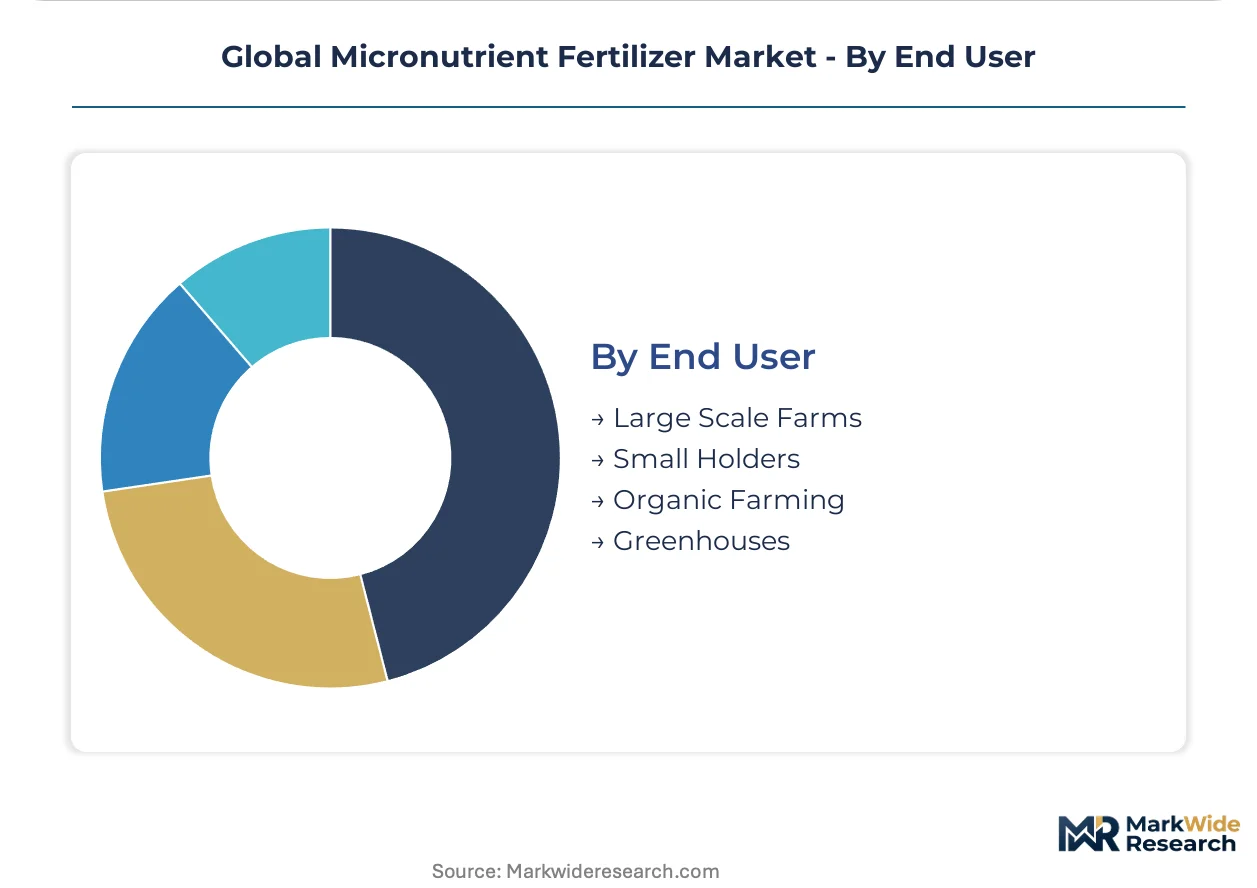
End User:
Operational scale and certification status fragment procurement patterns across service requirements and price sensitivity.
- Large Scale Farms:Commercial corn-soy and specialty crop operations in Iowa, Illinois, and California's Central Valley consolidate purchasing through direct manufacturer relationships and precision agriculture service bundles.
- Small Holders:India's cooperative structures and government soil health programs aggregate fragmented demand in Gujarat and Maharashtra, creating institutional procurement channels.
- Greenhouses:Protected agriculture consortia in the Netherlands, Spain, and Mexico demand water-soluble compounds compatible with closed-loop fertigation and recirculation systems.
- Organic Farming:Certified operations in California and Germany require natural-source micronutrient forms, accepting lower bioavailability and higher application rates to meet input restrictions.
Large-scale farms concentrate volume; greenhouses concentrate specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomic expertise clusters in the Netherlands' greenhouse engineering sector and India's soil science institutes anchor regional innovation pipelines for micronutrient formulation.
United States
California's Central Valley specialty crop producers and Iowa's corn-soy belt drive differentiated demand for liquid and chelated zinc formulations. The EPA governs product registration under FIFRA, tightening label claim documentation for foliar applications. Fresno and Kern county grower cooperatives consolidate procurement through shared agronomic advisory services, displacing traditional distributor channels.
Brazil
Soybean-corn rotations in Mato Grosso and Goiás deplete soil boron reserves fastest, institutionalizing annual micronutrient programs among large-scale operators. ANVISA coordinates with state agriculture departments on fertilizer quality protocols. The Cerrado region's intensifying cultivation expands addressable volume for precision application equipment compatible with liquid formulations.
India
Horticulture expansion in Gujarat and Maharashtra accelerates adoption among smallholder cooperatives cultivating pomegranates and grapes. The FSSAI and state agriculture departments distribute soil health cards recommending site-specific micronutrient doses. Anand and Nashik district clusters concentrate blending operations serving institutional procurement channels created by government programs.
China
Protected agriculture expansion in Shandong and Hebei provinces demands water-soluble compounds for closed-loop fertigation systems. The MEE enforces discharge standards on manufacturing facilities under dual carbon goals, elevating compliance costs for sulfate-based crystallization processes. The Yangtze River Delta hosts reformulation investments targeting biodegradable chelating agent transitions.
Netherlands
Greenhouse consortia in Westland and Almeria seek specialty micronutrient compounds compatible with recirculating nutrient solutions. REACH and the EU Fertilizing Products Regulation impose strict biodegradability criteria on EDTA and DTPA carriers, forcing chemistry substitution toward lignosulfonate alternatives. Wageningen University research clusters anchor European innovation in controlled-release coating technologies.
Global Micronutrient Fertilizer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and distribution architecture tiers. The vendor base organizes around captive mineral access, chelation technology licensing, and precision application service bundling. Three archetypes dominate: mining-integrated blenders with backward integration into phosphate and potash assets; specialty formulation houses with proprietary chelation chemistry; and precision agriculture platforms combining micronutrients with variable-rate equipment. Competitive moves concentrate on M&A for regional distribution access and partnerships with drone spraying service providers.
Among diversified mining-integrated players, Yara International ASA and The Mosaic Company exemplify scale-driven positioning anchored in captive raw material access. ICL Group Ltd occupies a specialist tier focused on water-soluble compounds for protected agriculture systems. European regulatory pressure on synthetic chelating agents creates differentiation openings for manufacturers with biodegradable carrier portfolios, a dynamic where K+S Aktiengesellschaft and Haifa Group represent alternative chemistry pathways. Koch Agronomic Services and Nutrien Ltd sit within the North American distribution infrastructure layer, competing through precision agriculture service integration rather than formulation exclusivity.
| Leading Market Players |
|---|
| Yara International ASA |
| The Mosaic Company |
| ICL Group Ltd |
| K+S Aktiengesellschaft |
| Coromandel International Ltd |
| Koch Agronomic Services |
| BASF SE |
| Nutrien Ltd |
| Haifa Group |
| Others |
Supply & Pricing Matrix
China's MEE discharge standards under dual carbon goals filter qualified suppliers and gate premium-tier pricing access for low-emission crystallization processes. Manufacturers meeting these benchmarks capture pricing power in European and North American markets where REACH biodegradability mandates compound compliance costs.
Pricing Analysis
Bundled precision agriculture service packages command 15-25% premiums over unbundled micronutrient product sales. Three-tier pricing structure across premium chelated, standard sulfate, and economy oxide grades reflects certification complexity and bioavailability differentials. Cost compression in standard sulfate tiers intensifies because phosphate fertilizer sector competition for sulfuric acid feedstock elevates input costs. Smallholder cooperatives in India's Gujarat and Maharashtra exhibit highest price sensitivity, while California Central Valley specialty crop operations absorb premium formulations with minimal volume pushback.
Supply Chain Analysis
Direct-to-greenhouse channels handle protected agriculture demand in the Netherlands and Spain, while distributor networks serve fragmented smallholder markets in India and Brazil. Manufacturing concentration centers on China, India, and Germany, with crystallization and chelation capacity tethered to phosphate mining clusters and specialty chemical feedstocks. Sulfuric acid, lignosulfonate carriers, and EDTA precursors constitute critical input dependencies. Single-source vulnerability in synthetic chelating agent supply creates exposure to ECHA biodegradability restriction timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge from divergent regulatory compliance costs between REACH-regulated European markets and India's institutional procurement channels. The cost differential in chelation chemistry certification creates margin expansion potential for manufacturers with dual-qualification capabilities.
For Market Incumbents: Extend captive blending capacity into India's Anand and Nashik district clusters to intercept government soil health program procurement flows. Deepen backward integration into sulfuric acid supply or lignosulfonate carrier production to offset phosphate sector feedstock competition. Biodegradable chelation alternatives represent the priority R&D lever against REACH-driven chemistry substitution cycles. For New Entrants and Emerging Players: Drone spraying service providers in Australia's wheat belt present the most penetrable channel partner type for ultra-low-volume foliar formulation entry. Target protected agriculture consortia in Almeria and Mexico with water-soluble compound specialization. White-space exists in carbon-intensity benchmarked crystallization processes for Chinese MEE compliance. For Investors and Strategic Acquirers: Roll-up economics work for regional formulation specialists because institutional procurement consolidation in India and cooperative buying in California compress distributor margins and favor scaled direct relationships. Five-to-ten year viability hinges on biodegradable chelation patent portfolios. The signal to watch is ECHA enforcement acceleration on non-compliant legacy EDTA product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Chelation Chemistry Transition | ECHA REACH restrictions on EDTA and DTPA force reformulation investments toward IDHA and GLDA alternatives. |
| Backward Integration into Sulfuric Acid Supply | Captive feedstock access insulates sulfate-based micronutrient production from phosphate fertilizer sector competition. |
| Drone Application Formulation Development | Aerial spraying service providers in Australia's wheat belt require optimized droplet adhesion for ultra-low-volume delivery. |
| Greenhouse Consortium Direct Contracts | Almeria and Netherlands protected agriculture clusters consolidate procurement through shared agronomic advisory services. |
| Carbon-Intensity Benchmarked Crystallization | China's MEE discharge standards under dual carbon goals reward first-movers with low-emission manufacturing processes. |
Research Methodology
Direct dialogue with micronutrient formulation chemists, precision agriculture equipment distributors, and state agriculture department procurement officers in India and Brazil grounds qualitative assessment. Secondary validation draws from EPA FIFRA registration databases, ECHA REACH substance evaluations, customs trade data on sulfuric acid and chelating agent flows, and SEC filings of diversified fertilizer conglomerates. Bottom-up volume estimates from application rate assumptions triangulate against top-down market sizing from production capacity declarations.
Top-down macroeconomic drivers and bottom-up segment penetration rates converge across the analysis window. Segmentation dimensions include nutrient type, chelation chemistry, physical form, application method, crop category, and farm scale archetype. CAGRs derive from slope analysis of historical adoption curves adjusted for regulatory inflection points and precision agriculture equipment penetration. Soil health card distribution velocity in India and drone spraying service expansion in Australia constitute key forecast inputs.
Revisions become necessary when ECHA accelerates biodegradability enforcement timelines, China's MEE tightens discharge standards beyond current dual carbon commitments, or sulfuric acid feedstock competition from phosphate fertilizer producers intensifies. Periodic stress-testing of base assumptions against these regulatory and input cost triggers is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Soil Conditioners Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Europe Fertilizers Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Boron Fertilizers Market