
 Diammonium Hydrogen Phosphate (DAP) Market | 2026-2036
Diammonium Hydrogen Phosphate (DAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Diammonium Hydrogen Phosphate (DAP) Market Outlook
REACH compliance in Europe is recalibrating the cost-of-entry calculus for DAP suppliers seeking export certification. The Mosaic Company leverages its integrated phosphate rock mining and processing infrastructure to sustain margin resilience against regulatory compliance costs. PhosAgro Group of Companies anchors its competitive stance through vertical control over apatite concentrate supply from the Kola Peninsula. OCP Group dominates North African export corridors with captive port and logistics assets serving Atlantic and Mediterranean routes.
Diammonium hydrogen phosphate is a water-soluble phosphate fertilizer manufactured through the neutralization of phosphoric acid with ammonia, yielding a compound with approximately 18% nitrogen and 46% phosphorus pentoxide content. Its primary commercial purpose centers on delivering concentrated phosphorus nutrition to row crops, horticultural produce, and specialty agriculture where soil phosphorus fixation limits native availability. Granular formulations lead volume shipments due to their compatibility with mechanized broadcasting equipment and reduced drift losses during application, while liquid DAP represents the fastest-growing product configuration driven by precision agriculture adoption and fertigation system integration. Agricultural co-operatives constitute a structurally significant distribution channel in concentrated farming regions, capturing margin pools through bulk purchasing leverage and seasonal credit extension to member growers.
The EPA oversees water quality standards affecting phosphate fertilizer application rates in watersheds with impaired nutrient loads, while India's FSSAI and BIS frameworks govern food-grade DAP specifications for processed food applications. China's MEE enforces dual carbon goals that constrain ammonia production intensity, directly tightening DAP feedstock availability and reshaping regional supply dynamics. Stakeholders must monitor how evolving nutrient use efficiency mandates across multiple jurisdictions will restructure product formulation requirements and procurement qualification criteria.
Market Dynamics
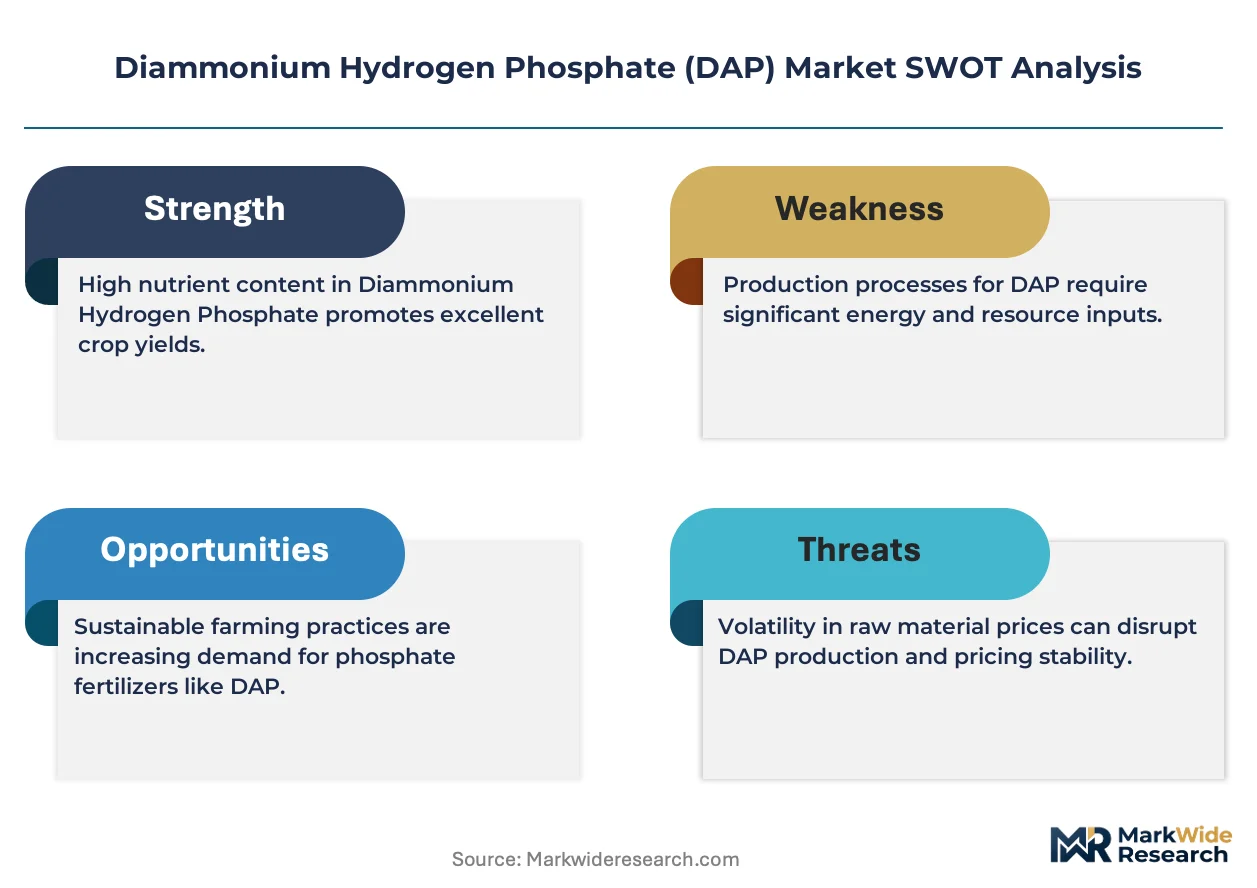
Soil phosphorus depletion across intensive grain belts is compelling farmers to escalate DAP application rates, while the EU Green Deal's tightening runoff protocols force costly reformulation investments that compress supplier margins.
Growth Catalysts
- India's phosphatic fertilizer subsidy programs:Government procurement guarantees underwrite stable demand volumes for domestic and import suppliers. The PLI scheme for fertilizer manufacturing reinforces local production capacity.
- REACH compliance recalibration:Export certification requirements into Europe are filtering out marginal producers, consolidating market share among compliant manufacturers with testing infrastructure.
- Precision agriculture fertigation systems:Liquid DAP adoption is accelerating as drip irrigation networks expand in water-stressed horticultural regions, displacing traditional broadcasting methods.
Market Restraints
- Ammonia feedstock volatility:China's MEE dual carbon goals constrain domestic ammonia production intensity, tightening DAP precursor availability and amplifying input cost swings.
- Phosphate rock supply concentration:Captive mining assets in Morocco, Russia, and the United States dominate merchant concentrate flows, creating geopolitical exposure for non-integrated processors.
- Phosphogypsum waste accumulation:Wet-process phosphoric acid production generates radioactive byproduct stockpiles that face escalating EPA and state-level disposal restrictions.
Strategic Opportunities
- Sub-Saharan African underpenetration:Fertilizer application rates in Nigeria, Ethiopia, and Kenya remain below agronomic optimums, creating volume expansion potential as soil testing extension services expand.
- Food-grade DAP certification:FSSAI and BIS framework alignment for processed food applications opens premium pricing tiers in leavening agents and nutritional fortification segments.
- Controlled-release coating convergence:Polymer-sulfur encapsulation technologies married to DAP granules enable synchronized nutrient release matching crop uptake curves, reducing leaching losses.
Industry Challenges
- Soil testing agronomy skill scarcity:Extension services lack personnel trained in phosphorus fixation chemistry and variable-rate prescription mapping, limiting precision adoption.
- Granulation plant capex intensity:Ammoniation-granulation units require sulfuric acid integration or merchant acid sourcing, demanding nine-figure investments with decade-long payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diammonium Hydrogen Phosphate (DAP) Market |
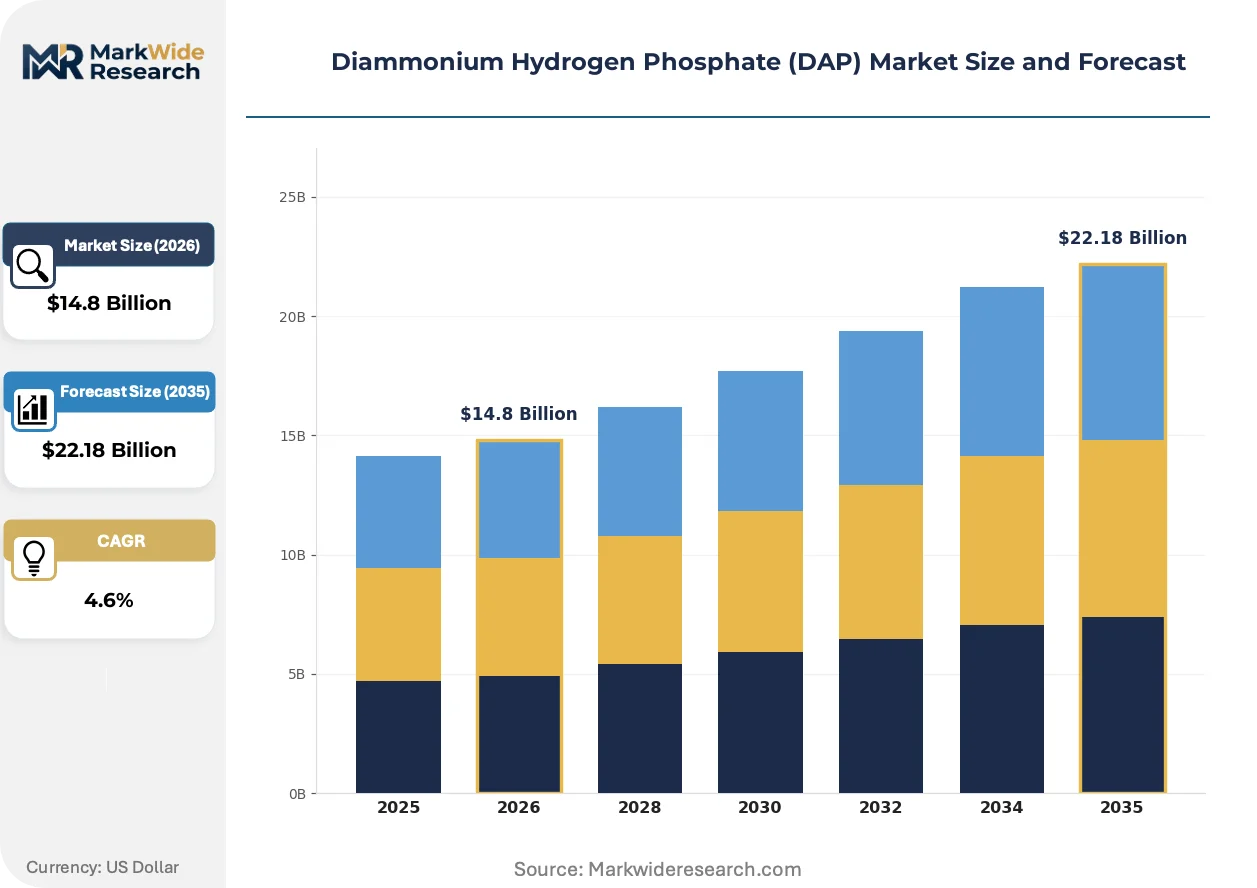
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Prill Application: Agriculture, Fertilizers, Animal Feed, Food Industry End User: Farmers, Fertilizer Producers, Food Processors, Livestock Owners Distribution Channel: Online Retail, Distributors, Direct Sales, Agricultural Co-operatives |
| Companies Covered | The Mosaic Company, PhosAgro Group of Companies, China BlueChemical Ltd., SABIC, GNFC Limited, Nutrien Ltd., OCP Group, Yara International ASA, CF Industries Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diammonium Hydrogen Phosphate (DAP) Market Strategic Shifts
Electrification of ammonia synthesis and phosphate processing is decarbonizing production footprints, while regulatory tightening on nutrient runoff and precision agriculture hardware diffusion are rewriting formulation and distribution economics.
Green ammonia production via electrolytic hydrogen is electrifying DAP manufacturing pathways, replacing steam methane reforming feedstock. Nordic and Middle Eastern producers with stranded renewable assets are piloting commercial-scale installations. This transition is compressing carbon-adjusted cost differentials between regional supply basins.
The EU Green Deal's nutrient management protocols are mandating maximum permissible phosphate runoff limits in watersheds with impaired water quality. Fertilizer blenders must reformulate with stabilizers and inhibitors. Granular DAP with nitrification inhibitor coatings is capturing preferential placement in Dutch and Danish procurement tenders.
Co-operative buying consolidation is displacing independent dealer networks across North American and European grain belts. Member-growers are aggregating seasonal credit and volume commitments to extract price concessions. This behavior is most visible in Iowa, Illinois, and Saskatchewan where crop input co-ops command majority channel share.
Diammonium Hydrogen Phosphate (DAP) Market Segmentation
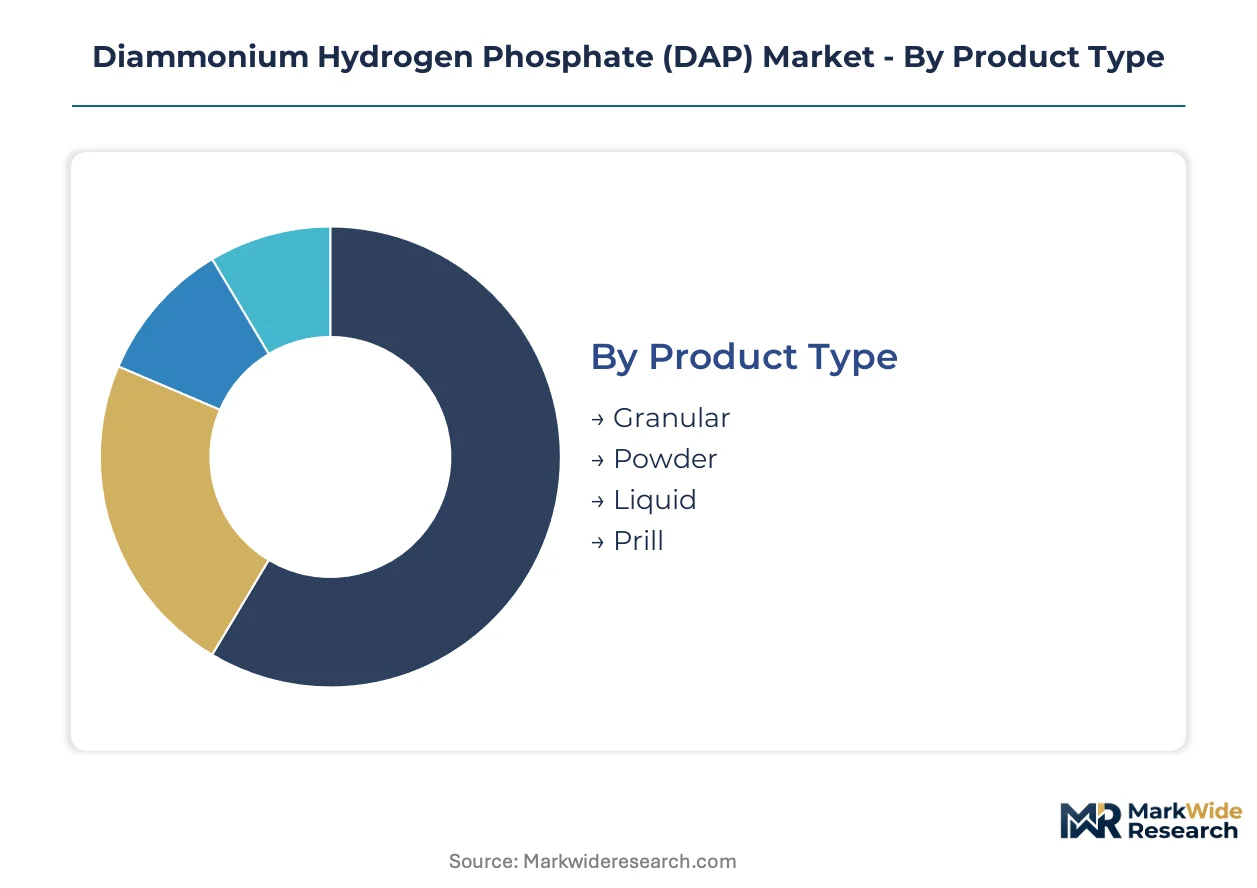
DAP formulation variations determine equipment compatibility, nutrient release kinetics, and handling economics across disparate farming systems. Segment-level procurement patterns reveal where margin pools concentrate and which product configurations warrant capacity expansion.
Product Type:
Supply concentration in granulation infrastructure favors formats with existing installed capacity, while emerging precision agriculture requirements are redirecting investment toward fluid handling systems.
- Granular:Spherical pellets manufactured through ammoniation-granulation towers yield 2-4mm particles optimized for mechanized broadcasting equipment. Demand clusters in Iowa, Illinois, and Saskatchewan grain belts where co-operative procurement aggregates volume commitments for bulk handling.
- Liquid:Aqueous solutions with 8-10% nitrogen and 20-24% phosphorus pentoxide content enable direct injection into drip irrigation networks. Adoption accelerates in California's Central Valley and Almería's greenhouse complexes where fertigation systems displace surface broadcasting.
- Powder:Fine-ground crystalline material serves specialty blending operations and water-soluble fertilizer compounding. Niche positioning in hydroponic nutrient formulations and controlled-release coating substrates.
- Prill:Smaller spherical particles (1-2mm) produced via spray crystallization for aerial application and high-analysis compound fertilizers. Limited production capacity concentrated in European nitrogen-phosphate complexes.
Granular absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Cost tier differentiation separates commodity fertilizer sales from certified food-grade and feed-grade specifications requiring additional purification and documentation.
- Agriculture:Field crop production accounts for dominant volume flows, with phosphorus supplementation targeting corn, wheat, and soybean systems on depleted Mollisols and Alfisols. Application rates respond to soil test phosphorus thresholds and yield response curves.
- Fertilizers:Intermediate blending into NPK compounds and specialty formulations for horticultural, turf, and plantation crops. Toll manufacturing arrangements predominate in India and Brazil.
- Animal Feed:Purified grades serve as phosphorus and nitrogen supplements in ruminant and monogastric rations. FSSAI and BIS certification requirements govern mineral bioavailability specifications.
- Food Industry:Food-grade DAP functions as a leavening acid in baking powders and yeast foods, plus a buffering agent in processed cheese. Premium pricing tiers reflect heavy metal limits and microbial specifications.
Agriculture commands the volume base; food industry commands the margin premium.
End User:
Customer type fragmentation creates divergent service requirements, with farmers demanding agronomic support and industrial buyers prioritizing specification consistency and documentation.
- Farmers:Owner-operators and tenant producers purchasing through seasonal credit programs and co-operative buying pools. Procurement timing concentrates pre-planting windows with price sensitivity to commodity grain futures.
- Fertilizer Producers:Compound fertilizer manufacturers and blenders sourcing merchant DAP for NPK formulation. Backward integration into phosphoric acid production characterizes major Indian and Chinese processors.
- Food Processors:Baking, dairy, and prepared food manufacturers requiring certified food-grade material with batch traceability and contaminant testing.
- Livestock Owners:Integrated poultry and swine operations formulating mineral premixes, plus independent feed mills serving regional dairy markets.
Farmers generate the transaction volume; fertilizer producers generate the tonnage throughput.
Distribution Channel:
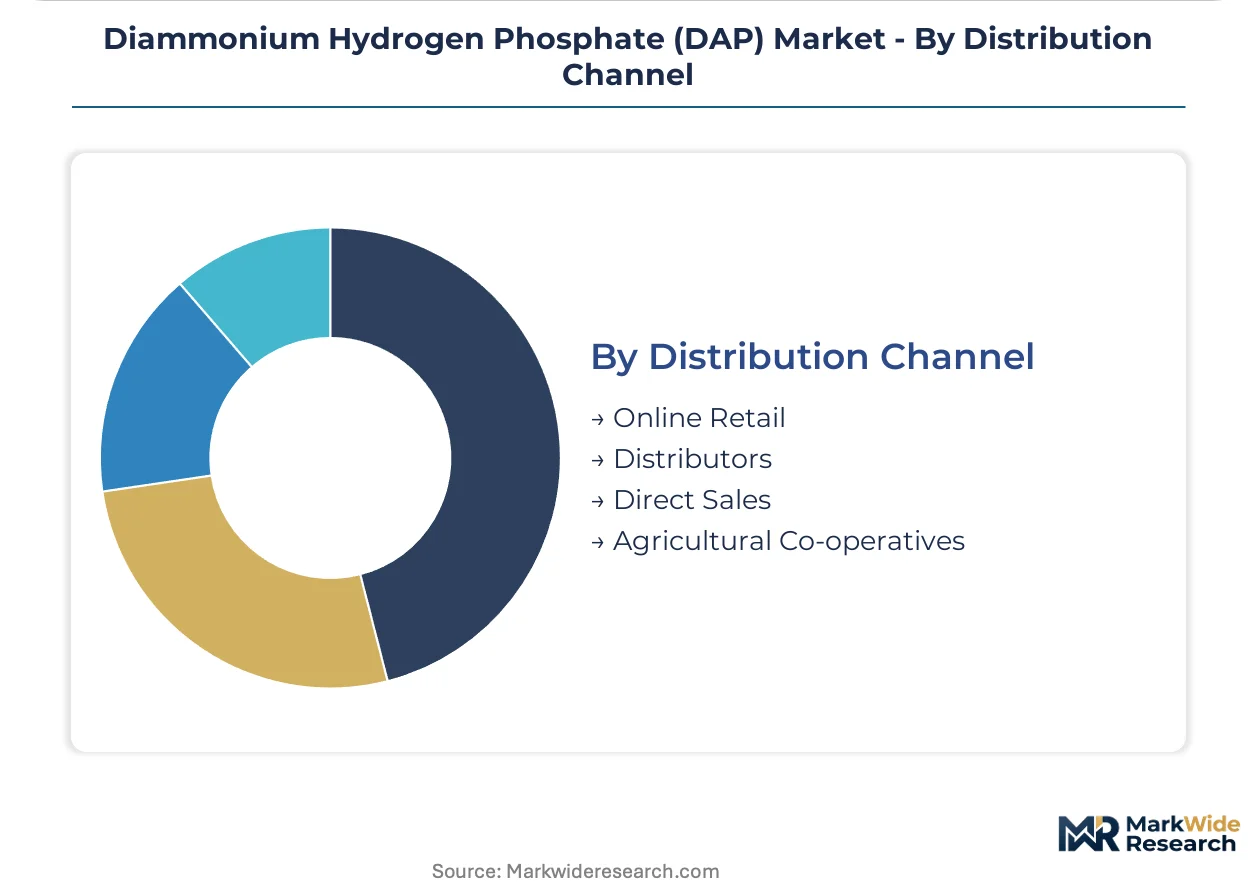
Geographic reach constraints and credit risk appetites segment channel economics, with co-operatives leveraging member equity to extend seasonal financing unavailable through arms-length distributors.
- Agricultural Co-operatives:Member-owned buying organizations in US Corn Belt, Canadian Prairies, and European grain regions aggregate procurement volumes to extract manufacturer rebates and extend deferred payment terms.
- Distributors:Independent dealer networks with warehousing infrastructure and application equipment fleets serving dispersed farm populations beyond co-operative territories.
- Direct Sales:Large-scale farming enterprises and industrial buyers purchasing truckload quantities direct from manufacturing sites, bypassing intermediate margins.
- Online Retail:E-commerce platforms serving smallholder specialty crop producers and hobby farming segments with packaged quantities and technical content delivery.
Agricultural co-operatives dominate volume capture in consolidated farming regions; online retail is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates procurement volumes through government subsidy programs, while regulatory tightening across the EU and feedstock constraints in China reshape supply economics.
United States
Corn and soybean growers in Iowa and Illinois drive seasonal DAP demand through co-operative buying pools. The EPA enforces water quality standards that limit phosphate application rates in impaired watersheds. Gulf Coast ammonia production clusters anchor domestic supply chains for phosphoric acid manufacturing.
India
Government phosphatic fertilizer subsidies underwrite stable procurement for wheat and rice cultivation across the Indo-Gangetic Plain. The FSSAI and BIS frameworks govern food-grade specifications for processed food applications. Gujarat and Maharashtra host backward-integrated fertilizer complexes serving domestic compound blending operations.
China
The country's MEE dual carbon goals constrain ammonia production intensity, tightening DAP precursor availability and amplifying input cost volatility. Yangtze River Delta processing hubs face emissions compliance pressures that favor larger integrated producers. Shandong Peninsula phosphate fertilizer manufacturing clusters serve both domestic agriculture and export markets.
Morocco
OCP Group dominates Atlantic and Mediterranean export corridors with captive port and logistics infrastructure. The country's phosphate rock mining assets supply merchant concentrate flows to non-integrated processors worldwide. Jorf Lasfar industrial complex anchors North African fertilizer production capacity.
Germany
REACH compliance recalibrates cost-of-entry for DAP suppliers seeking export certification into European markets. The EU Green Deal's nutrient management protocols mandate maximum permissible phosphate runoff limits in watersheds with impaired water quality. Rhine-Ruhr industrial corridor hosts specialized granulation and coating operations for controlled-release formulations.
Diammonium Hydrogen Phosphate (DAP) Market Competitive Environment
North American producers anchor one tier; Russian and Moroccan specialists hold upstream resource positions. Market structure tilts toward consolidation among integrated miners with captive phosphate rock assets, while regional blenders and toll manufacturers occupy fragmented downstream niches. Three archetypes dominate: vertically integrated mining-to-fertilizer conglomerates, ammonia-centric nitrogen producers diversifying into phosphates, and government-backed national champions securing food security. Competitive moves center on backward integration into phosphate rock mining and geographic expansion into underpenetrated African and Southeast Asian markets.
Within the integrated mining conglomerate tier, The Mosaic Company and PhosAgro Group of Companies exemplify archetypes built on captive phosphate rock infrastructure. OCP Group anchors the North African export corridor position. Among diversified nitrogen specialists, Yara International ASA and CF Industries Holdings, Inc. occupy positions where ammonia production capabilities enable phosphate product line extension. China BlueChemical Ltd. and SABIC represent state-linked entities where national resource strategies shape competitive posture. GNFC Limited and Nutrien Ltd. sit within regional procurement networks where distribution scale and seasonal credit extension determine market access.
| Leading Market Players |
|---|
| The Mosaic Company |
| PhosAgro Group of Companies |
| China BlueChemical Ltd. |
| SABIC |
| GNFC Limited |
| Nutrien Ltd. |
| OCP Group |
| Yara International ASA |
| CF Industries Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in Morocco, Russia, and China anchor supply discipline through captive phosphate rock assets, translating upstream control into pricing power that resists margin erosion from ammonia feedstock volatility. Their state-linked financing insulates capacity decisions from short-term commodity swings, compressing price competition for non-integrated merchants.
Pricing Analysis
Short lead-time premiums command measurable markups against contract-of-take baselines, with spot inventory discounts widening during seasonal planting windows. Three-tier pricing structure across food-grade certification, standard agricultural grade, and uncoated bulk material separates premium tiers. Cost compression in standard-grade DAP is intensifying because China's MEE dual carbon goals constrain ammonia availability. Smallholder farmers in Sub-Saharan Africa exhibit highest price sensitivity; food processors with FSSAI certification requirements show least.
Supply Chain Analysis
Direct-to-compound-blender channels handle bulk procurement volumes from integrated producers, bypassing distributor markups for NPK manufacturers in India and Brazil. Geographic supply concentration rests on Morocco, Russia, and the United States for phosphate rock; China, Russia, and Trinidad for merchant ammonia. Raw material dependencies center on sulfuric acid, phosphoric acid, and ammonia feedstocks. Single-source vulnerability in Kola Peninsula apatite concentrate creates geopolitical exposure. Distribution runs through agricultural co-operatives in consolidated grain belts and independent dealer networks in fragmented farming regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as REACH compliance costs and ammonia feedstock volatility force sub-scale processors toward exit or acquisition. Regulatory recalibration in Europe and carbon-constrained production in China are accelerating this filtering mechanism.
For Market Incumbents: Deepen backward integration into phosphate rock mining or captive ammonia production to defend margin structures against input cost swings. Prioritize certification investment for REACH export compliance and FSSAI food-grade qualification to capture premium pricing tiers. Channel control through co-operative buying pool penetration in Iowa, Illinois, and Saskatchewan secures volume commitments against distributor displacement. For New Entrants and Emerging Players: E-commerce platforms serving smallholder specialty crop producers offer the most penetrable entry vector, bypassing capital-intensive granulation infrastructure. Target Nigeria, Ethiopia, and Kenya where fertilizer application rates sit below agronomic optimums and soil testing extension services are expanding. Food-grade DAP certification for processed food applications opens premium positioning against commodity-grade incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Indian compound fertilizer blenders facing working capital pressure from subsidy payment delays. Long-term viability hinges on proximity to phosphate rock supply or ammonia production clusters. The signal to watch is policy shifts in India's PLI scheme for fertilizer manufacturing capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive Kola Peninsula or Moroccan mine assets eliminate merchant concentrate price exposure. |
| Green Ammonia Production Transition | Electrolytic hydrogen pathways in Nordic and Middle Eastern sites compress carbon-adjusted cost differentials. |
| Controlled-Release Coating Convergence | Polymer-sulfur encapsulation technologies married to DAP granules reduce EU Green Deal runoff compliance costs. |
| Sub-Saharan African Distribution Expansion | Soil testing extension service partnerships in Nigeria and Kenya build demand pull for volume growth. |
| Food-Grade Certification Investment | FSSAI and BIS framework alignment opens premium pricing tiers in leavening agents and nutritional fortification. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with phosphate fertilizer plant managers, agricultural co-operative procurement leads, compound blender operations directors, and food-grade DAP quality assurance specialists. Secondary sources included IFA production statistics, ECHA REACH registration databases, Indian Fertilizer Association subsidy disbursement records, and USGS mineral commodity summaries. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates.
Granularity-level modeling operated at product-type, application-grade, end-user archetype, and regional production hub dimensions across the analysis window. CAGRs derived from segment-level volume projections calibrated against historical growth elasticities to grain prices and fertilizer subsidy intensities. Industry-specific forecast inputs incorporated phosphate rock mining capacity expansion timelines and ammonia plant utilization rates under China's dual carbon constraints.
The model holds under stable subsidy policy regimes in India and continued EU Green Deal implementation; deviation in phosphatic fertilizer subsidy suspension or REACH enforcement intensity would shift demand trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Urea Fertilizers Market
Fertilizers
South America Fertilizers Market
Fertilizers
Diammonium Phosphate (DAP) Market