
 Brazil Specialty Fertilizer Market | 2026-2036
Brazil Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Specialty Fertilizer Market Outlook
Polyhalite is hardening cost structures for sulfate-based specialty fertilizers across Brazil's potassium-deficient soils. Yara International ASA leverages its coastal blending infrastructure to dominate water-soluble and foliar product distribution. OCP Brasil anchors phosphate specialty output through its integrated mine-to-field operations in Minas Gerais and São Paulo. ICL Group Ltd differentiates via controlled-release coatings tailored to sugarcane and coffee nutrient uptake cycles.
Specialty fertilizers are formulated products delivering targeted nutrient ratios, often incorporating micronutrients, stabilizers, or coating technologies that regulate release rates through osmotic diffusion or polymer degradation, designed to optimize plant uptake efficiency and minimize environmental losses. Liquid fertilizers and slow-release formulations capture expanding margin pools as precision agriculture adoption spreads across mechanized farms. Microbial inoculants represent the fastest-growing product class, though organic fertilizers remain constrained by certification bottlenecks under Brazilian organic agriculture regulations.
ANVISA governs maximum residue limits for fertilizer-derived contaminants, while MAPA's registration requirements under Instrução Normative No. 27 shape market access timelines and product labeling standards. The Central-West region's state environmental secretariats in Mato Grosso and Goiás increasingly mandate buffer-zone nutrient management plans for watershed protection. Stakeholders must monitor pending revisions to Brazil's fertilizer import tariff structure and their cascading effects on domestic blending economics.
Market Dynamics
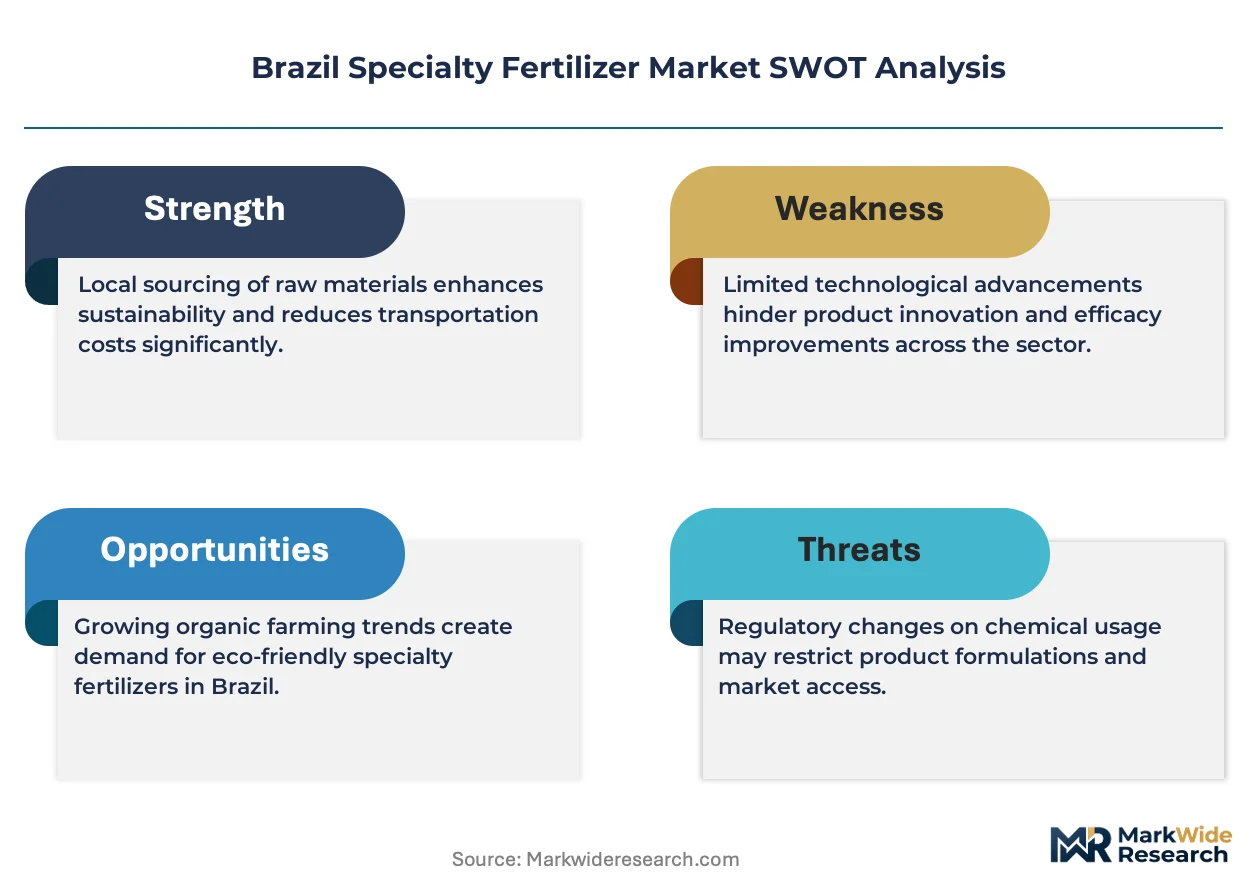
Polyhalite scarcity is restructuring sulfate-based fertilizer economics across Brazil's potassium-deficient Cerrado belt, forcing blenders to reformulate micronutrient ratios and renegotiate long-term offtake contracts with alternative mineral suppliers.
Growth Catalysts
- MAPA Instrução Normative No. 27:Streamlined registration pathways for controlled-release coatings accelerate product commercialization timelines for domestic formulators targeting sugarcane and coffee growers.
- Mato Grosso soybean belt:Precision agriculture penetration creates concentrated demand for foliar micronutrient blends calibrated to variable-rate application maps from mechanized farms exceeding 5,000 hectares.
- Microbial inoculants:Biological nitrogen fixation technologies reduce synthetic input dependency for legume producers seeking residue compliance with tightening watershed protection mandates in Goiás.
Market Restraints
- Polyhalite supply concentration:Dependence on a single UK-based mine operator for sulfate of potash feedstock exposes Brazilian blenders to shipping cost volatility and currency fluctuation risk.
- ANVISA residue thresholds:Maximum contaminant limits for heavy metals in organic-derived fertilizers extend certification timelines and disqualify imported compost products from key coastal blending facilities.
- Urea price anchoring:Commodity nitrogen pricing sets a low ceiling for specialty product premiums, constraining margin expansion even where agronomic performance differentials justify higher application costs.
Strategic Opportunities
- Western Bahia expansion corridor:Cotton and soybean conversion from degraded pastureland creates first-mover advantage for micronutrient-enriched starter fertilizers in previously uncultivated Cerrado fringe zones.
- Buffer-zone nutrient management mandates:Mato Grosso state environmental secretariat watershed protection rules create service-contract opportunities for precision application and runoff monitoring bundled with product supply.
- Liquid fertilizer infrastructure:Coastal terminal investments enable direct-to-farm delivery of bulk liquids, bypassing inland bagging operations and capturing margin from time-sensitive topdressing windows.
Industry Challenges
- Controlled-release coating calibration:Matching polymer degradation rates to specific soil temperature profiles across Brazil's climatic zones demands localized field trial investment that smaller blenders cannot fund.
- Organic certification bottlenecks:Brazilian organic agriculture regulation ambiguities around microbial inoculant origin documentation delay product labeling and create liability exposure for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Specialty Fertilizer Market |
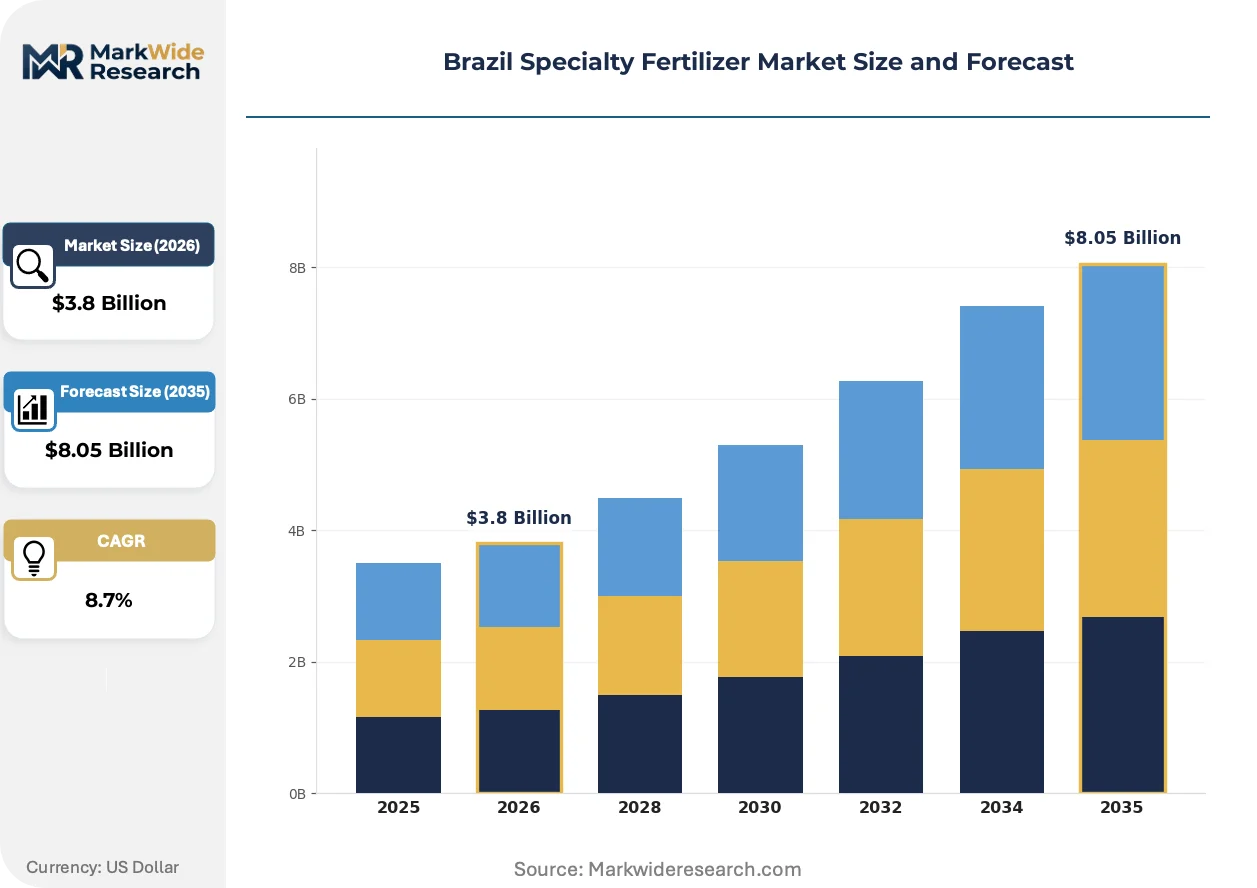
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Fertilizers, Liquid Fertilizers, Slow-Release Fertilizers, Organic Fertilizers Application: Crops, Turf and Ornamental, Greenhouse, Hydroponics End User: Agriculture, Horticulture, Landscape Contractors, Home Gardeners Distribution Channel: Online Stores, Garden Centers, Agricultural Cooperatives, Retail Outlets |
| Companies Covered | Yara International ASA, Nutrien, K+S Aktiengesellschaft, Indorama Fertilizer, OCP Brasil, Sociedad Quimica y Minera de Chile SA, ICL Group Ltd, Adufértil, The Mosaic Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Specialty Fertilizer Market Strategic Shifts
Digital soil mapping and variable-rate application hardware are converging to transform how Brazilian growers specify nutrient formulations, shifting purchasing power from distributors to agronomic service providers with embedded analytics capabilities.
Polymer-coated controlled-release fertilizers is electrifying uptake efficiency in Brazil's sugarcane sector. São Paulo state mill operators with mechanized green-cane harvesting systems have adopted these formulations at accelerating rates since residue burning prohibitions took full effect. The technology is electrifying margin compression for conventional split-application urea suppliers unable to match the labor and fuel savings from single-pass nutrient delivery.
ANVISA's evolving maximum residue limit protocols for fertilizer-derived contaminants are tightening product compliance verification requirements across all import and domestic manufacturing channels. MAPA's parallel enforcement of Instrução Normative No. 27 labeling standards forces reformulation of legacy products with incomplete micronutrient disclosure. Specialty blenders with dedicated regulatory affairs functions are capturing shelf space from commodity importers struggling to adapt documentation packages.
Buying committees at large-scale Mato Grosso farming cooperatives are consolidating annual fertilizer procurement into single-source contracts with performance guarantees tied to satellite-verified yield outcomes. Traditional distributor networks with inventory-heavy models are losing share to direct manufacturer relationships where agronomists embed with farm management software platforms. This consolidation pattern is most visible in the Primavera do Leste-Sorriso corridor where soybean operations exceed 10,000 hectares.
Brazil Specialty Fertilizer Market Segmentation
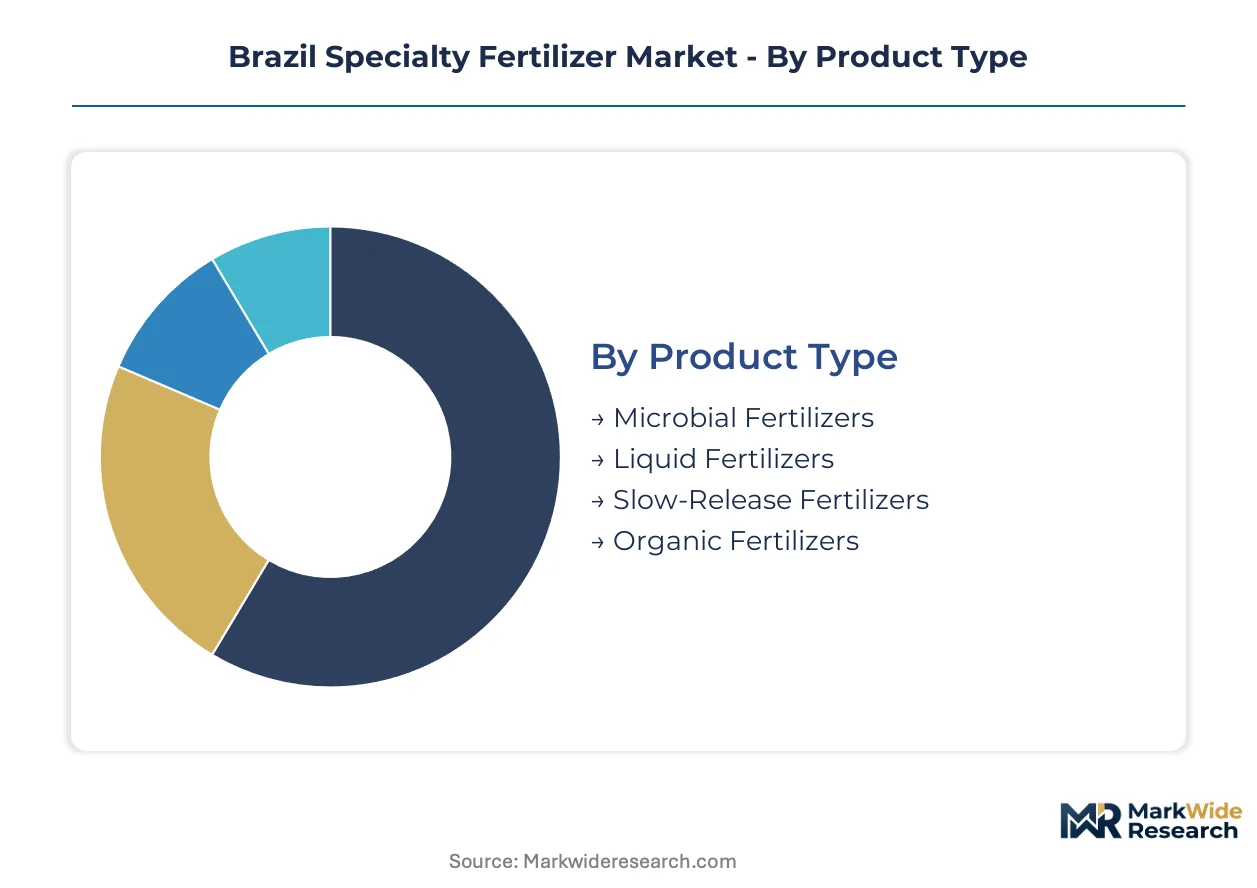
Brazil's specialty fertilizer market fragments across four critical dimensions that determine how formulators capture value. Product chemistry dictates margin pools, while application setting shapes regulatory exposure and distribution economics.
Product Type:
Buyers prioritize nutrient delivery precision and labor reduction when selecting formulation chemistry, with coating technology and microbial content commanding premium positioning over commodity alternatives.
- Microbial Fertilizers:Biological nitrogen fixation and phosphate-solubilizing inoculants reduce synthetic input dependency for Mato Grosso soybean growers facing tightening watershed protection mandates in Goiás. ANVISA residue documentation requirements and MAPA origin certification bottlenecks constrain import velocity despite accelerating farmer adoption.
- Liquid Fertilizers:Water-soluble concentrates enable foliar application and fertigation integration with precision agriculture hardware on mechanized farms exceeding 5,000 hectares. Coastal terminal infrastructure investments by Yara International ASA and domestic blenders are bypassing inland bagging operations to capture time-sensitive topdressing windows.
- Slow-Release Fertilizers:Polymer-coated formulations regulate nutrient release through osmotic diffusion calibrated to soil temperature profiles. São Paulo sugarcane mills with mechanized green-cane harvesting systems have accelerated uptake since residue burning prohibitions took full effect.
- Organic Fertilizers:Compost and manure-derived products face certification bottlenecks under Brazilian organic agriculture regulations. ANVISA heavy metal maximum contaminant limits disqualify imported compost products from key coastal blending facilities.
Microbial fertilizers lead on momentum; slow-release formulations lead on scale in high-value perennial crops.
Application:
Volume concentration and application precision requirements vary sharply across cultivation settings, with open-field row crops dominating tonnage and controlled environments commanding formulation premiums.
- Crops:Soybean, sugarcane, and cotton production across the Cerrado corridor from Goiás through western Bahia absorbs the majority of micronutrient-enriched and controlled-release tonnage. Variable-rate application hardware penetration at cooperatives in the Primavera do Leste-Sorriso corridor is consolidating procurement into performance-guaranteed manufacturer contracts.
- Greenhouse:Protected cultivation in São Paulo state and the Central-West demands water-soluble and foliar formulations with exacting micronutrient ratios for high-value vegetable and flower production.
- Turf and Ornamental:Golf course and landscape maintenance in coastal metropolitan zones utilizes slow-release and liquid formulations where labor cost reduction justifies premium positioning.
- Hydroponics:Soilless cultivation systems for leafy greens and tomatoes require complete nutrient solutions with pH-buffering capacity, representing a niche but high-margin segment concentrated near urban consumption centers.
Crops dominate absolute volume; greenhouse applications sustain the steepest expansion trajectory as protected area expands.
End User:
Farm scale and technical sophistication determine purchasing behavior, with large mechanized operations consolidating procurement and fragmented smallholders remaining tethered to distributor networks.
- Agriculture:Commercial row crop and perennial producers in Mato Grosso, Goiás, and São Paulo states drive demand for precision-formulated products with satellite-verified yield outcome guarantees.
- Horticulture:Vegetable and fruit producers in Minas Gerais and Bahia utilize micronutrient foliar blends and controlled-release coatings for high-value export crops.
- Landscape Contractors:Municipal and commercial maintenance operations in southeastern metropolitan zones source bulk liquid and slow-release formulations through direct manufacturer relationships.
- Home Gardeners:Retail-packaged specialty products reach this segment through garden centers and online channels, representing low volume but brand-building exposure.
Agriculture anchors revenue concentration; horticulture delivers the fastest margin expansion.
Distribution Channel:
Channel selection reflects farm scale, urgency requirements, and technical service intensity, with direct manufacturer relationships displacing inventory-heavy distributor models at the top end.
- Agricultural Cooperatives:Buying committees at Mato Grosso farming cooperatives are consolidating annual procurement into single-source contracts with embedded agronomic service providers.
- Garden Centers:Urban and peri-urban retail outlets serve home gardeners and small-scale horticulture operations with packaged specialty formulations.
- Online Stores:E-commerce penetration remains limited to specialty micronutrient products and microbial inoculants where technical documentation and origin verification are standardized.
- Retail Outlets:Traditional rural supply stores with inventory-heavy models are losing share to direct relationships where manufacturers embed agronomists with farm management software platforms.
Agricultural cooperatives capture the largest transaction values; online stores are climbing the fastest despite regulatory documentation friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cerrado agricultural corridor anchors Brazil's specialty fertilizer consumption, with mechanized soybean and cotton operations driving micronutrient-enriched formulation demand across Mato Grosso, Goiás, and western Bahia.
São Paulo
Sugarcane mills with mechanized green-cane harvesting systems absorb polymer-coated controlled-release fertilizers at accelerating rates since residue burning prohibitions took full effect. ANVISA's evolving maximum residue limit protocols tighten compliance verification requirements for all import and domestic manufacturing channels. São Paulo state mill operators in the Ribeirão Preto-Araraquara cluster have adopted single-pass nutrient delivery systems that displace conventional split-application urea suppliers.
Mato Grosso
Precision agriculture penetration at cooperatives in the Primavera do Leste-Sorriso corridor creates concentrated demand for foliar micronutrient blends calibrated to variable-rate application maps. State environmental secretariat watershed protection rules mandate buffer-zone nutrient management plans that create service-contract opportunities for precision application bundled with product supply. Buying committees at farming cooperatives exceeding 10,000 hectares consolidate annual procurement into single-source contracts with satellite-verified yield outcome guarantees.
Goiás
Biological nitrogen fixation technologies for legume producers accelerate adoption of microbial inoculants as synthetic input dependency faces tightening watershed protection mandates. MAPA's Instrução Normative No. 27 shapes registration timelines for controlled-release coatings targeting regional sugarcane and coffee growers. The state's Central-West position within the Cerrado belt positions Goiás blenders as distribution hubs for sulfate-based formulations reformulated around polyhalite scarcity.
Minas Gerais
Phosphate specialty output anchors through integrated mine-to-field operations supplying micronutrient-enriched starter fertilizers for coffee and dairy pasture renovation. ANVISA heavy metal maximum contaminant limits for organic-derived fertilizers extend certification timelines for imported compost products. The Triângulo Mineiro region's cotton and soybean expansion from degraded pastureland creates first-mover advantage for specialty formulators in previously uncultivated fringe zones.
Bahia
Western Bahia's cotton and soybean conversion from degraded Cerrado pastureland generates demand for micronutrient-enriched starter fertilizers in frontier agricultural zones. Coastal terminal infrastructure investments enable direct-to-farm liquid fertilizer delivery bypassing inland bagging operations. The Barreiras-Luís Eduardo Magalhães corridor represents the fastest-expanding addressable market for precision-formulated products with performance guarantees tied to farm management software platforms.
Brazil Specialty Fertilizer Market Competitive Environment
Capacity expansion dominates the current landscape as coastal terminal investments and controlled-release coating facilities reshape distribution economics. The market structure concentrates around integrated multinationals with captive mineral supply, regional blenders with regulatory affairs specialization, and biological input specialists navigating certification bottlenecks. Three archetypes define competitive positioning: mine-to-field phosphate operators, coastal water-soluble distributors, and microbial inoculant formulators. M&A activity and technology licensing partnerships represent the dominant competitive moves as players seek polymer coating calibration capabilities and liquid infrastructure access.
Within the integrated multinational tier, Yara International ASA and OCP Brasil exemplify divergent strategic positions. Yara leverages Scandinavian coastal blending heritage to anchor water-soluble and foliar product distribution through terminal infrastructure investments. OCP Brasil represents mine-to-field phosphate integration with upstream mineral control over specialty output in Minas Gerais and São Paulo. ICL Group Ltd occupies a technology-specialist position where controlled-release coating expertise targets sugarcane and coffee nutrient uptake cycles. These three entities collectively illustrate how mineral access, coastal logistics, and formulation technology define separable competitive vectors in Brazil's specialty fertilizer market.
| Leading Market Players |
|---|
| Yara International ASA |
| Nutrien |
| K+S Aktiengesellschaft |
| Indorama Fertilizer |
| OCP Brasil |
| Sociedad Quimica y Minera de Chile SA |
| ICL Group Ltd |
| Adufértil |
| The Mosaic Company |
| Others |
Value Chain & Pricing Dynamics
Mato Grosso state environmental secretariat watershed protection mandates gate qualified supply for precision application services and premium-tier pricing access for runoff-monitoring bundles. ANVISA residue documentation requirements and MAPA origin certification bottlenecks further stratify formulators by compliance capability, concentrating margin capture among blenders with dedicated regulatory affairs functions.
Pricing Analysis
Input-cost pass-through from polyhalite scarcity and UK-based sulfate of potash feedstock concentration shapes contract-based long-term offtake pricing for Brazilian blenders. Price differentiation rests on coating technology calibration and ANVISA certification tier, with polymer-coated controlled-release formulations commanding substantial premiums over commodity urea. Cost compression in conventional split-application nitrogen is intensifying because labor and fuel savings from single-pass nutrient delivery displace legacy suppliers. Large mechanized cooperatives in the Primavera do Leste-Sorriso corridor exhibit lowest price sensitivity due to yield-outcome guarantees, while fragmented smallholders tethered to retail distributor networks face acute margin pressure.
Supply Chain Analysis
Direct-to-farm liquid delivery channels handle hyperscale buyer demand from Mato Grosso and Goiás cooperatives exceeding 10,000 hectares, bypassing inland bagging operations. Geographic supply concentration centers on the United Kingdom for polyhalite feedstock, Morocco for phosphate rock via OCP Brasil's integrated operations, and Scandinavia for Yara International ASA's coastal blending heritage. Raw material dependencies hinge on sulfate of potash, polymer coating substrates, and microbial inoculant strains. Single-source vulnerability to the UK mine operator exposes Brazilian blenders to shipping cost volatility and currency fluctuation risk. Distribution runs through agricultural cooperatives consolidating procurement, coastal terminals enabling bulk liquid delivery, and embedded agronomic service providers displacing inventory-heavy retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's specialty fertilizer market offers sustained margin expansion as precision agriculture adoption shifts procurement toward performance-guaranteed manufacturer contracts and away from commodity distributors. Labor and fuel savings from single-pass nutrient delivery create structural cost-down advantages for controlled-release formulations.
For Market Incumbents: Deploy coastal terminal infrastructure as the primary lever to defend against Yara International ASA's water-soluble distribution dominance and OCP Brasil's mine-to-field phosphate integration. Backward integration into polymer coating calibration capabilities protects against technology licensing dependency, while capacity addition in western Bahia's Barreiras-Luís Eduardo Magalhães corridor captures first-mover advantage in frontier Cerrado conversion zones. ANVISA's evolving residue thresholds threaten commodity importers lacking dedicated regulatory affairs functions. For New Entrants and Emerging Players: Microbial inoculant formulation expertise offers a technology-first wedge into biological nitrogen fixation demand from Goiás legume producers facing tightening watershed protection mandates. Western Bahia's cotton and soybean conversion from degraded pastureland represents the most penetrable geography, with direct-to-farm liquid delivery partnerships as the optimal go-to-market angle bypassing cooperative buying committee consolidation. For Investors and Strategic Acquirers: Roll-up economics work for regional blenders with regulatory affairs specialization because MAPA Instrução Normative No. 27 compliance timelines create acquisition targets struggling with documentation packages. Long-term viability over the medium-term projection horizon favors controlled-release coating technology and microbial inoculant platforms over commodity nitrogen. Watch for inflection in ANVISA maximum residue limit protocol revisions that would accelerate disqualification of legacy products with incomplete micronutrient disclosure.| Strategic Initiative | Industry Significance |
|---|---|
| Coastal Terminal Infrastructure Investment | Yara International ASA's Scandinavian heritage anchors direct-to-farm liquid delivery bypassing inland bagging cost structures. |
| Controlled-Release Coating Facility Expansion | ICL Group Ltd's polymer degradation calibration targets São Paulo sugarcane mill single-pass nutrient delivery adoption. |
| Microbial Inoculant Platform Acquisition | Biological nitrogen fixation technologies reduce synthetic input dependency for Goiás watershed compliance. |
| Regulatory Affairs Function Buildout | ANVISA residue documentation capabilities capture shelf space from commodity importers struggling with MAPA labeling standards. |
| Western Bahia Distribution Hub Establishment | Barreiras-Luís Eduardo Magalhães corridor frontier conversion creates first-mover advantage for micronutrient-enriched starter fertilizers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with secondary validation. Agronomic service providers at Mato Grosso cooperatives, MAPA regulatory affairs officials, coastal terminal operations managers, polymer coating R&D directors, and precision agriculture hardware integration specialists contributed firsthand operational perspective. Secondary sources included MAPA fertilizer registration databases, ANVISA contaminant limit protocols, customs and trade flow records, and SEC filings from listed multinationals. Bottom-up volume modeling from crop-specific application rates and top-down macroeconomic triangulation anchored the analytical framework.
Comparable-period anchoring to historical specialty fertilizer adoption curves in mechanized soybean and sugarcane systems informed the projection horizon. Segmentation dimensions spanned product chemistry, application setting, farm scale tier, and distribution channel structure across the modeling period. CAGRs derived from trend extrapolation adjusted for regulatory enforcement intensity and precision agriculture hardware penetration curves. Polyhalite supply concentration and ANVISA protocol evolution served as key industry-specific forecast inputs.
The model holds under stable MAPA registration timelines and continued precision agriculture investment; deviation in ANVISA residue threshold stringency or polyhalite shipping cost volatility would shift commercialization trajectories. Forecasts reflect base-case assumptions around watershed protection mandate enforcement and cooperative procurement consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Fertilizer Tester Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
Organic Fertilizers Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Blue-Green Algae Fertilizer Market