
 Controlled and Slow Release Fertilizers Market | 2026-2036
Controlled and Slow Release Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Controlled and Slow Release Fertilizers Market Analysis
Multi-source procurement of coated urea feedstock is expanding as manufacturers hedge against sulfur and polymer resin volatility. Nutrien Ltd. leverages its integrated potash and nitrogen network to secure captive supply of base materials for sulfur-coated production. Yara International ASA anchors its European position through R&D intensity in polymer coating technologies. ICL Group Ltd. specializes in precision-blended formulations for turf management and horticulture channels.
Controlled and slow release fertilizers are nutrient delivery systems engineered with physical or chemical barriers — sulfur coatings, polymer membranes, or urea-formaldehyde matrices — that modulate dissolution rates across 30- to 180-day windows, reducing leaching losses and aligning nitrogen availability with crop uptake curves. Polymer-coated variants command premium positioning due to superior release predictability in variable soil moisture conditions, while sulfur-coated urea occupies volume leadership in broad-acre grain applications. Agriculture dominates end-user consumption, though horticulture and turf management segments generate disproportionate margin pools through specification-driven procurement.
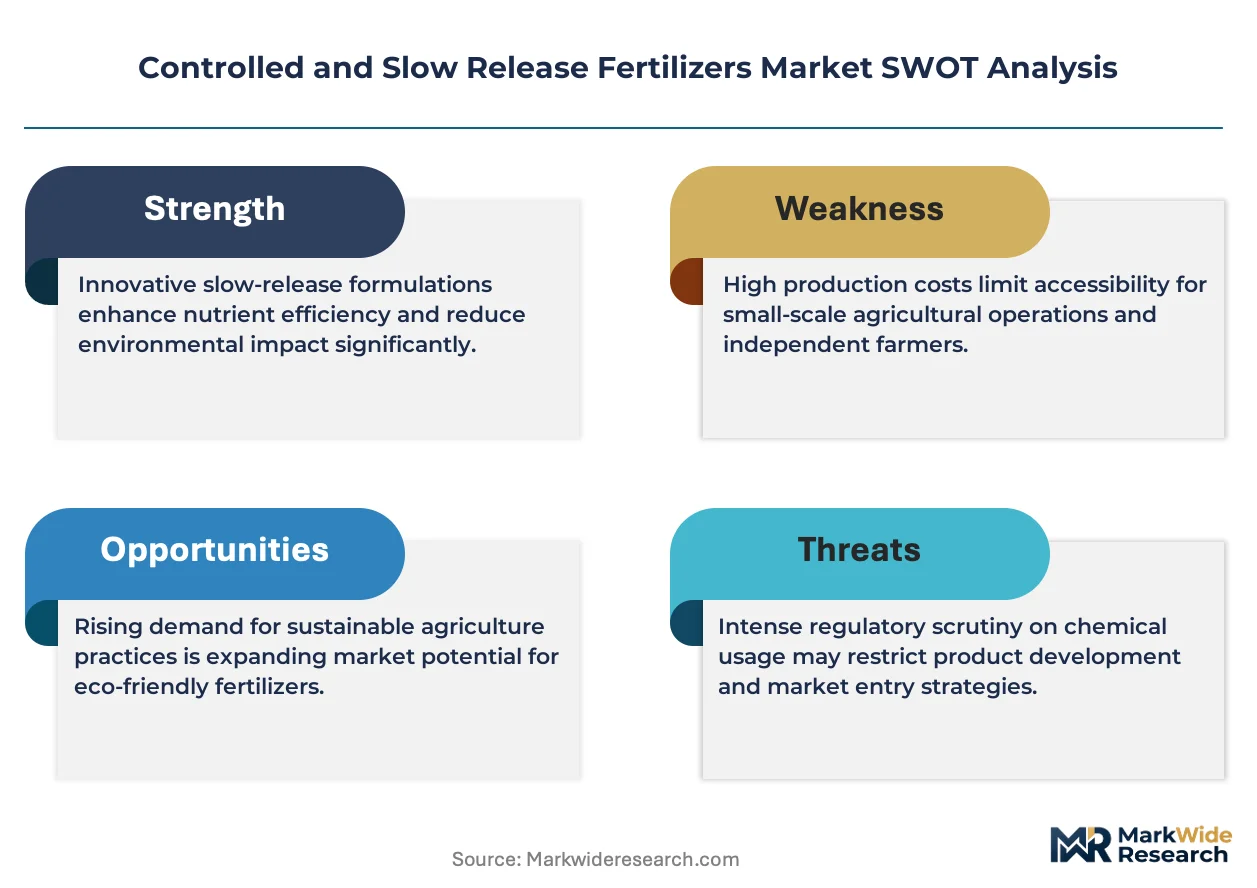
EPA water quality standards under the Clean Water Act, California's Irrigated Lands Regulatory Program, and China's MEE soil pollution prevention rules are tightening permissible nitrate discharge thresholds, directly elevating compliance-driven demand for slow-release formulations. The EU Green Deal's Farm to Fork strategy further mandates 20% fertilizer reduction targets that only controlled-release technologies can satisfy without yield sacrifice. Stakeholders must monitor how carbon border adjustment mechanisms reshape the cost calculus of imported sulfur and polymer feedstocks against regional manufacturing.
Market Dynamics
Polymer-coated urea formulations are capturing procurement share from sulfur-coated alternatives as specialty crop operations prioritize release predictability under tightening nitrate discharge limits.
Growth Catalysts
- California's Irrigated Lands Regulatory Program:Specialty vegetable and fruit producers in the Central Valley are converting acreage to controlled-release systems to meet groundwater nitrate thresholds.
- Polymer membrane precision:Moisture-activated diffusion coatings now match nitrogen release curves to crop phenology, reducing fertilizer rates without yield penalty.
- Brazilian precision agriculture clusters:Mato Grosso and São Paulo high-value fruit operations are concentrating demand for pelletized controlled-release formulations.
Market Restraints
- Sulfur and polymer resin volatility:Feedstock cost swings compress margin predictability for coating manufacturers dependent on petrochemical supply chains.
- Technical limitation in variable rainfall zones:Polymer-coated products exhibit release rate drift under erratic soil moisture, limiting adoption in rain-fed broad-acre grain systems.
- Substitution threat from stabilized nitrogen:Nitrification and urease inhibitors offer lower-cost leaching reduction for price-sensitive commodity crop producers.
Strategic Opportunities
- Underpenetrated Indian horticulture:Maharashtra and Karnataka grape and pomegranate growers remain below 15% controlled-release penetration despite water stress.
- EU Green Deal Farm to Fork mandate:The 20% fertilizer reduction target creates compliance-driven demand that only controlled-release technologies can satisfy.
- Drone-enabled variable-rate application:Convergence of aerial dispersal platforms with GPS-mapped soil zones enables site-specific controlled-release pellet placement.
Industry Challenges
- Coating technician skill scarcity:Polymer formulation and quality control expertise concentrates among legacy agrichemical engineering programs in Germany and the Netherlands.
- ISO 18644 certification timelines:Slow-release classification testing protocols delay product commercialization by 18-24 months in regulated export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Controlled and Slow Release Fertilizers Market |
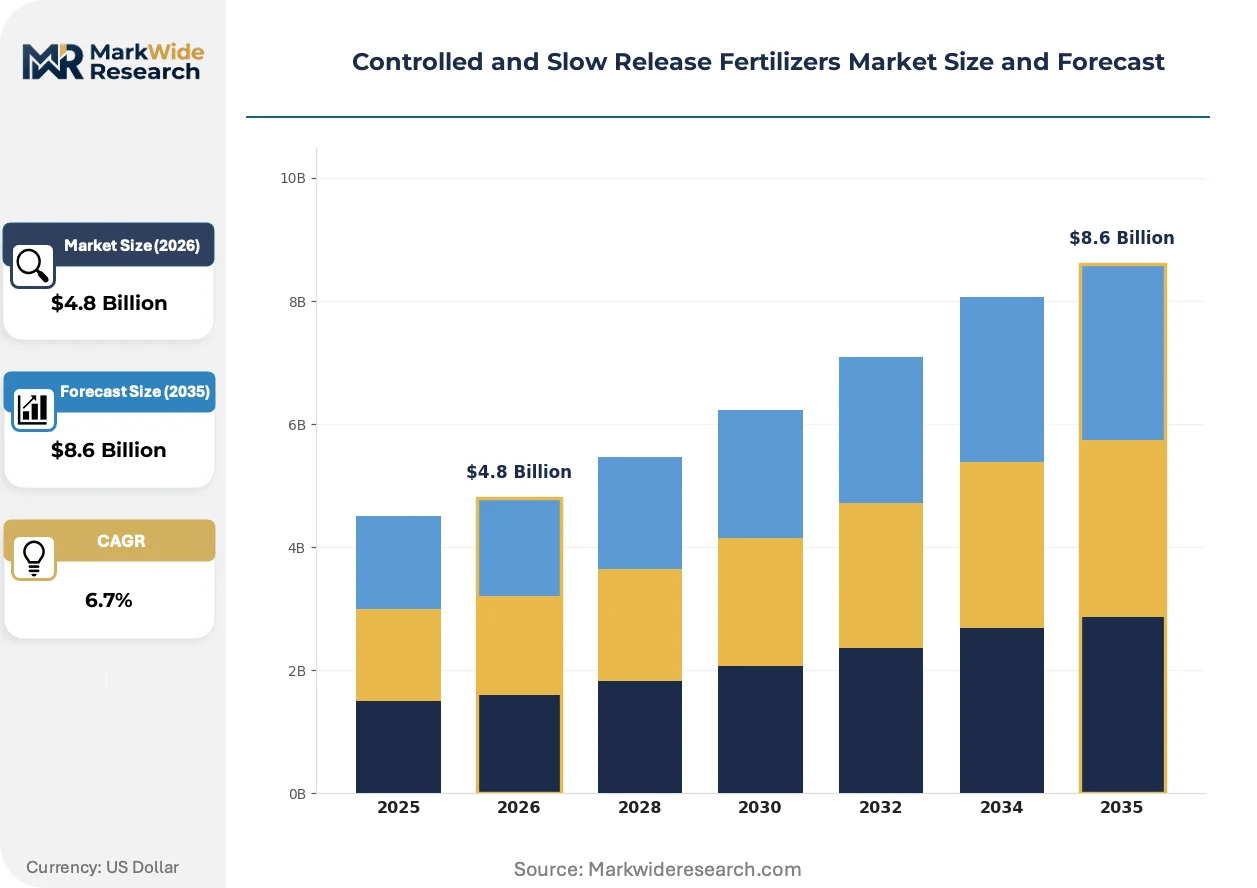
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea-Formaldehyde, Sulfur-Coated Urea, Polymer Coated, Natural Organic Application: Agriculture, Lawn & Garden, Horticulture, Turf Management Formulation: Granular, Liquid, Tablets, Controlled-Release Pellets End User: Commercial Growers, Home Gardeners, Agricultural Cooperatives, Distributors |
| Companies Covered | The Mosaic Company, Haifa Group, Nutrien Ltd., SQM (Sociedad Química y Minera de Chile), Scotts Miracle-Gro Company, Yara International ASA, Kingenta Ecological Engineering Group Co., Ltd., Koch Industries, Inc., ICL Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Controlled and Slow Release Fertilizers Market Emerging Trajectories
Bio-based coating materials and digital application platforms are converging to redefine how nutrient delivery systems integrate with precision farming infrastructure.
Biodegradable polymer coatings derived from lignin and starch matrices are decentralizing supply chain dependence on petroleum-derived resins. European horticulture cooperatives are piloting these formulations in greenhouse tomato and pepper operations. The shift is compressing carbon footprint differentials between regional and imported fertilizer sources.
China's MEE soil pollution prevention rules are mandating county-level nitrate monitoring in 15 major agricultural provinces. Fertilizer distributors must now document slow-release product efficacy to maintain operating licenses. The compliance burden favors polymer-coated urea with certified 90-day release profiles over conventional blends.
Cooperative procurement aggregators in Florida and Spain are consolidating smallholder demand into specification-driven tenders. These buying pools bypass traditional wholesale distributors and negotiate directly with coating manufacturers for customized NPK ratios. The disintermediation is most advanced in Mediterranean citrus and berry production clusters.
Controlled and Slow Release Fertilizers Market Segmentation
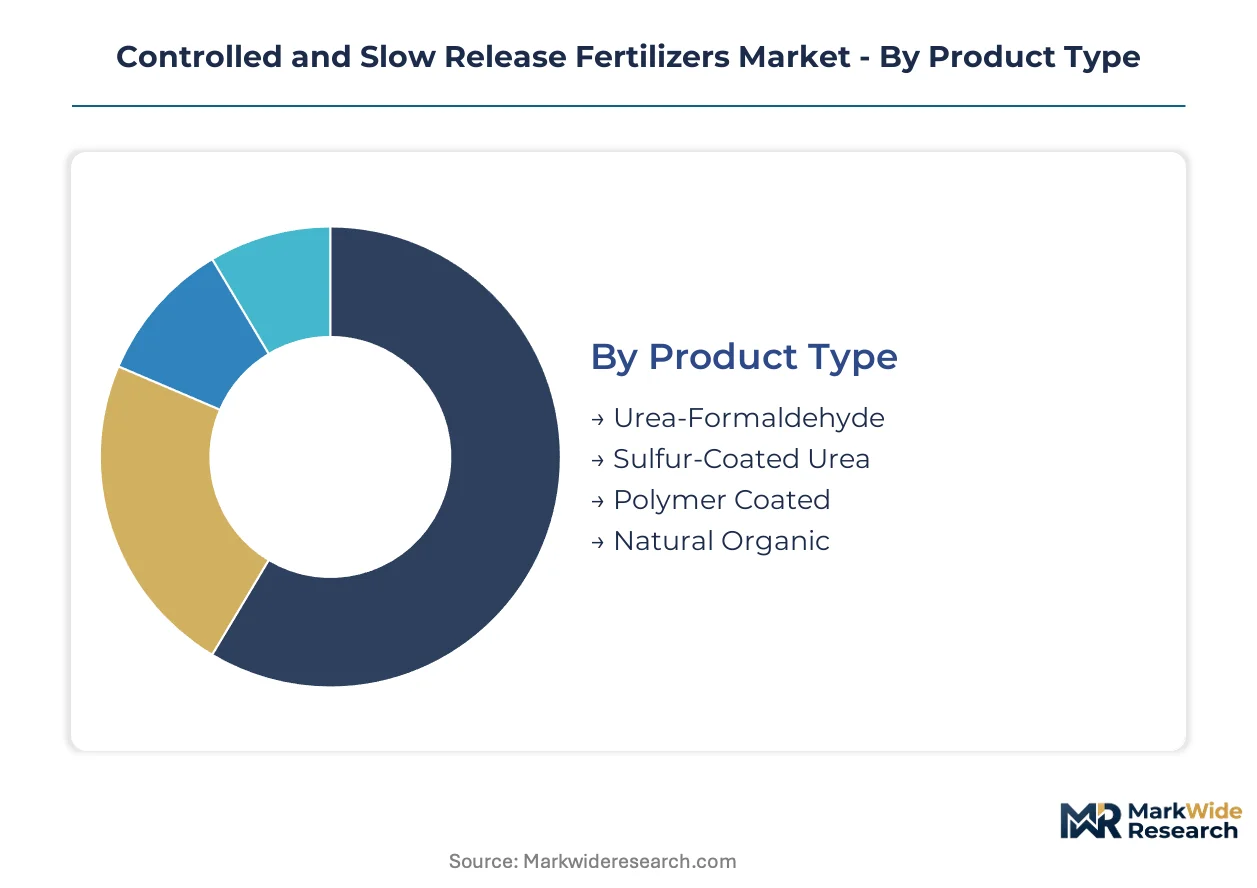
Segmentation in controlled and slow release fertilizers reveals how coating chemistry, application setting, and procurement channel shape margin architecture. Manufacturers configure production lines around these divides, with polymer-coated variants commanding premium positioning in specialty crop channels while sulfur-coated formulations dominate commodity grain procurement.
Product Type:
Supply concentration in polymer resin and sulfur feedstock determines which coating technologies achieve scale economics.
- Polymer Coated:Moisture-activated diffusion membranes deliver nitrogen across 60- to 180-day windows with minimal release drift. California Central Valley vegetable producers specify these formulations to comply with Irrigated Lands Regulatory Program groundwater thresholds.
- Sulfur-Coated Urea:Petroleum-derived sulfur barriers release nutrients through microbial degradation and coating fracture. Broad-acre corn and wheat operations in Brazil's Mato Grosso cluster favor this chemistry for cost-efficient leaching reduction at scale.
- Urea-Formaldehyde:Methylene-urea chains hydrolyze slowly in warm, moist soils. Turf management contractors specify these methylene urea matrices for golf course fairway maintenance.
- Natural Organic:Plant-derived protein and humic acid matrices biodegrade without synthetic polymer residues. Organic-certified operations in Florida's berry cooperatives source these formulations for export compliance.
Today's leader: Polymer Coated. Tomorrow's challenger: Natural Organic.
Application:
Margin stratification separates specification-driven horticulture procurement from price-sensitive broad-acre agriculture.
- Agriculture:Row crop and permanent crop operations consume volume share, with Brazilian precision agriculture clusters and Indian horticulture expansion driving pelletized formulation demand.
- Horticulture:Greenhouse tomato and pepper producers in Spain's Almería cluster negotiate directly with coating manufacturers for customized NPK ratios, bypassing wholesale distributors.
- Turf Management:Golf course superintendents and municipal park managers prioritize uniform greening without surge growth. ICL Group Ltd. concentrates precision-blended formulations for this channel.
- Lawn & Garden:Retail-packaged consumer products emphasize application convenience over release precision. Home improvement chains stock seasonal formulations with 30- to 60-day windows.
Agriculture captures volume leadership. Horticulture generates the steepest expansion trajectory through cooperative procurement consolidation.
Formulation:
Physical form dictates application equipment compatibility and distribution logistics intensity.
- Controlled-Release Pellets:Uniform diameter spheres enable drone-enabled variable-rate dispersal across GPS-mapped soil zones. São Paulo fruit operations pilot aerial application platforms with these formulations.
- Granular:Irregular crushed and screened particles suit conventional broadcast spreaders. Sulfur-coated urea granules dominate Midwestern US corn belt procurement through agricultural cooperatives.
- Liquid:Suspended polymer-encapsulated nutrients integrate with fertigation infrastructure. Florida citrus groves with micro-sprinkler systems specify liquid slow-release for root zone precision.
- Tablets:Compressed single-plant doses target container nursery stock. Bonsai and ornamental producers in Japan's Saitama Prefecture import tablet formulations for controlled dosing.
Granular formulations anchor current volume. Controlled-Release Pellets are gaining share fastest through precision agriculture convergence.
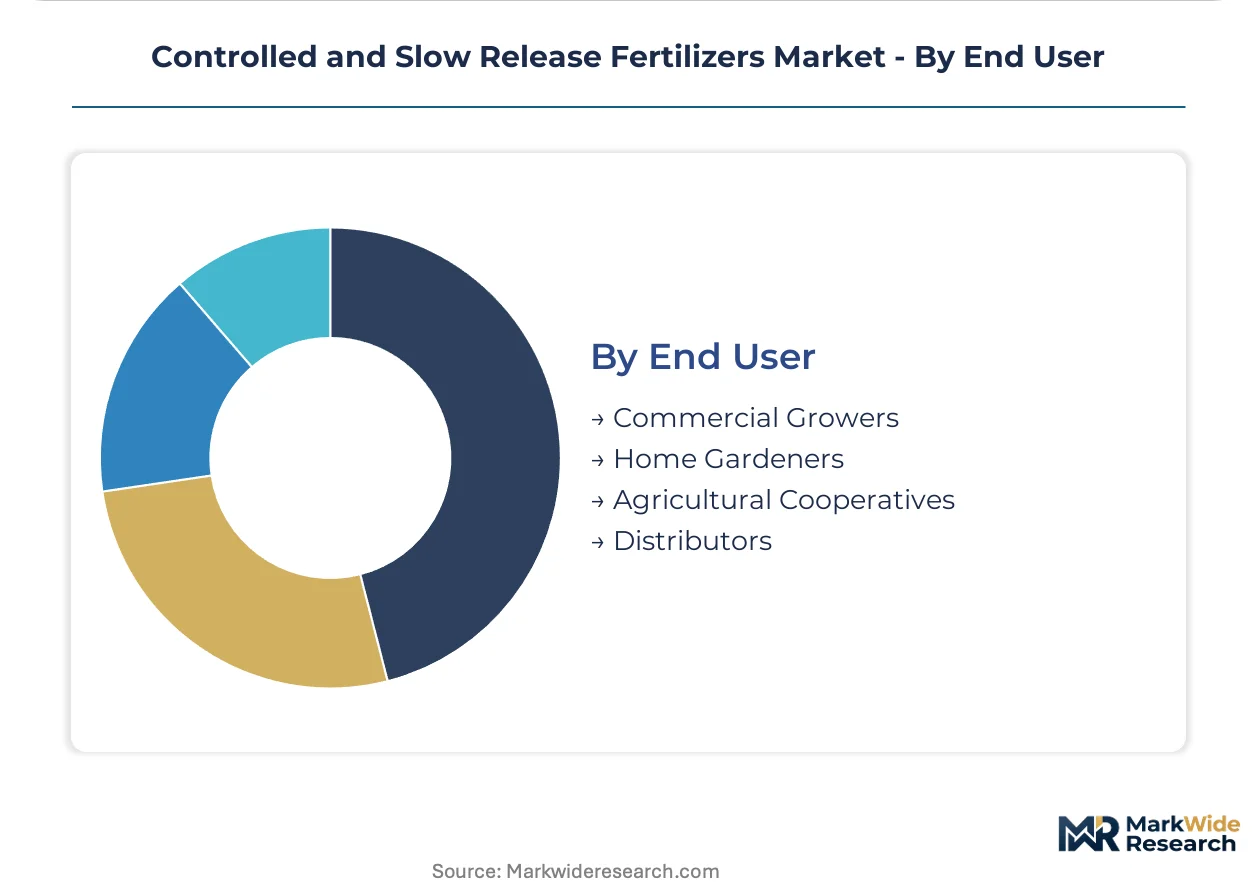
End User:
Procurement scale and technical sophistication separate commercial specification from retail convenience purchasing.
- Commercial Growers:Large-scale vegetable and fruit operations employ agronomists who evaluate release curve data. California's Central Valley specialty crop producers maintain direct supplier relationships for customized coating specifications.
- Agricultural Cooperatives:Member-owned buying pools aggregate smallholder demand into tender volumes. Maharashtra grape growers in India negotiate through cooperatives for polymer-coated urea with certified 90-day profiles.
- Distributors:Regional fertilizer dealers stock inventory across multiple coating types to serve mixed farming clienteles. China's county-level distributors now document slow-release efficacy to maintain operating licenses under MEE soil pollution rules.
- Home Gardeners:Retail consumers select branded products based on application interval claims and package size. Garden center merchandising emphasizes season-long feeding convenience.
Commercial Growers command specification authority today. Agricultural Cooperatives are consolidating procurement power fastest through disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley vegetable belt generates concentrated procurement pull for polymer-coated urea as groundwater nitrate thresholds tighten. Specialty crop producers across four continents are converting acreage to controlled-release systems to meet discharge compliance deadlines.
United States
California's Irrigated Lands Regulatory Program compels Central Valley specialty vegetable and fruit growers to adopt certified slow-release formulations. EPA water quality standards under the Clean Water Act elevate compliance costs for conventional fertilizer discharge. Florida's citrus belt and berry cooperatives concentrate demand for polymer-coated products with documented 90-day release profiles.
Brazil
Mato Grosso broad-acre grain operations and São Paulo high-value fruit clusters drive divergent formulation demand. ANVISA maintains fertilizer registration protocols that favor imported polymer-coated urea with certified efficacy data. Precision agriculture adoption in São Paulo's citrus and sugarcane districts concentrates procurement for pelletized controlled-release systems.
China
MEE soil pollution prevention rules mandate county-level nitrate monitoring across 15 major agricultural provinces. Shandong Peninsula greenhouse vegetable producers and Yangtze River Delta rice operations face divergent moisture conditions that favor distinct coating chemistries. Fertilizer distributors must document slow-release product efficacy to maintain operating licenses under tightening enforcement.
India
Maharashtra grape and pomegranate growers remain below 15% controlled-release penetration despite acute water stress in Nashik and Sangli districts. BIS certification requirements for specialty fertilizer imports create procedural delays for European polymer-coated formulations. Karnataka's coffee and spice belt generates emerging demand for sulfur-coated urea in terraced hillside applications.
Germany
EU Green Deal Farm to Fork strategy mandates 20% fertilizer reduction targets that only controlled-release technologies can satisfy without yield sacrifice. ECHA REACH compliance requirements for polymer resin feedstocks elevate formulation costs against sulfur-coated alternatives. Bavarian hop growers and Lower Saxony potato operations specify precision-blended coatings to match nitrogen release with crop phenology curves.
Controlled and Slow Release Fertilizers Market Vendor Landscape
Global majors compete with regional champions across coating technology specialization and feedstock integration depth. The vendor base separates into three tiers: integrated nutrient producers with captive sulfur and polymer supply, independent coating specialists serving horticulture channels, and regional compounders addressing price-sensitive broad-acre grain markets. Dominant competitive moves include backward integration into polymer resin production and strategic partnerships with precision agriculture platform providers.
Within the integrated nutrient tier, Nutrien Ltd. and Yara International ASA exemplify feedstock-backed coating capabilities. ICL Group Ltd. occupies a specialist position in precision-blended turf and horticulture formulations. Kingenta Ecological Engineering Group Co., Ltd. represents the regional champion archetype serving domestic Chinese specialty crop channels. Koch Industries, Inc. anchors a diversified industrial position spanning fertilizer and petrochemical feedstock verticals.
| Leading Market Players |
|---|
| The Mosaic Company |
| Haifa Group |
| Nutrien Ltd. |
| SQM (Sociedad Química y Minera de Chile) |
| Scotts Miracle-Gro Company |
| Yara International ASA |
| Kingenta Ecological Engineering Group Co., Ltd. |
| Koch Industries, Inc. |
| ICL Group Ltd. |
| Others |
Supply Flow & Price Mechanics
California's Irrigated Lands Regulatory Program mandates for certified slow-release formulations are forcing coating manufacturers to absorb polymer resin volatility while maintaining premium positioning for specialty crop channels.
Pricing Analysis
Petrochemical feedstock pass-through dynamics dominate margin architecture across coating tiers. Three-tier pricing structure across premium, standard, and economy levels separates polymer-coated urea with ISO 18644 certification from sulfur-coated alternatives and uncoated commodity blends. Cost compression in sulfur-coated segments is intensifying because nitrification inhibitor substitutes undercut leaching-reduction value propositions. Agricultural cooperatives in Brazil and India exhibit highest price sensitivity; California commercial growers with compliance deadlines show lowest.
Supply Chain Analysis
Direct-to-horticulture channels handle specification-driven procurement from Almería greenhouse cooperatives and Florida berry growers, bypassing wholesale distributors. Manufacturing concentrates in Germany, the Netherlands, and China, drawing from petroleum-derived sulfur, polymer resins, and urea feedstock. Single-source vulnerability in polymer resin supply from petrochemical complexes creates exposure to energy price shocks. Distribution runs through county-level fertilizer dealers in regulated markets and cooperative buying pools in specialty crop zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal Farm to Fork mandates and China's MEE soil pollution rules structurally expand addressable demand for compliant coating technologies.
For Market Incumbents: Lock in captive sulfur and polymer supply through backward integration into petrochemical feedstocks or long-term offtake agreements with resin producers. Secure ISO 18644 certification pipelines early to preempt 18-24 month commercialization delays that favor entrenched competitors with established testing relationships. For New Entrants and Emerging Players: Bio-based coating formulations from lignin and starch matrices offer technology-first entry into European horticulture cooperatives seeking carbon footprint differentiation. Target Maharashtra and Karnataka grape operations in India where controlled-release penetration sits below 15% despite acute water stress. Lead with drone-enabled variable-rate application partnerships to bypass established distribution. For Investors and Strategic Acquirers: Asymmetric upside sits with regional compounders possessing BIS certification pathways and direct cooperative relationships in underpenetrated Indian horticulture. Long-term viability hinges on coating technology portfolios that satisfy tightening nitrate discharge thresholds without yield sacrifice. Watch for county-level distributor license revocations under China's MEE enforcement as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Captive supply secures margin stability against petrochemical volatility for coating manufacturers. |
| ISO 18644 Certification Pre-Investment | Early testing protocol engagement compresses commercialization timelines in regulated export markets. |
| Drone-Enabled Variable-Rate Application Partnership | Aerial dispersal platforms open precision agriculture channels in São Paulo fruit operations. |
| Bio-Based Coating R&D Program | Lignin-derived matrices align with EU Green Deal carbon footprint requirements for horticulture. |
| Cooperative Procurement Aggregator Alliance | Direct relationships with Almería and Florida buying pools bypass wholesale margin capture. |
Methodological Framework
Multiple input streams — primary interviews with coating plant managers, agronomists at commercial growing operations, and fertilizer distribution channel partners; secondary validation through customs trade data, SEC filings of integrated nutrient producers, and EPA water quality compliance records — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Historical consumption patterns across polymer-coated, sulfur-coated, urea-formaldehyde, and natural organic chemistries were cross-referenced against panel input from procurement directors at agricultural cooperatives to derive expansion trajectories over the projection horizon. Segmentation dimensions modeled include coating technology, application setting, physical formulation, and end-user procurement scale. CAGRs were computed from annualized growth rate analysis of segment-level demand curves, incorporating nitrate discharge regulatory phase-in schedules and precision agriculture adoption curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polymer resin price volatility, substitution acceleration from stabilized nitrogen inhibitors, and regulatory enforcement variance across China's provincial MEE implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
South America Fertilizers Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
GCC Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market