
 Potash Market | 2026-2036
Potash Market Size, Share, and Industry Trends Forecast 2026-2036
Potash Market Analysis
Canada's Saskatchewan potash corridor is tilting global supply dynamics through incremental capacity expansions. Nutrien Ltd. leverages its integrated mine-to-farm logistics network across North American grain belts. The Mosaic Company anchors its position through phosphate-potash co-location economics in Florida and Saskatchewan. Uralkali competes on rail-export cost structures into Brazilian and Asian port terminals.
Potash denotes potassium-bearing salts, primarily potassium chloride (KCl, 60-62% K2O equivalent), extracted through conventional underground mining or solution mining of evaporite deposits for agricultural fertilization. Muriate of potash dominates commercial trade due to its concentrated potassium content and cost-effective bulk handling properties. Crop nutrient applications generate the deepest margin pools given recurring seasonal demand tied to planting cycles. Potash sulfate commands premium positioning in chloride-sensitive fruit and vegetable segments where sulfur co-nutrition justifies higher input costs.
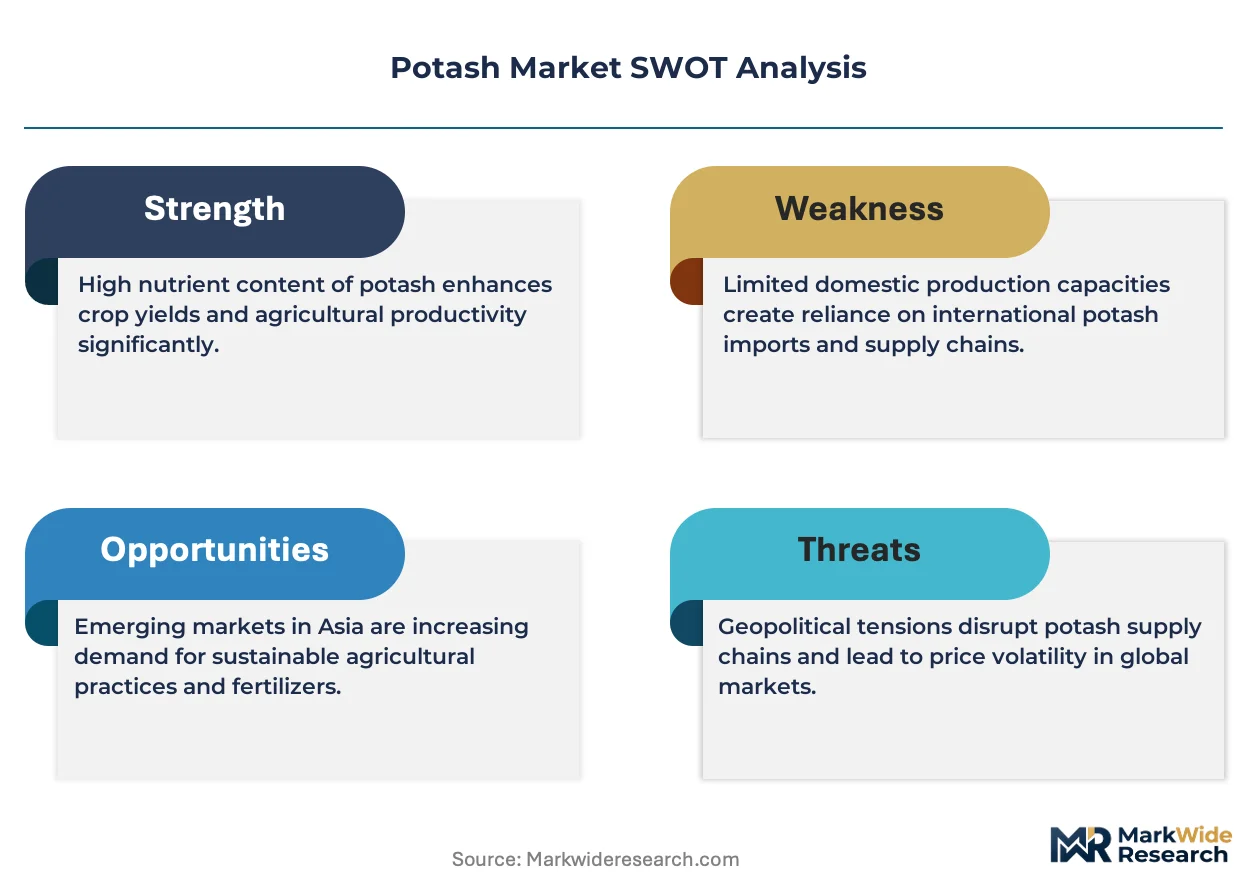
Canada's provincial environmental regulators, the EPA under the US Clean Water Act, and Brazil's MAPA fertilizer registration requirements collectively shape product certification timelines and market access conditions. Saskatchewan's potash royalty frameworks directly influence greenfield project economics and investment sequencing. Stakeholders must monitor how carbon border adjustment mechanisms and Scope 3 emissions accounting reshape contract terms between miners and agricultural cooperatives.
Market Dynamics
Saskatchewan's royalty framework and Brazil's MAPA fertilizer registration timelines are compressing investment cycles and dictating which capacity expansions reach commercial production first. Miners now sequence greenfield decisions around provincial environmental clearance windows rather than pure demand signals.
Growth Catalysts
- Soil potassium depletion cycles:Brazil's soybean belt requires recurring KCl application to maintain yields, generating predictable offtake volumes tied to planting seasons.
- REACH compliance premiums:EU fertilizer importers now pay certification premiums for chloride-sensitive crop formulations, expanding sulfate of potash margins.
- Rail-export infrastructure:Dedicated potash unit trains from Saskatchewan to Vancouver and Thunder Bay terminals cut port delivery costs versus truck-dependent competitors.
Market Restraints
- Natural gas input volatility:Solution mining operations in Saskatchewan and New Mexico face margin compression when Henry Hub prices spike, as evaporation and processing are energy-intensive.
- Supply concentration risk:Three Canadian provinces control over two-thirds of exportable reserves, creating single-point-of-failure exposure during labor disputes or provincial policy shifts.
- Organic farming substitution:Certified organic acreage in Germany and Austria rejects synthetic KCl, forcing miners to cede share to compost and green manure suppliers in those segments.
Strategic Opportunities
- Underpenetrated African demand:Ethiopia's agricultural transformation and commercial farm development in Tanzania offer first-mover positioning before domestic blending capacity matures.
- EU Green Deal carbon border adjustments:CBAM implementation favors Saskatchewan producers with lower Scope 1 emissions intensity versus Belarusian or Russian rail-shipped volumes.
- Precision agriculture convergence:Variable-rate application technology paired with soil sensor networks enables premium pricing for customized KCl blends matched to field-specific deficiency maps.
Industry Challenges
- Mine geotechnical engineering talent scarcity:Saskatchewan and New Brunswick operations compete for finite pools of potash-specific ground control specialists familiar with Prairie evaporite geology.
- Solution mining brine management compliance:EPA Class II injection well permitting timelines under the US Safe Drinking Water Act stretch 18-24 months, delaying New Mexico expansion schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potash Market |
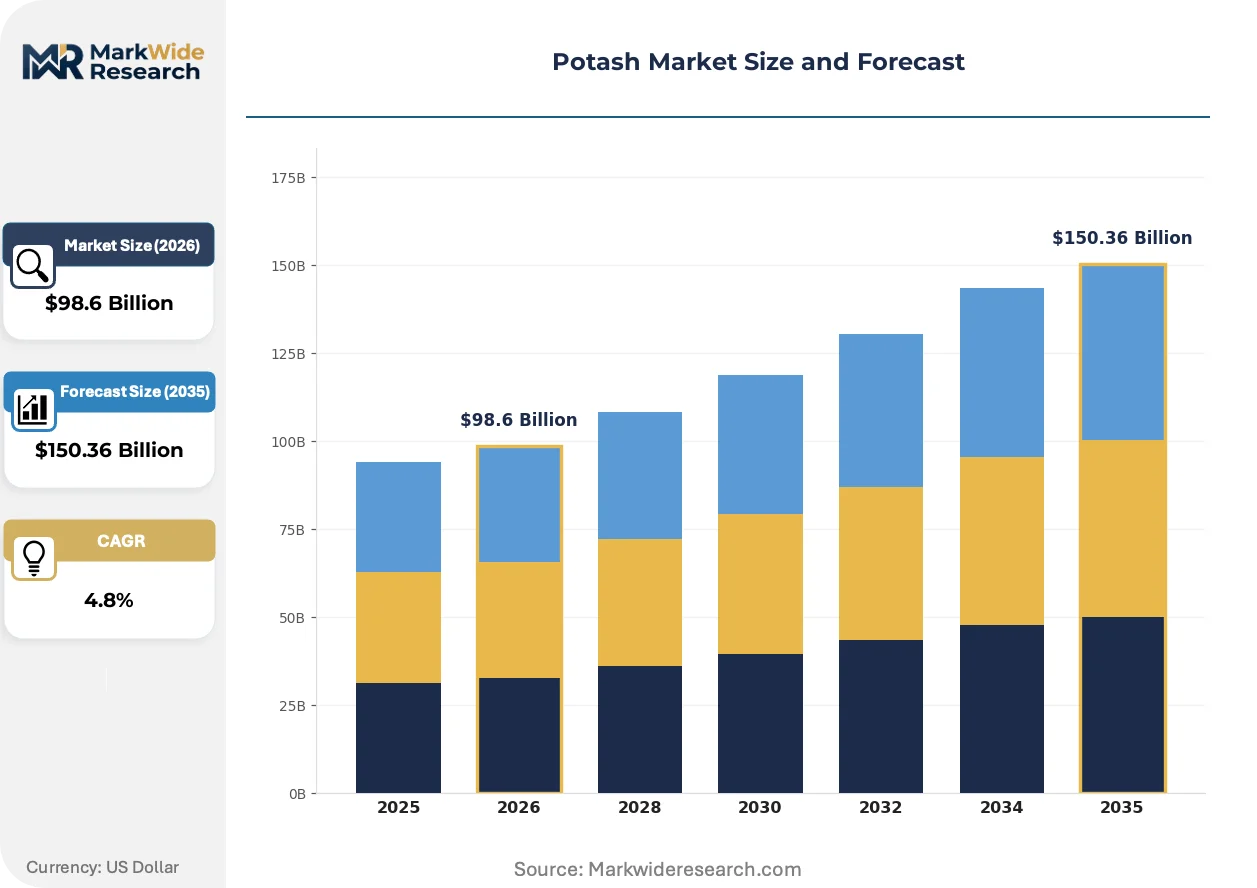
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $150.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potash Chloride, Potash Sulfate, Potash Nitrate, Muriate of Potash End Use Industry: Agriculture, Horticulture, Forestry, Water Treatment Distribution Channel: Direct Sales, Distributors, Retail, Online Sales Application: Crop Nutrient, Animal Feed, Fertilizer Production, Soil Amendment |
| Companies Covered | Nutrien Ltd., The Mosaic Company, JSC Belaruskali, Uralkali, Compass Minerals Intl. Ltd., K+S Aktiengesellschaft, Intrepid Potash Inc., Qinghai Salt Lake Industry, BHP Billiton Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potash Market Emerging Trajectories
Digital twin technology and automated hoisting systems are compressing extraction economics while regulatory carbon accounting is forcing supply chain reconfiguration toward lower-emission transport modes.
Solution mining with selective dissolution is virtualizing conventional shaft-sinking requirements for certain Saskatchewan deposits. Nutrien and BHP are piloting brine extraction from deeper Prairie evaporite horizons without vertical shaft construction, cutting capital intensity by half for greenfield projects. This approach is virtualizing the traditional mine development timeline, enabling production within 36 months versus 7-10 years for conventional methods.
Canada's federal Output-Based Pricing System and Saskatchewan's provincial offset protocols are tightening carbon cost exposure for miners with higher natural gas processing loads. Facilities without carbon capture retrofits face escalating compliance costs that erode rail-export competitiveness into European terminals. Sulfate of potash producers with lower thermal processing requirements are capturing margin premiums under this regime.
Cooperative procurement consolidation across Brazilian agricultural belts is compressing distributor margins and forcing direct mine-to-farm contracting models. Large Mato Grosso and Goiás farming cooperatives now negotiate annual KCl volumes directly with Saskatchewan exporters, bypassing traditional Rio Grande port traders. This disintermediation is most advanced in Brazil's Center-West region where single cooperatives control fertilizer demand for 500,000+ hectares.
Potash Market Segmentation
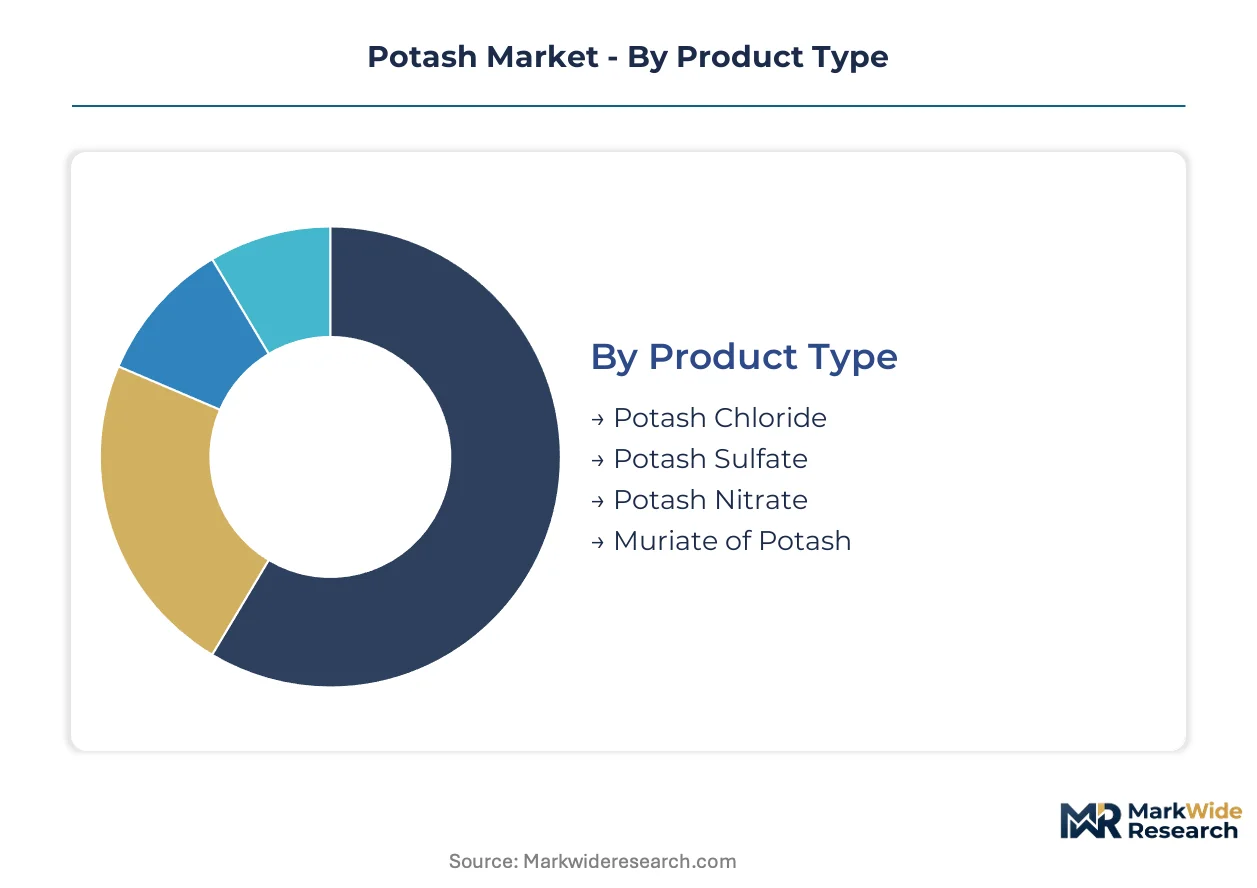
Potash segmentation reflects divergent margin structures across chloride-sensitive specialty crops versus bulk grain applications. Product chemistry and distribution channel selection determine access to premium pricing pools in horticulture versus commodity fertilizer markets.
Product Type:
Use-case spectrum spans chloride-tolerant commodity grains to sulfur-deficient specialty crops requiring co-nutrient formulations.
- Muriate of Potash:Potassium chloride concentrates at 60-62% K2O equivalent deliver the most cost-effective potassium unit for bulk handling. Brazil's Mato Grosso soybean belt consumes recurring volumes through direct mine-to-cooperative contracts tied to planting cycles.
- Potash Sulfate:Chloride-free formulation with sulfur co-nutrition commands premium positioning in EU fruit and vegetable segments where REACH compliance restricts chloride application. German and Austrian organic-adjacent operations absorb sulfate premiums for quality-sensitive produce.
- Potash Chloride:Standard agricultural grade serves broad-acre grain production across Saskatchewan-to-Vancouver export corridors with rail-unit train economics.
- Potash Nitrate:Dual-nutrient composition addresses nitrogen-potassium co-deficiency in intensive vegetable systems with higher solubility requirements.
Established volume favors Muriate of Potash; emerging adoption favors Potash Sulfate.
End Use Industry:
Cost tier separation distinguishes bulk commodity agriculture from precision-input horticulture and regulatory-intensive water treatment.
- Agriculture:Grain and oilseed production absorbs 70%+ of global potash movement through seasonal application windows tied to soil testing cycles. Brazil's Center-West cooperatives negotiate annual KCl volumes directly with Saskatchewan exporters.
- Horticulture:Greenhouse and protected-crop operations demand sulfate formulations with controlled-release properties for substrate-based cultivation. Netherlands and Spain glasshouse clusters specify chloride thresholds below 2% for premium tomato and pepper production.
- Forestry:Plantation timber operations in Southeast Asia apply potassium to correct lateritic soil deficiencies in eucalyptus and acacia stands.
- Water Treatment:Municipal softening and industrial process applications consume lower-grade potash for ion-exchange regeneration.
Volume concentration sits with Agriculture; margin expansion sits with Horticulture.
Distribution Channel:
Customer type fragmentation separates cooperative procurement consolidation from fragmented retail and emerging digital channels.
- Direct Sales:Mine-to-farm contracting bypasses traditional port traders for Brazilian cooperatives controlling 500,000+ hectare demand blocks. Nutrien's integrated logistics network anchors this channel across North American grain belts.
- Distributors:Rio Grande and Santos port traders maintain position in fragmented smallholder segments where cooperative penetration remains incomplete.
- Retail:Farm supply stores and agricultural cooperatives serve last-mile delivery for time-sensitive planting-season demand.
- Online Sales:Digital procurement platforms emerge for standardized grades with transparent pricing, though bulk logistics constraints limit penetration.
Procurement consolidation favors Direct Sales; channel fragmentation sustains Distributor relevance.
Application:
Supply concentration varies between integrated fertilizer manufacturing and standalone soil amendment deployment.
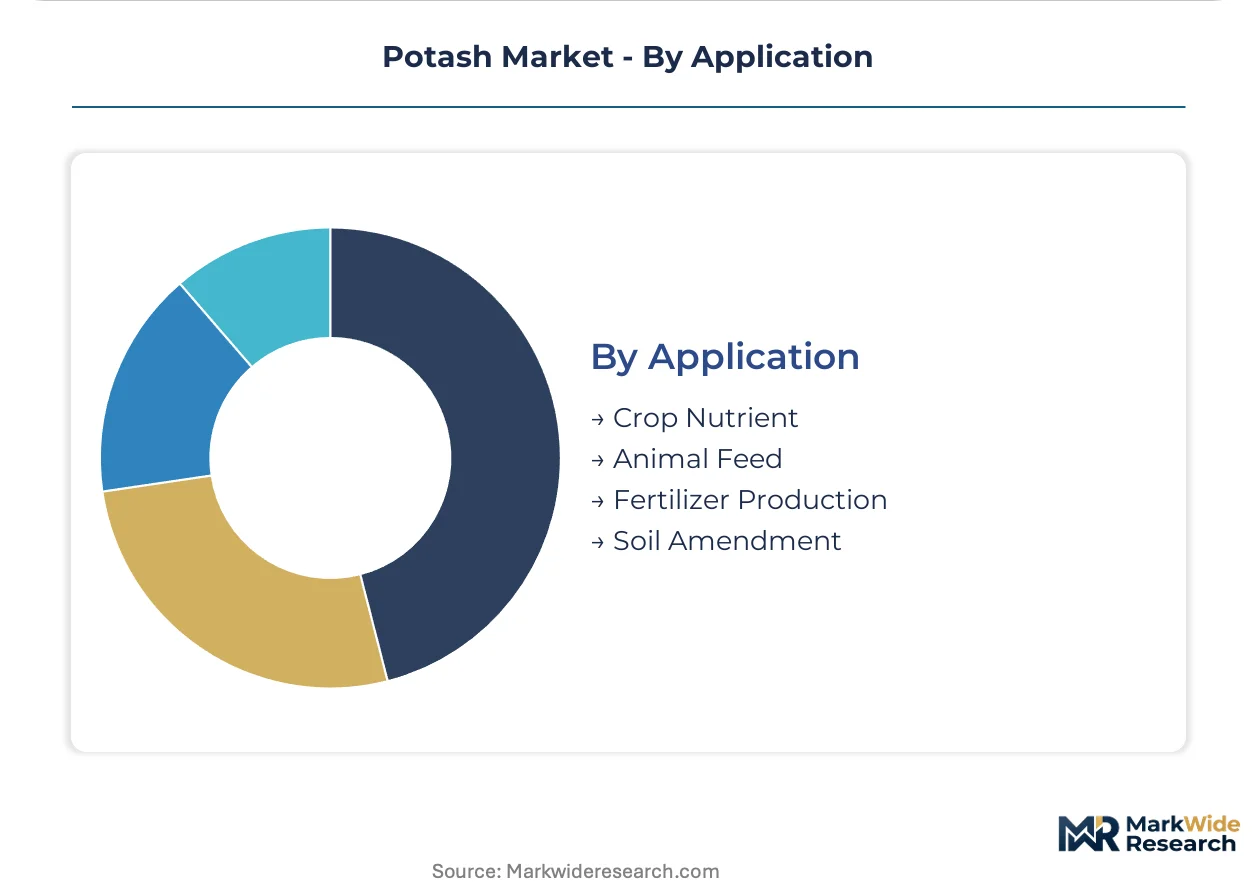
- Fertilizer Production:NPK blending operations consume bulk KCl as the potassium input for compound fertilizer manufacturing. Southeast Asian domestic blending capacity expansion absorbs import volumes before finished product distribution.
- Crop Nutrient:Direct field application of straight potash addresses soil potassium depletion in intensive soybean and corn rotations.
- Soil Amendment:Reclamation of degraded soils in Ethiopia's agricultural transformation zones applies potash to correct severe nutrient mining.
- Animal Feed:Potassium supplementation in dairy and poultry rations represents a stable but lower-volume demand pool with different specification requirements.
Upstream integration favors Fertilizer Production; field-level precision favors Crop Nutrient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian provincial regulators control two-thirds of exportable potash reserves through Saskatchewan's royalty frameworks and environmental clearance protocols. This supply concentration shapes investment sequencing across Brazilian, Southeast Asian, and European demand corridors. The following analysis examines specific country-level dynamics where extraction economics and import regulations intersect.
Canada
Saskatchewan's potash corridor anchors global supply through Nutrien's integrated mine-to-farm logistics and BHP's Jansen project development. The province's Output-Based Pricing System and provincial offset protocols tighten carbon cost exposure for natural gas-intensive solution mining operations. Saskatoon-based engineering clusters compete for finite geotechnical talent familiar with Prairie evaporite geology.
Brazil
Brazil's Mato Grosso soybean belt drives recurring potassium chloride application cycles tied to soil depletion and yield maintenance targets. MAPA fertilizer registration requirements dictate product certification timelines and market access conditions for imported formulations. Center-West cooperatives in Goiás and Mato Grosso negotiate annual volumes directly with Saskatchewan exporters, bypassing traditional Rio Grande port traders.
China
Qinghai Salt Lake Industry exploits domestic evaporite deposits in the Qaidam Basin to reduce import dependency for agricultural potassium inputs. The Ministry of Ecology and Environment enforces dual carbon goals that reshape processing energy intensity requirements for domestic producers. Xinjiang's emerging solution mining capacity targets self-sufficiency in chloride-sensitive specialty crop formulations.
Germany
German horticulture clusters in Lower Saxony and Bavaria absorb premium sulfate of potash volumes for organic-adjacent fruit and vegetable production. ECHA REACH compliance mandates certification premiums for chloride-sensitive crop formulations, expanding sulfate margins versus standard muriate grades. Kassel-based blending operations serve Netherlands and Spanish glasshouse clusters with controlled-release potassium specifications.
United States
New Mexico solution mining operations face EPA Class II injection well permitting timelines under the Safe Drinking Water Act that stretch 18-24 months. Henry Hub natural gas price volatility compresses margins for energy-intensive evaporation and processing at Intrepid Potash's Carlsbad facilities. Midwest grain belt distributors rely on Saskatchewan rail-unit trains through Vancouver and Thunder Bay terminals for cost-competitive potassium chloride supply.
Potash Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction and processing. The potash sector exhibits tiered consolidation with integrated miners controlling rail-export infrastructure and regional distributors managing last-mile farm delivery. Three archetypes dominate: Saskatchewan-based royalty-optimized producers with captive logistics networks, Russian and Belarusian state-linked exporters competing on rail-port cost structures, and Chinese domestic operators exploiting Qaidam Basin evaporite deposits. Competitive moves center on solution mining virtualization to compress greenfield timelines and direct mine-to-cooperative contracting to disintermediate port traders.
Within the integrated platform tier, Nutrien Ltd. and The Mosaic Company exemplify North American archetypes with provincial royalty exposure and phosphate-potash co-location economics. Uralkali anchors the rail-export cost-competitive segment with terminal access into Brazilian and Asian markets. Among state-linked operators, JSC Belaruskali occupies a position shaped by European border adjustment exposure and alternative route development through non-EU terminals.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| The Mosaic Company |
| JSC Belaruskali |
| Uralkali |
| Compass Minerals Intl. Ltd. |
| K+S Aktiengesellschaft |
| Intrepid Potash Inc. |
| Qinghai Salt Lake Industry |
| BHP Billiton Ltd. |
| Others |
Supply Flow & Price Mechanics
Rail-export infrastructure concentration in Saskatchewan determines both the spread between contract and spot pricing tiers and the geographic shape of downstream distribution. Henry Hub natural gas volatility feeds directly into solution mining cost structures, compressing margins for energy-intensive evaporation operations while rewarding producers with lower thermal processing footprints.
Pricing Analysis
Brazil's MAPA fertilizer registration requirements dictate the pricing tier structure across import-dependent markets, separating premium-certified formulations from standard bulk grades. Three-tier pricing structure across premium, standard, and economy levels reflects chloride sensitivity thresholds, with sulfate of potash commanding spreads justified by REACH-compliant certification in EU horticulture. Cost compression in standard muriate grades is intensifying because cooperative procurement consolidation in Brazil's Center-West erodes distributor markups. Smallholder segments served through Rio Grande port traders exhibit highest price sensitivity; large cooperatives with direct mine contracts show lowest.
Supply Chain Analysis
Nutrien Ltd., The Mosaic Company, and BHP anchor contract-mining concentration through Saskatchewan-based extraction and captive logistics networks. Supply concentrates in Canada, Russia, and Belarus, with Chinese Qaidam Basin operations feeding domestic demand. Raw material dependencies center on natural gas for solution mining evaporation, sulfuric acid for sulfate conversion, and railcar fleets for unit-train economics. Single-source vulnerability sits with Saskatchewan's two-thirds share of exportable reserves during labor disputes or provincial policy shifts. Distribution runs through direct mine-to-farm contracting for Brazilian cooperatives and port-trader intermediation for fragmented Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Potash markets track agricultural commodity cycles, with Brazilian soybean planting intensity serving as the primary cyclical recovery driver. Stakeholders should position around soil potassium depletion cycles and regulatory carbon accounting shifts.
For Market Incumbents: Pre-empt cooperative disintermediation by accelerating direct contracting coverage across Brazil's Goiás and Mato Grosso belts before regional blending capacity matures. Anchor position through backward integration into rail-terminal ownership at Vancouver and Thunder Bay, locking in cost advantages over truck-dependent competitors. Carbon border adjustment exposure in European markets threatens Belarusian and Russian rail-export volumes; incumbents with lower Scope 1 intensity should capture share through premium sulfate positioning.
For New Entrants and Emerging Players: Ethiopia's agricultural transformation zones and Tanzania's commercial farm development represent the most penetrable entry points before domestic blending infrastructure consolidates. Solution mining virtualization technology offers capital-light production entry without 7-10 year shaft-sinking timelines. Partner with precision agriculture platform providers to bundle soil-sensor-guided application services with customized KCl blends, bypassing commodity pricing pressure.
For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment implementation reshapes the acquisition landscape, favoring Saskatchewan assets with verified lower-emission profiles over Eastern European rail-dependent operations. Long-term viability centers on 5-10 year positioning around soil depletion-driven recurring demand rather than cyclical capacity expansion plays. Target mid-tier solution mining operators with brine extraction virtualization pilots. Monitor quarterly MAPA registration approval velocity as inflection indicator for Brazilian import demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Solution Mining Virtualization | Nutrien and BHP pilots compress greenfield timelines from 7-10 years to 36 months without vertical shaft construction. |
| Direct Mine-to-Farm Contracting | Bypassing Rio Grande port traders captures margin compression from cooperative procurement consolidation in Brazil's Center-West. |
| Rail-Export Infrastructure Lock-in | Unit train terminal ownership at Vancouver and Thunder Bay anchors cost competitiveness against truck-dependent New Mexico operations. |
| Carbon Capture Retrofit Investment | Facilities without capture face escalating compliance costs under Canada's Output-Based Pricing System that erode European export margins. |
| Precision Agriculture Platform Partnership | Soil sensor network integration enables premium pricing for field-specific KCl blends matched to deficiency mapping. |
Methodological Framework
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Mine operations managers, agricultural cooperative procurement directors, Brazilian MAPA registration consultants, and Saskatchewan geotechnical engineering clusters provided operational perspective. Secondary sources include Saskatchewan provincial royalty framework documentation, EPA Class II injection well permitting records under the Safe Drinking Water Act, Brazil's MAPA fertilizer registry, EU ECHA REACH compliance databases, and customs trade flow data. Bottom-up capacity modeling and top-down demand triangulation from planting acreage statistics were reconciled.
Calibration against historical price spreads between sulfate and muriate grades, rail freight rate movements, and natural gas input cost cycles refined the analytical framework. Segmentation dimensions span product chemistry tiers, end-use industry concentration, distribution channel structure, and application method integration. CAGRs were derived from regression against planted acreage intensity and yield maintenance targets across the projection horizon. Key inputs include Brazilian soybean belt soil testing frequency and EU carbon border adjustment implementation scope.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, Henry Hub natural gas rates, or Brazilian real exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding MAPA registration timelines and Saskatchewan environmental clearance windows. Quarterly review of Brazilian cooperative procurement consolidation metrics and EU CBAM certification velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Fertilizer Applicators Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Global Fertilizers Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Global Urea Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Multi-Nutrient Fertilizer Market