
 North America Specialty Fertilizer Market | 2026-2036
North America Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Specialty Fertilizer Market Analytics
The US Gulf Coast is rewriting regional supply dynamics as ammonia and phosphate capacity expansions concentrate near Louisiana and Texas petrochemical corridors. Nutrien Ltd. anchors North American potash supply through its Saskatchewan mining network, while The Mosaic Company leverages integrated phosphate rock-to-fertilizer operations across Florida and Louisiana. ICL Group Ltd. differentiates through bromine-adjacent specialty formulations serving controlled-release segments.
Specialty fertilizers deliver nutrients through engineered release mechanisms, with polymer-coated urea formulations achieving 60-120 day nitrogen availability windows tailored to crop phenology. These inputs serve commercial agriculture by minimizing leaching losses while matching nutrient supply to plant uptake curves. Water-soluble fertilizers occupy the fastest-expanding margin pool as greenhouse and hydroponic operations scale across Mexico's protected agriculture zones, while controlled-release products sustain premium positioning in high-value turf management contracts. Bio-based formulations remain structurally constrained by production scale limitations despite accelerating interest from organic-certified operations.
EPA Clean Water Act enforcement shapes product formulation requirements by restricting nitrogen and phosphorus runoff from agricultural sources. The USDA's Environmental Quality Incentives Program steers cost-share dollars toward precision nutrient management, indirectly subsidizing specialty fertilizer adoption. California's Department of Pesticide Regulation maintains additional coating chemistry standards that filter market access for non-compliant imports. Stakeholders must monitor how state-level 4R Nutrient Stewardship mandates diffuse beyond current adopters in the Midwest and Great Plains.
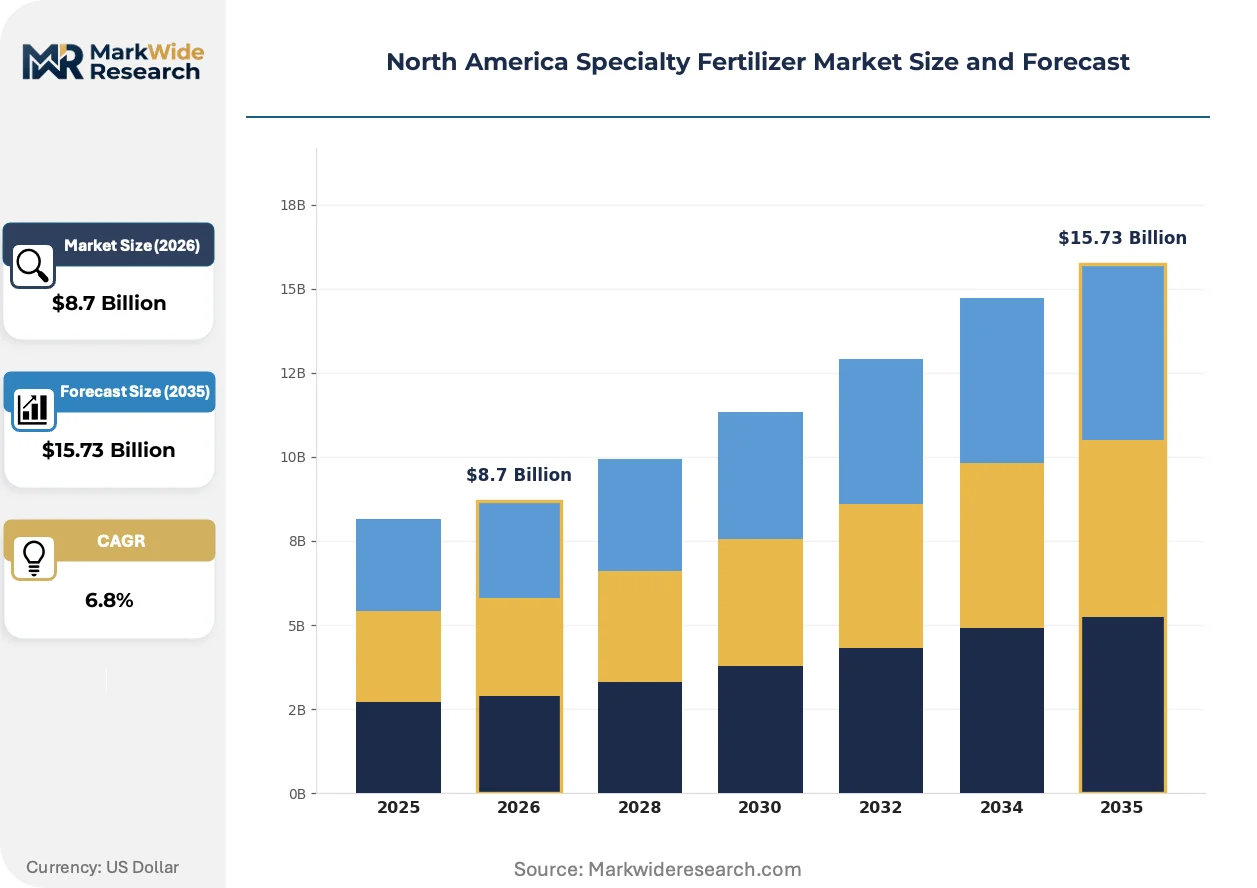
Market Dynamics
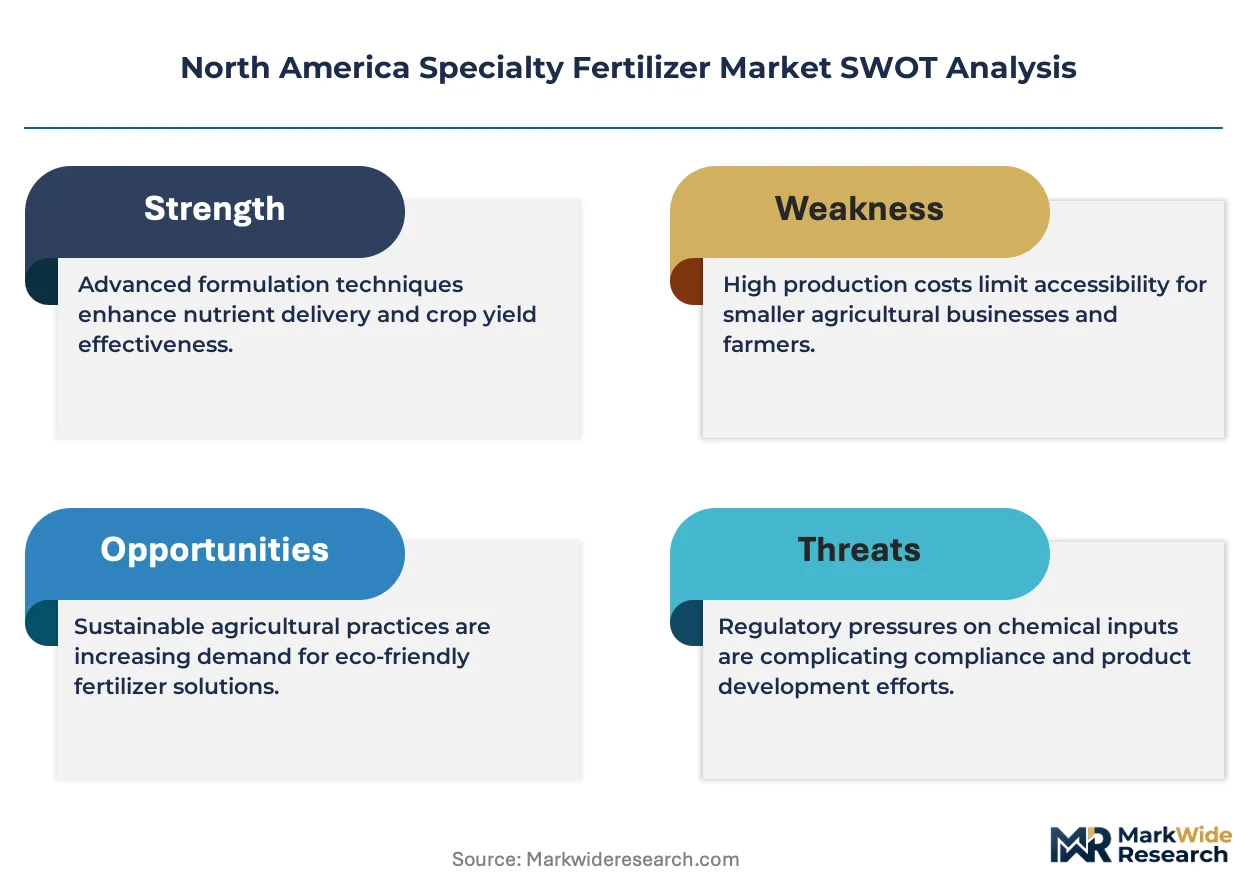
EPA Clean Water Act enforcement is compressing nitrogen and phosphorus runoff allowances, forcing growers toward controlled-release formulations that synchronize nutrient availability with crop uptake curves. This regulatory pressure intersects with precision agriculture adoption across the Corn Belt, where variable-rate application systems demand fertilizers engineered for spatial variability.
Growth Catalysts
- 4R Nutrient Stewardship mandates:State-level implementation across the Midwest and Great Plains creates compliance-driven demand for right-source, right-rate fertilizer technologies.
- Controlled-release polymer chemistry:Formulations achieving 60-120 day nitrogen windows match nutrient supply to corn and soybean phenology, reducing leaching losses.
- California specialty crop premiums:High-value fruit and vegetable production in the Central Valley commands input investments that absorb specialty fertilizer price premiums.
Market Restraints
- Natural gas feedstock volatility:Ammonia synthesis depends on natural gas prices, exposing margin structures to Gulf Coast petrochemical corridor supply shocks.
- Saskatchewan potash concentration:North American supply depends on a single province's mining network, creating geographic vulnerability to rail or labor disruptions.
- Coating chemistry compliance:California Department of Pesticide Regulation standards filter import access, raising formulation costs for non-compliant suppliers.
Strategic Opportunities
- Mexico protected agriculture zones:Greenhouse and hydroponic expansion across Sinaloa and Baja California creates demand for water-soluble fertilizer formats.
- USDA Environmental Quality Incentives Program:Cost-share dollars for precision nutrient management indirectly subsidize grower adoption of specialty formulations.
- Bio-based formulation convergence:Integration of microbial inoculants with controlled-release matrices addresses organic-certified operations previously excluded from synthetic inputs.
Industry Challenges
- Polymer coating scale-up:Achieving consistent 60-120 day release profiles at commercial volumes requires capital-intensive fluidized bed equipment and quality control systems.
- Legacy fertility program integration:Agronomists and crop consultants face retraining burdens to specify variable-rate specialty products within existing recommendation frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Specialty Fertilizer Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controlled-Release, Water-Soluble, Bio-Based, Organic Application: Crop Nutrition, Soil Health, Foliar Feeding, Turf Management End User: Agricultural Producers, Landscape Professionals, Lawn Care Providers, Retail Garden Centers Distribution Channel: Online Retail, Direct Sales, Wholesale, Garden Supply Stores |
| Companies Covered | The Mosaic Company, Nutrien Ltd., CF Industries Holdings, Inc., Haifa Group, Koch Industries Inc., ICL Group Ltd, Yara International ASA, Sociedad Quimica y Minera de Chile SA, The Andersons Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Specialty Fertilizer Market Evolving Landscape
Formulation chemistry and application hardware are converging to collapse the distinction between fertilizer input and precision agriculture data layer. This convergence is compressing product development cycles and reshaping how manufacturers partner with equipment OEMs.
Polymer-coated urea formulations with temperature-responsive release kinetics are collapsing the performance gap between conventional split applications and single-pass specialty products. Corn Belt operators adopting variable-rate planters are specifying these coatings at accelerating rates. The technology is collapsing inventory complexity for retailers while compressing application labor requirements during narrow spring planting windows.
EPA enforcement of Total Maximum Daily Load allocations under the Clean Water Act is tightening nitrogen discharge permits in Chesapeake Bay and Mississippi River watersheds. Agricultural non-point source restrictions are forcing fertilizer retailers to certify product placement protocols. Corn and soybean growers in Iowa, Illinois, and Minnesota are responding by specifying controlled-release products that document reduced runoff potential.
Buying committees at large-scale farming operations are consolidating input procurement around performance guarantees rather than price-per-ton metrics. Distributors serving the Corn Belt are unbundling agronomic advisory from product supply, charging separately for prescription map development. This shift is most visible among 5,000+ acre operations in Nebraska and Kansas where equity investors demand documented sustainability metrics for capital access.
North America Specialty Fertilizer Market Segmentation
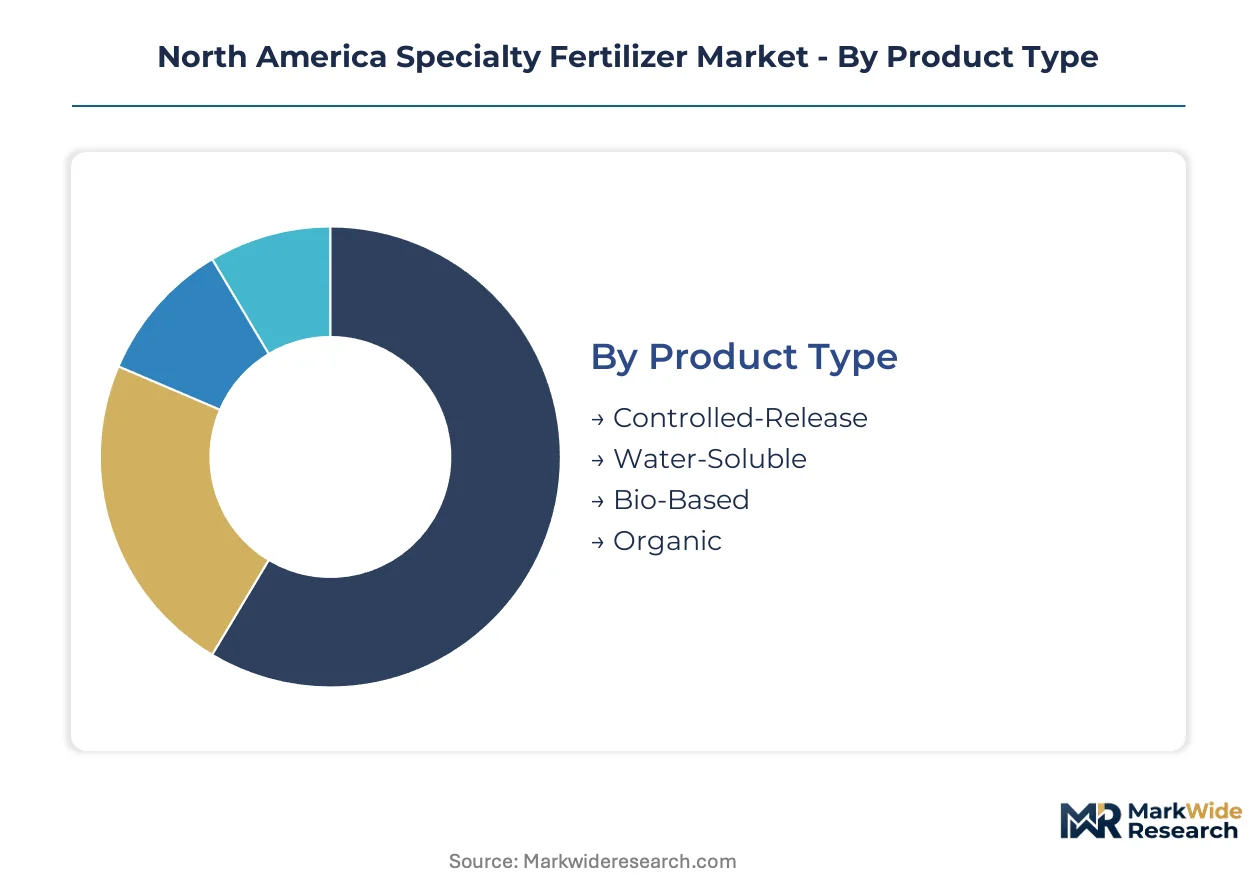
Specialty fertilizer purchasing patterns diverge sharply across use contexts, from precision corn operations in Iowa to greenhouse complexes in Sinaloa. Manufacturers must configure formulation chemistry, packaging formats, and advisory services to match these distinct demand profiles.
Product Type:
Polymer coating chemistry, solubility engineering, and biological activation define four distinct technology platforms with overlapping but non-identical customer bases.
- Controlled-Release:Polymer-coated urea formulations synchronize nitrogen availability with crop uptake curves across 60-120 day windows. Corn Belt operators adopting variable-rate planters specify these coatings to compress application labor during narrow spring windows.
- Water-Soluble:Complete nutrient solutions dissolve for immediate root zone or foliar uptake. Protected agriculture expansion across Mexico's Sinaloa and Baja California greenhouse corridors drives specification of these precision-dosed formats.
- Bio-Based:Microbial inoculants and enzymatic activators deliver nutrients through biological pathways. Production scale limitations constrain availability despite accelerating interest from organic-certified operations in California's Central Valley.
- Organic:Certified inputs derived from plant and animal residues meet USDA National Organic Program standards. Premium pricing absorbs compliance costs for growers supplying Whole Foods and regional organic distributors.
Established volume favors controlled-release; emerging adoption favors bio-based.
Application:
Functional purpose determines formulation concentration, application timing, and equipment compatibility across four distinct agronomic protocols.
- Crop Nutrition:Macronutrient delivery optimized for yield response in commodity grain and specialty crop systems. EPA Clean Water Act runoff restrictions in Chesapeake Bay and Mississippi River watersheds are forcing specification of controlled-release products that document reduced leaching potential.
- Soil Health:Microbial food sources and slow-release organic matter rebuild soil biology. Midwest operators participating in USDA Environmental Quality Incentives Program cost-share initiatives specify these inputs to meet conservation compliance requirements.
- Foliar Feeding:Micronutrient solutions applied directly to leaf tissue for rapid correction of deficiencies. California avocado and citrus growers use these formulations during critical fruit development windows.
- Turf Management:Controlled-release nitrogen sustains color and density across extended intervals. Municipal parks departments and golf course superintendents in Arizona and Florida absorb premium pricing to minimize labor-intensive reapplication cycles.
Volume concentrates in crop nutrition; margin expansion concentrates in turf management.
End User:
Customer scale and technical sophistication create four distinct service requirements from bulk logistics to retail merchandising.
- Agricultural Producers:Large-scale farming operations consolidating procurement around performance guarantees rather than price-per-ton metrics. Nebraska and Kansas operations exceeding 5,000 acres demand documented sustainability metrics for equity investor reporting.
- Landscape Professionals:Commercial installation and maintenance contractors serving municipal and corporate accounts. These buyers prioritize application labor efficiency over input cost minimization.
- Lawn Care Providers:Residential service operators managing recurring subscription revenue models. Seasonal cash flow patterns shape purchasing timing and inventory financing requirements.
- Retail Garden Centers:Consumer-facing outlets merchandising bagged products to hobbyist growers. Staff training demands and shelf space constraints filter supplier access.
Procurement consolidation favors agricultural producers; margin rate favors landscape professionals.
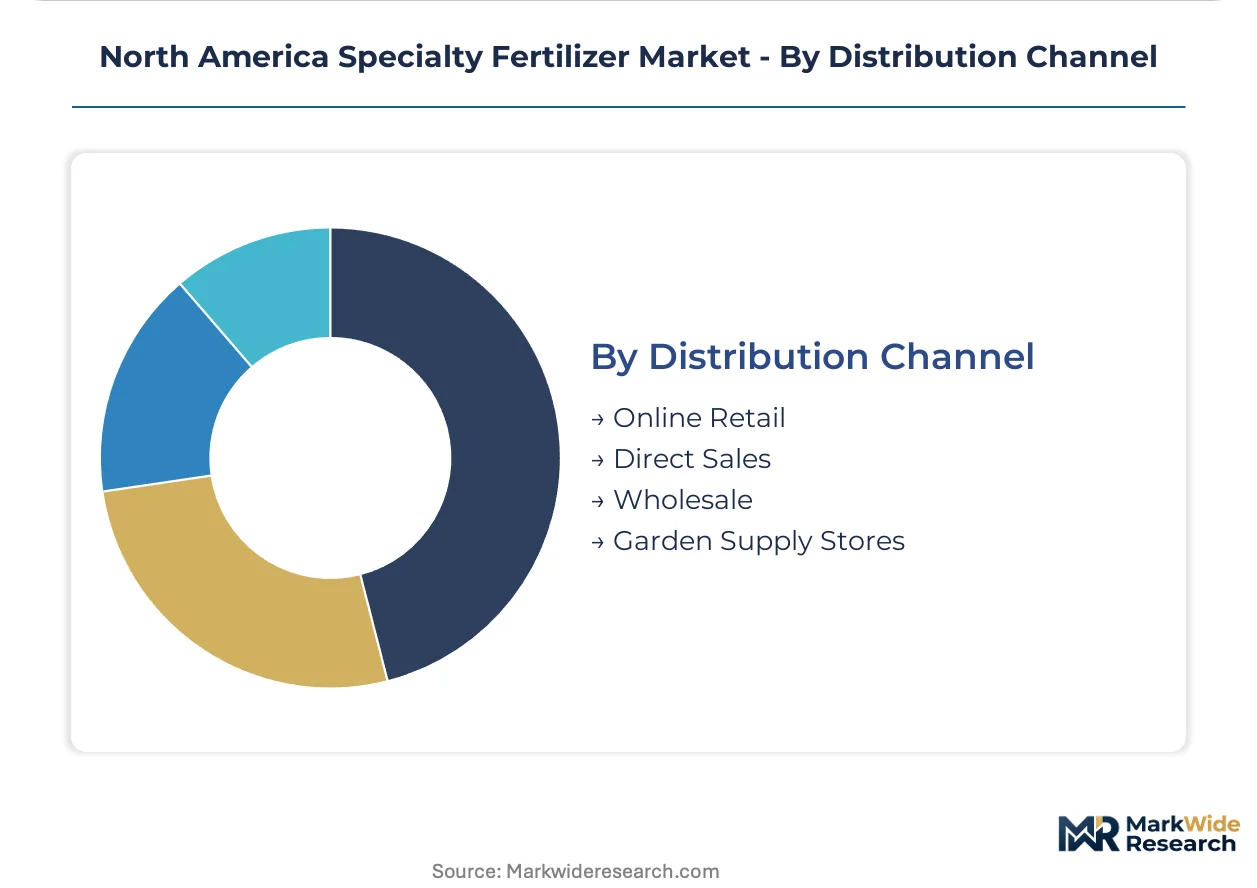
Distribution Channel:
Logistics configuration and customer touchpoint intensity separate four channel structures with diverging working capital requirements.
- Online Retail:E-commerce platforms serving hobbyist and small-scale professional buyers. Amazon and specialized agricultural marketplaces are capturing urban and suburban gardening segments.
- Direct Sales:Manufacturer-to-grower relationships bypassing distributor markups for large-volume accounts. Nutrien and Mosaic field agronomists develop prescription maps and variable-rate recommendations.
- Wholesale:Regional distributors aggregating inventory for retail and professional resale. Gulf Coast ammonia and phosphate capacity expansions are compressing freight costs to Midwest delivery points.
- Garden Supply Stores:Independent retailers serving local landscaping contractors and serious hobbyists. California Department of Pesticide Regulation coating chemistry standards filter import access for these channels.
Volume flows through wholesale; growth rate climbs fastest in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Clean Water Act enforcement anchors United States regulatory pressure, while provincial mining networks and protected agriculture corridors define Canadian and Mexican demand centers respectively.
United States
Corn Belt precision agriculture operators and California specialty crop growers drive differentiated demand profiles. The USDA Environmental Quality Incentives Program steers cost-share dollars toward controlled-release formulations in Iowa, Illinois, and Minnesota. Gulf Coast ammonia and phosphate capacity expansions near Louisiana and Texas petrochemical corridors are rewriting Midwest supply logistics.
Canada
Saskatchewan potash mining networks supply North American macronutrient requirements through integrated rail and port infrastructure. Provincial environmental regulations in Alberta and Manitoba increasingly mirror EPA runoff restrictions, pressuring prairie grain operations toward polymer-coated formulations. Ontario's greenhouse vegetable sector around Leamington and Kingsville specifies water-soluble precision fertilizers for hydroponic tomato and pepper production.
Mexico
Protected agriculture expansion across Sinaloa and Baja California greenhouse corridors creates demand for water-soluble and foliar fertilizer formats. Mexican agricultural regulators are gradually adopting nitrogen runoff guidelines that align with US EPA frameworks, particularly in watersheds draining into shared water bodies. The Bajío Region's berry and vegetable export operations command premium input investments to meet US retail buyer certification requirements.
North America Specialty Fertilizer Market Competitive Landscape
Integrated mining-to-fertilizer conglomerates and specialty formulation specialists split the market between scale-driven commodity supply and precision-engineered nutrient delivery. Nutrien Ltd. and The Mosaic Company anchor the consolidated upstream tier through captive potash and phosphate rock reserves. Mid-scale operators differentiate through coating chemistry expertise and regional distribution density. Competitive moves concentrate on backward integration into raw material security and forward integration into agronomic advisory services.
Within the integrated mining-to-fertilizer tier, Nutrien Ltd. and The Mosaic Company exemplify scale-driven supply security through Saskatchewan potash networks and Florida-Louisiana phosphate operations respectively. ICL Group Ltd. occupies a specialty formulation position, leveraging bromine-adjacent chemical expertise to serve controlled-release segments. These three entities represent divergent strategic postures: captive mineral reserves versus engineered release chemistry versus regional distribution integration.
| Leading Market Players |
|---|
| The Mosaic Company |
| Nutrien Ltd. |
| CF Industries Holdings, Inc. |
| Haifa Group |
| Koch Industries Inc. |
| ICL Group Ltd |
| Yara International ASA |
| Sociedad Quimica y Minera de Chile SA |
| The Andersons Inc. |
| Others |
Value Network & Pricing Analysis
Gulf Coast rail corridors connecting Louisiana ammonia terminals to Midwest distribution hubs compress freight costs for bulk nitrogen while amplifying price spreads between controlled-release coatings and commodity urea. This logistics concentration grants integrated producers pricing power over specialty formulations that smaller blenders cannot replicate.
Pricing Analysis
Geographic price spreads between Saskatchewan potash mine gates and Iowa farm delivery points exceed coating chemistry premiums for polymer-encapsulated urea. Three-tier pricing structure across premium controlled-release, standard water-soluble, and economy bulk nitrogen segments reflects certification grade and volume scale differentiation. Pricing pressure stems from natural gas feedstock volatility at Gulf Coast ammonia crackers, squeezing margin structures for non-integrated blenders. Large-scale Corn Belt operators exceeding 5,000 acres exhibit lowest price sensitivity due to sustainability-linked capital access requirements, while retail garden center channels face acute cost compression.
Supply Chain Analysis
Extended payment terms from wholesale distributors to agricultural retailers now stretch 90-120 days, mirroring seasonal cash flow patterns of Midwest grain operations. Supply concentrates in Saskatchewan potash mines, Florida phosphate rock quarries, and Louisiana ammonia synthesis corridors. Raw material dependencies include natural gas feedstock, sulfuric acid for phosphate processing, and polymer resin coatings. Single-source vulnerability to Saskatchewan rail disruptions poses structural risk. Distribution runs through regional wholesale aggregators serving variable-rate applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American specialty fertilizer penetration remains early-cycle, with 4R Nutrient Stewardship mandates accelerating adoption faster than historical fertility program conversion rates.
For Market Incumbents: Pre-empt coating chemistry commoditization by securing captive polymer resin supply through backward integration into Gulf Coast petrochemical networks. Defend premium positioning against emerging bio-based entrants by embedding agronomic advisory services into direct sales relationships with precision agriculture operators. For New Entrants and Emerging Players: Mexico's protected agriculture zones in Sinaloa and Baja California represent the most penetrable entry point for water-soluble format specialists lacking bulk logistics infrastructure. Organic-certified operations in California's Central Valley offer second-tier white space for microbial inoculant convergence products. Go-to-market execution should prioritize greenhouse agronomist relationships over commodity distributor channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating chemistry specialists with fluidized bed manufacturing capabilities over upstream mining conglomerates. Long-term viability hinges on regulatory enforcement durability across Chesapeake Bay and Mississippi River watersheds. Watch EPA Total Maximum Daily Load allocation tightening as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Supply | Captive coating chemistry supply secures margin structures against Gulf Coast petrochemical volatility. |
| Precision Agriculture Data Platform Partnership | Integration with variable-rate planter OEMs collapses product specification friction for Corn Belt operators. |
| California DPR Coating Compliance Certification | Regulatory clearance filters import competition and sustains premium positioning in specialty crop channels. |
| Mexico Greenhouse Corridor Distribution Buildout | Protected agriculture expansion in Sinaloa creates dedicated water-soluble fertilizer demand concentration. |
| USDA EQIP Advisory Service Bundling | Cost-share program alignment subsidizes grower adoption while locking in prescription map recurring revenue. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fertilizer manufacturing executives, wholesale distribution managers, and precision agriculture agronomists; and secondary validation through USDA Environmental Quality Incentives Program disbursement records, EPA Clean Water Act enforcement actions, and SEC 10-K filings from integrated mining-to-fertilizer conglomerates. Bottom-up volume estimates triangulated against top-down macronutrient consumption projections.
Forecast inputs considered controlled-release coating adoption curves, water-soluble format penetration in protected agriculture, and bio-based formulation scale constraints across the analysis window. Segmentation dimensions modeled include product technology platform, application protocol, end-user scale category, and distribution channel structure. CAGRs derived from regression analysis of historical specialty fertilizer premium spreads relative to commodity nitrogen benchmarks, incorporating natural gas price elasticity and regulatory enforcement intensity.
Practitioners should monitor EPA Total Maximum Daily Load allocation revisions and state-level 4R Nutrient Stewardship mandate diffusion for early signals of demand trajectory shifts. Forecasts reflect assumptions regarding regulatory enforcement durability and precision agriculture hardware adoption rates. Macroeconomic commodity price volatility, abrupt regulatory relaxation, or breakthrough bio-based formulation scale achievements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Potash Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Silicon Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market