
 Global Potash Fertilizer Market | 2026-2036
Global Potash Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Potash Fertilizer Market Foresight
Blended and compound fertilizer bundling is consolidating buyer choice across the potash value chain. Nutrien Ltd. leverages its integrated retail network to push bundled NPK formulations directly to commercial farms. The Mosaic Company anchors North American supply through its phosphate-potash co-location strategy. K+S Aktiengesellschaft specializes in sulfate of potash for chloride-sensitive crops, occupying a premium niche in European horticulture.
Potash fertilizer comprises potassium-bearing salts, primarily potassium chloride containing 60-62% K₂O equivalent, extracted through conventional underground mining or solution mining of evaporite deposits. Its primary commercial purpose is to correct soil potassium deficiency, a macronutrient essential for plant osmotic regulation and enzyme activation. Muriate of potash dominates volume trade as the lowest-cost potassium source, while sulfate of potash commands margin pools in high-value fruit and vegetable systems where chloride tolerance is limited. Fertigation application is expanding fastest among method categories, driven by precision agriculture adoption in greenhouse and intensive row-crop operations.
The EPA oversees water runoff standards affecting potash application rates in US watersheds, while the EU Green Deal's nutrient management targets are reshaping import specifications across member states. India's FSSAI and CEA coordinate on fertilizer quality benchmarks and power allocation for domestic production expansion. Stakeholders must monitor how carbon border adjustments and evolving mine permitting timelines in Saskatchewan and Belarus alter supply availability and contract structures.
Market Dynamics
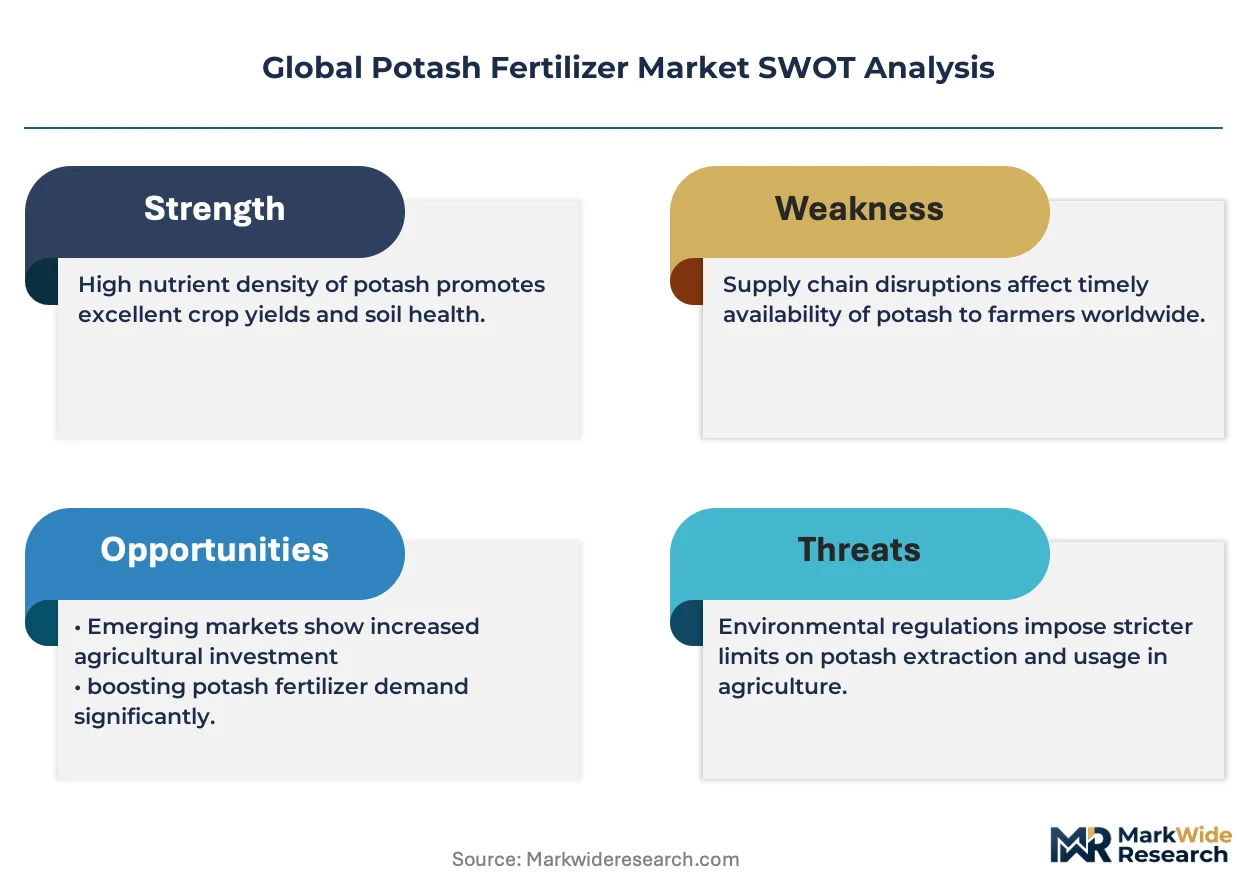
Supply concentration in Saskatchewan and Belarus is tightening contract structures as buyers seek origin diversification. The EU Green Deal's nutrient-efficiency mandates are compressing demand for standard muriate grades while accelerating sulfate of potash qualification timelines.
Growth Catalysts
- India's FSSAI subsidy programs:Government procurement pools are pulling import volumes toward record levels as food security mandates harden. Domestic blenders are expanding warehouse capacity to capture allocated tonnage.
- Fertigation technology:Precision agriculture adoption in Brazilian soybean operations is displacing broadcast application. Drip system installers are bundling soluble potassium products with irrigation hardware.
- EU Farm to Fork nutrient targets:Member-state import specifications are redirecting procurement toward certified low-chloride products. Horticulture buyers in Spain and Italy are qualifying sulfate grades for vegetable rotations.
Market Restraints
- Natural gas cost volatility:Solution mining energy intensity in Saskatchewan and New Mexico exposes production economics to Henry Hub price swings. Marginal operators face margin compression during winter heating-demand spikes.
- Supply concentration risk:Belarusian state-owned producers control roughly one-fifth of seaborne trade. Sanctions exposure and logistics bottlenecks through Lithuanian ports are forcing buyers to maintain dual-source inventories.
- Chloride sensitivity limitations:High-value fruit crops in California's Central Valley and Chilean avocado orchards cannot tolerate standard muriate grades. This technical ceiling fragments addressable demand across product categories.
Strategic Opportunities
- Indonesian palm oil expansion:Kalimantan plantation operators are underapplying potassium relative to agronomic optimums. Agronomy service providers can capture volume growth by demonstrating yield response curves.
- Carbon border adjustment mechanisms:The EU's CBAM framework creates premium positioning for low-carbon production routes. Saskatchewan solution mines with hydropower integration can certify intensity advantages.
- Controlled-release coating convergence:Polymer encapsulation technology is merging with potassium prill production. Specialty blenders in the Netherlands and Israel are piloting season-long nutrient delivery for greenhouse tomatoes.
Industry Challenges
- Mine geologist talent scarcity:Saskatchewan's potash belt competes with Nevada lithium and Arizona copper for subsurface mapping expertise. Operators are extending retirement timelines and automating core logging workflows.
- CE mark certification timelines:Sulfate of potash qualification under EU fertilizer product regulations requires 18-24 month stability testing. Importers are pre-positioning inventory to avoid spring application season stockouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Potash Fertilizer Market |
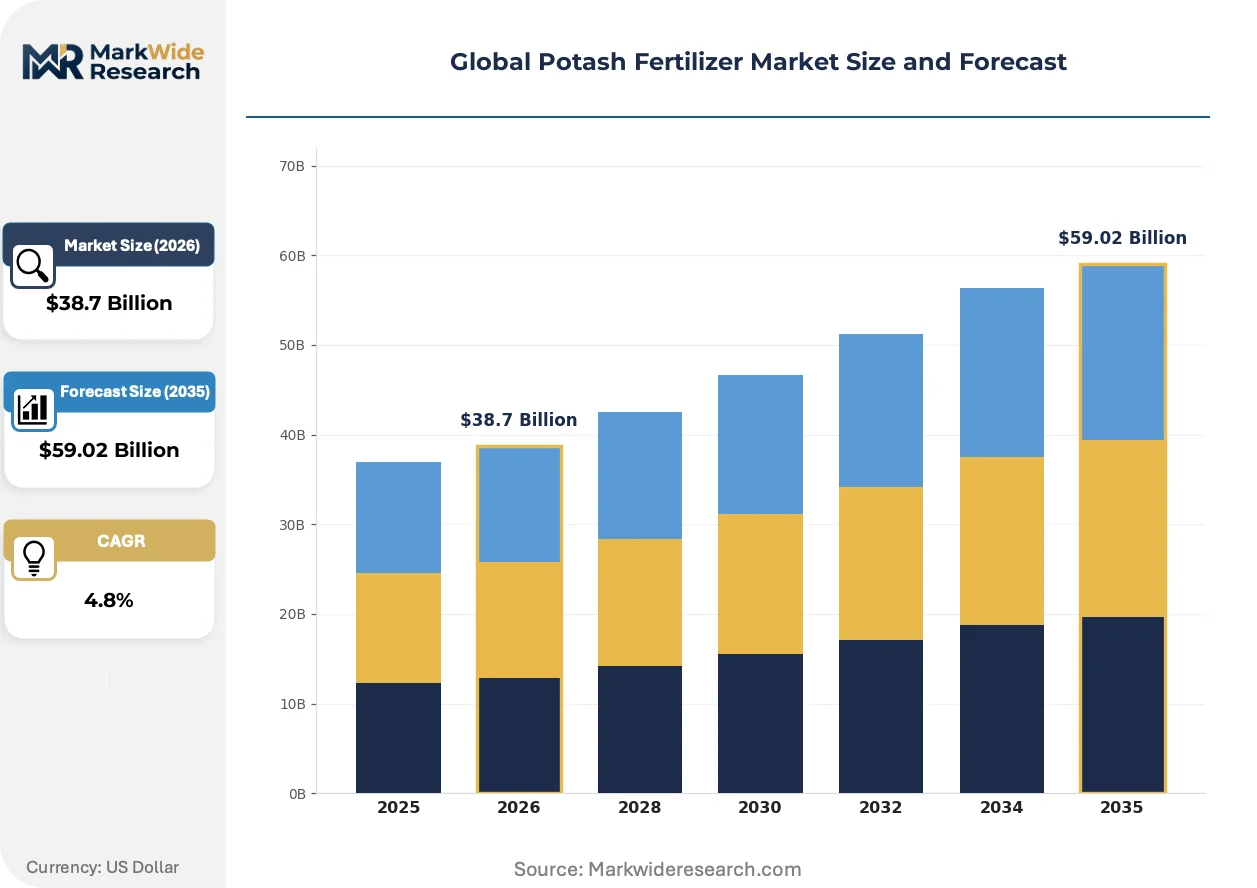
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Muriate of Potash, Sulfate of Potash, Potassium Nitrate, Potassium Magnesium Sulfate, Liquid Potash Crop Type: Cereals & Grains, Fruits & Vegetables, Oilseeds & Pulses, Cotton, Turf & Ornamentals Application Method: Basal Application, Foliar Application, Side Dressing, Fertigation End User: Commercial Farms, Smallholder Farms, Greenhouses, Nurseries |
| Companies Covered | JSC Belaruskali, Compass Minerals International Ltd., Nutrien Ltd., Rio Tinto Ltd., Intrepid Potash Inc., The Mosaic Company, K+S Aktiengesellschaft, BHP Billiton Ltd., Uralkali, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Potash Fertilizer Market Shifts & Advancements
Digital soil mapping and variable-rate application systems are compressing the gap between agronomic prescription and field execution. Equipment manufacturers and fertilizer distributors are converging on integrated service models.
Sensor-based potassium detection is modularizing application decision support. John Deere and CNH Industrial are integrating ion-selective electrode arrays into planter-mounted units. Brazilian sugarcane cooperatives are adopting real-time tissue testing to split potassium applications across growth stages. The technology is compressing agronomist-to-field latency from weeks to hours.
REACH fertilizer product regulations are forcing reformulation transparency across EU supply chains. Importers must disclose additive compositions and contaminant thresholds to notified bodies. Specialty crop distributors in Germany and Poland are qualifying alternative sulfate sources from Chilean brine operations to meet tightened chloride limits.
Direct farm purchasing is consolidating buyer power in North American row-crop regions. Large Illinois and Iowa operators are bypassing local cooperatives to negotiate railcar deliveries from Saskatchewan loaders. This channel compression is forcing regional distributors to add agronomy services and financing packages to defend position.
Global Potash Fertilizer Market Segmentation
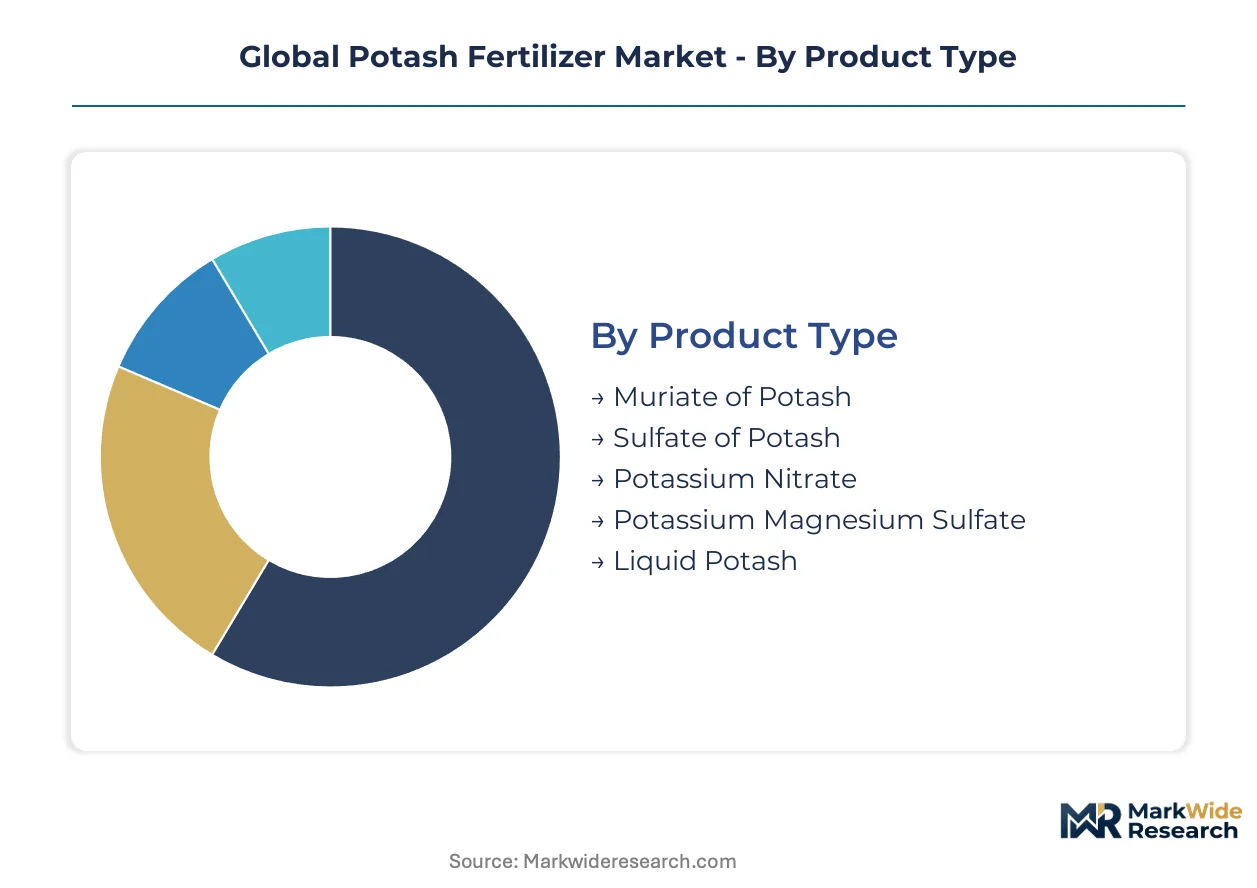
Potash fertilizer segmentation reflects divergent agronomic requirements across crop systems and farm scales. Product chemistry, application technology, and end-user purchasing power create distinct margin pools that suppliers must navigate simultaneously.
Product Type:
Cost tier separates commodity potassium salts from premium specialty grades.
- Muriate of Potash:Potassium chloride containing 60-62% K₂O equivalent dominates seaborne trade volumes as the lowest-cost potassium source. Indian government subsidy pools and Brazilian soybean operations pull imports toward record tonnage despite chloride content limitations.
- Sulfate of Potash:Potassium sulfate with negligible chloride content commands premium positioning in EU horticulture and California's Central Valley fruit systems. REACH fertilizer product regulations and EU Green Deal nutrient-efficiency mandates are accelerating qualification timelines for certified low-chloride grades.
- Potassium Nitrate:Dual-nutrient formulation supplying potassium and nitrogen without chloride; Israeli and Chilean producers target greenhouse tomato and high-value vegetable rotations.
- Potassium Magnesium Sulfate:Langbeinite-derived product addressing simultaneous sulfur and magnesium deficiencies; specialty blenders in the Netherlands pilot season-long nutrient delivery systems.
- Liquid Potash:Soluble potassium solutions compatible with drip irrigation hardware; Brazilian sugarcane cooperatives adopt real-time tissue testing to split applications across growth stages.
Muriate of Potash leads volumes today; Sulfate of Potash is gaining share fastest.
Crop Type:
Application intensity varies by crop value and potassium removal rates.
- Cereals & Grains:Wheat, rice, and corn systems account for bulk potassium consumption; Indian FSSAI procurement programs and rising food security mandates redirect import volumes toward record levels.
- Fruits & Vegetables:High-value horticulture demands chloride-sensitive grades; Spanish and Italian buyers qualify sulfate sources for vegetable rotations under EU Farm to Fork nutrient targets.
- Oilseeds & Pulses:Soybean and palm oil expansion in Brazil and Indonesian Kalimantan drives potassium depletion; agronomy service providers capture volume by demonstrating yield response curves.
- Cotton:Fiber crop with moderate potassium requirements; Indian domestic blenders expand warehouse capacity to capture allocated government tonnage.
- Turf & Ornamentals:Golf course and landscape maintenance segments; North American direct farm purchasing consolidates buyer power as large operators negotiate railcar deliveries.
Cereals & Grains retains the largest volume footprint; Fruits & Vegetables shows the steepest margin expansion.
Application Method:
Technology adoption curves separate precision agriculture adopters from conventional broadcast practitioners.
- Fertigation:Soluble potassium delivery through drip and micro-sprinkler systems; Brazilian soybean operations displace broadcast application as precision agriculture adoption accelerates.
- Basal Application:Pre-planting soil incorporation of granular products; Saskatchewan solution mines with hydropower integration target carbon border adjustment premium positioning.
- Foliar Application:Direct leaf-surface spraying for rapid deficiency correction; sensor-based potassium detection modularizes decision support through ion-selective electrode arrays.
- Side Dressing:Post-emergence banded application in row crops; Illinois and Iowa operators bypass local cooperatives for direct railcar procurement.
Basal Application maintains dominant volume; Fertigation is climbing the fastest.
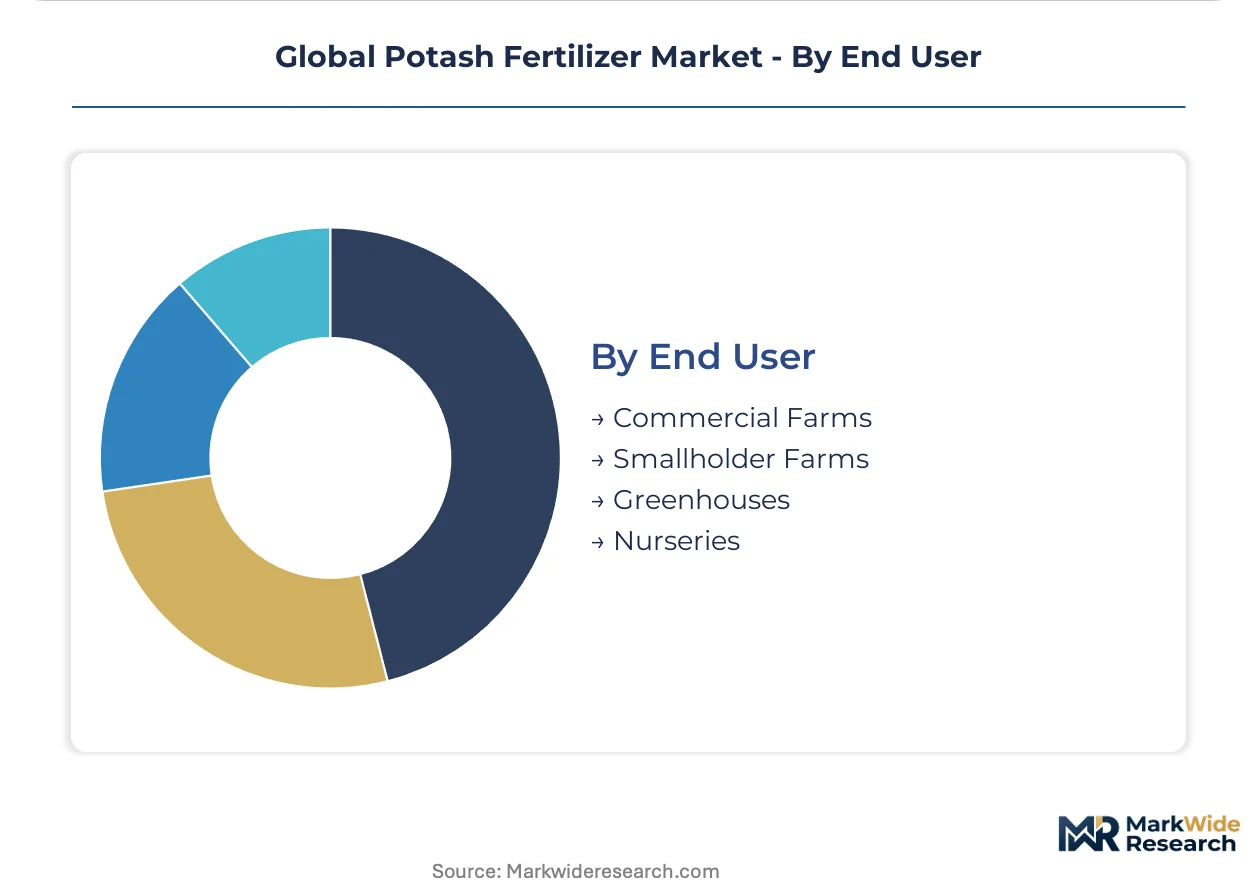
End User:
Scale and sophistication determine channel structure and service bundling requirements.
- Commercial Farms:Large-scale operations with in-house agronomy staff; North American channel compression forces regional distributors to add financing packages and technical services.
- Smallholder Farms:Fragmented landholdings dependent on government subsidy access; India's CEA coordinates power allocation for domestic production expansion serving this segment.
- Greenhouses:Controlled-environment agriculture with fertigation infrastructure; Dutch and Israeli specialty blenders pilot polymer encapsulation for season-long nutrient delivery.
- Nurseries:Containerized plant production requiring precise nutrient control; EPA water runoff standards constrain application rates in US watersheds serving this segment.
Commercial Farms absorb the majority of tonnage; Greenhouses demonstrate the strongest value-per-hectare metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Potash fertilizer production traces its industrial lineage to 19th-century German salt dome discoveries, with Stassfurt operations establishing the first commercial extraction methods that later migrated to Saskatchewan's vast evaporite deposits.
Canada
Saskatchewan's potash belt supplies roughly one-third of global seaborne trade through solution mining operations. The province's CEPA-regulated pipeline network and hydropower integration positions producers for EU carbon border adjustment premiums. Saskatoon-based engineering clusters automate core logging workflows to offset geologist talent scarcity.
Belarus
State-controlled producers command approximately twenty percent of international export volumes despite sanctions exposure through Lithuanian port bottlenecks. Domestic blenders maintain dual-source inventory strategies as logistics constraints harden contract structures. The Soligorsk mining district anchors extraction gravity despite geopolitical risk premiums.
India
FSSAI-coordinated subsidy programs and CEA power allocation for domestic production expansion pull import volumes toward record levels. Government procurement pools redirect warehouse capacity expansion toward allocated tonnage capture. Gujarat and Maharashtra port infrastructure handles the bulk of arriving muriate shipments.
Brazil
Soybean operations in Mato Grosso and Paraná displace broadcast application with fertigation precision systems. Agronomy service providers demonstrate yield response curves to plantation operators underapplying potassium relative to agronomic optimums. Santos port terminals manage seasonal import surges.
Germany
REACH fertilizer product regulations and EU Green Deal nutrient-efficiency mandates compress demand for standard muriate grades. Kassel-based specialty blenders pilot polymer encapsulation for sulfate of potash season-long delivery. The country's central European position qualifies redistribution toward Spanish and Italian horticulture buyers.
Global Potash Fertilizer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chloride-sensitivity and carbon-intensity dimensions. The market structure concentrates around integrated miners with captive ore bodies and specialty blenders with formulation expertise. Three archetypes dominate: Saskatchewan-based solution miners with hydropower integration, German sulfate specialists serving EU horticulture, and diversified resource conglomerates with potash as non-core revenue. Competitive moves center on railcar direct-delivery contracts to North American commercial farms and 18-24 month CE mark pre-positioning for EU qualification timelines.
Within the integrated mining tier, Nutrien Ltd. and The Mosaic Company represent North American supply anchoring through retail network control and phosphate-potash co-location. K+S Aktiengesellschaft occupies the premium sulfate specialization vector for chloride-sensitive crop systems. These three entities exemplify divergent strategic positioning across commodity and specialty grade portfolios.
| Leading Market Players |
|---|
| JSC Belaruskali |
| Compass Minerals International Ltd. |
| Nutrien Ltd. |
| Rio Tinto Ltd. |
| Intrepid Potash Inc. |
| The Mosaic Company |
| K+S Aktiengesellschaft |
| BHP Billiton Ltd. |
| Uralkali |
| Others |
Supply & Pricing Matrix
Solution mining geologist talent scarcity in Saskatchewan and New Mexico widens labor-cost differentials between established operators and marginal entrants, compressing spreads between premium sulfate grades and standard muriate pricing tiers as certification timelines extend.
Pricing Analysis
Contract-based long-term offtake agreements dominate seaborne trade, with pricing stratifying across premium, standard, and economy tiers driven by chloride content certification and carbon intensity benchmarking. Price differentiation hinges on EU Green Deal nutrient-efficiency compliance and volume scale commitments from Indian government procurement pools. Margins are tightening due to natural gas cost volatility exposing solution mining economics to Henry Hub spikes. Smallholder farms dependent on subsidy access exhibit highest price sensitivity; greenhouse operators purchasing sulfate of potash for chloride-sensitive rotations show lowest.
Supply Chain Analysis
Empty railcar repositioning and bulk vessel chartering constitute the primary reverse-logistics flows, with Saskatoon-based engineering clusters automating core logging to offset geologist attrition. Production concentrates in Canada, Belarus, and Russia, drawing from sylvinite and carnallite ore bodies. The supply chain rests on ammonia and natural gas feedstocks plus specialized extraction equipment. Single-source vulnerability through Lithuanian port bottlenecks for Belarusian tonnage forces dual-source inventory maintenance. Distribution runs through integrated miner retail networks, direct railcar procurement by large North American farms, and government allocation channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global potash fertilizer market reads as a late-cycle quality story, with EU Farm to Fork nutrient targets redirecting procurement toward certified low-chloride sulfate grades commanding sustained premium positioning.
For Market Incumbents: Lock in railcar direct-delivery contracts with Illinois and Iowa commercial farms to defend against channel compression from cooperative bypass. Secure 18-24 month CE mark pre-positioning for sulfate of potash qualification under REACH fertilizer product regulations to avoid spring application stockouts. Carbon border adjustment premium positioning requires hydropower integration documentation for Saskatchewan solution mines. For New Entrants and Emerging Players: Polymer encapsulation technology for controlled-release potassium prills offers entry into Dutch and Israeli greenhouse tomato systems where season-long nutrient delivery commands value-per-hectare premiums. Target Indonesian Kalimantan palm oil plantations underapplying potassium relative to agronomic optimums, demonstrating yield response curves through agronomy service bundling rather than commodity tonnage competition. For Investors and Strategic Acquirers: Diversified resource conglomerates with potash as non-core revenue are the most active acquirer in this space, seeking captive ore bodies to anchor integrated supply positions. Acquisition target archetypes include German sulfate specialists with EU horticulture qualification timelines and Brazilian fertigation technology installers with precision agriculture adoption curves. Monitor EU carbon border adjustment mechanism implementation timing as inflection indicator for low-carbon production route premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Ore Bodies | Saskatchewan solution miners secure supply anchoring against Belarusian sanctions exposure and logistics bottlenecks. |
| CE Marking Pathway for Sulfate Grades | Specialty blenders pre-position inventory to meet EU fertilizer product regulation stability testing timelines. |
| Long-term Supply Agreement with Government Procurement | Domestic blenders capture allocated Indian FSSAI subsidy tonnage through warehouse capacity expansion. |
| Green Manufacturing Transition to Hydropower Integration | Producers certify carbon intensity advantages for EU carbon border adjustment premium positioning. |
| Joint Venture for Fertigation Technology Bundling | Brazilian cooperatives adopt drip system installers pairing soluble potassium with irrigation hardware. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and South America, with primary inputs from each region combining interviews with mine operations managers, procurement leads at downstream blenders, agronomy service providers, and government fertilizer subsidy administrators. Secondary validation draws from customs and trade data, SEC 10-K filings, Indian FSSAI procurement disclosures, and EU fertilizer product regulation filings. Bottom-up tonnage modeling and top-down value estimation triangulate market sizing.
Granularity-level modeling disaggregates volume and value across product chemistry tiers, crop system intensity bands, application technology adoption curves, and end-user scale categories throughout the forecast period. CAGRs derive from segment-level growth trajectory analysis weighted by regional demand pull factors. Forecast inputs include Indian government subsidy allocation trajectories, EU Green Deal implementation pacing, and Brazilian precision agriculture adoption curves.
The model holds under stable geopolitical conditions for Belarusian supply routes and sustained natural gas pricing regimes; deviation in sanctions exposure or Henry Hub volatility would shift production economics and contract structures. Practitioners should monitor EU carbon border adjustment mechanism enforcement timing and Saskatchewan mine permitting timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Australia Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Russia Fertilizers Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Asia-Pacific Organic Fertilizer Market