
 India Controlled Release Fertilizer Market | 2026-2036
India Controlled Release Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
India Controlled Release Fertilizer Market Foresight
The Nutrient Based Subsidy scheme is broadening the cost-of-entry calculus for new manufacturers seeking government procurement eligibility. ICL Group Ltd leverages its polymer coating expertise to sustain premium positioning in the western state markets. Coromandel International Ltd anchors its portfolio through backward integration into coating material supply. IFFCO competes on cooperative distribution density, reaching farmer networks that private labels struggle to match.
Controlled release fertilizers employ polymer or sulfur coatings to meter nutrient diffusion across 30-120 day windows, matching crop uptake curves while reducing leaching losses. Polymer-coated grades command the widest margin pools due to precision release kinetics and compatibility with high-value horticultural crops. Sulfur-coated variants occupy the volume-intensive tier, serving broad-acre cereals where cost sensitivity dominates farmer selection. The application split tilts toward agricultural and horticultural end uses, with greenhouse operators representing the fastest adoption segment as water-use efficiency regulations tighten.
BIS certification requirements and the Fertilizer Control Order shape product standards, while the PLI scheme for agrochemical manufacturing incentivizes domestic coating capacity expansion. The CEA monitors energy inputs at production facilities, indirectly influencing sulfur-coated product economics through power cost pass-throughs. Stakeholders must track how state-level subsidy disbursement timelines synchronize with kharif and rabi planting windows to optimize inventory positioning and farmer financing programs.
Market Dynamics
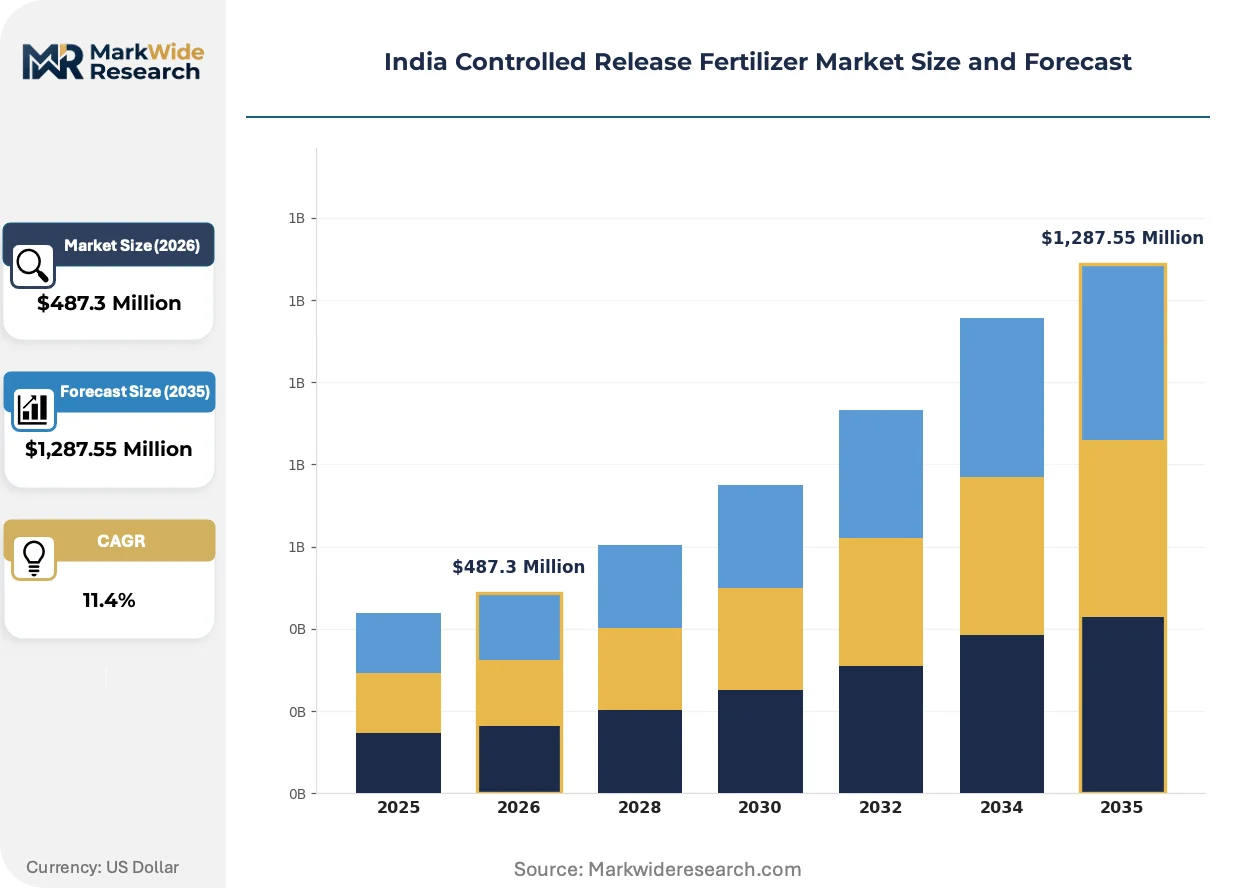
The Nutrient Based Subsidy scheme is redirecting procurement eligibility toward efficiency-certified products, compressing margins for uncertified manufacturers while rewarding coating technology investments. State-level disbursement timelines now dictate inventory positioning across kharif and rabi planting windows.
Growth Catalysts
- Polymer coating technology:Precision release kinetics matching crop uptake curves are reducing leaching losses in Maharashtra horticulture belts. Adoption spreads as water-use efficiency regulations tighten for greenhouse operators.
- PLI scheme for agrochemical manufacturing:Domestic coating capacity expansion receives direct fiscal support. Incentives target backward integration into coating material supply chains.
- Maharashtra and Gujarat specialty crop clusters:Horticulture and precision farming overlap creates concentrated demand pockets. Western state distribution networks prioritize polymer-coated grades for high-value applications.
Market Restraints
- Petrochemical input volatility:Polymer resin prices fluctuate with crude oil movements. Coating material costs transmit directly to finished product margins.
- Sulfur-coated volume tier compression:Broad-acre cereal farmers exhibit extreme cost sensitivity. Price competition from conventional fertilizers limits premium capture.
- BIS certification timelines:Fertilizer Control Order compliance requires extended laboratory validation. New entrants face 12-18 month approval windows before procurement eligibility.
Strategic Opportunities
- Southern state horticulture expansion:Karnataka and Tamil Nadu greenhouse segments remain underpenetrated by controlled release formulations. Water-scarce districts present targeted entry points.
- CEA energy monitoring integration:Power cost pass-through transparency enables sulfur-coated product economics optimization. Facilities with captive renewable supply gain structural advantage.
- Cooperative distribution density:Farmer network reach through cooperative channels exceeds private label penetration in rural districts. Partnership models unlock last-mile access.
Industry Challenges
- Coating technician skill scarcity:Polymer application precision requires specialized training absent from standard agricultural extension programs.
- Legacy inventory synchronization:Kharif and rabi subsidy disbursement misalignment strains working capital cycles for distributors.
- Coating equipment capex intensity:Fluidized bed and drum coating lines demand substantial upfront investment before volume break-even.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Controlled Release Fertilizer Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,287.55 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, NPK, Sulfur Coated, Polymer Coated Application: Agricultural, Horticultural, Turf, Greenhouse Technology: Coating, Encapsulation, Slow-Release, Controlled-Release End User: Farmers, Agricultural Cooperatives, Research Institutes, Crop Consultants |
| Companies Covered | ICL Group Ltd, COMPO EXPERT GmbH, Haifa Negev technologies LTD, Indian Farmers Fertiliser Cooperative Limited (IFFCO), Coromandel International Ltd., Yara Fertilisers India Pvt. Ltd., Deepak Fertilisers and Petrochemicals Corporation Limited, Hebei Sanyuanjiuqi Fertilizer Co., Ltd, Florikan ESA LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Controlled Release Fertilizer Market Shifts & Advancements
Release kinetics customization is reshaping competitive differentiation as manufacturers engineer crop-specific formulations rather than generic 30-120 day windows.
Biodegradable polymer coatings is overtaking conventional synthetic alternatives in premium horticulture segments. Maharashtra grape and pomegranate growers are switching rapidly to starch-derivative and cellulose-based formulations. This transition is compressing synthetic polymer margins while opening patent-protected formulation licensing revenue streams.
The Fertilizer Control Order amendment tightening heavy metal contamination limits is forcing coating material supplier audits. Manufacturers must now document polymer resin provenance through batch-level traceability. Sulfur-coated urea producers in Gujarat face the steepest compliance reconfiguration as legacy sulfur sources require purification upgrades.
Greenhouse operator procurement consolidation is replacing fragmented individual farmer purchasing. Large integrated horticulture enterprises in Nashik and Pune districts now negotiate direct manufacturer contracts bypassing dealer networks. This channel compression is most visible in western Maharashtra where 50+ acre protected cultivation clusters centralize input sourcing decisions.
India Controlled Release Fertilizer Market Segmentation
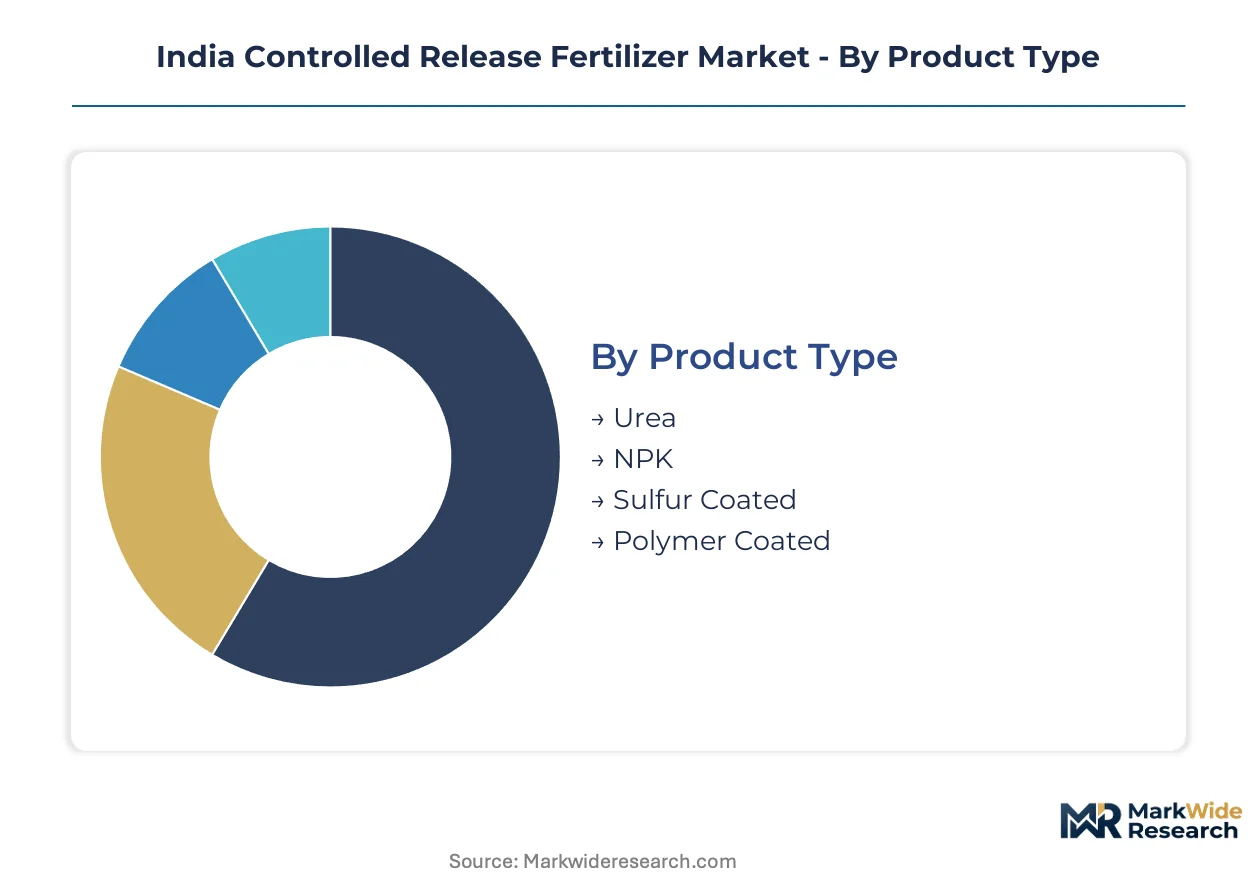
Segmentation in the India controlled release fertilizer market reveals how coating technologies, crop applications, and procurement channels create distinct margin pools. Manufacturers must align product portfolios with subsidy eligibility tiers and regional crop economics to capture value.
Product Type:
Integration depth varies sharply across product categories, with polymer-coated grades functioning as standalone precision inputs while sulfur-coated variants embed into bulk procurement systems.
- Polymer Coated:Synthetic or biodegradable polymer membranes enable precise nutrient diffusion across 30-120 day windows calibrated to crop uptake curves. Maharashtra grape and pomegranate growers in Nashik and Pune districts drive concentrated demand as water-use efficiency regulations tighten for protected cultivation. Premium positioning depends on BIS certification under the Fertilizer Control Order.
- Sulfur Coated:Elemental sulfur barriers surrounding urea granules provide cost-effective release modulation for broad-acre cereals. Gujarat cereal farmers exhibit extreme price sensitivity, compressing margins despite volume throughput. CEA energy monitoring at production facilities indirectly shapes economics through power cost pass-through mechanisms.
- Urea:Base substrate for most coating applications, with controlled-release variants commanding subsidy premiums over conventional grades under the Nutrient Based Subsidy scheme.
- NPK:Compound formulations with multi-nutrient coatings address balanced fertilization requirements in Tamil Nadu rice and vegetable systems.
Polymer-coated grades lead volumes today; biodegradable polymer variants are gaining share fastest in western state horticulture belts.
Application:
Cost tier stratification separates high-value horticulture segments from volume-intensive cereal applications, with greenhouse operators occupying the premium position.
- Greenhouse:Protected cultivation enterprises in Nashik and Pune districts centralize procurement decisions, bypassing dealer networks through direct manufacturer contracts. Water-scarce districts face tightening irrigation efficiency mandates that accelerate controlled-release adoption.
- Horticultural:Open-field fruit and vegetable operations in Karnataka and Tamil Nadu present underpenetrated expansion opportunities. Starch-derivative and cellulose-based biodegradable coatings are displacing synthetic alternatives in premium segments.
- Agricultural:Broad-acre cereal and oilseed cultivation across Gujarat and Maharashtra generates volume demand but limits premium capture due to farmer cost sensitivity.
- Turf:Golf course and landscaping applications remain nascent, concentrated around urban centers in Maharashtra and Karnataka with limited subsidy access.
Horticultural applications lead volumes today; greenhouse segments are expanding most quickly as protected cultivation clusters consolidate.
Technology:
Maturity gradients separate established coating methods from emerging encapsulation approaches, with technology choice determining regulatory pathway complexity.
- Coating:Fluidized bed and drum application systems represent the dominant production method, with equipment capex intensity creating barriers for new entrants. Polymer resin provenance documentation now required under amended Fertilizer Control Order heavy metal limits.
- Controlled-Release:Precision kinetics engineering enables crop-specific formulation customization rather than generic release windows. Patent-protected biodegradable formulations generate licensing revenue streams.
- Slow-Release:Conventional diffusion-based systems serve cost-sensitive market tiers with simpler regulatory approval pathways.
- Encapsulation:Advanced matrix embedding technologies remain developmental, targeting high-value specialty crops with complex nutrient timing requirements.
Coating technology leads volumes today; controlled-release formulations are climbing the fastest as manufacturers engineer crop-specific kinetics.
End User:
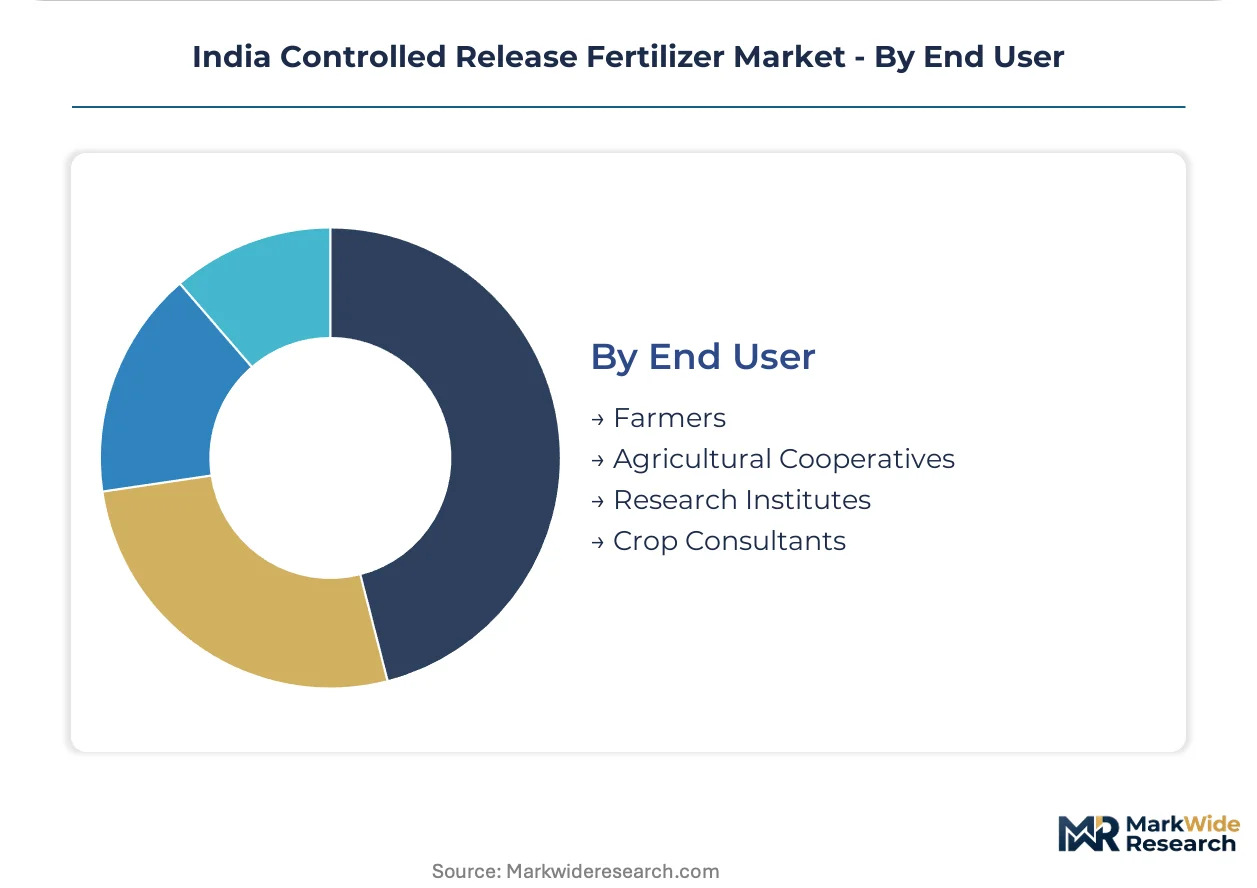
Customer type determines channel economics, with cooperative density exceeding private label reach in rural districts while research institutes shape technology validation.
- Farmers:Individual procurement dominates volume but fragments purchasing power; kharif and rabi subsidy disbursement misalignment strains working capital cycles.
- Agricultural Cooperatives:IFFCO and state-level cooperative networks provide last-mile access that private labels struggle to match, particularly in Maharashtra and Gujarat hinterlands.
- Research Institutes:Indian Agricultural Research Institute and state agricultural universities validate release kinetics claims, influencing BIS certification outcomes.
- Crop Consultants:Precision farming advisors in western state clusters drive specification decisions for high-value horticulture enterprises.
Agricultural cooperatives lead volumes today; crop consultants are gaining influence fastest as greenhouse operators consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controlled release fertilizer technology first achieved commercial scale in Israel during the 1960s before spreading to European and North American agricultural markets. India emerged as a concentrated demand center during the 2000s as water scarcity intensified across western and southern state clusters. The current geographic distribution reflects this diffusion pattern, with adoption concentrated where horticulture value chains and subsidy infrastructure overlap.
Maharashtra
Nashik and Pune districts host India's largest protected cultivation clusters, where grape and pomegranate growers drive polymer-coated urea consumption. The state agricultural department's precision farming incentives align with BIS certification requirements under the Fertilizer Control Order. Greenhouse operators in these districts now negotiate direct manufacturer contracts, bypassing traditional dealer networks entirely.
Gujarat
Broad-acre cereal cultivation across Saurashtra and North Gujarat generates volume demand for sulfur-coated variants, though extreme farmer price sensitivity compresses margins. The state's industrial corridor hosts domestic coating capacity expansion projects incentivized under the PLI scheme for agrochemical manufacturing. CEA energy monitoring at production facilities in Vadodara and Bharuch districts shapes sulfur-coated product economics through power cost pass-through mechanisms.
Karnataka
Bangalore Rural and Hassan districts present underpenetrated expansion opportunities in greenhouse and open-field horticulture segments. The state's water-scarce districts face tightening irrigation efficiency mandates that accelerate controlled-release adoption. Biodegradable polymer coatings are displacing synthetic alternatives among premium vegetable exporters in this region.
Tamil Nadu
Rice and vegetable systems in the Cauvery Delta generate demand for compound NPK formulations with multi-nutrient coatings. State agricultural universities validate release kinetics claims, influencing BIS certification outcomes for manufacturers seeking procurement eligibility. The Nutrient Based Subsidy scheme redirects state procurement toward efficiency-certified products, compressing margins for uncertified suppliers.
India Controlled Release Fertilizer Market Competitive Landscape
The competitive structure tilts toward cooperative-backed domestic incumbents with established last-mile distribution density. Three distinct archetypes occupy the vendor landscape: multinational coating technology specialists with polymer expertise, domestic fertilizer majors leveraging backward integration into coating material supply, and cooperative networks matching government procurement eligibility requirements. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players racing to secure BIS certification before subsidy disbursement windows.
Among multinational specialists, ICL Group Ltd and COMPO EXPERT GmbH exemplify the premium-tier archetype built on polymer coating expertise. Domestic majors Coromandel International Ltd and IFFCO occupy positions anchored in cooperative distribution density and backward integration capabilities. Haifa Negev technologies LTD represents the technology-licensing vector, while Yara Fertilisers India Pvt. Ltd. sits within the scale-driven tier serving broad-acre applications.
| Leading Market Players |
|---|
| ICL Group Ltd |
| COMPO EXPERT GmbH |
| Haifa Negev technologies LTD |
| Indian Farmers Fertiliser Cooperative Limited (IFFCO) |
| Coromandel International Ltd. |
| Yara Fertilisers India Pvt. Ltd. |
| Deepak Fertilisers and Petrochemicals Corporation Limited |
| Hebei Sanyuanjiuqi Fertilizer Co., Ltd |
| Florikan ESA LLC |
| Others |
Supply & Pricing Matrix
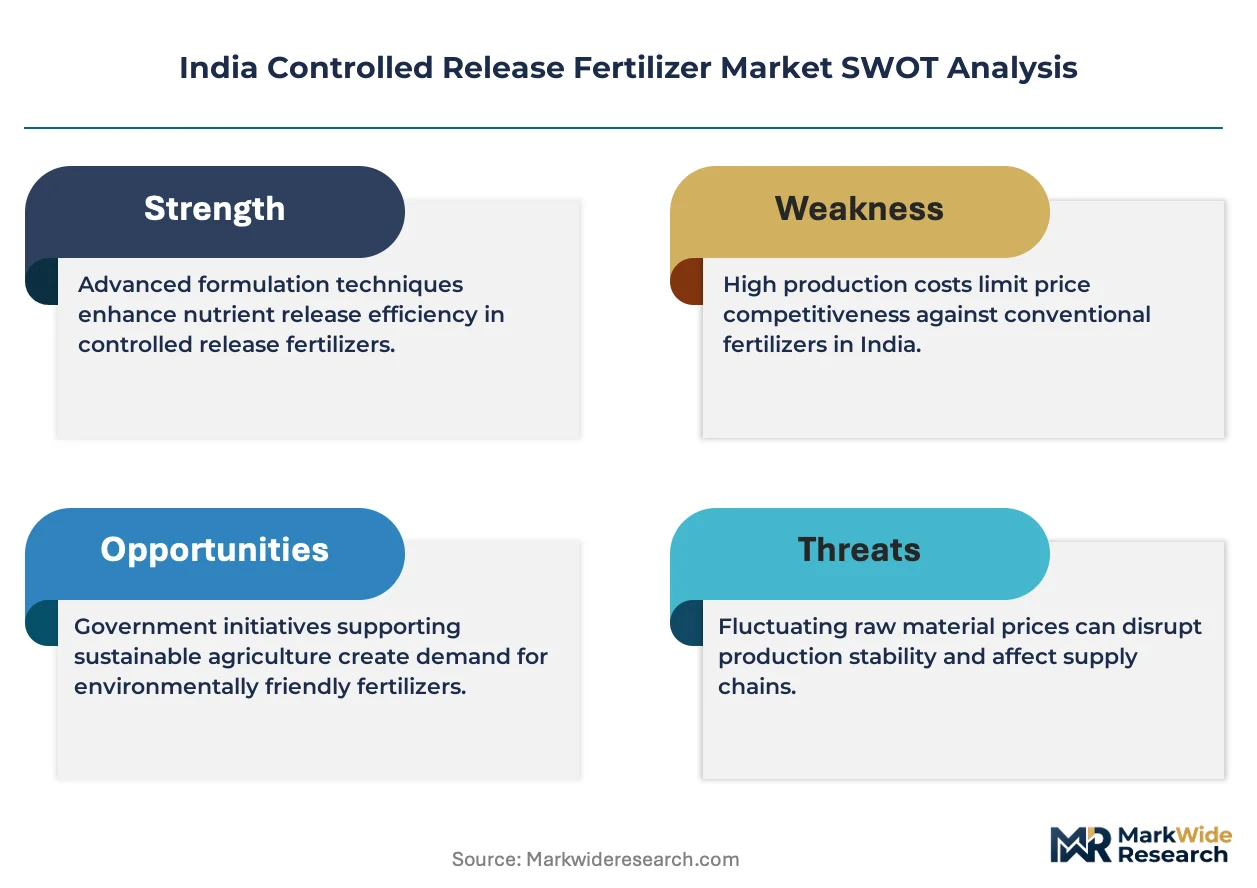
Certification-grade bifurcation between BIS-validated polymer-coated formulations and uncertified sulfur-coated alternatives shapes both margin capture and procurement channel access across Maharashtra and Gujarat. The Nutrient Based Subsidy scheme rewards efficiency-certified products with premium disbursement rates while compressing margins for uncertified manufacturers, forcing supply chain reconfiguration toward coating material backward integration.
Pricing Analysis
Coating-technology bundling separates premium polymer formulations from uncoated base fertilizer sales. Pricing stratifies across premium, standard, and economy tiers driven by BIS certification status and release-kinetics precision. Pricing pressure stems from petrochemical input volatility transmitting directly to polymer resin costs. Broad-acre cereal farmers in Gujarat exhibit extreme price sensitivity, while greenhouse operators in Nashik prioritize performance over cost.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for agrochemical manufacturing are redirecting coating capacity expansion toward Gujarat and Maharashtra production corridors. Raw material supply draws from Saudi Arabian sulfur sources, Indian petrochemical polymer resin producers, and domestic urea substrate from IFFCO and Coromandel facilities. Single-source vulnerability concentrates in imported polymer resin grades. Distribution runs through cooperative networks in rural districts and direct manufacturer contracts for consolidated greenhouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biodegradable polymer coatings as Maharashtra horticulture shifts toward starch-derivative formulations, compressing synthetic polymer cost structures while opening premium-tier licensing revenue.
For Market Incumbents: Extend biodegradable coating formulation portfolios to capture Maharashtra grape and pomegranate grower switching behavior. Deepen captive supply of coating materials through backward integration into polymer resin production. Defend against emerging domestic coating specialists by accelerating BIS certification timelines ahead of subsidy disbursement windows. For New Entrants and Emerging Players: Launch via Karnataka and Tamil Nadu cooperative distribution partnerships to bypass entrenched western state networks. Target underpenetrated greenhouse segments in Bangalore Rural and Hassan districts where water-scarcity mandates accelerate adoption. Enter through biodegradable coating technology licensing rather than capital-intensive manufacturing buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where coating equipment capex intensity exceeds working capital capacity of regional distributors. Long-term viability favors manufacturers with integrated coating material supply and validated release-kinetics patents. Acquisition targets include mid-cap coating technology specialists with BIS certification and southern state distribution access. Watch for PLI scheme disbursement acceleration as inflection signal for domestic capacity profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Materials | Captive polymer resin supply insulates margins from petrochemical volatility under CEA energy monitoring. |
| Biodegradable Formulation Patent Licensing | Starch-derivative coatings generate recurring revenue as Maharashtra growers switch from synthetic alternatives. |
| BIS Certification Acceleration | Fertilizer Control Order compliance unlocks Nutrient Based Subsidy eligibility ahead of competitor approval timelines. |
| Direct Manufacturer Contracting | Bypassing dealer networks captures Nashik and Pune greenhouse procurement consolidation trends. |
| Southern State Cooperative Partnership | IFFCO-aligned distribution density in Karnataka and Tamil Nadu exceeds private label rural penetration. |
Research Methodology
Multiple input streams — primary interviews with coating plant managers and fertilizer procurement officers at agricultural cooperatives, secondary validation through Fertilizer Control Order filings and PLI scheme disbursement records, and customs data on polymer resin imports — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed technical R&D directors at domestic coating facilities, state agricultural university researchers validating release kinetics, and distribution channel partners across Maharashtra and Gujarat hinterlands.
Data-stream reconciliation anchored volume and value outputs across coating technology type, crop application tier, and procurement channel structure. The analytical framework modeled polymer-coated versus sulfur-coated grade splits, BIS certification status segments, and regional subsidy disbursement timing across the projection horizon. CAGRs derived from historical adoption curves in western state horticulture belts and projected PLI scheme capacity additions. Industry-specific inputs included CEA energy cost pass-through coefficients and kharif-rabi planting window synchronization patterns.
Several conditions sit outside the modeled scope, including unforeseen Fertilizer Control Order amendments to heavy metal limits, abrupt petrochemical price shocks exceeding historical volatility bands, and state-level subsidy disbursement delays disrupting inventory cycles. Forecasts reflect documented assumptions regarding PLI scheme continuity and cooperative network stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
Global Micronutrient Fertilizer Market
Fertilizers
Brazil Fertilizers Market