
 Middle East and Africa Specialty Fertilizer Market | 2026-2036
Middle East and Africa Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Specialty Fertilizer Market Foresight
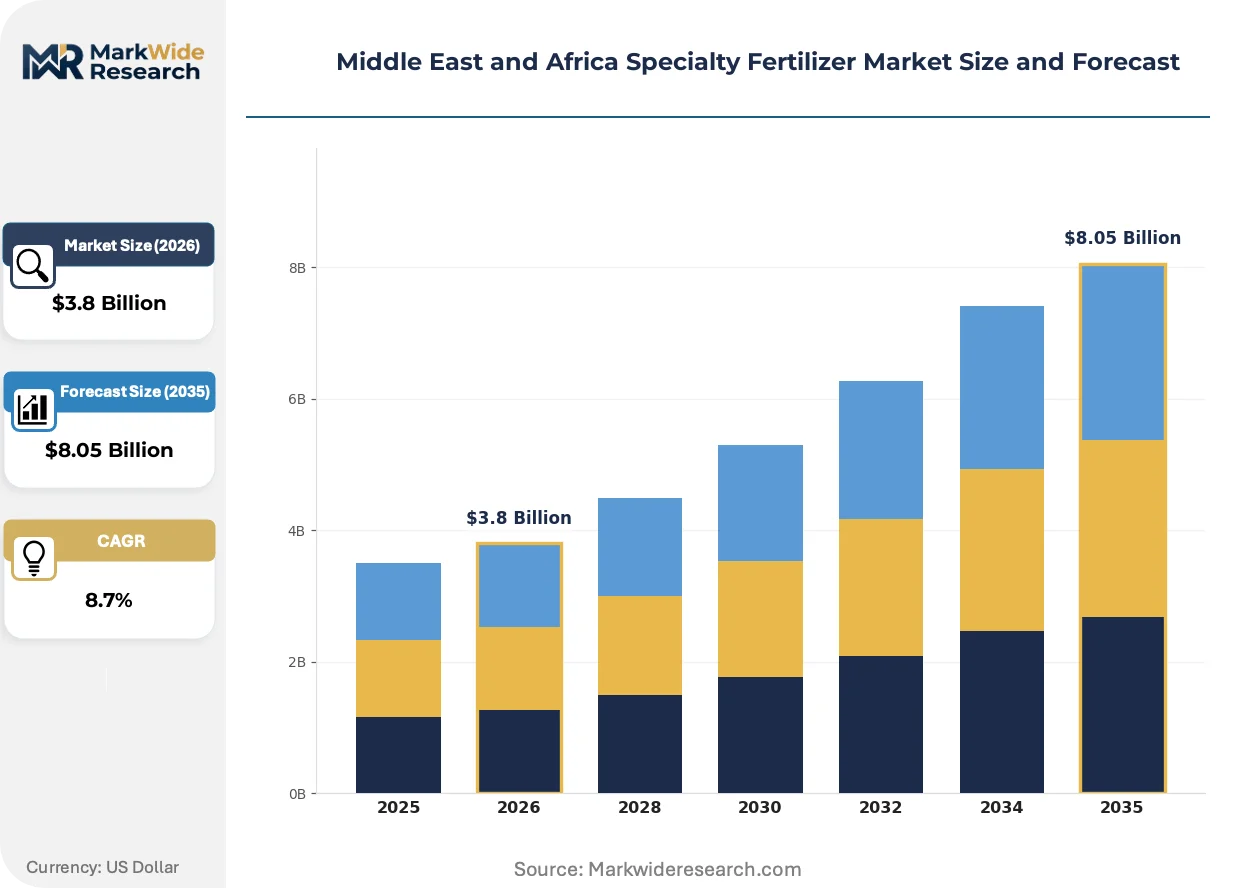
Project finance tied to sovereign agricultural development programs is rewriting competitive entry rules across the Middle East and Africa specialty fertilizer landscape. Yara International ASA leverages its integrated ammonia and nitrate network to sustain cost advantages in liquid fertilizer supply. OCP Group anchors Moroccan phosphate conversion into higher-margin specialty outputs. ICL Group Ltd differentiates through bromine-extracted potassium derivatives tailored to regional soil chemistry.
Specialty fertilizers in the Middle East and Africa encompass chemically or physically modified nutrient formulations engineered for targeted release kinetics, enhanced micronutrient availability, or application-specific delivery—typically incorporating polymer coatings, urease inhibitors, or chelated trace elements to optimize plant uptake efficiency under arid or saline conditions. Controlled-release fertilizers command premium positioning in high-value export crop segments where labor costs and nutrient leaching risks concentrate margin pools. Liquid fertilizers represent the fastest-expanding formulation class, driven by mechanized drip irrigation expansion in Israeli, Egyptian, and Saudi Arabian protected cultivation. Organic fertilizers remain structurally constrained by raw material collection logistics and certification fragmentation across national boundaries.
Saudi Arabia's SFDA and the UAE's MOHAP enforce fertilizer registration and contaminant thresholds that shape product approval timelines and import access conditions. Egypt's Ministry of Agriculture and Land Reclamation administers subsidy eligibility criteria that steer formulation preferences toward domestically blended solutions. Stakeholders must monitor how Gulf sovereign wealth capital allocation to food security programs reshapes procurement centralization and long-term offtake contracting structures.
Market Dynamics
Water scarcity across the Middle East and Africa is forcing a structural pivot toward precision delivery systems that minimize nutrient runoff and maximize uptake efficiency in arid cultivation zones.
Growth Catalysts
- Drip Irrigation Expansion:Mechanized protected cultivation in Israel, Egypt, and Saudi Arabia is pulling liquid fertilizer demand upward as growers retrofit open-field operations with fertigation infrastructure.
- SFDA Registration Streamlining:Saudi Arabia's consolidated fertilizer approval pathway is shortening product entry timelines for specialty formulations targeting high-value export crops.
- Phosphate Downstream Investment:Moroccan conversion capacity expansion is anchoring regional supply security for enhanced-efficiency derivatives serving water-stressed agricultural zones.
Market Restraints
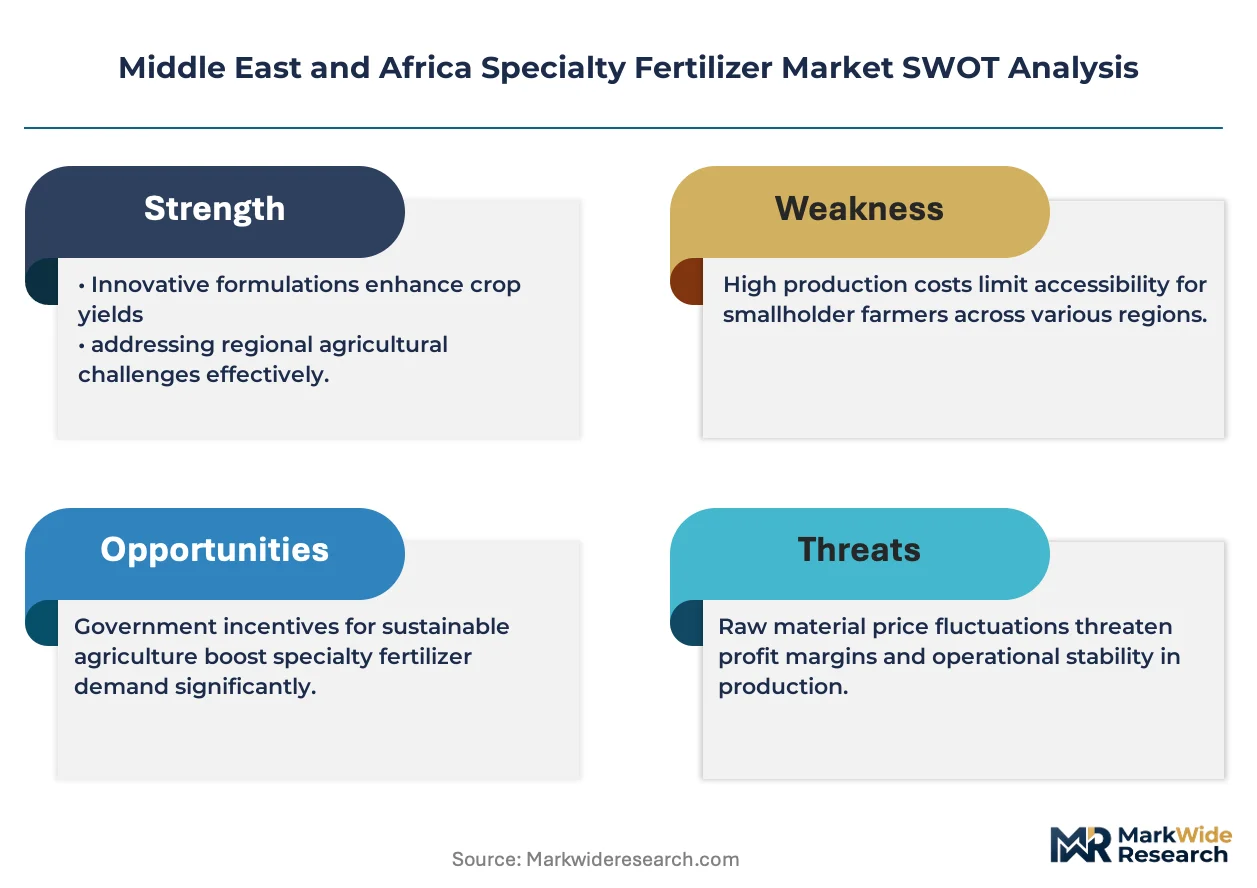
- Sulfur and Phosphate Feedstock Volatility:Input cost swings for phosphate rock and sulfuric acid concentrate margin pressure on domestic blending operations.
- Single-Source Concentration:Moroccan phosphate dominance creates supply vulnerability for nitrogen-phosphate compound formulations across import-dependent markets.
- Organic Certification Fragmentation:Incompatible national standards between Egypt, South Africa, and Gulf states block cross-border organic fertilizer trade scalability.
Strategic Opportunities
- Nile Delta Greenhouse Density:Egypt's concentrated protected cultivation cluster offers captive offtake potential for foliar and liquid specialty systems.
- Controlled-Release Citrus Applications:South African orchard precision adoption opens premium positioning for polymer-coated formulations reducing labor input.
- Food Security Capital Allocation:Gulf sovereign wealth deployment into agricultural self-sufficiency programs is restructuring long-term procurement toward centralized specialty fertilizer contracting.
Industry Challenges
- Soil Chemistry Specialization Gap:Field agronomists trained in saline-alkaline condition management remain scarce across North African and Levantine markets.
- SFDA-MOHAP Divergence:Non-harmonized contaminant thresholds between Saudi Arabia and UAE force dual registration costs for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Specialty Fertilizer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controlled-Release Fertilizers, Organic Fertilizers, Liquid Fertilizers, Foliar Fertilizers Application: Crop Production, Turf Management, Landscape Gardening, Greenhouse Cultivation Formulation: Granular, Powder, Liquid, Suspended Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale |
| Companies Covered | Safsulphur, Unikeyterra Chemical, Yara International ASA, Kynoch Fertilizer, OCP Group, ICL Group Ltd, Foskor, Azra Group AS, K+S Aktiengesellschaft, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Specialty Fertilizer Market Shifts & Advancements
Formulation science and application hardware are converging to collapse the efficiency gap between conventional and specialty nutrient delivery in water-constrained environments.
Polymer-coated controlled-release fertilizers are collapsing the historical trade-off between application labor reduction and nutrient precision in South African citrus and Egyptian greenhouse operations. Growers operating under drip irrigation are adopting these formulations at accelerating rates to synchronize nutrient release with crop phenology. The technology is collapsing leaching losses that previously made specialty premiums economically unviable in sandy soils.
Egypt's Ministry of Agriculture and Land Reclamation subsidy eligibility criteria are redirecting formulation preferences toward domestically blended specialty solutions. The policy is compressing import market share for finished controlled-release products while expanding tolling opportunities for regional compounders. Protected cultivation operators in the Nile Delta are responding by qualifying local blenders for precision fertigation supply contracts.
Centralized procurement through Gulf sovereign wealth food security programs is consolidating buyer power and extending contract durations. Traditional distributor networks serving Saudi Arabian and Emirati growers are losing volume to direct mill-to-farm arrangements negotiated by sovereign-backed agricultural ventures. This channel compression is most visible in Saudi Arabia's wheat and fodder crop segments where long-term offtake agreements now specify custom micronutrient blends.
Middle East and Africa Specialty Fertilizer Market Segmentation
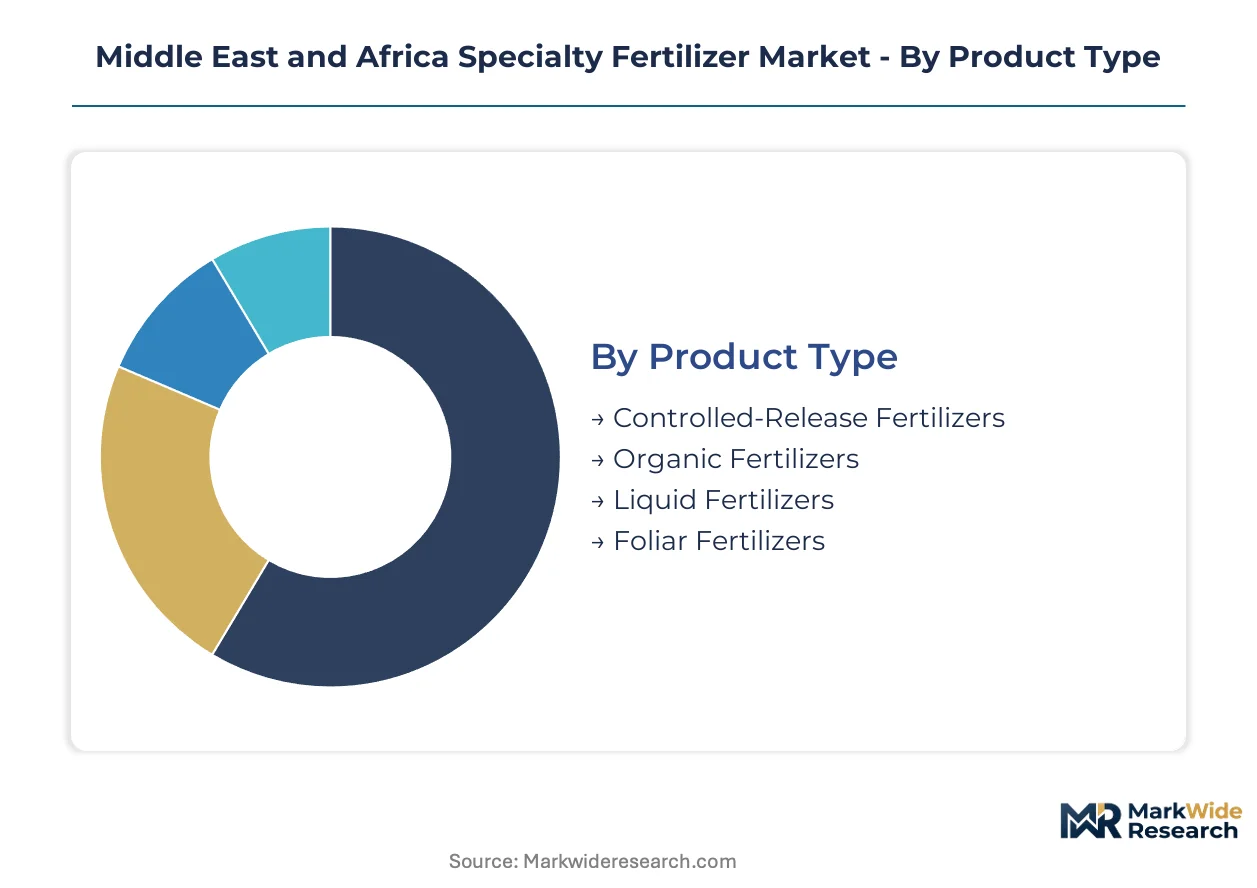
Specialty fertilizer segmentation across the Middle East and Africa reflects divergent agronomic constraints and infrastructure maturity. Formulation choices map directly to water availability, mechanization levels, and crop value intensity across national markets.
Product Type:
Cost tier positioning separates commodity alternatives from precision-engineered nutrient delivery systems commanding formulation premiums.
- Controlled-Release Fertilizers:Polymer-coated or sulfur-coated granules synchronize nutrient release with crop uptake cycles. South African citrus orchards and Egyptian greenhouse operators adopt these formulations to reduce labor rounds and leaching losses in sandy soils.
- Liquid Fertilizers:Fully dissolved nutrient solutions engineered for fertigation compatibility. Israeli, Saudi Arabian, and Egyptian protected cultivation expansion pulls demand upward as growers retrofit drip irrigation infrastructure.
- Organic Fertilizers:Composted or processed biological matter supplying macro and micronutrients. Raw material collection logistics and certification fragmentation constrain cross-border scalability.
- Foliar Fertilizers:Micronutrient suspensions or solutions for direct leaf application. High-value export crop segments in Morocco and Tunisia use these for rapid deficiency correction.
Controlled-release formulations command the established base. The steepest expansion runs through liquid fertilizers.
Application:
End-use intensity correlates with water stress severity and export orientation across regional agricultural systems.
- Greenhouse Cultivation:Protected environments in Egypt's Nile Delta and Saudi Arabian high-tech glasshouse clusters demand precision nutrient delivery. Fertigation integration and controlled atmosphere management favor liquid and foliar specialty systems.
- Crop Production:Open-field cereal, oilseed, and fiber cultivation across Morocco, Ethiopia, and Sudan. Volume scale competes with cost sensitivity, limiting specialty penetration outside high-value segments.
- Turf Management:Golf course and sports field maintenance in UAE, Qatar, and South African urban centers. Aesthetic performance standards sustain premium formulation tolerance.
- Landscape Gardening:Municipal and private ornamental plantings. Fragmented demand across climate zones restricts specialty product standardization.
Greenhouse cultivation anchors value concentration. Crop production delivers volume scale despite formulation commoditization pressure.
Formulation:
Physical state determines application equipment compatibility and storage logistics across diverse climatic conditions.
- Liquid:Homogeneous solutions with immediate dissolution for injection into irrigation lines. Saudi Arabian wheat and fodder segments under sovereign wealth programs specify custom liquid micronutrient blends.
- Granular:Coated or compacted solid particles for broadcast or banded application. Moroccan phosphate downstream conversion supplies regional compounders with enhanced-efficiency granular bases.
- Powder:Finely ground formulations requiring dissolution before application. Egyptian subsidy-eligible domestic blending operations favor powder inputs for cost flexibility.
- Suspended:Concentrated slurries combining solid and liquid phases. Niche positioning in South African precision agriculture for variable-rate application.
Granular formulations retain infrastructure alignment. Liquid states are climbing the fastest as fertigation networks expand.
Distribution Channel:
Channel structure reflects buyer consolidation trends and sovereign capital deployment patterns reshaping procurement pathways.
- Direct Sales:Mill-to-farm contracting bypassing traditional distributor networks. Gulf sovereign wealth agricultural ventures negotiate long-term offtake agreements specifying custom formulations.
- Wholesale:Bulk volume aggregation for domestic blending operations and cooperatives. Egyptian Nile Delta greenhouse clusters source through wholesale channels qualifying local compounders for precision supply contracts.
- Retail:Packaged products through agricultural supply stores. Smallholder access points in Ethiopia, Kenya, and Nigeria with limited specialty product penetration.
- E-commerce:Digital platforms for input ordering and agronomic advisory. Early-stage development constrained by last-mile logistics and payment infrastructure gaps.
Wholesale channels maintain volume dominance. Direct sales are gaining share fastest as centralized procurement consolidates buyer power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sovereign agricultural development programs across the Middle East and Africa are redirecting capital flows toward domestic fertilizer production and precision farming infrastructure. Subsidy frameworks and food security mandates are reshaping procurement patterns and import dependencies. Water scarcity regulations are accelerating technology adoption in arid cultivation zones.
Saudi Arabia
The SFDA's consolidated fertilizer registration pathway is compressing product entry timelines for specialty formulations targeting high-value export crops. Sovereign wealth capital allocation to wheat and fodder self-sufficiency programs is restructuring procurement toward direct mill-to-farm contracting. The Riyadh-based agricultural investment cluster is driving demand for custom liquid micronutrient blends.
United Arab Emirates
MOHAP contaminant thresholds and registration requirements are shaping import access conditions for specialty fertilizer suppliers. Dubai and Abu Dhabi golf course maintenance operations sustain premium formulation tolerance in turf management segments. The emirates' high-tech glasshouse clusters are pulling liquid fertilizer demand through fertigation infrastructure expansion.
Egypt
The Ministry of Agriculture and Land Reclamation's subsidy eligibility criteria are steering formulation preferences toward domestically blended specialty solutions. Nile Delta greenhouse operators are qualifying local compounders for precision fertigation supply contracts. Cairo-based blending operations are expanding tolling capacity for controlled-release and foliar formulations.
Morocco
OCP Group's downstream phosphate processing investments are anchoring regional supply security for enhanced-efficiency derivatives. The country's conversion capacity expansion is shifting regional supply dynamics for nitrogen-phosphate compounds. Casablanca-Jorf Lasfar industrial corridor facilities are supplying compounders across water-stressed North African agricultural zones.
South Africa
Precision agriculture adoption in citrus orchards is accelerating uptake of polymer-coated controlled-release formulations. Cape Town and Durban port infrastructure supports import logistics for specialty nutrient inputs. The Western Cape and Limpopo cultivation belts are reducing labor rounds through synchronized nutrient release technologies.
Middle East and Africa Specialty Fertilizer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market architectures. The market structure tiered between integrated phosphate converters, ammonia-nitrate network operators, and regional blending specialists. Strategic archetypes include upstream resource owners, formulation technology licensors, and tolling service providers. Dominant competitive moves center on backward integration into phosphate rock assets and geographic expansion through sovereign-backed offtake contracting.
Within the integrated phosphate converter tier, OCP Group and ICL Group Ltd occupy positions anchoring regional supply security. Yara International ASA exemplifies the ammonia-nitrate network archetype with integrated liquid fertilizer capabilities. Among regional African specialists, Kynoch Fertilizer and Foskor represent blending and distribution-focused competitive positions serving import-dependent cultivation markets.
| Leading Market Players |
|---|
| Safsulphur |
| Unikeyterra Chemical |
| Yara International ASA |
| Kynoch Fertilizer |
| OCP Group |
| ICL Group Ltd |
| Foskor |
| Azra Group AS |
| K+S Aktiengesellschaft |
| Others |
Supply & Pricing Matrix
Moroccan phosphate rock concentration as a single-source dependency compresses margin pools across nitrogen-phosphate compound formulations while simultaneously dictating three-tier supply chain architectures. SFDA registration timelines and sulfuric acid feedstock volatility determine both premium-to-economy price spreads and whether regional compounders opt for tolling arrangements versus captive blending investments.
Pricing Analysis
Certification level (SFDA versus MOHAP registration tiers) creates the primary spread between premium controlled-release formulations and economy-grade commodity alternatives. Contract-based long-term offtake agreements dominate Gulf sovereign wealth procurement, while Egyptian subsidy-eligible domestic blending operates on per-ton transactional pricing. Price differentiation hinges on micronutrient customization depth and drip irrigation compatibility certification. Cost compression in standard granular formulations is intensifying because OCP Group's downstream conversion capacity expansion floods regional compounders with enhanced-efficiency base materials. Smallholder cooperatives in Ethiopia and Kenya exhibit highest price sensitivity, whereas Israeli and Saudi Arabian protected cultivation operators tolerate premium positioning for fertigation-optimized liquid systems.
Supply Chain Analysis
Extended payment terms through Gulf sovereign wealth agricultural ventures are restructuring working capital requirements for regional compounders. Supply concentrates in Morocco for phosphate derivatives, Saudi Arabia for ammonia-nitrate liquid bases, and Egypt for domestic blending tolling capacity. Raw material dependencies encompass phosphate rock, sulfuric acid, and urea prills. Single-source vulnerability to Moroccan phosphate dominance threatens nitrogen-phosphate compound security across import-dependent Levantine and East African markets. Distribution runs through wholesale channels serving Nile Delta greenhouse clusters, with direct mill-to-farm contracting gaining share fastest in Saudi Arabian wheat and fodder segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The convergence of fertigation hardware and formulation chemistry constitutes a platform-economics inflection where drip irrigation infrastructure interoperability determines specialty fertilizer switching costs and ecosystem lock-in across Middle East and Africa protected cultivation.
For Market Incumbents: Pre-empt channel compression by securing long-term offtake agreements with Gulf sovereign wealth agricultural ventures before distributor networks lose volume entirely. Backward integration into phosphate conversion capacity in Morocco or ammonia production in Saudi Arabia defends margin position against OCP Group's downstream expansion. Certification investment in dual SFDA-MOHAP registration streamlines multi-market access and raises rival entry barriers. For New Entrants and Emerging Players: Mid-scale domestic blending operations in Egypt's Nile Delta represent the most penetrable entry point given Ministry of Agriculture subsidy eligibility criteria redirecting procurement toward locally compounded solutions. Toll manufacturing partnerships with Cairo-based blenders offer asset-light positioning for controlled-release and foliar formulation capabilities. A precision agronomy advisory bundling strategy differentiates against commodity importers in South African citrus orchard segments. For Investors and Strategic Acquirers: SFDA registration pathway consolidation reshapes the acquisition landscape toward regulatory-approval-holding regional specialists rather than raw material traders. Long-term viability centers on backward-integrated compounders with captive phosphate or ammonia supply over pure blending operations exposed to feedstock volatility. Watch for sovereign wealth fund agricultural venture capital deployment velocity as the inflection signal for procurement centralization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Conversion | OCP Group's Jorf Lasfar capacity anchors regional supply security for enhanced-efficiency derivatives. |
| Dual SFDA-MOHAP Registration Investment | Consolidated approval pathways shorten product entry timelines for multi-market suppliers. |
| Precision Agronomy Advisory Bundling | South African citrus orchard operators reduce labor rounds through synchronized nutrient release protocols. |
| Long-term Offtake Contracting with Sovereign Ventures | Gulf food security programs restructure procurement toward direct mill-to-farm arrangements. |
| Toll Manufacturing Partnership in Nile Delta | Egyptian subsidy eligibility redirects formulation preferences toward domestically blended solutions. |
Research Methodology
The analysis maps controlled-release, liquid, organic, and foliar formulation sub-sectors, each validated through interviews with procurement managers at protected cultivation operators, regulatory affairs leads at SFDA and MOHAP, agronomists specializing in saline-alkaline soil management, and distribution channel heads serving wholesale and direct sales networks. Secondary validation draws from customs and trade data, OCP Group and Yara International ASA disclosures, Egyptian Ministry of Agriculture subsidy eligibility documentation, and Gulf sovereign wealth fund agricultural investment announcements. Bottom-up volume builds triangulate against top-down macroeconomic and agricultural output projections.
Assumptions around drip irrigation infrastructure expansion rates, SFDA registration pathway efficiency gains, and OCP Group downstream conversion capacity utilization were held fixed across baseline scenarios while phosphate rock pricing volatility and sulfuric acid supply disruptions were stress-tested. Segmentation dimensions modeled encompass formulation type, application environment, physical state, and distribution channel structure. CAGRs derive from fitted growth curves applied to validated base-year estimates, with industry-specific inputs including greenhouse cultivation area expansion in Egypt and Saudi Arabia, citrus orchard precision adoption rates in South Africa, and sovereign wealth agricultural capital deployment velocity.
Practitioners should monitor SFDA-MOHAP regulatory harmonization progress, OCP Group capacity expansion announcements, and Gulf sovereign wealth fund agricultural venture formation for early signals of procurement centralization acceleration. Macroeconomic deviation in phosphate and sulfur feedstock markets, regulatory restriction tightening on contaminant thresholds, or technological disruption in precision application hardware would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Fertilizer Additives Market
Fertilizers
South Africa Fertilizer Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
Silicon Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Global Foliar Fertilizer Market