
 Nano Fertilizer Market | 2026-2036
Nano Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Fertilizer Market Intelligence
Grain farming is restructuring the end-use mix for nano fertilizers as commercial operations replace conventional inputs with precision-delivery formulations. EuroChem Group anchors its position through captive phosphate reserves and integrated manufacturing across Eastern Europe. IFFCO dominates India's cooperative channel, leveraging its farmer-member base to distribute nano urea at scale. Aqua-Yield Operations LLC specializes in nano-encapsulation technology for foliar application, competing primarily in North American specialty crop segments.
Nano fertilizers are engineered colloidal or particulate formulations with particle dimensions below 100 nanometers, designed to enhance nutrient use efficiency through targeted delivery and controlled release mechanisms. Their primary commercial purpose centers on reducing nitrogen volatilization and phosphorus fixation losses that plague conventional fertilizer application. Liquid fertilizers occupy the largest share of current revenue as farmers retrofit existing spraying infrastructure, while controlled-release fertilizers capture the fastest expansion trajectory due to their alignment with variable-rate application systems. Nano emulsions concentrate margin pools in high-value horticulture, whereas granulated formulations sustain volume leadership in broadacre agriculture.
The EPA regulates nano fertilizer registration under FIFRA pesticide provisions, creating compliance thresholds that filter smaller entrants from the US market. India's FSSAI and BIS jointly oversee nano agri-input standards, with the PLI scheme subsidizing domestic manufacturing scale-up. The EU REACH framework mandates nanomaterial characterization dossiers, shaping product development pipelines for European market access. Stakeholders must monitor how evolving nano-specific toxicity protocols across these jurisdictions will redefine registration timelines and capital requirements.
Market Dynamics
Precision agriculture adoption among large-scale grain operations is restructuring procurement patterns, forcing input suppliers to reformulate around variable-rate delivery systems and nutrient use efficiency metrics rather than bulk volume sales.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for domestic agrochemical manufacturing are accelerating nano fertilizer scale-up and reducing import dependency for controlled-release formulations.
- EU F-Gas Regulation:Emission caps on conventional fertilizer production are accelerating product reformulation requirements across European manufacturing bases.
- Nano-encapsulation technology:Foliar application systems are capturing share from soil-incorporation methods in high-value horticulture segments.
Market Restraints
- Phosphate rock concentration:Captive reserve ownership in Morocco and Russia creates supply security vulnerabilities for phosphorus-based nano formulations.
- REACH dossier costs:Nanomaterial characterization requirements under the EU framework impose capital thresholds that filter smaller developers from European market access.
- Conventional urea substitution:Subsidized granular fertilizers in emerging markets continue to undercut nano premium pricing in price-sensitive smallholder channels.
Strategic Opportunities
- Indo-Gangetic Plain cooperatives:Aggregated smallholder procurement in Bihar and Uttar Pradesh offers volume pathways for liquid nano urea distribution at scale.
- Drone application convergence:Integration of nano-emulsion formulations with unmanned aerial spraying systems is opening precision delivery channels in North American specialty crops.
- Carbon credit monetization:Nitrogen use efficiency improvements from nano formulations are qualifying for agricultural carbon offset protocols in voluntary markets.
Industry Challenges
- Formulation chemist scarcity:Colloidal stabilization expertise for sub-100 nanometer particle engineering remains concentrated among a limited pool of academic and industrial specialists.
- FIFRA registration timelines:EPA pesticide-equivalent review processes for nano fertilizers extend commercialization cycles by 24-36 months compared to conventional product categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Fertilizer Market |
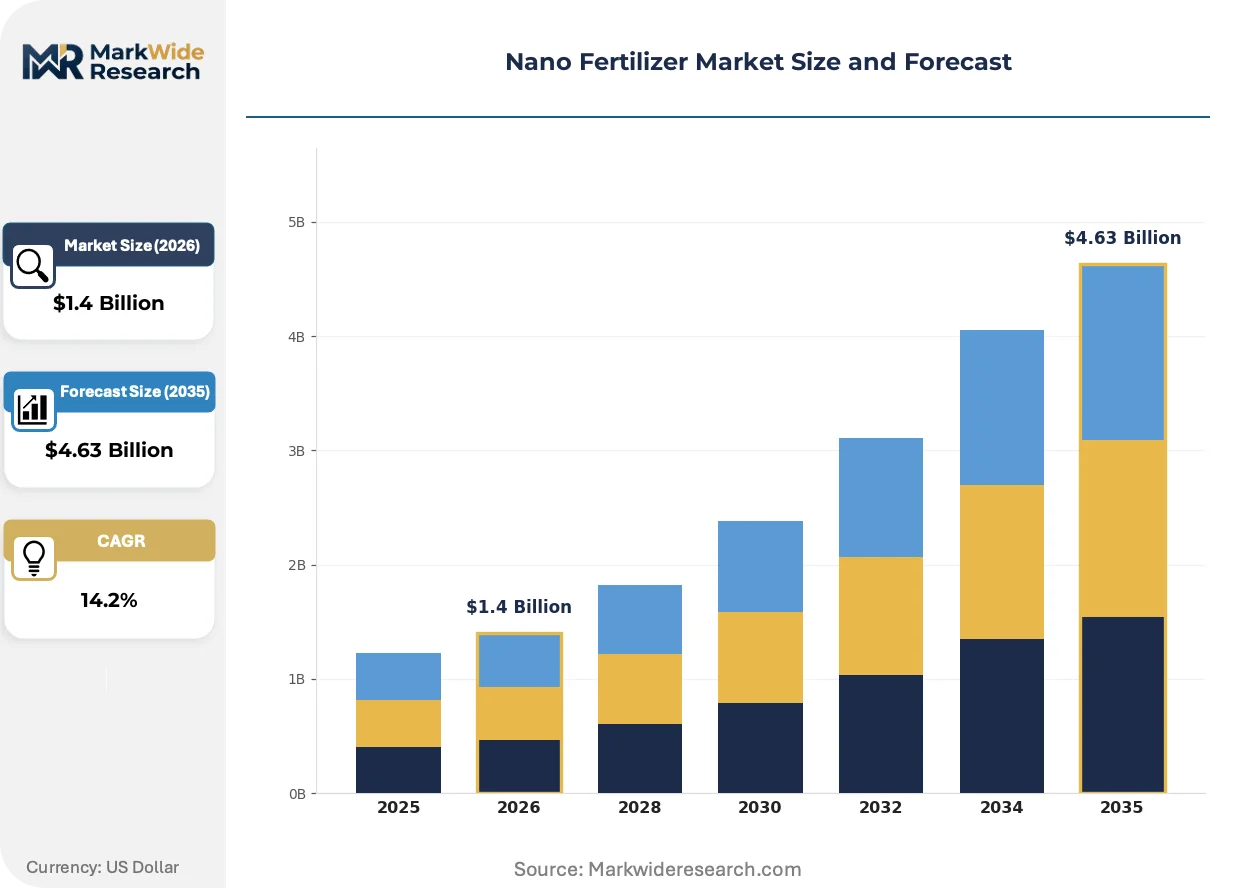
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.63 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fertilizers, Solid Fertilizers, Coated Fertilizers, Controlled-Release Fertilizers Application: Agriculture, Horticulture, Turf Management, Greenhouse Crops Formulation: Nano Emulsions, Nano Suspensions, Granulated Formulations, Powders End User: Farmers, Agricultural Cooperatives, Research Institutes, Distribution Channels |
| Companies Covered | Indian Farmers Fertiliser Cooperative Ltd. (IFFCO), EuroChem Group, Aqua-Yield Operations LLC, Lazuriton Nano Biotechnology Co., Ltd., AG CHEMI Group s.r.o., Fanavar Nano-Pazhoohesh Markazi Company, Tropical Agrosystem India (P) Ltd., Geolife Group, JU Agri Sciences Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Fertilizer Market Strategic Shifts & Innovations
Nano fertilizer development is pivoting from laboratory-scale particle engineering toward manufacturing processes that can deliver consistent colloidal stability at agricultural input price points.
Chitosan-based nano carrier systems are consolidating their position as the dominant encapsulation platform for nitrogen and micronutrient delivery. Large-scale corn and wheat operations in the US Midwest are retrofitting existing sprayer fleets for nano-emulsion application. This consolidation is compressing the addressable market for unformulated bulk nutrients and elevating margin capture toward delivery-technology providers.
The EU F-Gas Regulation is tightening emission thresholds for ammonia and nitrous oxide from fertilizer production and application. Manufacturing facilities across Germany and Poland are retrofitting for closed-loop synthesis processes. Controlled-release nano formulations are capturing preference in Dutch greenhouse operations where emission accounting is tied to carbon border adjustment mechanisms.
Cooperative procurement aggregation is displacing individual smallholder purchasing across India's northern agricultural belt. IFFCO's farmer-member networks are consolidating demand for nano urea into volume contracts that bypass traditional distributor markups. This channel restructuring is most advanced in Punjab and Haryana where irrigation infrastructure supports precision application equipment adoption.
Nano Fertilizer Market Segmentation
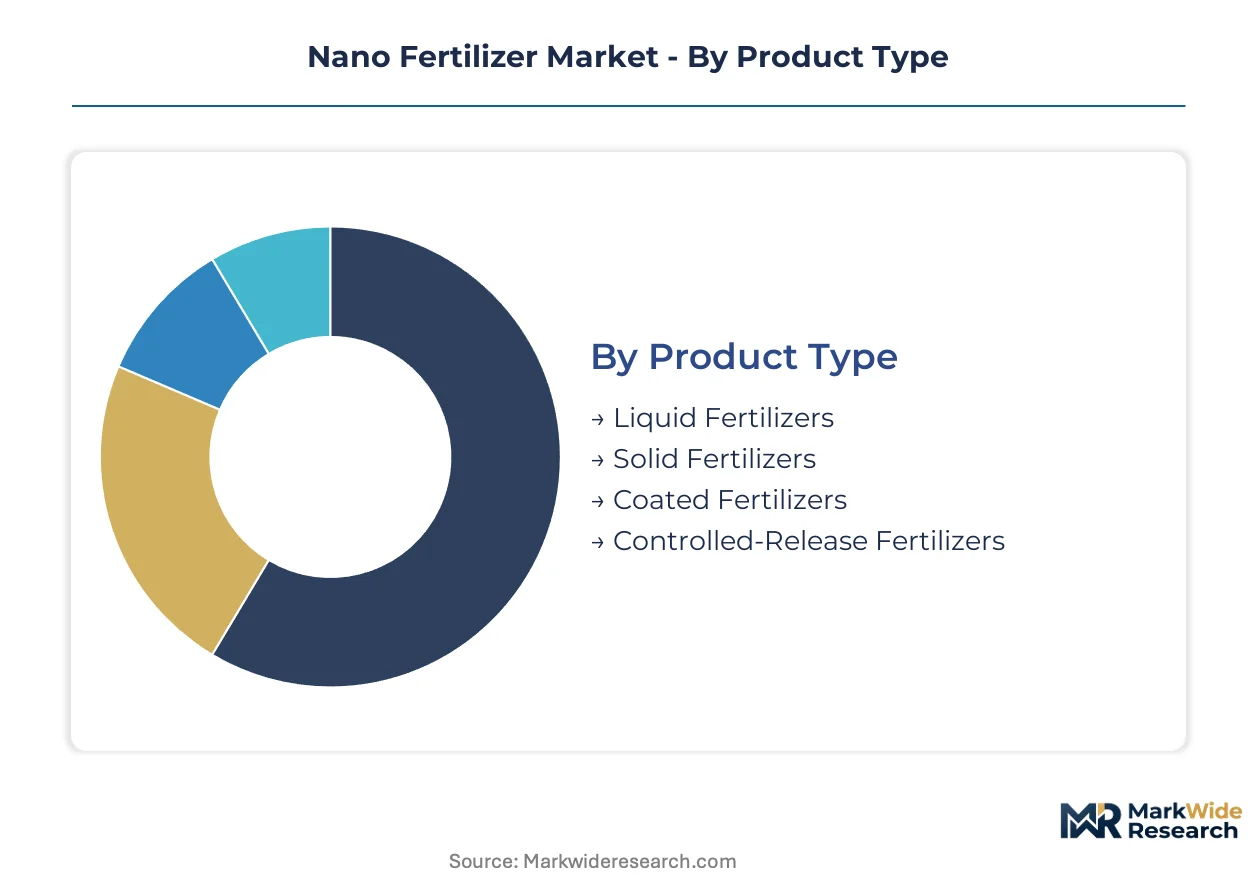
Nano fertilizer segmentation tracks how formulation chemistry, application infrastructure, and buyer procurement power reshape commercial pathways. Each dimension reveals distinct margin pools and capital requirements for technology deployment.
Product Type:
Customization intensity varies sharply across this category, from off-the-shelf liquid concentrates to engineered controlled-release matrices requiring particle-size calibration.
- Liquid Fertilizers:Colloidal suspensions and nano-dispersed solutions compatible with existing sprayer infrastructure dominate current procurement volumes. US Midwest grain operations retrofitting John Deere and Case IH fleets for variable-rate application drive concentrated demand.
- Controlled-Release Fertilizers:Polymer-coated and matrix-embedded nano formulations synchronize nutrient release with crop phenological stages. Dutch greenhouse operations under EU carbon border adjustment mechanisms favor these systems for emission accounting compliance.
- Solid Fertilizers:Granular carriers impregnated with nano-scale nutrient coatings serve price-sensitive broadacre markets in India's northern states.
- Coated Fertilizers:Surface-engineered conventional fertilizer substrates offer intermediate nano functionality without full formulation conversion costs.
Leading the category by volume: Liquid Fertilizers. Expanding most quickly: Controlled-Release Fertilizers.
Application:
Margin capture follows the value-per-hectare gradient from commodity grain to protected cultivation systems.
- Agriculture:Large-scale corn, wheat, and rice operations in the Indo-Gangetic Plain and US Midwest generate foundational volume demand for nano urea and nano DAP formulations. Procurement concentrates among cooperatives and commercial farming enterprises with precision equipment access.
- Horticulture:High-value fruit and vegetable cultivation in California's Central Valley and Maharashtra's Nashik district commands premium pricing for foliar nano formulations targeting micronutrient deficiencies.
- Greenhouse Crops:Controlled-environment agriculture in the Netherlands and Almeria, Spain, integrates nano fertilizers with hydroponic and substrate-based systems.
- Turf Management:Golf course and sports field maintenance in Florida and the UAE deploys nano iron and manganese formulations for aesthetic performance without environmental runoff penalties.
Volume leadership sits with Agriculture. Steepest expansion trajectory belongs to Horticulture.
Formulation:
Technical sophistication determines manufacturing capital thresholds and regulatory pathway complexity across this dimension.
- Nano Emulsions:Oil-in-water or water-in-oil dispersions with particle sizes below 100 nanometers enable foliar penetration through cuticular wax layers. North American specialty crop aerial application via drone systems is accelerating adoption.
- Nano Suspensions:Aqueous dispersions of insoluble nano particles require continuous agitation and stabilization chemistry. These formulations dominate India's liquid nano urea distribution through IFFCO's cooperative network.
- Granulated Formulations:Nano-active coatings on conventional fertilizer granules balance performance enhancement with minimal equipment retrofit requirements.
- Powders:Dry nano formulations for integration into bulk blending operations serve emerging market price points where liquid infrastructure remains underdeveloped.
Nano Suspensions lead by current volume. Nano Emulsions are climbing the fastest.
End User:
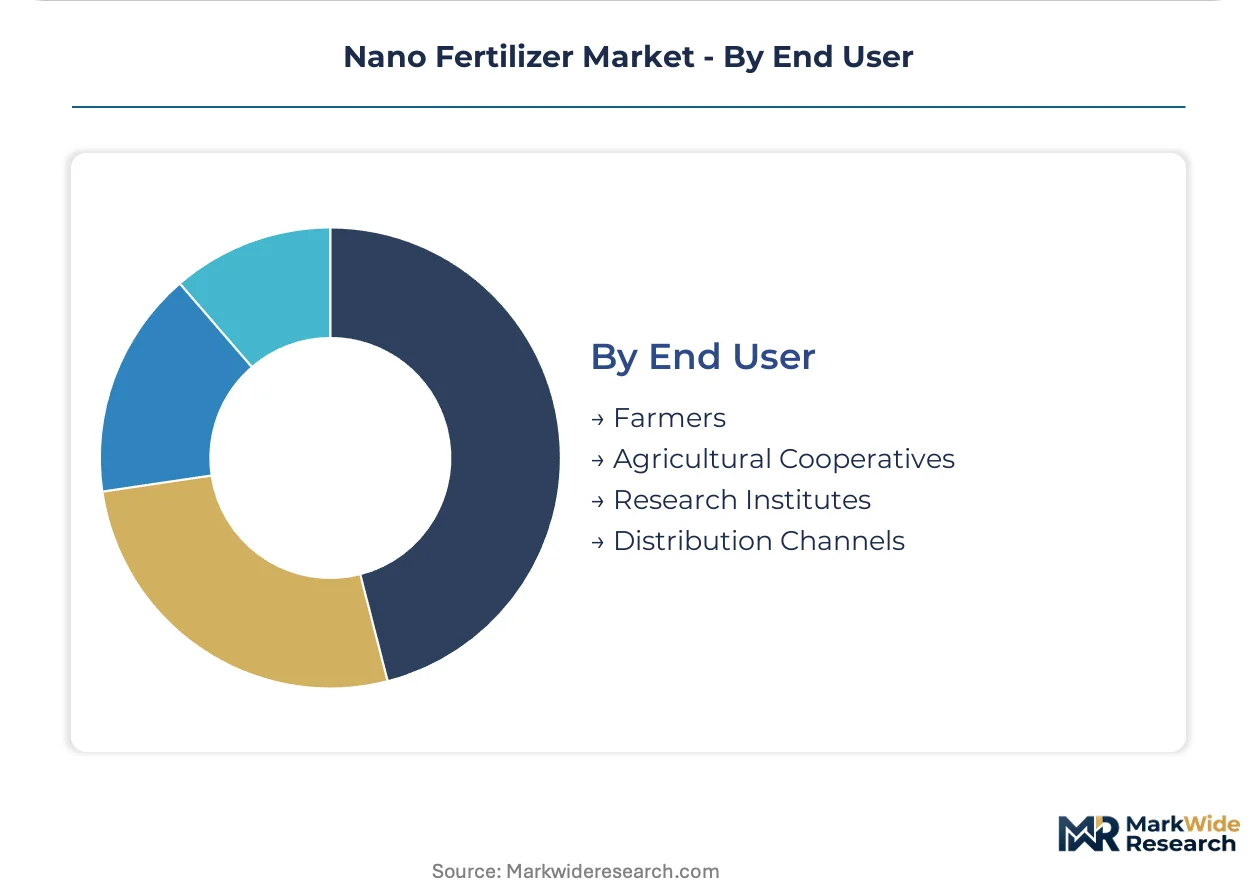
Procurement scale and technical specification authority diverge sharply between fragmented individual growers and consolidated cooperative buyers.
- Agricultural Cooperatives:Aggregated smallholder demand in Bihar, Uttar Pradesh, and Punjab consolidates into volume contracts bypassing traditional distributor markups. India's PLI scheme subsidies flow through these channels for domestic nano urea manufacturing scale-up.
- Farmers:Individual commercial operators in the US and Brazil specify nano formulations based on precision agriculture service provider recommendations and equipment compatibility.
- Research Institutes:ICAR stations in India and USDA-ARS facilities conduct field trials generating efficacy data supporting regulatory registration dossiers.
- Distribution Channels:Agrochemical retailers and input suppliers in Eastern Europe and Southeast Asia curate nano fertilizer portfolios based on manufacturer technical support and margin structures.
Agricultural Cooperatives dominate procurement volume. Research Institutes are gaining share fastest through trial-to-commercialization pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Eastern Europe and South Asia where phosphate reserves and cooperative procurement infrastructure align, while consumption tilts toward grain belts in North America and the Indo-Gangetic Plain where precision agriculture adoption accelerates.
United States
Midwest corn and soybean operations retrofit John Deere and Case IH sprayer fleets for nano-emulsion application, driving concentrated demand for liquid formulations. EPA registration under FIFRA pesticide provisions filters smaller developers from market access. Iowa and Illinois grain cooperatives aggregate procurement volume for variable-rate nutrient delivery systems.
India
Smallholder cooperatives in Punjab, Haryana, and Uttar Pradesh consolidate demand for nano urea into volume contracts bypassing traditional distributor markups. The PLI scheme subsidizes domestic manufacturing scale-up for controlled-release formulations. IFFCO's farmer-member networks in the Indo-Gangetic Plain anchor distribution infrastructure for liquid nano fertilizers.
Germany
Greenhouse operations in Lower Saxony and North Rhine-Westphalia integrate controlled-release nano formulations with hydroponic systems under EU carbon border adjustment mechanisms. The EU F-Gas Regulation tightens emission thresholds for ammonia and nitrous oxide from fertilizer production. Manufacturing facilities across the Rhine-Ruhr corridor retrofit for closed-loop synthesis processes.
Netherlands
Dutch greenhouse clusters in Westland and Aalsmeer prioritize emission accounting compliance through nano fertilizer integration with substrate-based cultivation. REACH nanomaterial characterization dossiers impose capital thresholds shaping product development pipelines. Wageningen University research stations generate field trial data supporting regulatory registration for European market access.
Brazil
Commercial soybean and corn operations in Mato Grosso and Goiás specify nano formulations based on precision agriculture service provider recommendations. The national agricultural regulator oversees agri-input standards alongside environmental licensing for large-scale fertilizer application. São Paulo-based distribution channels curate nano fertilizer portfolios for the Cerrado grain belt.
Nano Fertilizer Market Key Industry Players
Top-tier vendors anchor integrated phosphate reserves and cooperative distribution networks, while mid-tier specialists compete on encapsulation technology and regional formulation expertise. The vendor base stratifies across captive mineral owners, agricultural cooperative channels, and nano-technology licensors. Strategic archetypes include reserve-integrated manufacturers, cooperative-linked distributors, and foliar application specialists. Dominant competitive moves encompass backward integration into phosphate mining and strategic partnerships with precision agriculture equipment providers.
Within the cooperative-channel archetype, Indian Farmers Fertiliser Cooperative Ltd. (IFFCO) occupies a position exemplifying farmer-member network leverage for domestic scale-up. EuroChem Group anchors the reserve-integrated tier through Eastern European manufacturing presence. Aqua-Yield Operations LLC sits within the specialty-application segment, representing North American foliar technology positioning. These three entities collectively illustrate how geographic origin and organizational structure shape competitive positioning without converging on identical capability profiles.
| Leading Market Players |
|---|
| Indian Farmers Fertiliser Cooperative Ltd. (IFFCO) |
| EuroChem Group |
| Aqua-Yield Operations LLC |
| Lazuriton Nano Biotechnology Co., Ltd. |
| AG CHEMI Group s.r.o. |
| Fanavar Nano-Pazhoohesh Markazi Company |
| Tropical Agrosystem India (P) Ltd. |
| Geolife Group |
| JU Agri Sciences Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
Cooperative procurement aggregation across India's Indo-Gangetic Plain is compressing distributor margins and forcing manufacturers to absorb logistics costs into volume contract pricing. This buyer-side consolidation is reshaping how nano fertilizer suppliers structure regional distribution networks and where they position formulation capacity.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as grain cooperatives in Iowa and Illinois prioritize just-in-time delivery for variable-rate application windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in economy-tier liquid formulations is intensifying because of subsidized conventional urea competition in Indian smallholder channels. Agricultural cooperatives exhibit highest price sensitivity due to aggregated bargaining power, while Dutch greenhouse operators show lowest sensitivity given emission compliance premiums.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Mumbai anchor hub-and-spoke patterns for nano emulsion formulations serving European and Asian horticulture markets. Manufacturing concentration rests on Morocco, Russia, and India for phosphate rock and colloidal stabilization chemistry. Raw material dependencies include chitosan carriers, polymer coating substrates, and nano-particle stabilizing agents. Single-source vulnerability in Moroccan phosphate reserves creates supply security exposure for phosphorus-based formulations. Distribution runs through agricultural cooperative networks in India and precision agriculture service providers in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity is constraining manufacturing scale-up and propping pricing power for incumbents with captive technical talent. This supply-constrained dynamic favors early movers with established colloidal engineering capabilities.
For Market Incumbents: Acquire colloidal stabilization expertise through targeted hiring from Wageningen University and ICAR research stations to defend against emerging biostimulant substitutes. Prioritize backward integration into phosphate processing in Eastern Europe to reduce Moroccan supply exposure. Channel control through cooperative equity stakes in Punjab and Haryana locks in volume offtake. For New Entrants and Emerging Players: Drone-compatible nano-emulsion formulations offer a technology-first wedge into North American specialty crop aerial application segments. Target California Central Valley vineyard operators and Maharashtra Nashik grape growers as the most penetrable white-space for foliar micronutrient delivery. Partner with precision agriculture equipment OEMs for bundled application service offerings. For Investors and Strategic Acquirers: The window for entry favors reserve-integrated manufacturers with captive phosphate assets and REACH-compliant dossier libraries. Long-term viability hinges on carbon credit monetization protocols qualifying nitrogen use efficiency improvements. Watch for EU F-Gas Regulation enforcement tightening as the signal for accelerated reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Processing | Captive Moroccan and Russian reserve access reduces supply security vulnerabilities for phosphorus-based nano formulations. |
| Drone Application Technology Partnership | Integration with John Deere and Case IH precision spraying systems opens North American specialty crop channels. |
| REACH Dossier Investment | Nanomaterial characterization compliance enables European market access for controlled-release formulations. |
| Cooperative Equity Stake Acquisition | IFFCO-style farmer-member network control secures aggregated demand in India's Indo-Gangetic Plain. |
| Carbon Credit Protocol Qualification | Nitrogen use efficiency improvements from nano urea qualify for voluntary agricultural offset markets. |
Research Approach
Document review covered EPA FIFRA registration filings, EU REACH nanomaterial dossiers, and India's PLI scheme implementation guidelines, complemented by interviews with nano fertilizer formulation chemists, agricultural cooperative procurement managers, and precision agriculture service providers. Secondary validation drew from BIS agri-input standards, customs trade data for phosphate rock flows, and SEC filings from reserve-integrated manufacturers. Bottom-up demand modeling triangulated against top-down production capacity estimates across Eastern Europe and South Asia.
Segmentation outputs tracked product type, application method, formulation chemistry, and end-user procurement structure across the projection horizon. CAGRs were derived from installed base penetration curves for precision agriculture equipment and cooperative membership growth in target geographies. Industry-specific forecast inputs included drone spraying adoption rates in North American specialty crops and F-Gas Regulation compliance timelines for Dutch greenhouse operations.
Several conditions sit outside the modeled scope, including unannounced regulatory toxicity protocol revisions and breakthroughs in alternative nutrient delivery technologies. Forecasts reflect assumptions about cooperative procurement aggregation sustaining current trajectories and phosphate reserve access remaining stable. Periodic stress-testing of base assumptions is recommended given geopolitical exposure in Moroccan supply corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Argentina Fertilizer Market
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Soil Conditioners Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
Fertilizer Additives Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Fertilizer Applicators Market