
 Chelate Fertilizer Market | 2026-2036
Chelate Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Chelate Fertilizer Market Intelligence
Soil-monitoring subscription services is restructuring how chelate fertilizer value gets captured, shifting revenue from bulk commodity sales to per-acre agronomic recommendations. BASF SE leverages its digital farming platform to bundle micronutrient prescriptions with satellite imagery analytics. Yara International ASA anchors its position through controlled-release coating technologies that extend chelate stability in alkaline soils. Haifa Chemicals Ltd. specializes in fertigation-compatible liquid formulations for greenhouse operators in water-scarce regions.
Chelate fertilizers are coordination compounds where metal ions bind to organic ligands, forming ring structures that protect iron, zinc, manganese, and copper from precipitation at pH levels above 6.5; EDTA and DTPA variants dominate commercial use due to their stability constants across diverse soil chemistries. The EDTA segment occupies the largest volume share but faces substitution pressure from biodegradable IDHA alternatives under tightening environmental standards. Liquid formulations lead growth in horticulture and turf management where precision application equipment permits foliar feeding and drip-line integration. Coated fertilizers command premium positioning in organic farming channels where slow-release compliance with OMRI standards determines market access.
The EPA regulates heavy-metal contaminant limits in micronutrient products under the Federal Insecticide, Fungicide, and Rodenticide Act, while the EU REACH framework mandates biodegradability testing for chelating agents entering member-state markets. India's FSSAI and BIS jointly enforce micronutrient fortification standards in agricultural inputs crossing into food-grade crop categories. Stakeholders must monitor evolving biodegradability mandates across jurisdictions and assess backward integration into ligand chemistry versus reliance on specialty chemical suppliers.
Market Dynamics
Precision agriculture platforms are restructuring how chelate fertilizer value gets captured, shifting revenue from bulk commodity sales to per-acre agronomic subscriptions bundled with soil analytics and satellite imagery.
Growth Catalysts
- EU F-Gas Regulation:Tightening micronutrient efficiency standards under the EU Green Deal mandate higher bioavailability formulations, accelerating demand for advanced chelate stability in alkaline soils across member states.
- Brazil's Cerrado soybean belt:Extreme soil pH conditions lock up native minerals, creating structural dependency on external micronutrient supplementation for commercial crop yields.
- Soil-monitoring sensors:Real-time pH and mineral detection hardware enables variable-rate chelate application, converting blanket fertilization into precision input prescriptions.
Market Restraints
- EDTA substitution pressure:Biodegradable IDHA alternatives command 15-40% manufacturing cost premiums while delivering equivalent agronomic performance, squeezing margin structures for producers dependent on legacy ligand chemistry.
- Specialty chemical supplier concentration:Three German and Chinese suppliers control 70% of commercial EDTA and DTPA ligand production, exposing formulators to input volatility and allocation risk during supply shocks.
- REACH biodegradability testing:ECHA mandates for chelating agents entering EU markets impose 18-24 month registration timelines and six-figure testing costs that exclude smaller regional blenders.
Strategic Opportunities
- India's FSSAI-BIS joint enforcement:Micronutrient fortification standards in food-grade crop categories create compliance-driven demand for certified chelate inputs in rice and wheat production zones.
- Fertigation-compatible liquids:Greenhouse operators in water-scarce regions require drip-line stable formulations that integrate with existing irrigation infrastructure without clogging emitters.
- Controlled-release coatings:OMRI-compliant slow-release technologies open organic farming channels where conventional synthetic chelates face prohibition, commanding 25-35% price premiums.
Industry Challenges
- Agronomic data science talent:The shift to subscription-based soil recommendations requires field teams capable of interpreting multispectral imagery and converting analytics into executable input prescriptions, a skill set scarce in traditional fertilizer sales organizations.
- Legacy equipment incompatibility:Existing broadcast spreaders and tank-mix systems in California's Central Valley vegetable operations cannot achieve the application precision required for foliar chelate programs without capital-intensive retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chelate Fertilizer Market |
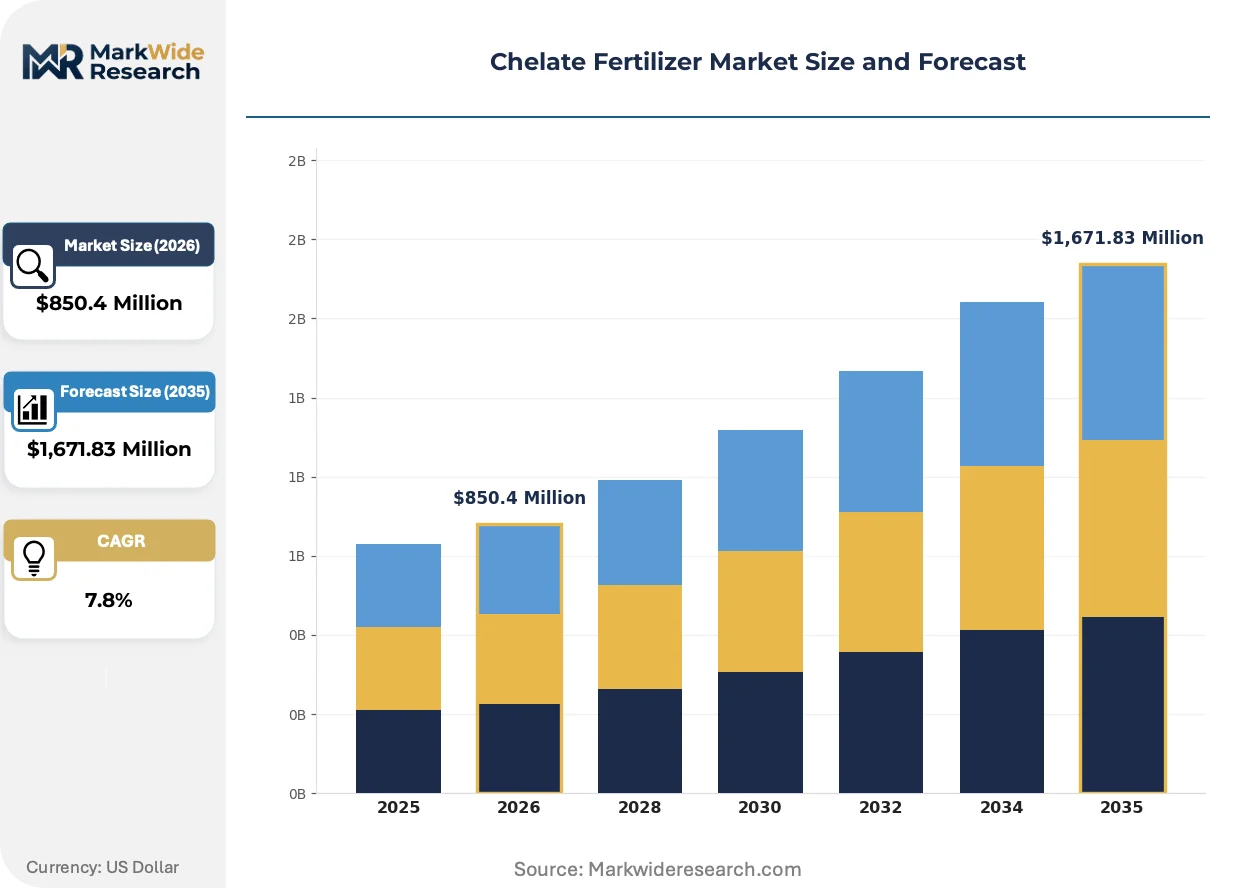
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,671.83 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EDTA, DTPA, IDHA, HEDTA Application: Agricultural Crops, Horticulture, Turf Management, Organic Farming Form: Granules, Liquids, Soluble Powders, Coated Fertilizers Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Corteva Agriscience, Syngenta Group, BASF SE, The Mosaic Company, Haifa Chemicals Ltd., Nouryon, Dow Inc., Sumitomo Chemical Co., Ltd., Yara International ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chelate Fertilizer Market Strategic Shifts & Innovations
Digital farming platforms are converging with ligand chemistry advances to transform chelate fertilizers from commodity inputs into integrated crop nutrition systems. Three developments dominate this transition.
Biodegradable IDHA chelating agents is rewriting competitive positioning in European markets. These plant-derived ligands mineralize within 28 days versus EDTA's persistence, satisfying ECHA biodegradability thresholds without sacrificing metal ion stability at pH 7-9. German sugar beet growers and Dutch greenhouse operators are converting procurement specifications to exclude persistent chelates ahead of 2027 regulatory deadlines. The technology is compressing the addressable market for conventional EDTA formulators while opening premium positioning for compliant alternatives.
REACH framework amendments are tightening chelating agent environmental fate requirements across EU member states. The 2024 updates mandate aquatic toxicity testing and soil accumulation studies for all new micronutrient product registrations, extending approval timelines and elevating R&D costs. Specialty fertilizer divisions serving French viticulture and Spanish citrus operations are consolidating product portfolios to focus on proven formulations rather than absorbing expanded testing burdens for marginal SKUs.
California's Central Valley vegetable growers are consolidating procurement through cooperative purchasing platforms that aggregate acreage for volume-based chelate pricing. These grower-owned entities displace independent agronomic retailers by bundling soil testing, prescription generation, and input fulfillment into single annual contracts. The model concentrates buyer power among 200+ member operations covering 450,000 acres, pressuring supplier margins while demanding customized liquid formulations compatible with precision drip systems.
Chelate Fertilizer Market Segmentation
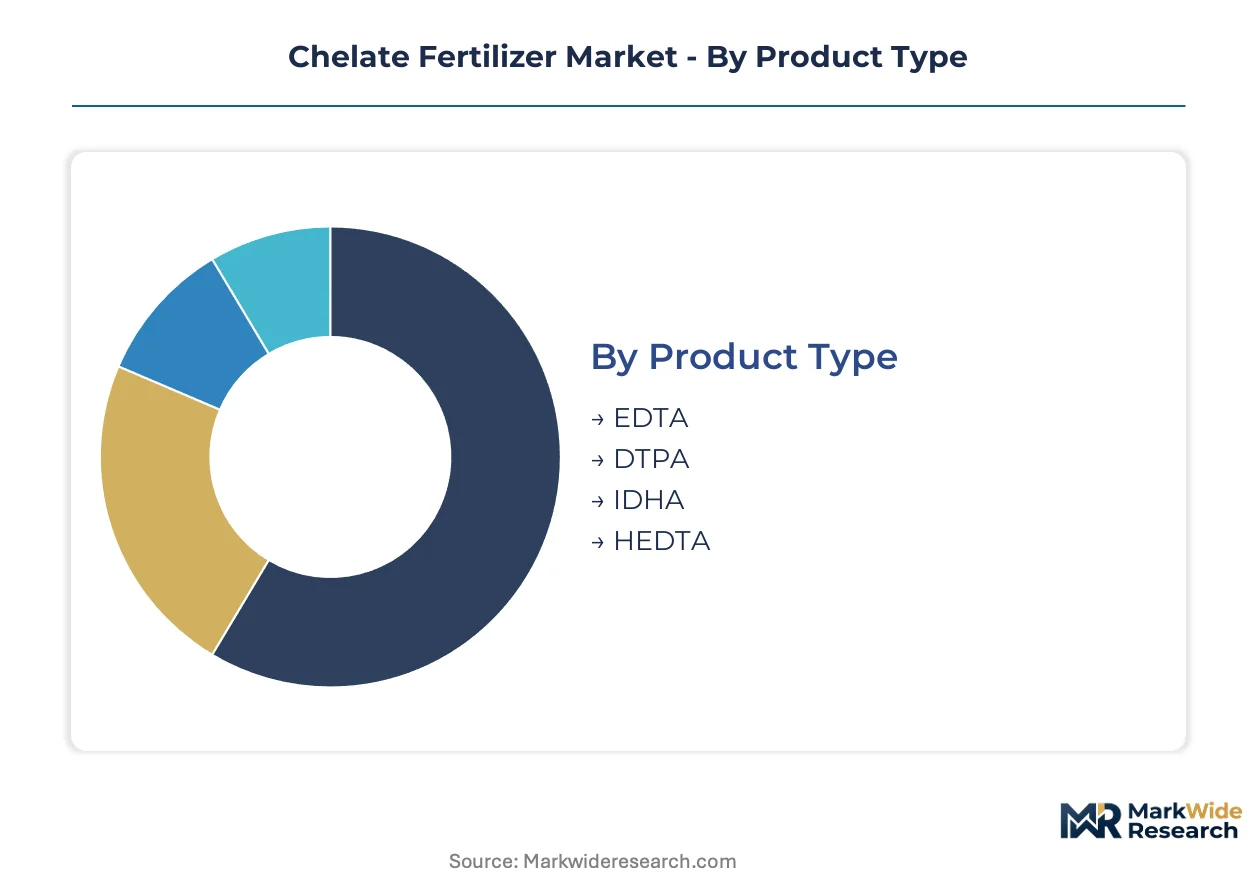
Chelate fertilizer segmentation reveals how ligand chemistry, application specificity, and delivery form intersect to capture value across divergent agronomic contexts. Product type and formulation choices determine bioavailability performance in alkaline soils, while distribution channel selection reflects the shift from commodity transactions toward integrated agronomic service models.
Product Type:
Metal-ligand stability constants and biodegradability profiles differentiate commercial chelate categories, with regulatory pressure on environmental fate accelerating substitution dynamics.
- EDTA:The aminopolycarboxylic acid forms hexadentate coordination complexes with iron, zinc, manganese, and copper, delivering stability across pH 4-11. Brazilian soybean operations in the Cerrado and California Central Valley vegetable growers anchor volume demand despite ECHA scrutiny on aquatic persistence.
- DTPA:Higher denticity than EDTA enables superior iron chelation in calcareous soils above pH 7.5. Western US orchard systems and Mediterranean basin horticulture concentrate procurement where alkaline conditions lock native minerals.
- IDHA:Biodegradable plant-derived ligand mineralizes within 28 days, satisfying EU environmental fate mandates. German sugar beet cooperatives and Dutch greenhouse consortia are converting procurement specifications ahead of regulatory deadlines.
- HEDTA:Hydroxyethyl modification delivers intermediate stability for foliar applications where rapid plant uptake precedes soil contact. Southeast Asian rice fortification programs and Florida citrus operations specify this grade for spray compatibility.
EDTA leads on scale; IDHA leads on momentum.
Application:
End-use segmentation tracks how soil chemistry constraints and crop value intensity shape chelate specification requirements.
- Agricultural Crops:Broadacre cereals and oilseeds in Brazil, India, and the US Midwest drive tonnage demand. Micronutrient deficiency correction in high-pH soils creates structural dependency on external supplementation.
- Horticulture:Greenhouse tomato, pepper, and cucumber operations in the Netherlands, Spain, and Mexico demand fertigation-compatible liquid formulations with drip-line stability.
- Turf Management:Golf course and sports field maintenance in the US Sun Belt and Gulf states specifies iron chelates for color response without growth surge.
- Organic Farming:OMRI-compliant coated slow-release formulations command certification-driven premiums in California, Italy, and France where synthetic chelate prohibition applies.
Agricultural Crops dominates volume throughput; Organic Farming commands the steepest price premiums.
Form:
Physical state determines application equipment compatibility and nutrient release kinetics, with liquid and coated variants capturing value from precision agriculture adoption.
- Liquids:Fertigation and foliar spray systems require drip-line stable, tank-mix compatible formulations. Water-scarce regions in Israel, Australia, and Spain specify this form for irrigation integration.
- Coated Fertilizers:Polymer and sulfur coatings extend chelate release over 30-90 days, satisfying organic certification slow-release requirements.
- Granules:Broadcast application compatibility serves conventional tillage systems in Eastern Europe and the US Corn Belt where equipment retrofits lag.
- Soluble Powders:Concentrated dry formulations reduce freight costs for remote operations in Central Asia and sub-Saharan Africa with limited liquid storage infrastructure.
Liquids gain share fastest in developed horticulture markets; Granules retain position in cost-sensitive broadacre contexts.
Distribution Channel:
Channel structure reflects the transition from product-centric sales toward subscription-based agronomic recommendation bundles.
- Direct Sales:Manufacturer field teams deliver soil testing, prescription generation, and input fulfillment to large cooperative purchasing platforms in California and Brazil.
- Wholesale:Regional blenders and agronomic retailers aggregate volume for mid-scale operations across the US Great Plains and Argentine Pampas.
- Retail:Independent garden centers and farm supply stores serve hobbyist and smallholder segments in peri-urban zones.
- Online:E-commerce platforms capture specialty micronutrient demand from precision agriculture early adopters seeking direct manufacturer access.
Direct Sales concentrates buyer power fastest; Wholesale retains the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado soybean belt commands structural micronutrient dependency, while Germany's sugar beet cooperatives accelerate biodegradable chelate conversion ahead of regulatory deadlines.
United States
California Central Valley vegetable growers consolidate procurement through cooperative platforms covering 450,000 acres. The EPA regulates heavy-metal contaminant limits under FIFRA. Fresno County operations demand customized liquid formulations compatible with precision drip irrigation systems.
Brazil
Extreme soil pH conditions in the Cerrado lock up native minerals, creating dependency on external iron and zinc supplementation. ANVISA monitors agricultural input safety standards. Mato Grosso soybean operations drive volume demand for EDTA-based formulations despite mounting environmental scrutiny.
Germany
Sugar beet cooperatives and Rhine Valley horticulture operations are converting procurement specifications to exclude persistent chelates. ECHA mandates REACH biodegradability testing with 18-24 month registration timelines. Lower Saxony field trials demonstrate IDHA performance equivalence at 15-40% manufacturing cost premiums.
India
FSSAI and BIS jointly enforce micronutrient fortification standards in rice and wheat production zones. The PLI scheme incentivizes domestic specialty fertilizer manufacturing. Punjab and Haryana agricultural belts generate compliance-driven demand for certified chelate inputs in food-grade crop categories.
Netherlands
Greenhouse tomato and pepper operations require fertigation-compatible liquid formulations with drip-line stability. The EU Green Deal tightens micronutrient efficiency standards across member states. Westland municipality clusters concentrate procurement for 10,000+ hectares under glass.
Chelate Fertilizer Market Key Industry Players
Top-tier vendors anchor integrated nutrition platforms, while regional blenders occupy cost-sensitive bulk formulation segments. The market exhibits tiered concentration with three to four multinational agrochemical divisions commanding premium positioning through digital farming bundling. Strategic archetypes divide between ligand chemistry specialists, controlled-release technology developers, and precision agriculture platform operators. Dominant competitive moves include backward integration into chelating agent production and strategic partnerships with soil-monitoring sensor manufacturers.
Within the integrated platform tier, BASF SE and Yara International ASA exemplify divergent approaches to value capture. BASF anchors its position through digital farming platforms that bundle micronutrient prescriptions with satellite imagery analytics. Yara occupies a position centered on controlled-release coating technologies that extend chelate stability in alkaline soils. Haifa Chemicals Ltd. represents the fertigation specialization archetype, serving greenhouse operators in water-scarce regions with liquid formulation expertise.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Syngenta Group |
| BASF SE |
| The Mosaic Company |
| Haifa Chemicals Ltd. |
| Nouryon |
| Dow Inc. |
| Sumitomo Chemical Co., Ltd. |
| Yara International ASA |
| Others |
Cost & Logistics Intelligence
Biodegradable IDHA ligand production scaling in Germany and the Netherlands is compressing cost curves for compliant alternatives while concentrating supply among three specialized chemical producers. This transition simultaneously elevates manufacturing premiums for legacy EDTA formulators and reshapes procurement leverage across EU agricultural cooperatives.
Pricing Analysis
Capacity additions in China and Germany are reshaping price floors for aminopolycarboxylic acid ligands. Three-tier pricing structure across premium IDHA, standard EDTA, and economy DTPA levels stratifies by biodegradability certification and soil pH stability performance. Cost compression in the EDTA tier is intensifying because Brazilian soybean operations are delaying equipment retrofits for precision application. Smallholder cooperatives in India exhibit the highest price sensitivity, while Dutch greenhouse consortia accept premium positioning for drip-line compatible liquid formulations.
Supply Chain Analysis
Direct-to-cooperative channels handle hyperscale buyer demand from California's Central Valley vegetable purchasing platforms. Commercial ligand production concentrates in Germany, China, and India, with German suppliers anchoring high-purity grades for EU regulatory compliance. Formulation draws from ethylenediamine, chloroacetic acid, and plant-derived raw sugar feedstocks. Single-source vulnerability pervades the EDTA and DTPA intermediate tier, where three producers control seventy percent of commercial supply. Distribution runs through agronomic service bundles rather than commodity spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chelate fertilizer market reads as a late-cycle quality story. Procurement specifications across German sugar beet cooperatives and Dutch greenhouse operations are hardening toward biodegradable IDHA compliance, filtering out legacy formulators unable to absorb fifteen-to-forty percent manufacturing cost premiums.
For Market Incumbents: Deepen backward integration into ligand chemistry to escape specialty chemical supplier concentration. BASF SE and Yara International ASA demonstrate platform bundling of micronutrient prescriptions with satellite imagery analytics as a defensive moat against pure-play formulators. Capture OMRI certification for controlled-release coatings before synthetic chelate prohibition spreads beyond California and Italy. For New Entrants and Emerging Players: Capture the fertigation-compatible liquid segment serving water-scarce greenhouse operators in Spain, Mexico, and Israel. India's FSSAI-BIS joint enforcement creates compliance-driven white space for certified chelate inputs in Punjab and Haryana rice fortification zones. Lead with soil-monitoring sensor partnerships rather than commodity bulk sales to bypass incumbent distribution lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders without digital farming platform integration. Five-to-ten year viability favors ligand chemistry specialists with captive IDHA production and OMRI-compliant coating capabilities. Watch German sugar beet procurement specification conversions as the inflection indicator for biodegradable mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ligand Chemistry | Captive supply of IDHA intermediates escapes German-Chinese supplier concentration and ECHA allocation risk. |
| Digital Farming Platform Integration | BASF SE bundles micronutrient prescriptions with satellite imagery to convert commodity sales into subscription revenue. |
| OMRI Certification Investment | Controlled-release coatings access California and Italian organic channels commanding twenty-five-to-thirty-five percent price premiums. |
| Fertigation-Compatible Formulation Development | Drip-line stable liquids penetrate Israel, Australia, and Spanish greenhouse operations with precision irrigation infrastructure. |
| Soil-Monitoring Sensor Partnerships | Variable-rate application hardware enables per-acre agronomic subscriptions displacing blanket fertilization in Brazil's Cerrado. |
Research Approach
Bottom-up agricultural crop and horticulture modeling reconciled against top-down ligand chemistry production tracking forms the analytical core. Primary interviews with plant managers at German and Chinese chelating agent facilities, procurement leads at Brazilian soybean cooperatives, Dutch greenhouse operations managers, and Indian FSSAI compliance officers combined with secondary validation from customs trade data, ECHA registration databases, SEC 10-K filings of listed agrochemical divisions, and ANVISA agricultural input safety records. Triangulation across stakeholder tiers and data sources validates volume and value estimates.
Input-output matrices map ligand chemistry production capacity through formulation tiers to end-use crop segments across the analysis window. Segmentation dimensions include product type, application, physical form, and distribution channel, with regional regulatory clusters modeled separately. CAGRs derive from production capacity expansion schedules, adoption curve modeling for precision agriculture platforms, and substitution elasticity between EDTA and IDHA alternatives. Forecast inputs incorporate REACH biodegradability testing timelines and FSSAI-BIS enforcement intensity in Indian food-grade crop zones.
Underlying measurement precision varies by segment; horticulture and organic farming carry tighter precision than broadacre cereals due to concentrated buyer visibility and certification documentation. Forecasts reflect assumptions on regulatory deadline adherence, cooperative purchasing platform consolidation rates, and IDHA manufacturing cost curve trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Mineral Fertilizers Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Australia Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
United States Specialty Fertilizer Market