
 Fertilizer Mixtures Market | 2026-2036
Fertilizer Mixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Fertilizer Mixtures Market Foresight
Brazil is rewriting the competitive map for fertilizer mixtures through massive capacity investments in blending and logistics infrastructure near its agricultural heartland. Nutrien leverages its integrated potash supply chain to dominate bulk distribution across South American soybean belts. Yara International sustains technology leadership through controlled-release coating innovations that reduce nitrogen leaching in tropical soils. CF Industries anchors North American ammonia supply, giving it upstream cost advantages in NPK formulation.
Fertilizer mixtures are multi-nutrient compounds produced by physically blending or chemically reacting primary macronutrients—nitrogen, phosphorus, and potassium—with secondary and micronutrient additives to achieve crop-specific N-P-K ratios and trace element profiles. Granular formulations occupy the largest volume share due to compatibility with existing mechanical spreaders and storage systems across broadacre farming, though controlled-release variants command premium positioning where environmental regulations restrict runoff. Liquid mixtures represent the fastest-growing product category, driven by precision agriculture adoption that enables fertigation and foliar feeding with exact dosing calibrated to growth stages. On the application side, agricultural end-use generates dominant demand, while horticultural segments concentrate margin pools through smaller-batch custom blends for greenhouse and protected-cropping operations.
The EPA enforces Clean Water Act provisions that limit nutrient discharge from fertilizer manufacturing and application, compelling producers to reformulate for reduced volatility and leaching potential. REACH and the EU Green Deal's nutrient management targets are reshaping product registration requirements across Europe, favoring mixtures with enhanced-efficiency coatings and organic-mineral hybrids. India's FSSAI and state-level agricultural departments monitor micronutrient fortification standards under revised subsidy schemes. Stakeholders must track how evolving carbon border mechanisms and soil carbon accounting protocols will alter the cost structure and geographic sourcing of fertilizer mixture ingredients.
Market Dynamics
Precision agriculture adoption is compressing formulation batch sizes and accelerating regional blending facility buildouts, forcing manufacturers to trade scale economies for proximity-to-farm responsiveness.
Growth Catalysts
- India's soil health card program:State agricultural departments issue site-specific nutrient prescriptions that mandate customized NPK-micronutrient blends, creating guaranteed offtake for registered mixture producers.
- Fertigation infrastructure expansion:Drip irrigation penetration in Brazil's Cerrado enables liquid fertilizer injection at variable rates, pulling demand for soluble compound formulations calibrated to growth stages.
- EU Green Deal nutrient management targets:Member states must reduce synthetic fertilizer use intensity, redirecting volume toward enhanced-efficiency coated mixtures that qualify for CAP greening payments.
Market Restraints
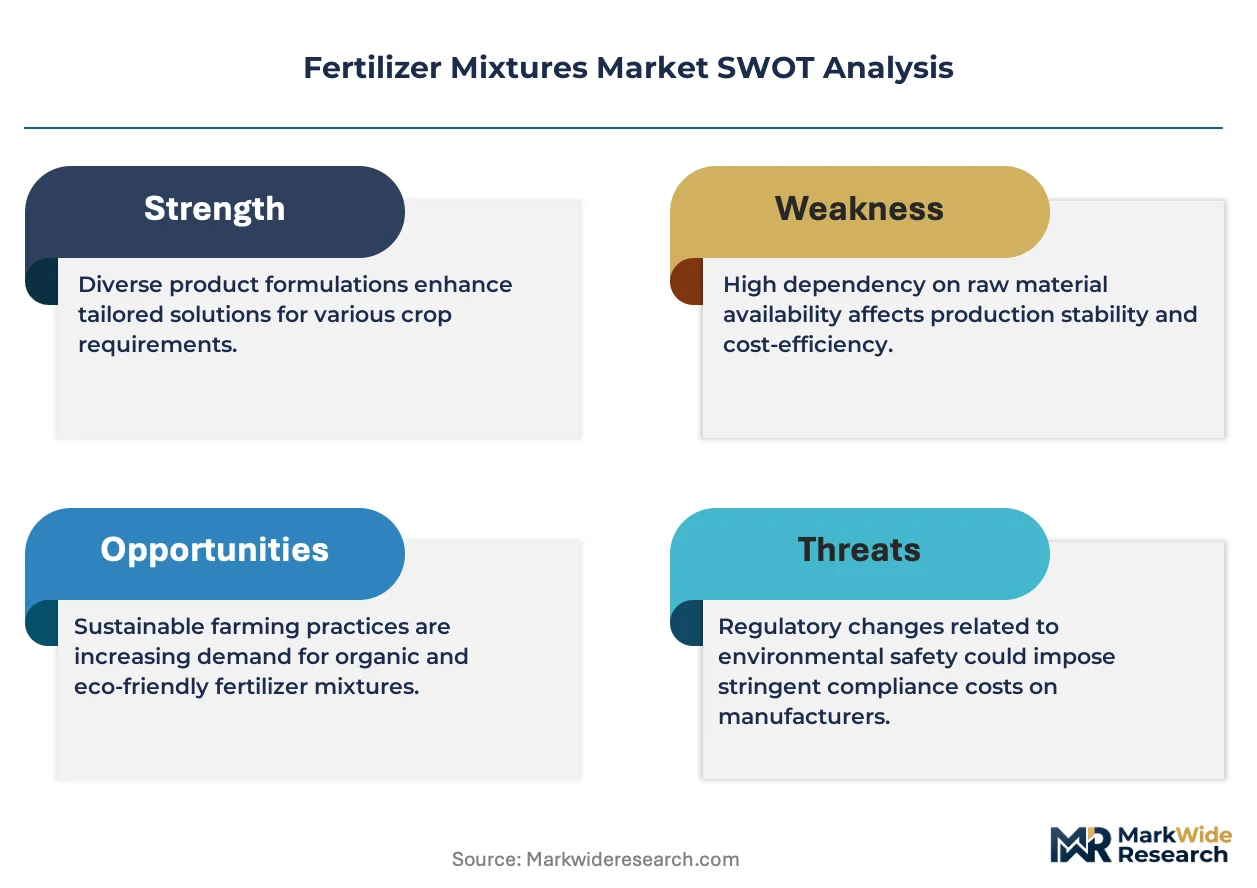
- Potash supply concentration:Canadian and Belarusian state-controlled producers dominate muriate of potash feedstock, exposing blenders to geopolitical disruption and export quota volatility.
- REACH registration costs:Novel additive chemistries require multi-year toxicology dossiers, freezing formulation innovation cycles for small and mid-scale European compounders.
- Organic-mineral substitution:Certified organic acreage expansion in Western Europe displaces conventional NPK mixtures where farmers access manure digestate and compost-based alternatives.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Fertilizer application rates in Nigeria and Ethiopia sit below 20 kilograms per hectare, creating volume expansion potential for mobile blending units serving fragmented smallholder networks.
- Carbon border adjustment mechanisms:The EU's CBAM will levy embedded emissions on imported ammonia and urea, rewarding European blenders with low-carbon hydrogen feedstock sourcing.
- Drone-enabled foliar application:Unmanned aerial systems enable micronutrient spot-spraying based on multispectral crop stress mapping, opening premium formulation tiers for high-value horticultural crops.
Industry Challenges
- Soil science agronomist scarcity:Custom blending requires site-specific prescription expertise that outpaces university training pipeline output in Brazil and India.
- Legacy ERP integration:Batch formulation software must interface with farm management information systems, creating middleware development burdens for regional blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertilizer Mixtures Market |
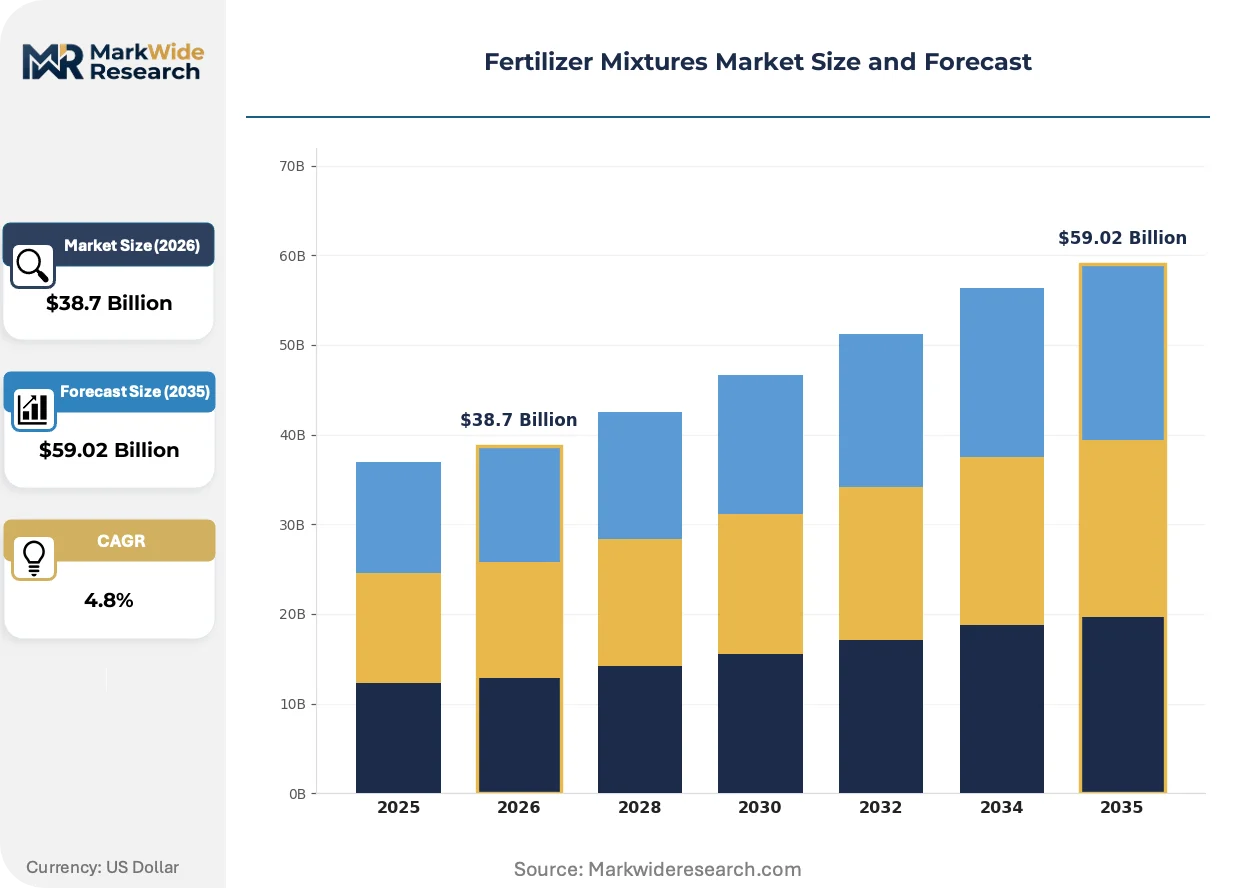
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powdered, Controlled-Release Application: Agricultural, Horticultural, Turf, Landscaping End User: Farmers, Garden Centers, Agricultural Co-ops, Nurseries Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Nutrien, Yara International, CF Industries, The Mosaic Company, K+S AG, OCP Group, ICL Group, EuroChem Group, Haifa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertilizer Mixtures Market Shifts & Advancements
Formulation science is converging with digital agriculture platforms, creating feedback loops between soil sensor data, prescription algorithms, and just-in-time blending operations.
Controlled-release polymer coatings are migrating from high-value horticultural crops to broadacre soybean and maize systems in Brazil and the US Midwest. Large-scale cooperatives and input retailers are retrofitting bulk blending towers with coating drums to capture premium positioning on environmental compliance. The technology is migrating from niche greenhouse applications to commodity grain markets, compressing the price premium for enhanced-efficiency products.
REACH authorization requirements are tightening scrutiny on cadmium and heavy metal contaminants in phosphate rock-derived fertilizers. ECHA's 2024 updated guidance forces blenders to certify raw material provenance and implement batch testing protocols. Western European compounders are responding by sourcing low-cadmium sedimentary phosphate deposits from Morocco and Jordan, reshaping Atlantic supply corridors.
Cooperative procurement consortia are consolidating input purchasing for smallholder networks in India and Kenya. These farmer producer organizations negotiate direct offtake agreements with regional blenders, bypassing traditional distributor markups. The model is most visible in Maharashtra and Karnataka states, where sugarcane and cotton cooperatives command sufficient volume to dictate custom micronutrient specifications.
Fertilizer Mixtures Market Segmentation
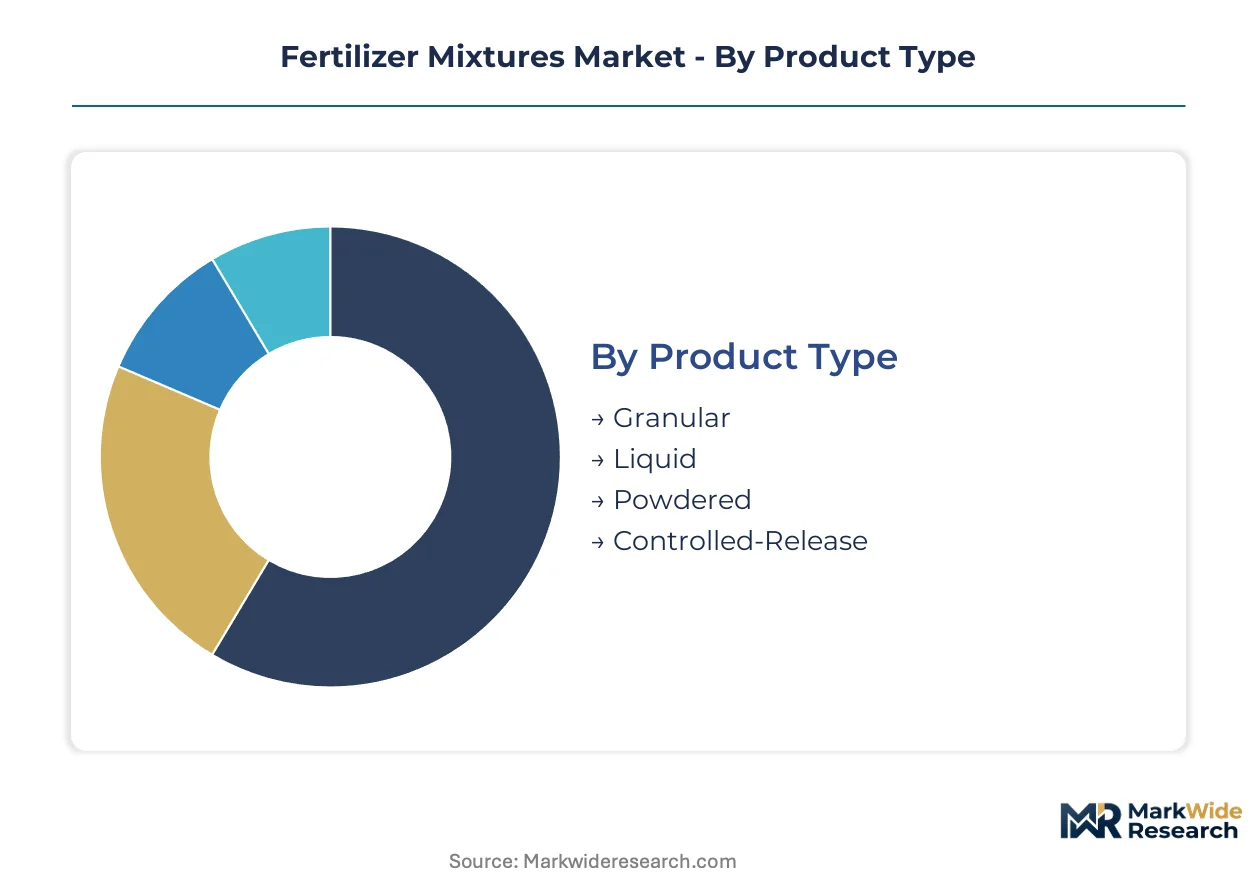
Fertilizer mixture buyers fragment across production scale, crop value, and input sophistication levels. Understanding these divides reveals where formulation complexity commands premium pricing versus where bulk commodity blends dominate procurement decisions.
Product Type:
Granular formulations anchor broadacre farming through mechanical spreading compatibility, while liquid and controlled-release variants target precision agriculture and environmental compliance use cases.
- Granular:Physical blending of NPK macronutrients into hard granules compatible with pneumatic spreaders and bulk storage silos. Brazilian soybean cooperatives in Mato Grosso and Goiás states concentrate procurement here, driven by existing equipment fleets and lowest per-ton handling costs.
- Liquid:Soluble compound concentrates designed for fertigation injection and foliar feeding with exact dosing calibration. Demand clusters in Brazil's Cerrado drip-irrigation zones and Indian sugarcane belts, pulled by precision agriculture adoption that enables growth-stage-specific nutrient delivery.
- Powdered:Fine-ground blends for greenhouse substrate incorporation and protected-cropping operations.
- Controlled-Release:Polymer-coated granules that meter nutrient release against soil temperature and moisture, commanding premium positioning where EPA Clean Water Act or EU Green Deal nutrient runoff restrictions apply.
The dominant share belongs to Granular, while Liquid is closing the gap fastest.
Application:
Volume concentrates in commodity grain production, though margin pools shift toward high-value protected cropping where custom micronutrient specifications justify smaller batch premiums.
- Agricultural:Broadacre cereal, oilseed, and fiber crop fertilization across mechanized farming systems. Indian wheat-rice rotations and Brazilian safrinha corn double-cropping anchor procurement volumes, reinforced by government subsidy schemes and yield-maximization imperatives.
- Horticultural:Greenhouse vegetable, fruit, and ornamental production requiring precise NPK-micronutrient ratios and pH-adjusted formulations. Western European protected-cropping clusters and Indian floriculture belts around Bengaluru drive specification intensity, constrained by REACH registration burdens for novel additive chemistries.
- Turf:Golf course, sports field, and amenity grass maintenance with seasonal fertility programs.
- Landscaping:Municipal and commercial ornamental plantings with aesthetic performance requirements.
Agricultural commands the volume base, yet Horticultural captures disproportionate margin through formulation complexity.
End User:
Procurement scale and agronomic sophistication determine whether buyers access custom-blending services or default to standard NPK grades.
- Farmers:Individual operators and family holdings purchasing through dealer networks or direct from regional blenders. Indian smallholders accessing soil health card prescriptions and Brazilian no-till soybean producers anchor this segment, fragmented across millions of decision-makers with varying technical capacity.
- Agricultural Co-ops:Consolidated purchasing bodies negotiating volume offtake and custom specifications. Maharashtra sugarcane cooperatives and Iowa grain marketing cooperatives exemplify the model, leveraging collective bargaining power to dictate micronutrient fortification standards.
- Garden Centers:Retail outlets serving hobbyist and residential lawn-care segments.
- Nurseries:Specialized propagation operations requiring starter fertilizer formulations and controlled-release options.
Farmers retain the largest headcount, though Agricultural Co-ops are consolidating procurement influence fastest.
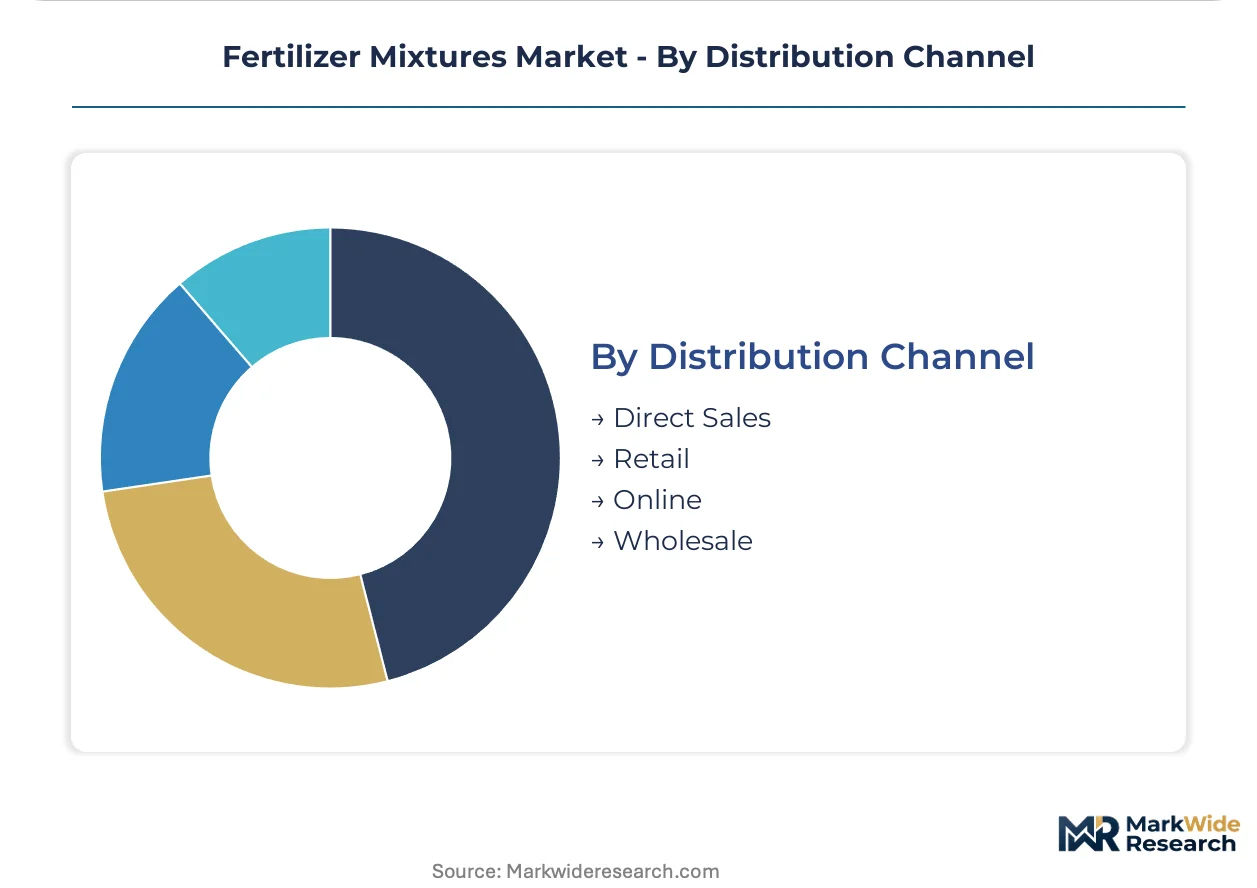
Distribution Channel:
Physical proximity to blending infrastructure and logistics cost structures shape channel selection across geographies.
- Direct Sales:Blending facilities contracting directly with large-scale farming operations and cooperative consortia. Nutrien's South American bulk distribution network and Yara International's farm-gate delivery systems illustrate the model, eliminating distributor markups for volume accounts.
- Wholesale:Regional distributors warehousing standard grades for dealer and retailer resale. Indian state fertilizer corporations and Brazilian input retail chains rely on this channel, constrained by working capital requirements and inventory risk.
- Retail:Bricks-and-mortar agronomy centers offering agronomic advice alongside product sales.
- Online:E-commerce platforms for specialty micronutrient packages and small-batch orders.
Direct Sales holds the volume advantage, while Online is gaining traction fastest among specialty crop producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminal expansion underwrites Brazil's fertilizer import dominance, handling over 30 million tonnes annually through dedicated bulk handling facilities purpose-built for urea and potash discharge.
United States
Corn Belt no-till adoption and precision variable-rate application compress formulation batch sizes. EPA Clean Water Act nutrient discharge limits tighten runoff standards across Chesapeake Bay and Mississippi River watersheds. Iowa and Illinois grain cooperatives anchor regional blending tower networks that retrofit coating drums for enhanced-efficiency products.
Brazil
Safrinha corn double-cropping and Cerrado soybean expansion drive compound fertilizer consumption volumes. ANVISA monitors micronutrient fortification standards under federal agricultural subsidy frameworks. Mato Grosso and Goiás states concentrate blending infrastructure investments near Sorriso and Rio Verde agricultural hubs.
India
Soil health card prescriptions mandate customized NPK-micronutrient ratios across wheat-rice rotations. FSSAI and state agricultural departments enforce micronutrient standards under revised subsidy schemes. Maharashtra and Karnataka sugarcane cooperatives dictate custom specifications through direct offtake agreements with regional blenders.
Germany
Organic-mineral hybrid demand accelerates where certified organic acreage expansion displaces conventional NPK. REACH and EU Green Deal nutrient management targets reshape product registration requirements. Lower Saxony and Bavaria greenhouse clusters drive specification intensity for protected-cropping formulations.
China
Domestic potash dependency reduction and controlled-release coating technology migration reshape procurement patterns. GB standards and MEE environmental compliance tighten manufacturing discharge protocols. Shandong Peninsula and Yangtze River Delta blending facilities concentrate capacity for domestic compound fertilizer supply.
Fertilizer Mixtures Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and additive supply. The vendor base concentrates around integrated nutrient producers with captive raw material positions and regional blenders serving proximity-to-farm responsiveness. Three archetypes dominate: integrated miners with backward potash control, technology-led coating innovators, and cooperative-anchored regional compounders. Competitive moves center on M&A for logistics infrastructure and strategic partnerships for precision agriculture platform integration.
Among North American integrated producers, Nutrien and CF Industries occupy positions anchored in captive potash and ammonia supply chains respectively. Yara International exemplifies the technology-led archetype through controlled-release formulation expertise. These three entities represent distinct competitive vectors: upstream resource security, environmental compliance technology, and farm-gate distribution density.
| Leading Market Players |
|---|
| Nutrien |
| Yara International |
| CF Industries |
| The Mosaic Company |
| K+S AG |
| OCP Group |
| ICL Group |
| EuroChem Group |
| Haifa Group |
| Others |
Supply & Pricing Matrix
The Santos-Rotterdam bulk freight corridor shapes cost dynamics for Brazilian blenders importing Canadian potash and European ammonia derivatives, compressing margins on standard NPK grades while enabling premium positioning for coated formulations that absorb higher logistics outlays.
Pricing Analysis
Volume-discount tiering structures separate agricultural cooperatives purchasing multi-thousand-tonne annual contracts from smallholder farmers accessing subsidized retail sachets. Price differentiation hinges on micronutrient fortification intensity and enhanced-efficiency coating certification, with uncoated bulk blends facing the steepest cost compression due to commodity urea price volatility. Margins are tightening for standard-grade producers as Indian subsidy reforms cap reimbursement rates. Agricultural cooperatives exhibit lowest price sensitivity through collective bargaining power, while fragmented smallholders in Sub-Saharan Africa show highest elasticity.
Supply Chain Analysis
Export-control regimes limiting Belarusian potash flows through EU ports have redirected Atlantic supply corridors toward Russian and Canadian feedstock alternatives. Geographic supply concentration centers on Canada, Russia, and Belarus for muriate of potash; China and Morocco for phosphate rock; and Trinidad, Qatar, and Russia for ammonia feedstock. Raw material dependencies rest on sulfuric acid for phosphate processing, natural gas for ammonia synthesis, and polymer resins for controlled-release coatings. Single-source vulnerability runs through the Strait of Hormus ammonia transit route. Distribution runs through direct sales to cooperative consortia and wholesale networks serving state fertilizer corporations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision agriculture platforms and EU carbon border mechanisms are disrupting established formulation economics, creating asymmetric opportunity for technology-anchored blenders over commodity compounders.
For Market Incumbents: Harden coating technology moats through backward integration into polymer resin production, insulating margin structures from petrochemical feedstock volatility. Secure captive potash offtake agreements with Saskatchewan producers before Canadian export quota tightening accelerates. Defend against regional blender encroachment by retrofitting existing bulk towers with rapid-switch formulation capabilities.
For New Entrants and Emerging Players: Build out mobile blending units serving Nigerian and Ethiopian smallholder networks where application rates sit below twenty kilograms per hectare and infrastructure gaps exclude incumbents. Target drone-enabled foliar application services for Indian horticultural belts around Bengaluru, where multispectral crop mapping creates demand for micronutrient spot-spraying. Anchor go-to-market strategy through farmer producer organization procurement consortia bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Regional compounders with soil science agronomist teams and farm-gate distribution density in Mato Grosso or Maharashtra represent the most defensible acquisition profile. Long-term viability favors blenders with integrated precision agriculture platform partnerships and low-carbon hydrogen feedstock sourcing for EU CBAM compliance. Watch for inflection when carbon border adjustment mechanisms trigger wholesale supply chain reconfiguration toward European production.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Captures coating cost margin and insulates against petrochemical volatility for controlled-release formulations. |
| Mobile Blending Unit Deployment | Penetrates fragmented smallholder networks in Sub-Saharan Africa where fixed infrastructure remains uneconomic. |
| Precision Agriculture Platform Partnership | Integrates soil sensor data with prescription algorithms for just-in-time formulation switching at farm gate. |
| Low-Carbon Hydrogen Feedstock Sourcing | Qualifies European production for EU CBAM preferential treatment against imported ammonia. |
| Cooperative Procurement Consortium Anchoring | Locks volume offtake through direct agreements with Maharashtra sugarcane and Karnataka cotton cooperatives. |
Research Methodology
Cross-validation between agronomist interviews at Brazilian cooperatives and Indian state agricultural departments anchors the qualitative findings against customs data on urea and potash import volumes. Primary fieldwork engaged blending plant managers, cooperative procurement officers, soil science extension agents, and precision agriculture platform engineers across Mato Grosso, Iowa, Maharashtra, and Lower Saxony. Secondary validation drew from ANVISA micronutrient fortification filings, FSSAI subsidy scheme notifications, ECHA REACH authorization databases, and EPA Clean Water Act enforcement records. Bottom-up capacity assessments at regional blending facilities were triangulated against top-down consumption estimates from crop area projections and application rate benchmarks.
Calibration against historical price spreads between standard and enhanced-efficiency grades informed the projection framework across the analysis window. Segmentation dimensions modeled include product type granularity, application intensity by crop value tier, end-user procurement scale, and regional regulatory cluster alignment. CAGRs were derived from elasticity-adjusted demand curves incorporating fertigation penetration rates and organic-mineral substitution thresholds. Industry-specific forecast inputs encompassed drip irrigation expansion trajectories in Brazil's Cerrado and soil health card prescription coverage ratios across Indian states.
Stress conditions across potash supply disruption scenarios, EU carbon border levy implementations, and organic acreage expansion ceilings were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on subsidy continuity, coating technology cost curves, and precision agriculture adoption S-cycles. Material shifts in Belarusian potash export quotas or Indian nutrient-based subsidy reform would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Africa Specialty Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
United States Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Africa Micronutrient Fertilizer Market