
 Agricultural Trailer Market | 2026-2036
Agricultural Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Trailer Market Analysis
Multi-source procurement for axles and hydraulic systems is rebalancing toward regional suppliers with shorter lead times. John Deere leverages its captive foundry network to control critical casting quality for high-capacity frames. AGCO Corporation competes through modular platform architectures that span multiple tractor horsepower classes. Escorts anchors its position in South Asian markets with localized fabrication plants and adapted suspension geometries.
An agricultural trailer is a towed vehicle designed for field and road transport of crops, livestock, or equipment, typically constructed with welded steel chassis members, galvanized or powder-coated surfaces, and rated for gross vehicle weights from 3.5 to over 30 tonnes. Its primary commercial purpose is to extend the logistical reach of mechanized farming operations beyond the limitations of a tractor's integral carrying capacity. Flatbed configurations dominate volume due to universal applicability across grain, hay, and machinery transport, while aluminum-intensive builds command premium positioning where tare weight reduction directly increases payload economics. Heavy Duty and Super Duty categories concentrate margin pools because axle, brake, and frame specifications escalate disproportionately with capacity ratings.
The EPA regulates off-road diesel emissions that affect tractor-trailer matching and powertrain compatibility in the United States. EU REACH restrictions on hexavalent chromium and certain epoxy primers redirect coating selection toward compliant zinc-rich and powder alternatives. Brazil's ANVISA and CONTRAN jointly oversee livestock trailer sanitation and roadworthiness standards that govern export eligibility. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving axle-load regulations reshape material choices and regional sourcing footprints.
Market Dynamics
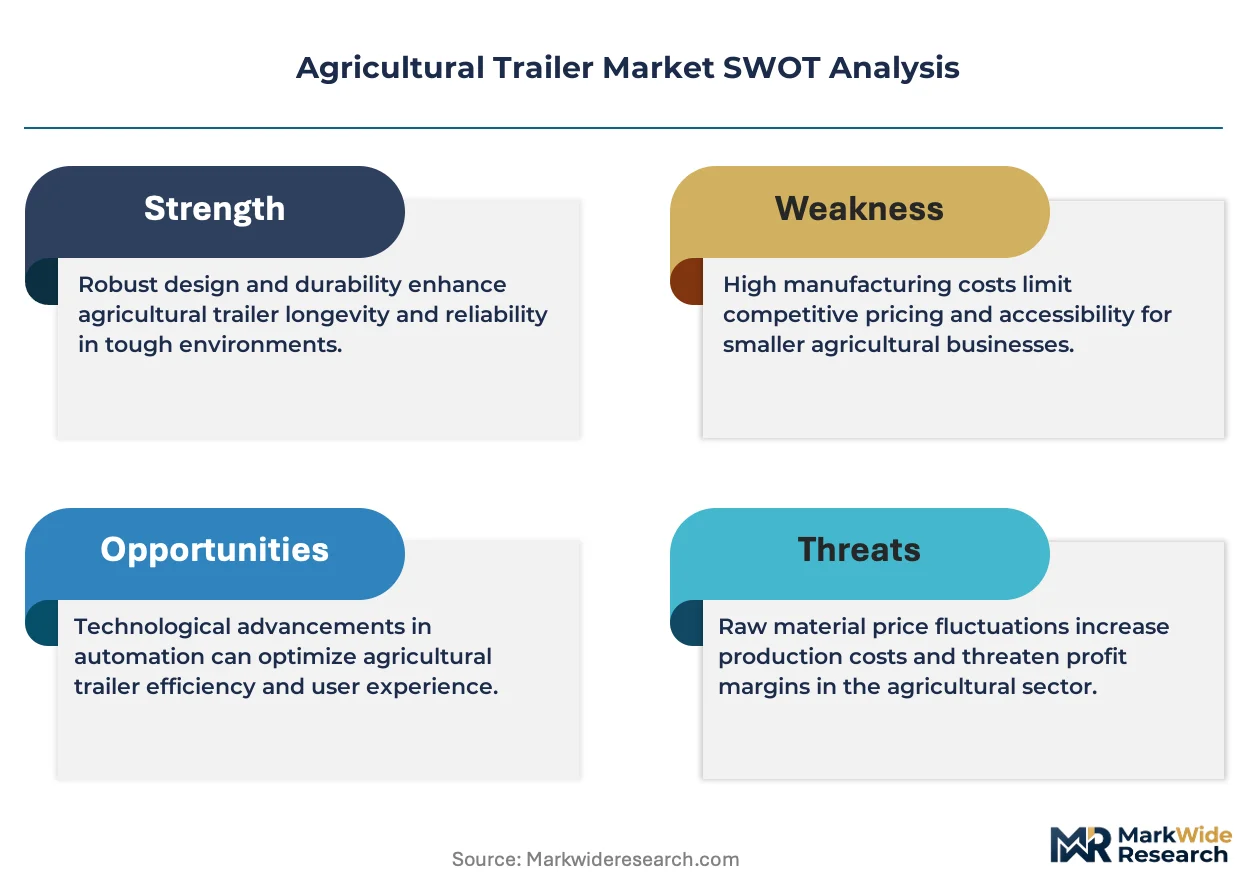
EU REACH restrictions on hexavalent chromium coatings are forcing steel-intensive trailer manufacturers toward zinc-rich and powder-coating alternatives, redrawing material cost structures and supplier relationships across European fabrication networks.
Growth Catalysts
- Livestock trailer sanitation mandates:Brazil's ANVISA and CONTRAN joint standards for roadworthiness and hygiene are expanding commercial fleet replacement cycles among large-scale farming enterprises in Mato Grosso and Paraná.
- Grain-handling corridor mechanization:Iowa, Illinois, and Nebraska are concentrating demand for high-capacity flatbed configurations as elevator consolidation and on-farm storage expansion extend hauling distances.
- Aluminum-intensive tare reduction:Premium payload economics are pulling commercial operators toward lighter chassis designs that maximize legal load limits on interstate corridors.
Market Restraints
- Steel price volatility:Hot-rolled coil fluctuations compress fabrication margins for welded chassis producers locked into annual contract pricing with agricultural OEMs.
- Axle supply concentration:German and Italian component specialists control heavy-duty rated axle assemblies, exposing North American trailer builders to 14-20 week lead time extensions.
- Epoxy primer regulatory friction:EU REACH substance restrictions eliminate proven corrosion-resistant coatings before compliant alternatives achieve equivalent field durability.
Strategic Opportunities
- South Asian localized production:India and Pakistan offer fabrication cost advantages for sub-10 tonne utility trailers serving fragmented smallholder mechanization.
- Telematics-integrated fleet management:GPS tracking and brake-wear sensors are converging with trailer rental and shared-ownership models in Australian broadacre operations.
- Carbon-border adjustment positioning:EU CBAM preparatory phase creates first-mover advantage for manufacturers with documented low-carbon steel sourcing and powder-coating process emissions data.
Industry Challenges
- Welder certification bottlenecks:AWS D1.1 structural welding qualifications for high-strength steel chassis lag demand in US Midwest fabrication hubs.
- Hydraulic system integration complexity:Tipper mechanisms and power-take-off compatibility require field calibration expertise that dealer networks struggle to maintain at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Trailer Market |
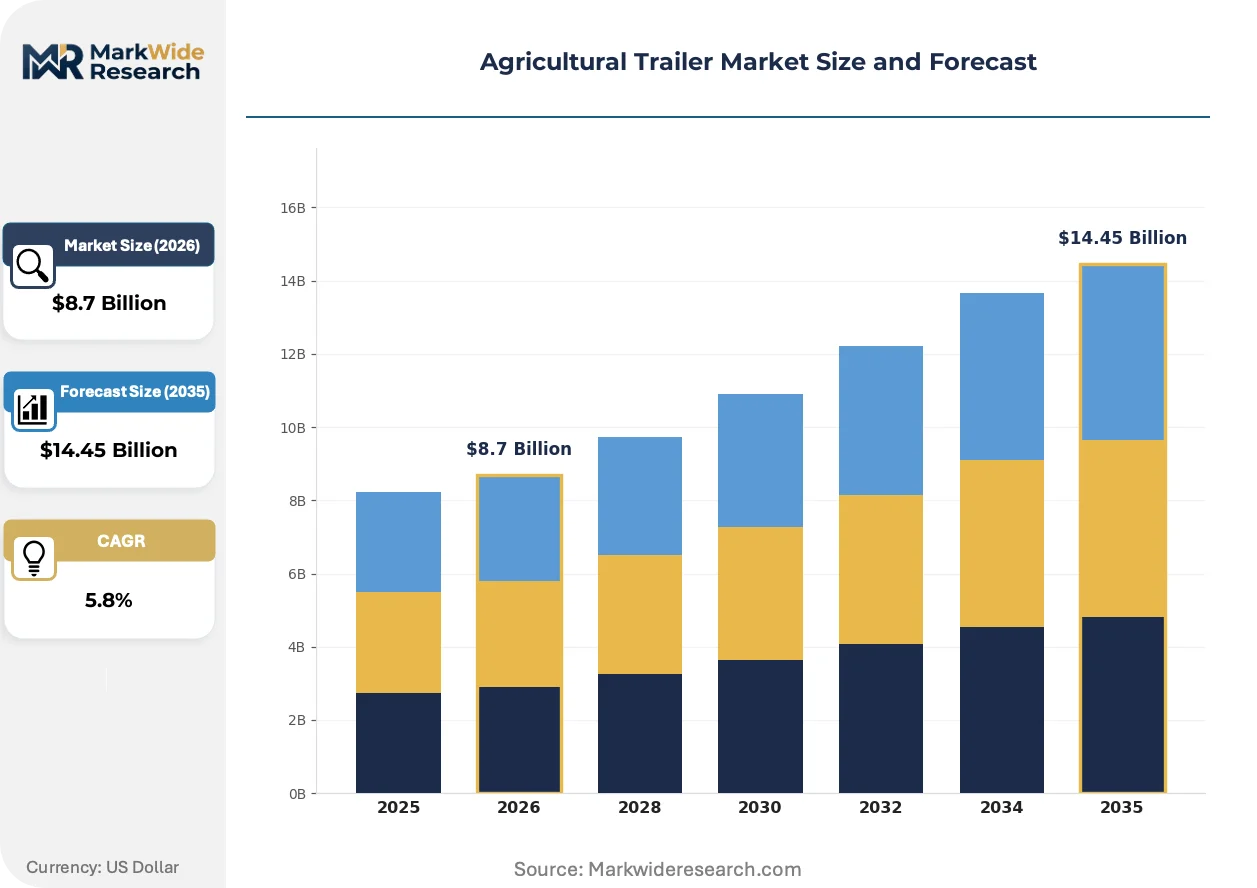
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Lowboy, Dump, Livestock End User: Farmers, Cooperatives, Rental Companies, Commercial Enterprises Material: Steel, Aluminum, Polypropylene, Composite Capacity: Light Duty, Medium Duty, Heavy Duty, Super Duty |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra, Claas, SDF Group, Escorts, Daedong Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Trailer Market Emerging Trajectories
Digital load-sensing and predictive maintenance systems are embedding intelligence into trailer subsystems, while regulatory pressure on coating chemistry accelerates materials substitution across European supply chains.
Telematics-enabled brake monitoring and tire pressure management is converging with cloud-based fleet optimization platforms. Large-scale grain cooperatives in the US Corn Belt are piloting these systems to reduce roadside downtime and extend component replacement intervals. The structural consequence is converging with traditional trailer manufacturing, forcing fabricators to source sensor hardware and software architecture from automotive-tier suppliers rather than legacy agricultural component channels.
EU REACH Annex XVII restrictions on chromium trioxide in conversion coatings are eliminating hexavalent chromium passivation for galvanized steel surfaces. Manufacturers serving European markets must validate zinc-flake and trivalent chromium alternatives through accelerated corrosion testing protocols. Livestock trailer segments face the steepest compliance timeline pressure, as ANVISA-aligned export requirements demand coating durability documentation that new chemistries have not yet accumulated.
Commercial farming enterprises are consolidating trailer procurement through cooperative purchasing agreements and multi-year fleet leases rather than individual unit acquisition. This channel compression displaces independent dealer networks in favor of direct OEM relationships with volume pricing and integrated service contracts. The shift is most visible in Brazilian commercial soybean operations, where equipment pools serving 50,000+ hectare properties negotiate standardized specifications across tipping, flatbed, and livestock configurations.
Agricultural Trailer Market Segmentation
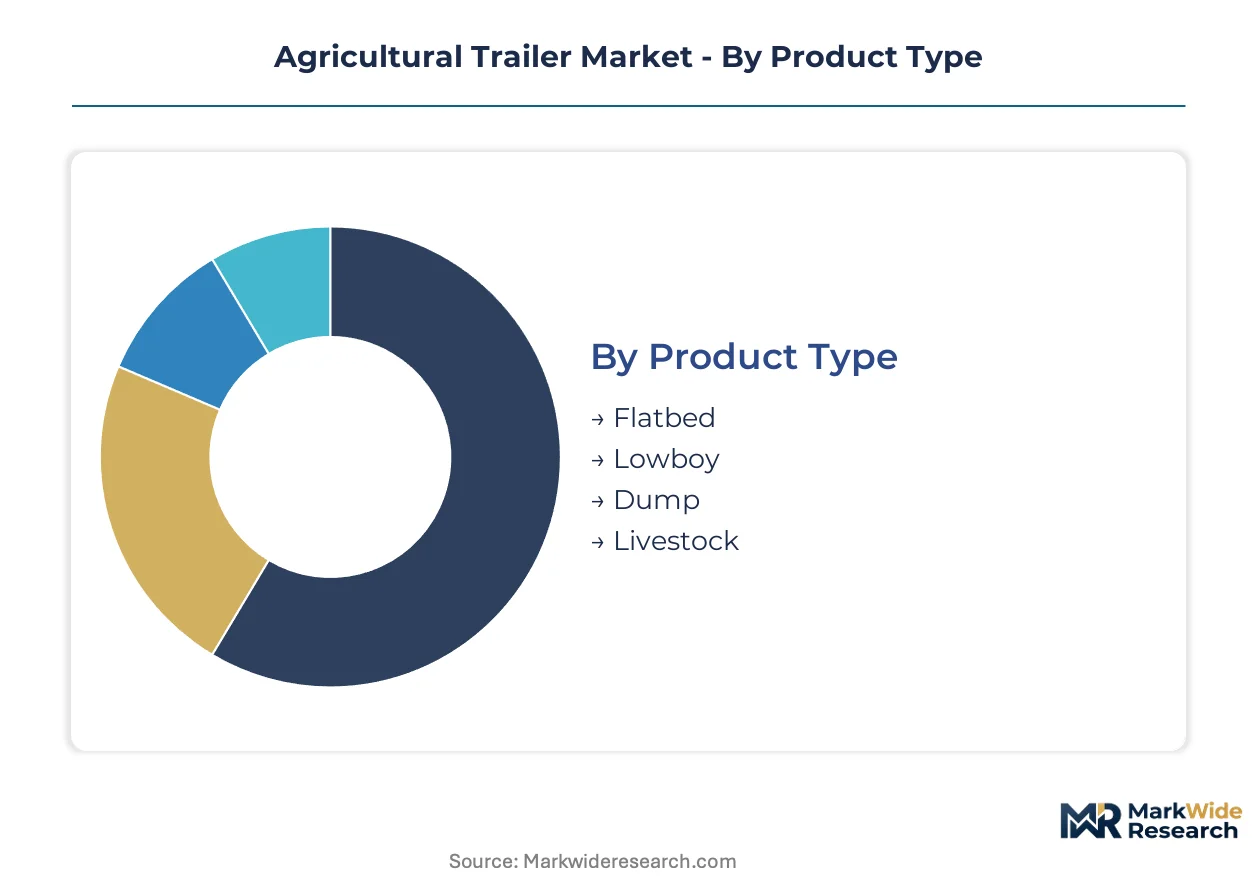
Trailer procurement decisions split across payload economics, regulatory compliance, and fleet standardization pressures. Buyers weigh tare weight reduction against acquisition cost, while coating chemistry and axle ratings reshape long-term ownership calculations across grain, livestock, and equipment transport applications.
Product Type:
Application environment dictates chassis configuration selection, with road-legal dimensions and field maneuverability creating divergent engineering priorities.
- Flatbed:Open-deck welded steel construction accommodates bulk grain, hay bales, and machinery without enclosure constraints. Demand clusters in Iowa, Illinois, and Nebraska as elevator consolidation extends hauling distances from on-farm storage.
- Dump:Hydraulic tipper mechanisms enable rapid unloading of grain and silage at processing facilities. Brazilian soybean operations in Mato Grosso specify reinforced hinge points and corrosion-resistant coatings to withstand high-moisture commodity handling.
- Lowboy:Drop-deck geometry lowers center of gravity for heavy equipment transport. Construction concentrates where combine and tractor distribution networks require oversize load compliance.
- Livestock:Enclosed aluminum or steel bodies with ventilation systems and non-slip flooring. ANVISA sanitation mandates in Brazil are accelerating fleet replacement cycles among commercial enterprises.
Volume sits with Flatbed configurations; growth tilts toward Livestock as biosecurity regulations tighten export eligibility requirements.
End User:
Procurement scale and financing access create tiered demand patterns across fragmented smallholders and consolidated commercial operations.
- Commercial Enterprises:Large-scale farming operations with 50,000+ hectare footprints negotiate multi-year fleet leases and standardized specifications across tipping, flatbed, and livestock configurations. Direct OEM relationships displace independent dealer networks.
- Cooperatives:Pooled purchasing agreements aggregate volume pricing for grain-handling corridors. Shared ownership models in Australian broadacre operations integrate telematics-enabled brake monitoring and tire pressure management.
- Farmers:Individual owner-operators prioritize acquisition cost over payload optimization. Sub-10 tonne utility trailers serve fragmented smallholder mechanization in India and Pakistan.
- Rental Companies:Asset utilization metrics drive specification standardization. GPS tracking and predictive maintenance systems reduce roadside downtime across distributed fleets.
Margin pools concentrate with Commercial Enterprises; cooperative purchasing is gaining share fastest as channel compression accelerates.
Material:
Weight-versus-durability tradeoffs intersect with coating compliance timelines and carbon-border documentation requirements.
- Steel:Hot-rolled coil chassis members with galvanized or powder-coated surfaces dominate welded construction. EU REACH restrictions on hexavalent chromium passivation force validation of zinc-flake and trivalent chromium alternatives.
- Aluminum:Extruded and plate alloys reduce tare weight to maximize legal payload limits on interstate corridors. Premium positioning commands price premiums where hauling economics justify material cost differentials.
- Composite:Fiberglass-reinforced panels and structural members resist corrosion without metallic coatings. Limited adoption concentrates in specialized livestock ventilation and temperature-controlled applications.
- Polypropylene:Molded polymer components for fenders, liners, and non-structural elements. Chemical resistance suits manure and fertilizer contact environments.
Steel retains volume leadership; aluminum-intensive builds show the steepest expansion trajectory as payload economics intensify.
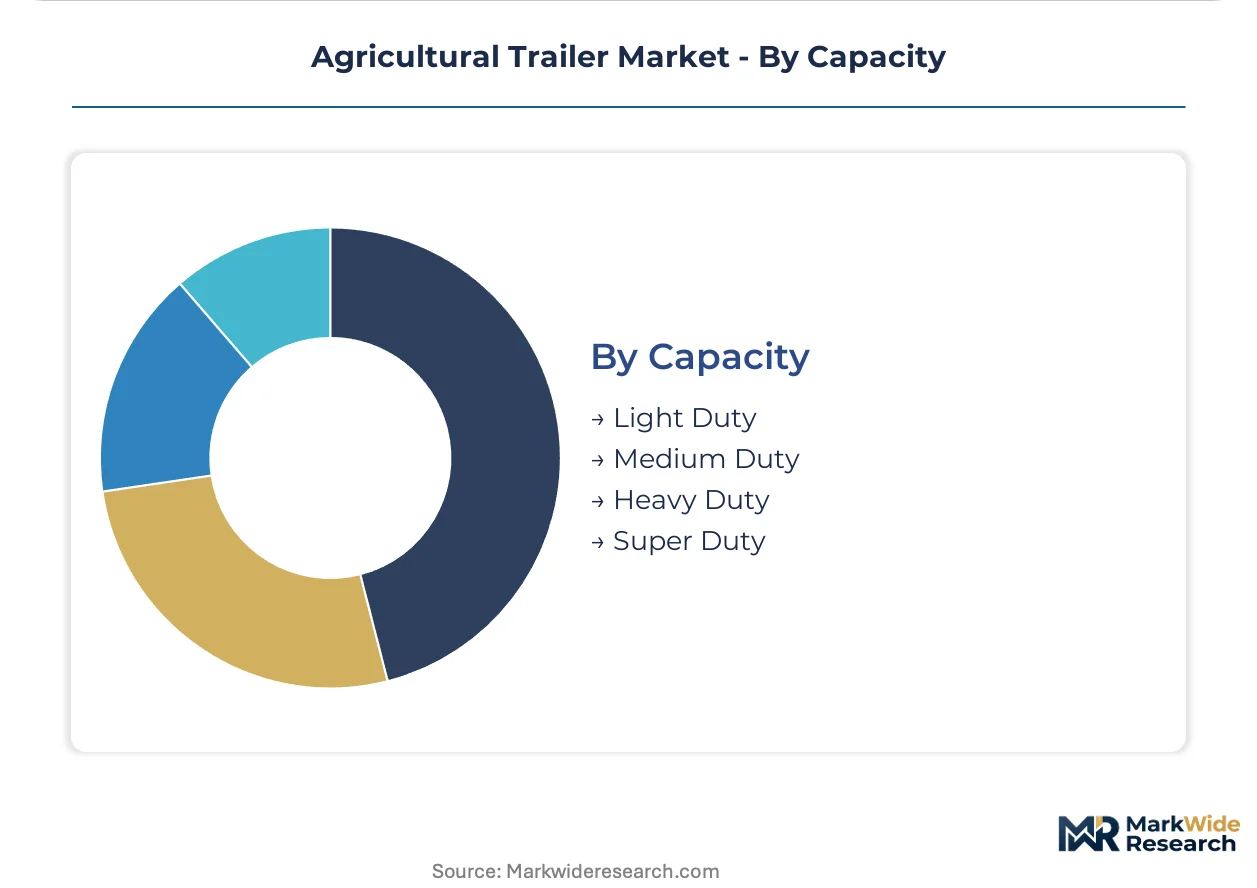
Capacity:
Axle, brake, and frame specifications escalate disproportionately with gross vehicle weight ratings, concentrating margin in upper tiers.
- Heavy Duty:Dual or triple axle configurations rated for 15-25 tonne gross vehicle weight. German and Italian component specialists control heavy-duty rated axle assemblies, exposing North American builders to extended lead times.
- Super Duty:Specialized frames and braking systems exceeding 25 tonnes for mining-scale agricultural operations. AWS D1.1 structural welding qualifications for high-strength steel chassis lag demand in US Midwest fabrication hubs.
- Medium Duty:Single or tandem axle ratings from 8-15 tonnes. Modular platform architectures span multiple tractor horsepower classes without full Heavy Duty engineering overhead.
- Light Duty:Sub-8 tonne ratings for utility and garden tractor compatibility. Localized fabrication plants in South Asia serve cost-sensitive smallholder segments.
Revenue concentrates in Heavy Duty and Super Duty tiers; Medium Duty offers the most accessible growth path for regional manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hot-rolled coil supply from integrated steel mills in the US Midwest anchors fabrication capacity for high-capacity grain trailers serving the Corn Belt corridor.
United States
Elevator consolidation across Iowa, Illinois, and Nebraska extends hauling distances from on-farm storage, concentrating demand for heavy-duty flatbed configurations. EPA off-road diesel emission standards govern tractor-trailer powertrain matching. Welding certification bottlenecks in Midwest fabrication hubs constrain chassis production for Super Duty ratings.
Brazil
Commercial soybean operations in Mato Grosso and Paraná negotiate standardized fleet specifications across tipping, flatbed, and livestock configurations. ANVISA and CONTRAN jointly oversee livestock trailer sanitation and roadworthiness standards. São Paulo-based equipment pools serving 50,000+ hectare properties drive cooperative purchasing agreements that displace independent dealer networks.
Germany
Axle and hydraulic component specialists control heavy-duty rated assemblies, exposing North American builders to extended lead times. EU REACH Annex XVII restrictions on hexavalent chromium passivation force validation of zinc-flake coating alternatives. Bavarian fabrication networks redraw material cost structures as compliant surface treatments replace legacy chemistries.
India
Fragmented smallholder mechanization creates demand for sub-10 tonne utility trailers with localized fabrication cost advantages. BIS standards govern structural welding and material specifications for agricultural equipment. Escorts anchors its position with adapted suspension geometries serving Punjab and Haryana farming belts.
Australia
Broadacre operations pilot telematics-enabled brake monitoring and tire pressure management through shared ownership models. The country's national agricultural equipment regulator oversees roadworthiness standards for interstate grain corridors. Queensland and New South Wales grain cooperatives integrate GPS tracking with cloud-based fleet optimization platforms.
Agricultural Trailer Market Vendor Landscape
Backward integration into critical component supply dominates the current landscape, with captive foundry networks and axle manufacturing reshaping cost structures. The vendor base clusters around three strategic archetypes: diversified agricultural OEMs with full-line tractor compatibility, regional specialists serving localized terrain requirements, and component-integrated fabricators controlling casting quality. M&A activity and capacity expansion in South Asian fabrication hubs represent the primary competitive vectors as manufacturers position for carbon-border documentation requirements.
Within the diversified OEM tier, John Deere, AGCO Corporation, and Escorts exemplify contrasting geographic anchoring strategies. Deere's North American foundry integration represents upstream control over high-strength steel chassis production. AGCO's modular platform architectures span multiple tractor horsepower classes without full heavy-duty engineering overhead. Escorts occupies a position in South Asian cost-optimized segments through localized fabrication plants and adapted suspension geometries for sub-10 tonne utility ratings.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra |
| Claas |
| SDF Group |
| Escorts |
| Daedong Industrial |
| Others |
Supply Flow & Price Mechanics
EU REACH-mandated coating substitutions are forcing trailer fabricators to absorb zinc-flake and powder-coating cost premiums, compressing margins on steel-intensive builds while rewarding early adopters with documented compliance for carbon-border positioning. This specification pressure cascades through supplier negotiations, with axle and hydraulic specialists extracting favorable terms from builders locked into annual OEM contracts.
Pricing Analysis
Warranty and field-service bundling separates premium trailer OEMs from unbundled regional fabricators, with John Deere and AGCO Corporation embedding multi-year maintenance contracts into fleet lease structures. Price differentiation rests on coating durability documentation and axle load certification tier, with Heavy Duty ratings commanding substantial premiums over Medium Duty configurations. Pricing pressure stems from hot-rolled coil volatility, with contract-locked builders unable to pass steel cost swings to agricultural OEMs. Individual owner-operators in South Asian markets exhibit the highest price sensitivity, while Brazilian commercial enterprises prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Welder certification bottlenecks in Iowa, Illinois, and Nebraska fabrication hubs constrain chassis throughput for Super Duty ratings, while AWS D1.1 qualification lags extend production queues. Geographic supply concentration centers on Germany and Italy for heavy-duty axle assemblies, the US Midwest for hot-rolled coil, and India for sub-10 tonne utility trailer fabrication. Raw material dependencies span high-strength steel coil, aluminum extrusions, and zinc-rich coating chemistries. Supply chain risk concentrates in single-source axle vulnerability, with 14-20 week lead time exposure for North American builders. Distribution runs through direct OEM relationships with commercial enterprises, cooperative purchasing agreements, and residual independent dealer networks serving fragmented farmers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable manufacturers, with EU REACH coating mandates and carbon-border documentation requirements forcing smaller fabricators without validation resources toward exit or acquisition.
For Market Incumbents: Deepen captive foundry control over high-strength steel casting quality to defend against modular platform competitors, while accelerating zinc-flake coating validation to capture first-mover advantage under EU CBAM preparatory rules. Capacity expansion in South Asian fabrication hubs anchors cost position against regional specialists. Certification investment in ANVISA-aligned livestock trailer sanitation documentation protects Brazilian export eligibility. For New Entrants and Emerging Players: The gap between premium aluminum-intensive builds and economy steel configurations offers entry space for hybrid material strategies targeting Medium Duty cooperative purchasers in Australian broadacre and US Corn Belt grain corridors. Telematics-integrated fleet management systems represent the most penetrable white-space, with GPS tracking and brake-wear sensors displacing legacy component channels. Go-to-market execution should prioritize shared-ownership model partnerships with equipment pools rather than dealer network replication. For Investors and Strategic Acquirers: The window for entry favors component-integrated fabricators with documented low-carbon steel sourcing and powder-coating emissions data ahead of EU CBAM full implementation. Long-term viability over the coming decade rests on regulatory compliance infrastructure rather than pure fabrication scale. Acquisition targets should demonstrate validated coating alternatives and established OEM direct relationships. The signal to watch is ANVISA livestock trailer sanitation enforcement intensity in Mato Grosso and Paraná, which will accelerate fleet replacement concentration among compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Axle Manufacturing | Captive supply of heavy-duty rated assemblies insulates North American builders from German and Italian lead time volatility. |
| Coating Chemistry Validation Investment | Accelerated corrosion testing of zinc-flake alternatives secures EU market access before REACH enforcement tightens. |
| South Asian Fabrication Footprint Expansion | Localized production in India and Pakistan captures cost-sensitive sub-10 tonne utility demand with adapted suspension geometries. |
| Telematics Platform Partnership | Sensor hardware and cloud architecture from automotive-tier suppliers enables fleet optimization for Australian grain cooperatives. |
| Carbon-Border Documentation System | Process emissions tracking and low-carbon steel sourcing records position manufacturers for EU CBAM first-mover advantage. |
Methodological Framework
Document review covered customs and trade databases, SEC filings from listed agricultural equipment manufacturers, and EU regulatory filings through ECHA, complemented by interviews with fabrication plant managers, OEM procurement teams at John Deere and AGCO Corporation, aftermarket service heads, and coating chemistry suppliers. Secondary validation drew from EPA emission standards documentation, ANVISA sanitation protocols, and BIS structural welding specifications. Bottom-up trailer production estimates triangulated against top-down agricultural mechanization expenditure data across the analysis window.
Unit shipment and revenue projections across the modeling period incorporated product type segmentation by flatbed, dump, lowboy, and livestock configurations; material tier differentiation across steel, aluminum, composite, and polypropylene; and capacity classification from Light Duty through Super Duty ratings. CAGRs were derived from regression analysis of historical mechanization intensity against arable land consolidation trends, with tractor horsepower class distributions and elevator network density serving as industry-specific demand drivers.
Inputs from primary stakeholder interviews and regulatory documentation were available through the study window; gaps in real-time coating durability field data and evolving EU CBAM implementation details introduce uncertainty bands around compliance cost assumptions. Forecasts reflect documented assumptions regarding REACH enforcement timelines and carbon-border phase-in schedules. Material deviation in ANVISA livestock trailer sanitation enforcement, hot-rolled coil price volatility, or axle supply concentration disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Hatchery Equipment Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Commercial Vegetable Chopper Market