
 Organic Fertilizers Market | 2026-2036
Organic Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Fertilizers Market Analysis
Buyer concentration among large-scale organic farms and contract horticulture operations is expanding as smaller growers form procurement cooperatives. Scotts Miracle-Gro leverages its retail garden center network to control shelf placement in North American home improvement channels. Yara International ASA anchors its position through backward integration into mineral extraction and biostimulant R&D. Coromandel International Limited dominates South Asian agricultural supply stores with region-specific micronutrient blends.
Organic fertilizers comprise carbon-based soil amendments derived from plant residues, animal manures, composted organic matter, or processed biological waste, typically containing nitrogen, phosphorus, and potassium in forms requiring microbial mineralization before plant uptake. Their primary commercial purpose centers on rebuilding soil organic carbon while delivering nutrients compliant with certified organic production standards. Dry fertilizers occupy the largest volume share due to lower transport costs and extended shelf stability across agricultural supply chains. Liquid formulations represent the fastest-expanding category as fertigation systems penetrate protected horticulture in Spain and the Netherlands. Granular products retain margin concentration among premium turf management contractors seeking slow-release nitrogen predictability.
The USDA National Organic Program governs input eligibility for certified organic operations in the United States, while the EU Green Deal and REACH frameworks constrain synthetic additive contamination across European supply chains. India's FSSAI and APEDA jointly enforce residue limits on exported organic produce, indirectly mandating input traceability. Stakeholders must monitor evolving carbon credit methodologies that could monetize soil organic sequestration claims tied to verified organic fertilizer application protocols.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing synthetic nitrogen allowances across European agriculture, forcing input suppliers to reconfigure product portfolios toward certified organic alternatives while contract horticulture operations consolidate procurement power.
Growth Catalysts
- EU Green Deal nitrogen limits:The Farm to Fork strategy mandates synthetic fertilizer reduction targets, redirecting commercial farm expenditure toward organic-certified inputs.
- India's horticulture export zones:Maharashtra and Gujarat states drive premium organic fertilizer uptake as APEDA residue enforcement tightens traceability requirements for export-bound produce.
- Fertigation technology penetration:Protected horticulture operations in Spain and the Netherlands accelerate liquid organic formulation demand through precision irrigation integration.
Market Restraints
- Raw material cost volatility:Animal manure and composted biomass prices fluctuate with livestock feed costs and seasonal collection availability.
- South Asian supply concentration:Coromandel International Limited controls regional micronutrient blending capacity, creating single-source dependency for specialized formulations.
- Mineralization rate uncertainty:Microbial nutrient release timing varies with soil temperature and moisture, limiting predictability for high-value crop scheduling.
Strategic Opportunities
- Carbon credit monetization:Emerging soil organic sequestration methodologies could create verified offset revenue streams tied to documented organic fertilizer application protocols.
- Retail garden center channel expansion:North American home improvement networks present underexploited shelf space for consumer-scale organic lawn and garden products.
- Biostimulant convergence:Integration of microbial inoculants with traditional organic fertilizers offers premium positioning in specialty crop segments.
Industry Challenges
- USDA National Organic Program compliance timelines:Input verification and listing processes create 12-18 month product launch delays.
- Soil microbiome expertise scarcity:Agronomic advisory capacity for optimizing microbial mineralization protocols lags behind formulation supply expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Fertilizers Market |
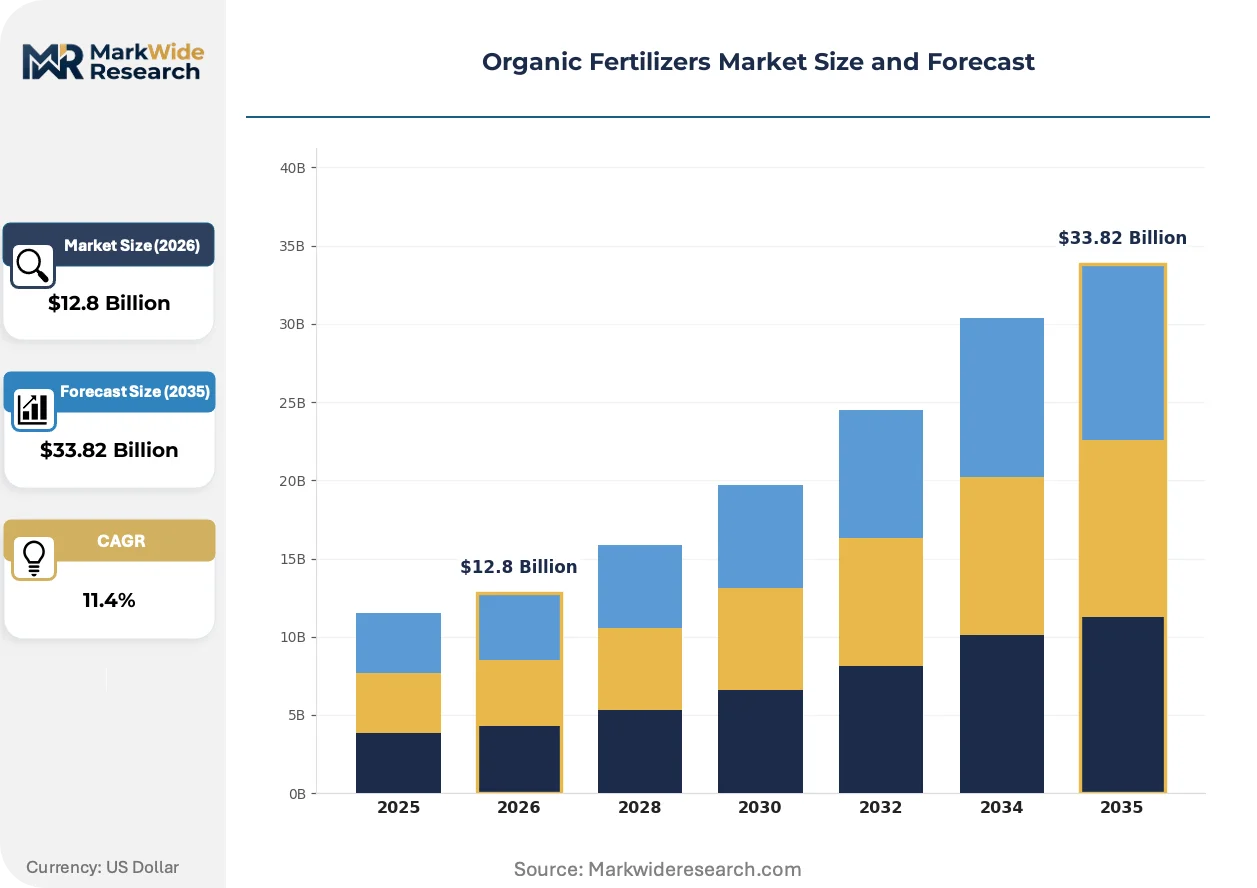
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fertilizers, Dry Fertilizers, Compost, Manure Application: Agricultural, Horticultural, Landscaping, Turf Management Formulation: Granular, Liquid, Powder, Pelletized Distribution Channel: Online Retail, Garden Centers, Agricultural Supply Stores, Wholesale Distributors |
| Companies Covered | Hello Nature (Italpollina S.p.A.), Coromandel International Limited, Darling Ingredients Inc., California Organic Fertilizers Inc., Scotts Miracle-Gro Company, Yara International ASA, Fertoz Ltd., SPIC Ltd., Midwestern BioAg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Fertilizers Market Emerging Trajectories
Biological processing technologies and regulatory carbon accounting frameworks are restructuring how organic fertilizers are manufactured, certified, and monetized across agricultural value chains.
Precision fermentation of agricultural waste streams is rewriting nitrogen recovery economics. Specialty crop operations in California's Central Valley adopt these systems at pilot scale. The technology compresses traditional composting cycles from months to days while standardizing nutrient content profiles.
REACH framework amendments tighten contaminant thresholds for processed organic inputs entering European supply chains. Industrial composting facilities face capital-intensive upgrading to meet heavy metal and pathogen screening requirements. Dry fertilizer exporters to Germany and France reconfigure preprocessing protocols to maintain market access.
Buyer consortium formation among mid-scale organic operations is displacing individual farm procurement. Horticulture cooperatives in India's export corridors aggregate volume to negotiate formulation customization and batch traceability. This concentration shifts bargaining power toward grower organizations and away from distributor intermediaries.
Organic Fertilizers Market Segmentation
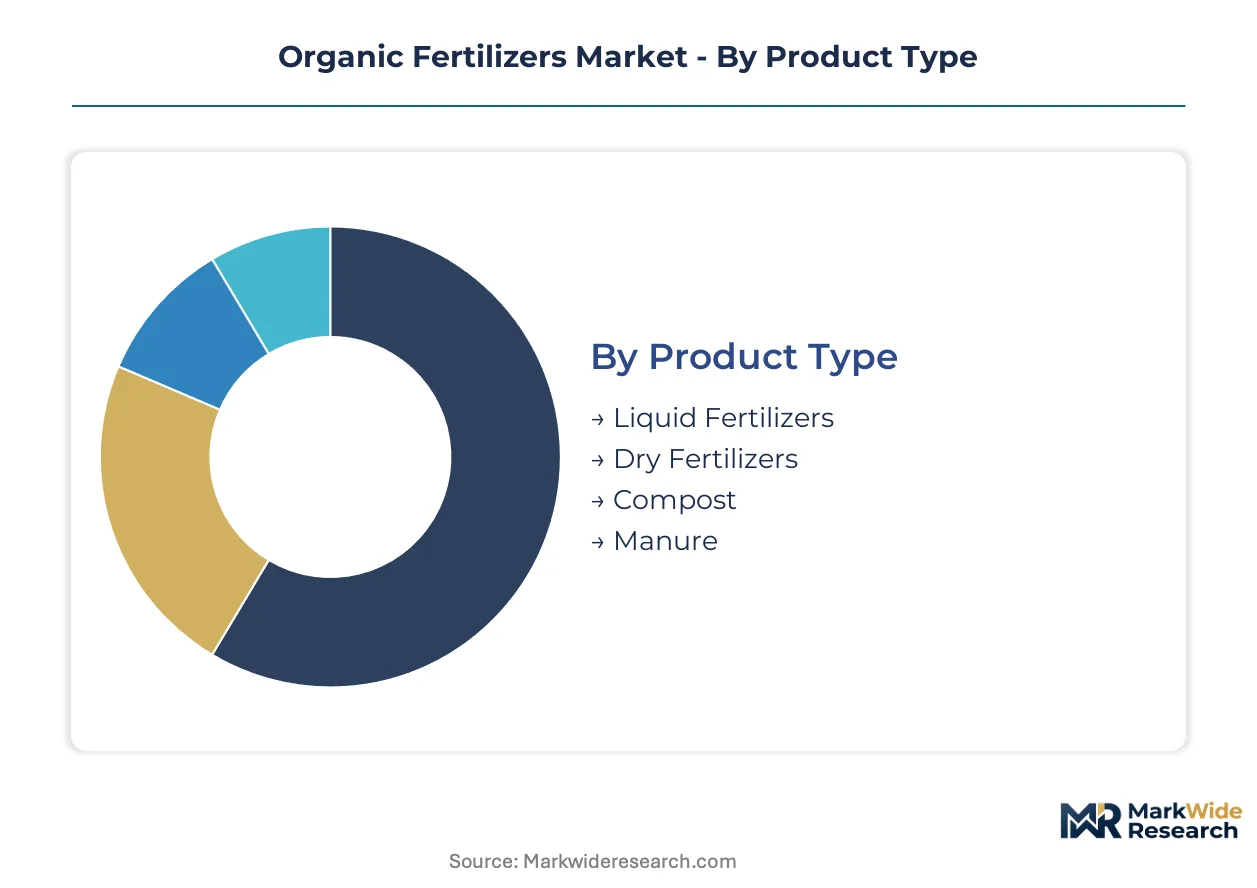
Segmentation in the organic fertilizers market reveals how supply chain configuration shapes competitive access and margin capture. Product form determines transport economics and shelf stability. Application context drives certification requirements and pricing power.
Product Type:
Supply concentration among compost processors and manure aggregators determines regional availability and input cost structures for each product category.
- Dry Fertilizers:Composted organic matter and processed residues in solid form deliver extended shelf stability and reduced moisture content for bulk agricultural distribution. Volume concentrates in Midwest grain operations and Indian wheat belts where mechanized spreading equipment dominates. Rail and truck economics favor high-density packaging for long-haul supply chains.
- Liquid Fertilizers:Suspended or dissolved organic nutrients in aqueous solution enable precision fertigation integration and rapid foliar uptake. Demand clusters in Spanish greenhouse complexes and Dutch glasshouse operations where drip irrigation infrastructure is mature. REACH contaminant thresholds force preprocessing investments for European market access.
- Compost:Aerobically decomposed organic matter stabilized through controlled thermophilic processing. Municipal and agricultural waste streams feed regional composting facilities near California's Central Valley specialty crop zones.
- Manure:Animal excreta collected from livestock operations, often composted or processed to reduce pathogens and odor. Poultry and dairy belt proximity shapes supply geography in Wisconsin, Netherlands, and Gujarat.
Today's leader: Dry Fertilizers. Tomorrow's challenger: Liquid Fertilizers.
Application:
End-use context determines certification stringency, nutrient specification, and buyer procurement sophistication across four distinct demand clusters.
- Agricultural:Broadacre field crop production requiring volume-scale nutrient replacement compliant with organic certification standards. Midwest soybean and corn operations and Indian Punjab rice-wheat systems drive bulk procurement. USDA National Organic Program listing requirements create 12-18 month supplier qualification timelines.
- Horticultural:Intensive fruit, vegetable, and ornamental production with premium pricing for certified organic output. Maharashtra grape exporters and California strawberry operations demand batch traceability and residue documentation. APEDA enforcement tightens input verification for Indian export corridors.
- Landscaping:Non-food turf and ornamental maintenance with lower regulatory burden but growing sustainability preference. Municipal and corporate grounds management specifications increasingly mandate organic-only protocols.
- Turf Management:Golf course and sports field maintenance requiring predictable nitrogen release and aesthetic uniformity. Slow-release granular formulations command premium positioning among specialty contractors.
Agricultural volume dominates procurement scale. Horticultural applications capture the steepest expansion trajectory through export premiumization.
Formulation:
Physical processing state determines application equipment compatibility, nutrient release kinetics, and storage infrastructure requirements.
- Granular:Compacted particles with controlled size distribution for mechanical spreader compatibility and gradual dissolution. Turf management contractors in Florida and Arizona prioritize slow-release nitrogen predictability for seasonal scheduling.
- Liquid:Pumpable suspensions or solutions integrating with irrigation infrastructure. Netherlands greenhouse operators and Spanish protected horticulture facilities drive formulation standardization for fertigation compatibility.
- Powder:Fine-ground organic matter requiring dissolution or soil incorporation before plant availability. Compost teas and microbial activator blends use powder bases for on-farm brewing systems.
- Pelletized:Compressed organic material with binding agents for reduced dust and controlled dispersion. Home garden retail channels favor pelletized products for consumer handling convenience.
Granular formulations anchor commercial agriculture procurement. Liquid formats are gaining share fastest through precision irrigation penetration.
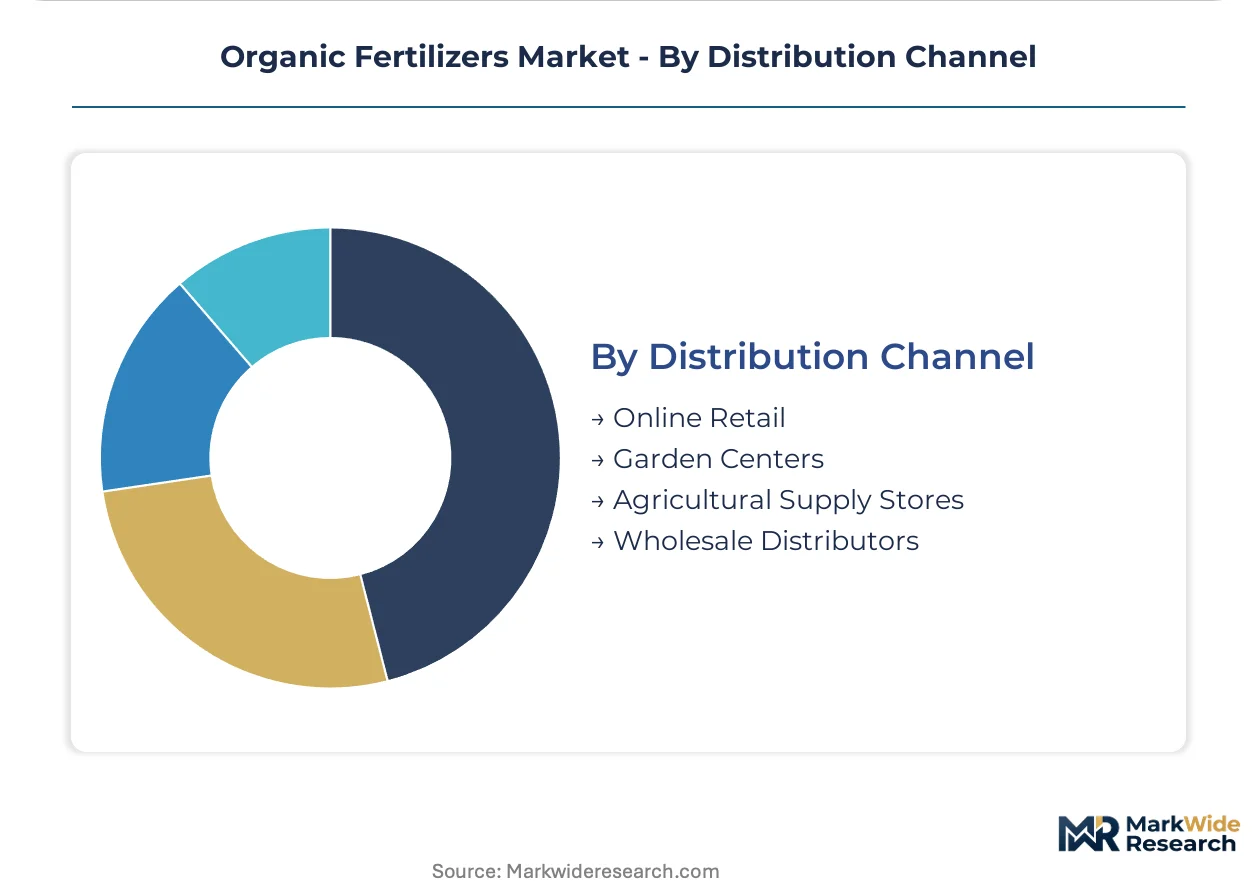
Distribution Channel:
Channel structure determines margin stacking, technical advisory access, and geographic reach for organic fertilizer suppliers.
- Agricultural Supply Stores:Rural-focused retailers with agronomic advisory capacity and seasonal credit terms for farm customers. Coromandel International Limited dominates South Asian store networks with region-specific micronutrient blends.
- Wholesale Distributors:Volume aggregators serving commercial farm operations and retail intermediaries with logistics consolidation. Midwest cooperatives and European farm supply groups centralize procurement for member operations.
- Garden Centers:Consumer-facing retail with shelf placement competition and seasonal demand concentration. Scotts Miracle-Gro leverages its North American home improvement network for premium positioning.
- Online Retail:Direct-to-consumer and small-farm channels with subscription models and technical content delivery. Urban gardening segments and hobby farm operations drive platform specialization.
Wholesale distributors control volume flow. Online retail presents the most rapid channel expansion opportunity through direct farmer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomic talent clusters in California's Central Valley, the Netherlands' Wageningen corridor, and India's Gujarat-Maharashtra belt anchor organic fertilizer innovation and commercial deployment worldwide.
United States
Specialty crop growers in California's Central Valley expand certified organic input purchases to meet export residue standards. The USDA National Organic Program governs input eligibility with 12-18 month verification timelines. Midwestern grain operations in Iowa and Illinois drive dry fertilizer volume through mechanized spreading infrastructure.
Germany
REACH framework amendments tighten heavy metal and pathogen thresholds for processed organic inputs entering European supply chains. Industrial composting facilities near Hamburg and Berlin face capital-intensive upgrading to maintain market access. Wholesale distributors centralize procurement for member farm cooperatives across Lower Saxony.
India
Horticulture exporters in Maharashtra and Gujarat states drive premium organic fertilizer uptake as FSSAI and APEDA tighten residue enforcement. Coromandel International Limited dominates South Asian agricultural supply stores with region-specific micronutrient blends. Punjab's rice-wheat systems anchor bulk agricultural procurement scale.
Netherlands
Protected horticulture operations in Dutch glasshouse clusters accelerate liquid organic formulation demand through precision fertigation integration. The EU Green Deal's Farm to Fork strategy compresses synthetic nitrogen allowances, redirecting commercial expenditure toward certified alternatives. Wageningen University anchors biostimulant R&D convergence with traditional organic inputs.
Spain
Greenhouse complexes in Almería and Murcia drive liquid fertilizer standardization for drip irrigation compatibility. The EU Green Deal mandates synthetic fertilizer reduction targets across Mediterranean agriculture. Regional composting networks near Valencia feed municipal and agricultural waste streams into certified organic input supply.
Organic Fertilizers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation concentrates among agricultural input majors with backward integration into mineral extraction and biostimulant research. Three archetypes dominate: vertically integrated multinationals with captive supply chains, regional formulators with micronutrient blending expertise, and retail-channel specialists controlling shelf placement. Capacity expansion and strategic partnerships represent the dominant competitive moves as players reposition portfolios toward nitrogen-compliant alternatives.
Among diversified multinationals, Yara International ASA and Scotts Miracle-Gro occupy positions exemplifying upstream integration and retail channel dominance respectively. Coromandel International Limited represents the regional formulator archetype with concentrated South Asian supply store presence. Hello Nature and California Organic Fertilizers Inc. sit within specialty crop-focused tiers serving export-oriented horticulture operations with batch traceability requirements.
| Leading Market Players |
|---|
| Hello Nature (Italpollina S.p.A.) |
| Coromandel International Limited |
| Darling Ingredients Inc. |
| California Organic Fertilizers Inc. |
| Scotts Miracle-Gro Company |
| Yara International ASA |
| Fertoz Ltd. |
| SPIC Ltd. |
| Midwestern BioAg |
| Others |
Supply Flow & Price Mechanics
Contract horticulture operations and procurement cooperatives among mid-scale organic farms concentrate buying power, shifting organic fertilizer markets toward volume-based contract structures with tiered certification premiums.
Pricing Analysis
Bundled agronomic advisory services command 15-25% premiums over unbundled product-only transactions, particularly where USDA National Organic Program compliance guidance is included. Pricing stratifies across premium, standard, and economy tiers based on certification grade and batch traceability depth. Cost compression in economy-grade compost and manure formulations is intensifying because livestock feed price volatility transmits directly through raw material costs. Smallholder cooperatives in India's export corridors exhibit highest price sensitivity, while California specialty crop operations prioritize residue documentation over unit economics.
Supply Chain Analysis
Animal manure and composted biomass supply rests on livestock operations concentrated in Wisconsin, Netherlands, and Gujarat, with poultry belt proximity shaping regional availability. Processed organic fertilizers draw from agricultural waste streams, municipal composting facilities, and mineral extraction operations as secondary inputs. Single-source vulnerability runs through Coromandel International Limited's micronutrient blending capacity for South Asian specialized formulations. Distribution runs through agricultural supply stores and wholesale cooperatives, with online retail channels expanding fastest for direct farm relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork nitrogen reduction mandates compound demand for certified organic alternatives, creating structural procurement shifts across European agriculture and export-oriented supply chains.
For Market Incumbents: To counter procurement cooperative consolidation and buyer price pressure, Yara International ASA and Scotts Miracle-Gro should deepen backward integration into biostimulant R&D and mineral extraction to secure captive nutrient supply. Certification investment in accelerated USDA National Organic Program listing processes compresses 12-18 month verification timelines to defend shelf placement and contract eligibility.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium California export-grade formulations and economy bulk compost presents white-space opportunity in region-specific micronutrient blends for India's Maharashtra grape cooperatives. Target underexploited North American garden center shelf space with pelletized consumer formats, leveraging subscription-based soil testing bundles as the go-to-market anchor.
For Investors and Strategic Acquirers: Diversified agricultural input majors with existing distribution infrastructure are the most active acquirer in this space, seeking nitrogen-compliant portfolio repositioning. Mid-cap regional formulators with APEDA-traceable batch systems and established South Asian supply store networks represent priority acquisition archetypes. Watch for carbon credit methodology finalization as the signal indicating monetizable soil sequestration revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biostimulant R&D | Yara International ASA secures captive nutrient supply and premium positioning in specialty crop segments. |
| USDA National Organic Program Certification Acceleration | Compressed verification timelines defend contract eligibility for Midwest grain operations and California exporters. |
| Garden Center Channel Expansion | Scotts Miracle-Gro leverages home improvement network density for consumer-scale organic lawn product placement. |
| Precision Fermentation Pilot Deployment | California Central Valley operations adopt waste-stream nitrogen recovery to standardize nutrient profiles. |
| Carbon Credit Methodology Alignment | Verified soil organic sequestration protocols enable offset revenue monetization for documented application systems. |
Methodological Framework
Direct dialogue with organic fertilizer plant managers, procurement leads at contract horticulture operations, agricultural supply store owners, and APEDA compliance officers grounded qualitative insights, cross-referenced with EU Green Deal implementation documents, USDA National Organic Program listings, FSSAI residue enforcement records, and customs trade data. Bottom-up volume aggregation and top-down market sizing approaches were triangulated to validate segment-level outputs.
Market value and volume projections across the analysis window reflect a segmented analytical framework incorporating product form, application context, certification tier, and regional regulatory cluster. CAGRs were derived from historical trajectory analysis and policy-mandated demand inflection modeling, with EU nitrogen limit timelines and India horticulture export growth patterns serving as primary forecast inputs.
Caveats apply where REACH contaminant threshold amendments or carbon credit methodology revisions could materially shift the outlook for processed organic input market access and revenue model viability. A small set of regulatory finalization triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
India Fertilizers Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market