
 Catalyst Fertilizers Market | 2026-2036
Catalyst Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Catalyst Fertilizers Market Intelligence
REACH compliance is rebalancing the cost-of-entry calculus for European catalyst fertilizer suppliers, requiring exhaustive substance registration and toxicity documentation before market placement. BASF SE leverages its integrated ammonia-to-catalyst pipeline to sustain margin control across urea and nitrate value chains. Clariant AG anchors its position through specialized zeolite formulations that dominate emission-control applications in ammonia plants. Johnson Matthey competes via deep R&D intensity in noble-metal catalyst recovery, reducing long-term input cost volatility for fertilizer producers.
Catalyst fertilizers are chemical accelerators—typically iron, vanadium, or nickel-based compounds supported on alumina or silica substrates—that lower activation energy in ammonia oxidation and urea synthesis reactions, enabling higher conversion efficiency at moderate temperature and pressure. Urea-based catalyst systems occupy the largest volume share due to their centrality in ammonia plant throughput, while phosphate-based formulations represent the fastest-growing category as sulfuric acid wet-process plants upgrade for food-grade phosphoric acid output. Complex fertilizers command premium positioning because their multi-nutrient catalyst beds require tailored active-site engineering that locks in technical service relationships with agrochemical companies and large cooperatives.
EPA New Source Performance Standards and China's MEE emission ceilings are tightening nitrogen oxide discharge limits, compelling ammonia producers to replace legacy catalyst beds with higher-activity formulations. ISO 14001 environmental management certification and India's BIS quality marks are becoming non-negotiable for vendor qualification by agricultural cooperatives and state procurement boards. Stakeholders must monitor regulatory divergence between jurisdictions, as catalyst lifetime claims and heavy-metal content thresholds are fragmenting into incompatible national standards that will reshape supplier certification investments and regional manufacturing footprints.
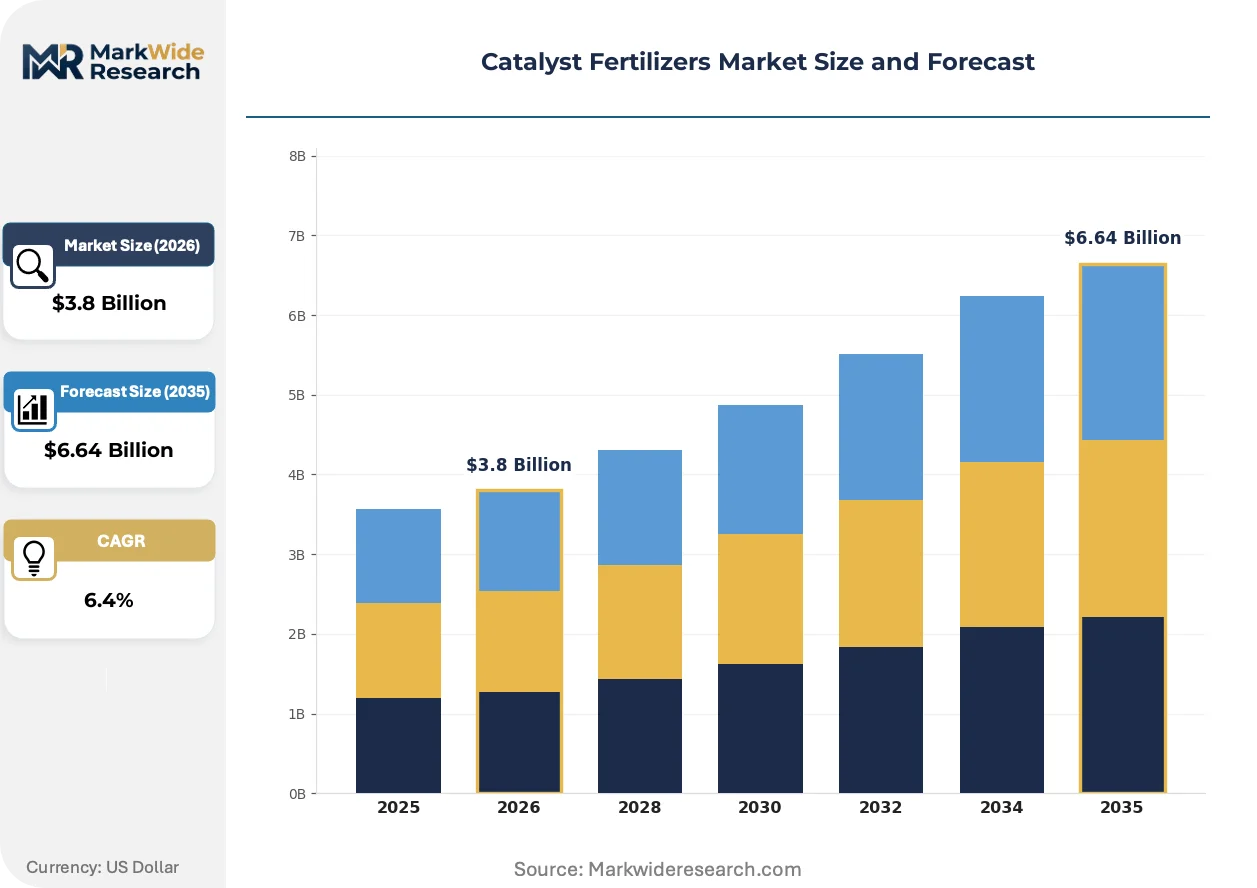
Market Dynamics
EU F-Gas Regulation retrofit mandates are compressing catalyst bed replacement cycles across European ammonia plants, while agricultural cooperatives in Brazil and India scale bulk procurement of emission-compliant formulations. This regulatory-driven hardware refresh is redrawing supplier qualification criteria and technical service relationships.
Growth Catalysts
- Emission ceiling enforcement:China's MEE nitrogen oxide discharge limits are compelling ammonia producers to upgrade legacy catalyst beds with higher-activity formulations, creating sustained replacement demand.
- Cooperative procurement consolidation:Agricultural cooperatives in Brazil's Mato Grosso and India's Punjab are aggregating coated urea catalyst purchases to meet state-level micronutrient mandates and nitrous oxide protocols.
- Zeolite substrate innovation:Specialized zeolite formulations for ammonia plant emission control are locking in multi-year technical service contracts with large fertilizer complexes.
Market Restraints
- Noble metal cost volatility:Iridium and ruthenium price swings embedded in catalyst active sites create margin instability for producers without recovery capabilities.
- REACH documentation burden:European substance registration and toxicity protocols extend time-to-market for new catalyst formulations by 18-24 months.
- Alumina supply concentration:High-purity alumina substrate production clusters in limited geographies, exposing catalyst manufacturers to freight and tariff risk.
Strategic Opportunities
- Smallholder penetration in India:Indo-Gangetic Plain state procurement boards are mandating complex fertilizer adoption, opening technical service relationships with catalyst suppliers.
- Food-grade phosphoric acid upgrade:Sulfuric acid wet-process plants are retrofitting catalyst systems to meet food-grade output standards, displacing commodity-grade capacity.
- ISO 14001 certification arbitrage:Environmental management certification is becoming a non-negotiable vendor qualifier, favoring pre-certified suppliers in public tenders.
Industry Challenges
- Catalyst lifetime validation:Fragmenting national standards for heavy-metal content thresholds and performance claims are forcing redundant testing protocols.
- Retrofit integration complexity:Legacy ammonia plant infrastructure requires custom catalyst bed engineering, stretching technical service teams and project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catalyst Fertilizers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea-Based, Ammonium Nitrate, Phosphate-Based, Potassium Chloride, Complex Fertilizers Application: Cereal Crops, Oilseeds, Vegetables, Pulses, Fiber Crops, Plantation Crops End User Industry: Smallholder Farmers, Agricultural Cooperatives, Agrochemical Companies, Commercial Growers, Research Institutions Distribution Channel: Retail Outlets, Online Marketplaces, Direct Sales, Agricultural Wholesalers, Agro-Dealers |
| Companies Covered | BASF SE, N.E. CHEMCAT, Clariant AG, Axens, LKAB Minerals, Johnson Matthey, Haldor Topsoe A/S, Albemarle Corporation, Topsoe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catalyst Fertilizers Market Strategic Shifts & Innovations
Modular catalyst bed designs and digital monitoring systems are compressing the traditional supplier-buyer relationship, shifting value capture toward performance-guarantee contracts and away from commodity hardware sales.
Electrochemical ammonia synthesis catalysts are decentralizing production geography by enabling smaller-scale, distributed ammonia plants with lower capital intensity. Agricultural cooperatives in Brazil are piloting containerized units for localized urea production. This topology is decentralizing the historical concentration of ammonia capacity near natural gas hubs.
REACH substance registration requirements are fragmenting catalyst formulation portfolios across European suppliers, forcing dedicated registration teams and toxicology partnerships. The compliance burden falls heaviest on multi-nutrient complex fertilizer catalyst beds with diverse active-site chemistries. Suppliers are responding by narrowing product lines to core zeolite and base-metal formulations with established dossiers.
Cooperative procurement boards are consolidating vendor panels and unbundling after-sales technical service from hardware supply. India's state agricultural departments now require standalone catalyst performance audits. This purchasing model shift is most visible in Punjab and Haryana, where cooperative buying power has compressed supplier margins and extended payment terms.
Catalyst Fertilizers Market Segmentation
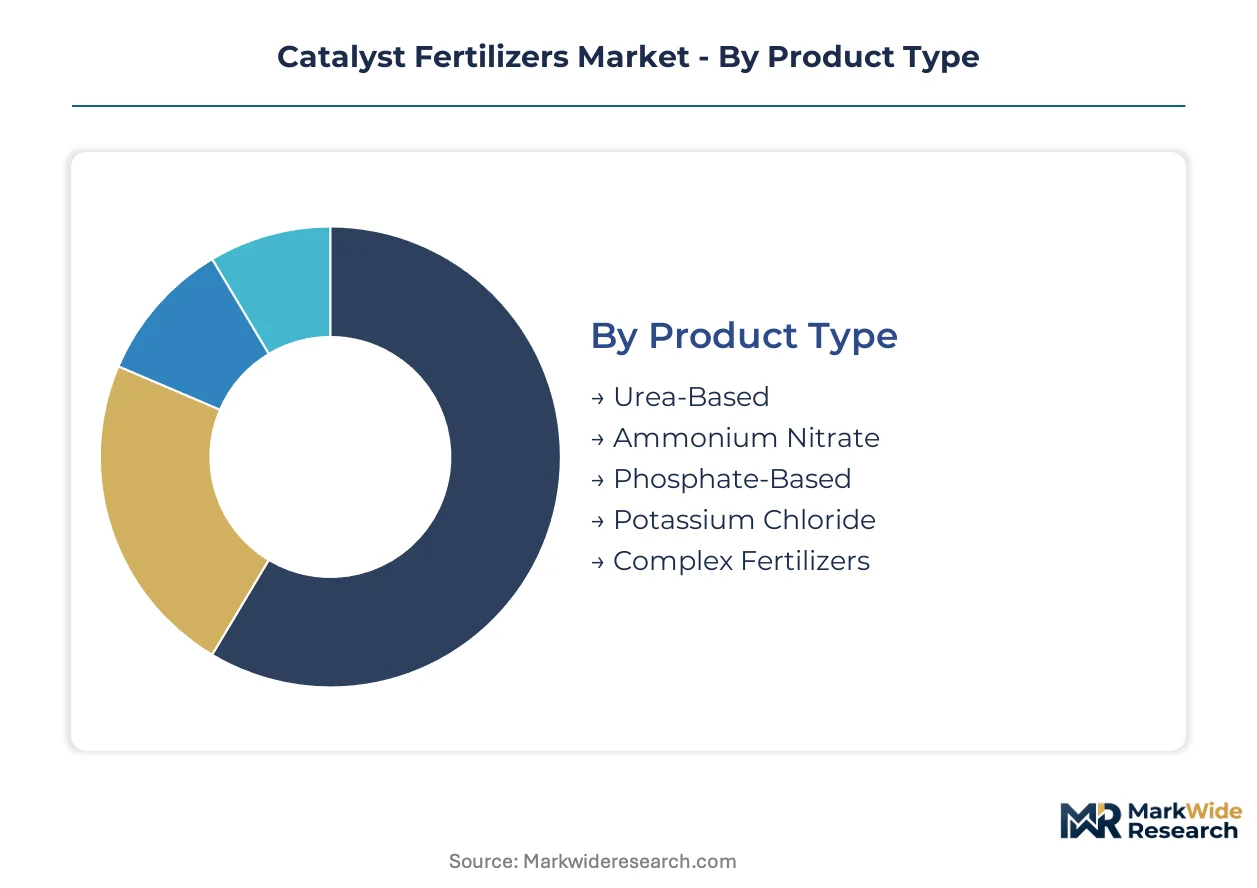
Catalyst fertilizer purchasing hinges on crop economics, regulatory exposure, and technical service requirements. Buyers segment choices by nutrient density, emission compliance, and cooperative procurement power rather than commodity pricing alone.
Product Type:
Cost tier determines procurement patterns across ammonia plant retrofits and agricultural applications.
- Urea-Based:Iron and vanadium compounds supported on alumina substrates dominate ammonia oxidation throughput. Demand concentrates in Brazil's Mato Grosso agricultural cooperatives scaling bulk purchases to meet state nitrous oxide protocols.
- Complex Fertilizers:Multi-nutrient catalyst beds require tailored active-site engineering with nickel-based formulations on silica supports. India's Indo-Gangetic Plain state procurement boards mandate these for smallholder compliance with micronutrient directives.
- Phosphate-Based:Sulfuric acid wet-process catalysts upgrading for food-grade phosphoric acid output.
- Ammonium Nitrate:Emission-control zeolite formulations for European ammonia plants under F-Gas Regulation retrofit mandates.
- Potassium Chloride:Base-metal catalyst systems for chloride-tolerant crop applications.
Volume sits with Urea-Based systems; growth tilts toward Complex Fertilizers.
Application:
Application selection tracks crop revenue intensity and nitrogen oxide exposure.
- Cereal Crops:High-volume urea catalyst consumption in wheat and rice cultivation. China's MEE nitrogen oxide discharge limits are compelling ammonia producers serving this segment to upgrade legacy catalyst beds.
- Vegetables:Precision nutrient delivery demands complex fertilizer catalyst beds with controlled-release active sites. Commercial growers in India's Punjab cluster procure these through consolidated cooperative panels.
- Oilseeds:Sulfur-tolerant catalyst formulations for soybean and rapeseed production systems.
- Pulses:Low-nitrogen catalyst options suited to leguminous crop nitrogen fixation.
- Fiber Crops:Cost-optimized base-metal catalysts for cotton and jute cultivation.
- Plantation Crops:Long-cycle catalyst stability requirements for tea and coffee estates.
Volume concentrates in Cereal Crops; premium expansion tracks Vegetables.
End User Industry:
Customer type dictates technical service intensity and contract structure.
- Agricultural Cooperatives:Aggregated procurement of coated urea catalysts with performance-guarantee contracts. Brazil and India cooperatives unbundle after-sales technical service from hardware supply, extending payment terms.
- Agrochemical Companies:Multi-year technical service relationships for complex fertilizer catalyst bed engineering. These buyers lock in specialized zeolite formulations through integrated ammonia-to-catalyst pipelines.
- Smallholder Farmers:State-mandated complex fertilizer adoption through Indo-Gangetic Plain procurement boards.
- Commercial Growers:Direct procurement of premium catalyst formulations for high-value crop output.
- Research Institutions:Pilot-scale catalyst testing for electrochemical ammonia synthesis validation.
Procurement volume aggregates through Agricultural Cooperatives; margin capture favors Agrochemical Companies.
Distribution Channel:
Channel selection reflects certification requirements and buyer scale.
- Agricultural Wholesalers:Bulk catalyst fertilizer movement to cooperative procurement boards with ISO 14001 certification as non-negotiable vendor qualifier. India's state agricultural departments require standalone catalyst performance audits through this channel.
- Direct Sales:Custom catalyst bed engineering for legacy ammonia plant retrofits. European F-Gas Regulation compliance drives technical service relationships directly with fertilizer complexes.
- Retail Outlets:Fragmented smallholder access with limited technical service attachment.
- Online Marketplaces:Emerging procurement for standardized catalyst formulations with documented dossiers.
- Agro-Dealers:Last-mile distribution with localized inventory for immediate replacement demand.
Volume flows through Agricultural Wholesalers; relationship value concentrates in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Petroleum, Chemicals and Petrochemicals Investment Regions (PCPIRs) concentrate ammonia catalyst demand through integrated fertilizer corridors. Brazil's Manaus Free Trade Zone and China's coastal chemical parks similarly anchor regional production clusters.
India
State procurement boards in Punjab and Haryana aggregate coated urea catalyst purchases for smallholder compliance with micronutrient mandates. BIS quality marks and standalone catalyst performance audits now gate vendor qualification for Indo-Gangetic Plain agricultural cooperatives. Gujarat's Dahej PCPIR hosts ammonia plant retrofits serving fertilizer complexes upgrading for stricter emission protocols.
China
MEE nitrogen oxide discharge limits compel ammonia producers across Shandong and Jiangsu provinces to replace legacy catalyst beds with higher-activity formulations. Dual carbon goals accelerate zeolite substrate adoption in coastal chemical parks. Yangtze River Delta fertilizer clusters concentrate demand for emission-compliant catalyst systems serving domestic urea output.
Brazil
Mato Grosso agricultural cooperatives scale bulk procurement of nitrous oxide-compliant coated urea catalysts under state environmental protocols. ANVISA registration requirements intersect with state-level fertilizer quality mandates. The Manaus Free Trade Zone attracts catalyst substrate importation for localized ammonia plant technical service relationships.
Germany
EU F-Gas Regulation retrofit mandates compress catalyst bed replacement cycles across Ludwigshafen and Leverkusen chemical corridors. REACH substance registration requirements extend time-to-market for new zeolite formulations. BASF SE's integrated ammonia-to-catalyst pipeline anchors technical service relationships with European fertilizer complexes.
United States
EPA New Source Performance Standards tighten nitrogen oxide discharge limits for Gulf Coast ammonia producers serving Corn Belt fertilizer demand. Louisiana's chemical corridor concentrates catalyst bed engineering for legacy plant retrofits. Agricultural cooperatives in Iowa and Illinois consolidate procurement through ISO 14001-certified vendor panels.
Catalyst Fertilizers Market Key Industry Players
German and Swiss producers anchor the premium catalyst formulation tier; Indian and Chinese specialists hold cost-optimized substrate positions. The market structures around three tiers: integrated chemical conglomerates with captive ammonia pipelines, specialized zeolite engineering houses, and regional base-metal catalyst fabricators. Consolidation pressures favor multi-year technical service contracts over commodity hardware sales. Capacity expansion and portfolio narrowing toward REACH-compliant core formulations dominate competitive moves.
Within the integrated chemical tier, BASF SE and Clariant AG occupy positions defined by upstream control over ammonia-to-catalyst value chains. Johnson Matthey exemplifies the noble-metal recovery archetype, reducing input cost volatility for fertilizer producers through R&D intensity in catalyst regeneration. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning: the German conglomerate, the Swiss specialty chemicals house, and the UK-based materials technology group each represent distinct competitive vectors in emission-control and fertilizer catalysis.
| Leading Market Players |
|---|
| BASF SE |
| N.E. CHEMCAT |
| Clariant AG |
| Axens |
| LKAB Minerals |
| Johnson Matthey |
| Haldor Topsoe A/S |
| Albemarle Corporation |
| Topsoe |
| Others |
Cost & Logistics Intelligence
Cooperative procurement consolidation across Brazil's Mato Grosso and India's Punjab is forcing suppliers to absorb extended payment terms and unbundle technical service from hardware, compressing margins and favoring producers with captive alumina substrate production.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as ammonia plant retrofit schedules tighten under EU F-Gas Regulation deadlines. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant zeolite formulations from base-metal commodity beds and uncertified regional alternatives. Cost compression in standard-tier catalysts is intensifying because Indian and Brazilian cooperatives now mandate standalone performance audits. Agricultural cooperatives exhibit highest price sensitivity; integrated agrochemical companies with multi-year technical service contracts show lowest.
Supply Chain Analysis
India's PLI scheme for specialty chemicals and China's domestic-content requirements for emission-control equipment are reshaping sourcing patterns for alumina and zeolite substrates. High-purity alumina production clusters in China, India, and Germany; noble-metal recovery capabilities concentrate in the UK and Switzerland. Catalyst formulation draws from iridium, ruthenium, and high-grade silica with freight and tariff exposure on cross-border substrate movements. Distribution runs through agricultural wholesalers with ISO 14001 certification gating vendor qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
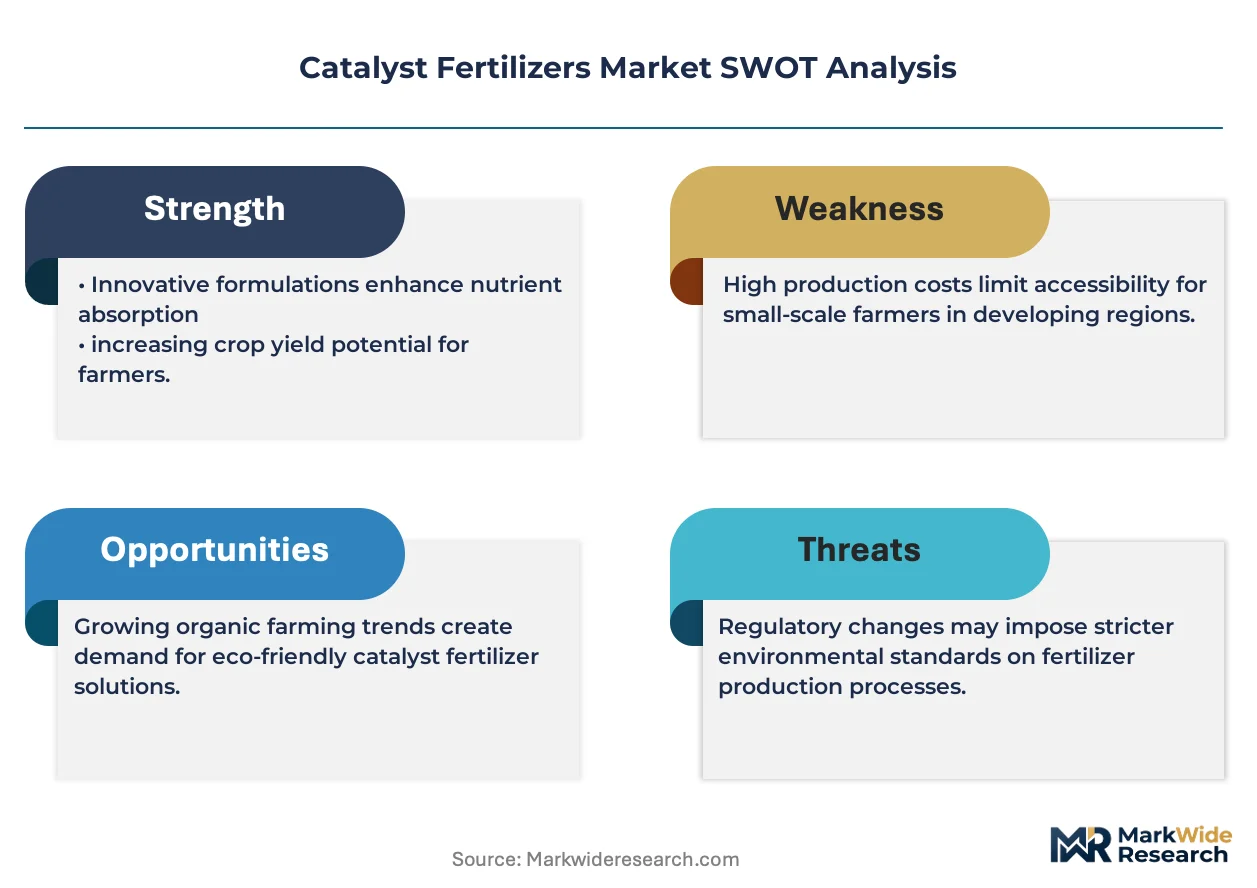
Analyst Recommendations
The catalyst fertilizer market sits in a technology-transition phase as electrochemical ammonia synthesis displaces Haber-Bosch infrastructure for distributed production.
For Market Incumbents: Anticipate margin compression from cooperative procurement unbundling by locking in backward integration into alumina substrate production and narrowing formulation portfolios to REACH-compliant core zeolites with established toxicology dossiers. Electrochemical ammonia pilots in Brazil threaten centralized catalyst bed demand. For New Entrants and Emerging Players: China's MEE nitrogen oxide discharge limits open a window for emission-control zeolite specialists to establish technical service relationships with Shandong and Jiangsu ammonia producers retrofitting legacy plants. Food-grade phosphoric acid upgrade demand in sulfuric acid wet-process facilities offers the most penetrable white-space. Lead with modular catalyst bed designs paired with digital monitoring subscriptions. For Investors and Strategic Acquirers: The window for entry favors noble-metal recovery technology holders with R&D intensity in catalyst regeneration. Long-term viability hinges on positioning for electrochemical ammonia catalyst architectures as Haber-Bosch capacity plateaus. Watch for inflection when containerized ammonia units achieve commercial scale in Brazilian agricultural cooperatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Substrates | Captive supply of high-purity alumina insulates margin from freight and tariff volatility. |
| REACH-Compliant Formulation Narrowing | Focused zeolite portfolios reduce registration burden and accelerate time-to-market. |
| Electrochemical Ammonia Catalyst R&D | Distributed production topology requires entirely new active-site engineering for containerized units. |
| Performance-Guarantee Contract Expansion | Outcome-based pricing shifts value capture from hardware to technical service relationships. |
| ISO 14001 Certification Arbitrage | Pre-certified suppliers capture public tender share as agricultural cooperatives consolidate vendor panels. |
Research Approach
Document review covered customs and trade data, SEC filings from listed chemical conglomerates, and REACH registration dossiers, complemented by interviews with ammonia plant engineering directors, agricultural cooperative procurement leads, zeolite R&D specialists, and emission-control regulatory consultants. Primary fieldwork across India's PCPIRs, Brazil's Mato Grosso cooperatives, and Germany's chemical corridors informed demand-side validation. Secondary sources included BIS quality mark documentation, MEE discharge limit notifications, and F-Gas Regulation implementation guidance. Bottom-up catalyst bed replacement forecasts triangulated against top-down ammonia capacity expansion projections.
Segmentation outputs across product type, application, end-user industry, and distribution channel were modeled over the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles against regulatory compliance deadlines. Industry-specific inputs incorporated zeolite substrate innovation timelines, noble-metal price volatility indices, and cooperative procurement consolidation rates.
The model assumes a particular technology adoption path; alternative pathways for electrochemical ammonia synthesis would alter the outlook for centralized Haber-Bosch catalyst demand. Forecasts reflect assumptions around regulatory enforcement consistency, substrate supply continuity, and cooperative buying power consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Fertilizer Additives Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
South America Fertilizers Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
India Fertilizers Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market