
 India Micronutrient Fertilizer Market | 2026-2036
India Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
India Micronutrient Fertilizer Market Foresight
Organic chelating agents are decoupling micronutrient delivery from traditional inert carriers, reducing leaching losses and improving foliar uptake economics. Coromandel International Ltd leverages its coastal manufacturing footprint to dominate eastern and southern distribution corridors. Zuari Agro Chemicals Ltd anchors its position through integrated phosphate-micronutrient complexes along the west coast. Haifa Group specializes in water-soluble specialty grades for protected cultivation, competing directly with domestic blenders in the premium horticulture channel.
India micronutrient fertilizers comprise mineral salts and chelated compounds containing essential trace elements such as zinc, iron, manganese, copper and boron, typically applied at concentrations below ten kilograms per hectare to correct soil deficiencies and optimize enzymatic functions in plants. Zinc sulfate remains the volume anchor across cereal belts where alkaline soils lock native zinc in unavailable forms, while iron chelates command premium positioning in high-value fruit orchards and export-oriented vegetable farms. Foliar spray application is gaining fastest among smallholder farmers adopting knapsack sprayers for targeted intervention during critical growth stages, whereas fertigation penetration tracks closely with expanding drip network coverage in Gujarat, Maharashtra and Tamil Nadu.
The Fertiliser Control Order under the Ministry of Agriculture mandates micronutrient content labeling and quality certification through BIS standards, tightening market access for unregistered importers and informal blenders. State-level agricultural departments in Punjab, Haryana and Uttar Pradesh enforce soil health card-based recommendations that directly influence farmer procurement of zinc and boron formulations. Stakeholders must monitor how the proposed integration of micronutrients under the nutrient-based subsidy regime alters pricing transparency and working capital cycles across the value chain.
Market Dynamics
The National Food Security Mission's nano-urea mandate is compressing traditional micronutrient procurement cycles while Maharashtra's drip irrigation expansion creates concentrated demand pockets for water-soluble grades.
Growth Catalysts
- Soil Health Card scheme:State agricultural departments in Punjab, Haryana and Uttar Pradesh mandate deficiency-based recommendations, creating institutional pull for zinc and boron formulations among wheat and rice growers.
- Protected cultivation expansion:Polyhouse clusters around Nashik, Bengaluru and Pune generate sustained offtake for chelated iron and specialty manganese grades in high-value horticulture.
- PLI scheme for agrochemical manufacturing:Domestic production incentives under the Ministry of Chemicals and Fertilizers are reshaping import dependency ratios for water-soluble complexes.
Market Restraints
- EDTA chelate cost volatility:Imported organic chelating agents from Chinese chemical manufacturers expose blenders to currency fluctuation and shipping disruption risks.
- Sulfuric acid supply concentration:Zinc sulfate production depends on captive acid supply from phosphoric acid manufacturers, limiting new entrant capacity additions.
- Alkaline soil lock-up:Native zinc unavailability in Indo-Gangetic plains forces repeated applications, raising per-hectare input costs above smallholder tolerance thresholds.
Strategic Opportunities
- North-eastern state penetration:Assam and Tripura tea estates remain underpenetrated for boron and manganese foliar programs, offering volume expansion outside saturated western markets.
- Drone-based micronutrient spraying:Kisan drones under the Sub-Mission on Agricultural Mechanization enable aerial application in flood-prone Bihar and eastern Uttar Pradesh rice belts.
- Nutrient-based subsidy integration:Proposed inclusion of micronutrients under the NBS regime would flatten price volatility and accelerate working capital rotation for distributors.
Industry Challenges
- Soil testing technician scarcity:District soil testing laboratories lack trained personnel to process health card samples within the recommended 15-day turnaround, delaying prescription accuracy.
- Fertigation system integration:Legacy flood irrigation infrastructure in Madhya Pradesh and Rajasthan requires capital-intensive retrofitting to accommodate compatible drip networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Micronutrient Fertilizer Market |
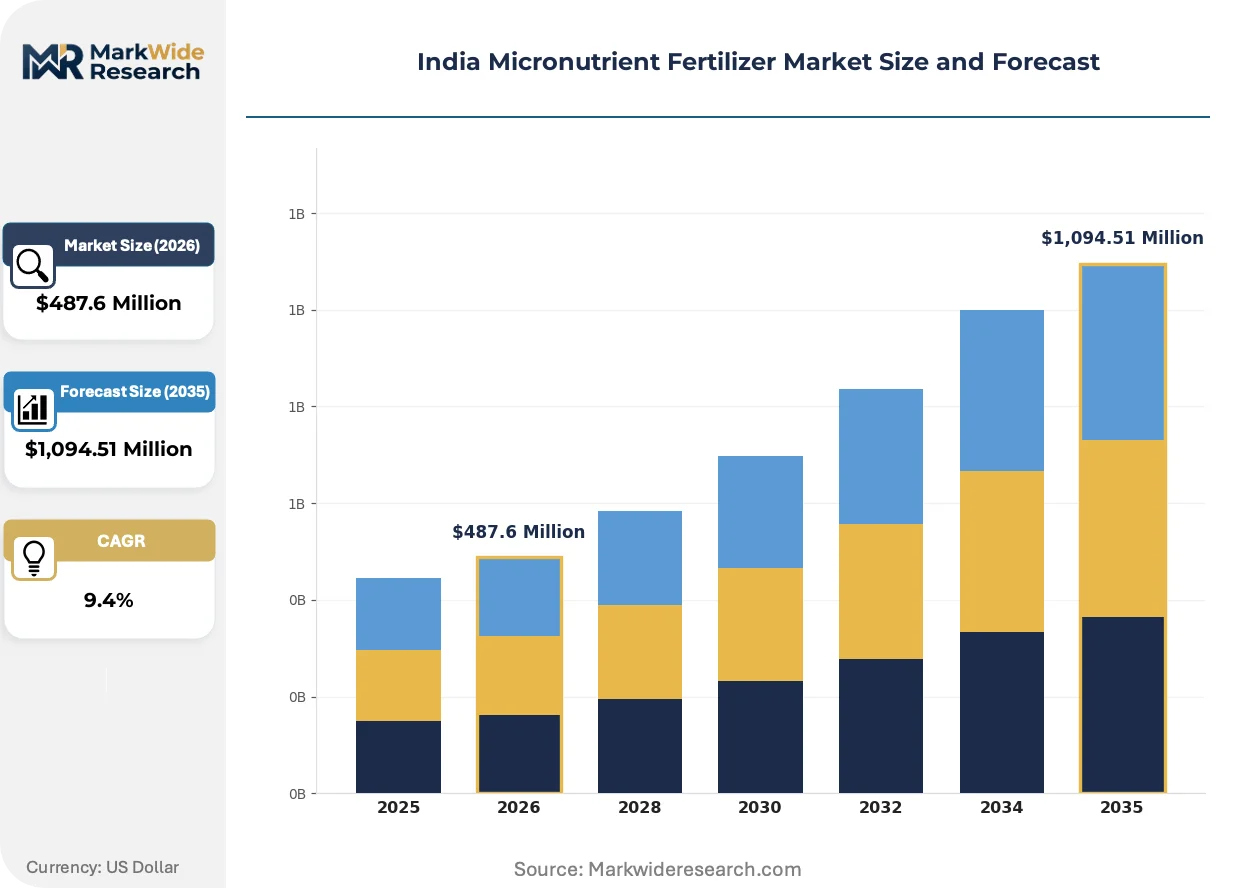
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc Sulfate, Manganese Sulfate, Copper Sulfate, Iron Chelates Application Method: Soil Application, Foliar Spray, Seed Treatment, Fertigation Crop Type: Cereals, Pulses, Fruits, Vegetables User Type: Large Farmers, Smallholder Farmers, Cooperatives, Commercial Growers |
| Companies Covered | Zuari Agro Chemicals Ltd, Mangalore Chemicals & Fertilizers Ltd, Coromandel International Ltd, Haifa Group, Yara Fertilisers India Pvt Ltd, Chambal Fertilizers & Chemicals Ltd, Indian Farmers Fertiliser Cooperative Limited, Grupa Azoty S.A. (Compo Expert), Deepak Fertilizers & Petrochemicals Corporation Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Micronutrient Fertilizer Market Shifts & Advancements
Formulation chemistry and application hardware are converging to reduce per-dose costs while regulatory pressure on input quality tightens compliance thresholds across the value chain.
Nano-encapsulation technology is electrifying micronutrient delivery economics by embedding zinc and iron particles in biodegradable polymer matrices. Vegetable exporters in Gujarat and Maharashtra are adopting these grades at twice the pace of cereal growers. The technology is electrifying premium positioning in export-oriented supply chains while compressing margins on conventional sulfate powders.
The Fertiliser Control Order amendments under the Ministry of Agriculture now mandate third-party BIS certification for all imported chelated compounds. This regulatory tightening has disqualified seventeen unregistered blenders from Maharashtra and Karnataka distribution channels. Foliar-grade specialty manufacturers face the steepest compliance timeline compression as state enforcement intensifies ahead of kharif planting windows.
Farmer buying patterns are fragmenting across channel types as agri-input e-commerce platforms aggregate smallholder demand for knapsack-compatible sachet packs. Traditional district-level stockists in Tamil Nadu and Telangana are responding with doorstep delivery and credit bundling. This behavioral shift is most visible among horticulture growers in peri-urban Bengaluru and Pune corridors where smartphone penetration exceeds rural averages by forty percentage points.
India Micronutrient Fertilizer Market Segmentation
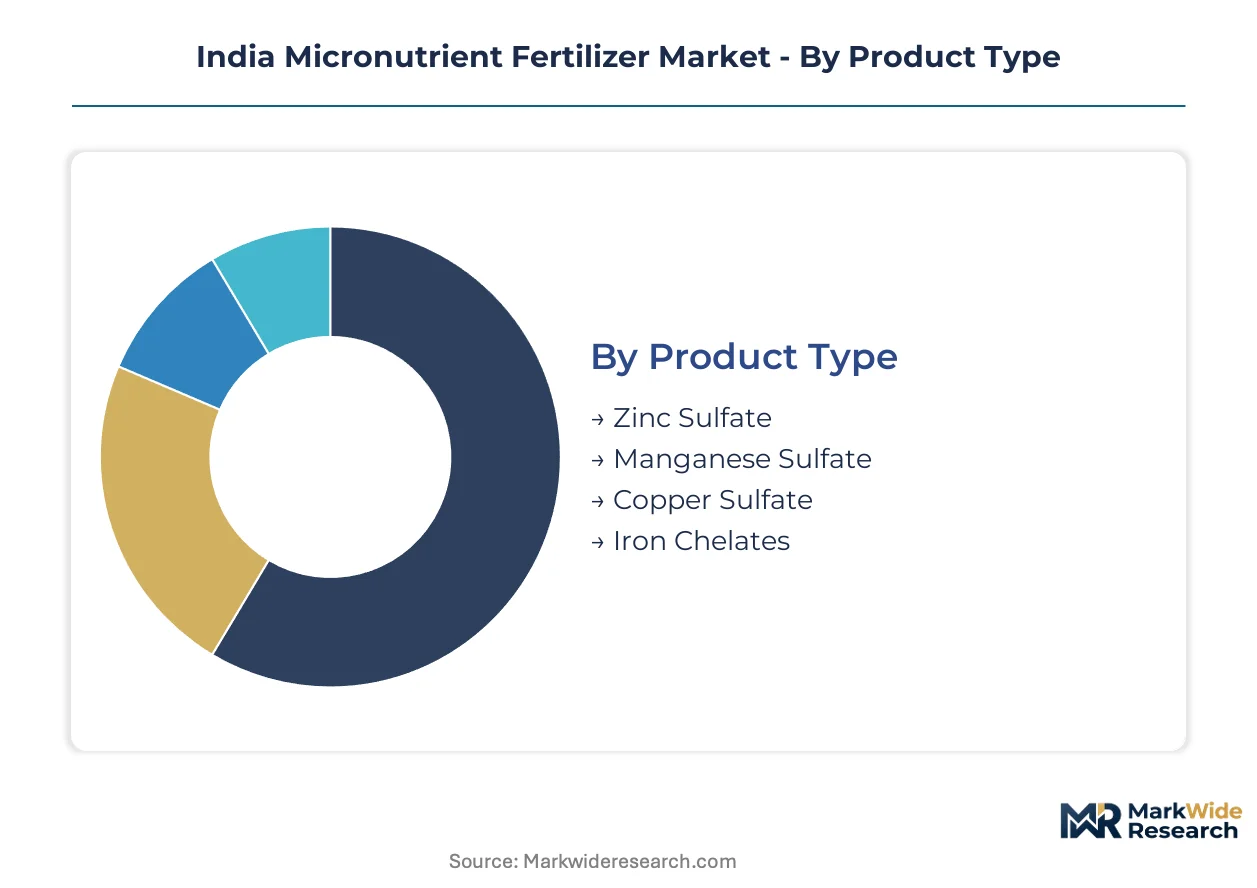
Segmentation in India's micronutrient fertilizer market reveals how procurement patterns fragment across application economics, crop value tiers, and farm scale. Understanding these divisions exposes where pricing power concentrates and which channels resist commoditization.
Product Type:
Production capacity clusters around sulfuric acid availability, with integrated phosphate manufacturers capturing margin through captive acid supply.
- Zinc Sulfate:Crystalline monohydrate and heptahydrate grades dominate volume, formulated for alkaline soil correction in wheat and rice belts. Punjab and Haryana procurement through Soil Health Card mandates sustains offtake despite repeated application requirements.
- Iron Chelates:EDTA and EDDHA-chelated formulations command premium positioning for foliar programs in protected cultivation. Maharashtra polyhouse clusters and Karnataka grape orchards absorb imports despite currency exposure on Chinese chelating agents.
- Manganese Sulfate:Powder and granular variants address deficiency in tea estates and soybean belts.
- Copper Sulfate:Fungicidal dual-use applications in citrus and vegetable farms limit pure nutrient positioning.
Today's leader: Zinc Sulfate. Tomorrow's challenger: Iron Chelates.
Application Method:
Equipment ownership patterns determine method selection, with capital investment thresholds filtering smallholders toward lower-cost options.
- Foliar Spray:Knapsack sprayer compatibility enables targeted intervention during critical growth stages without irrigation infrastructure. Smallholder adoption accelerates fastest in Tamil Nadu and Telangana where agri-input e-commerce aggregates sachet demand.
- Fertigation:Water-soluble grades require drip network compatibility, concentrating demand in Gujarat and Maharashtra where precision irrigation penetration exceeds national averages. Working capital intensity favors commercial growers with credit access.
- Soil Application:Broadcast and banding techniques persist in cereal belts with legacy flood irrigation.
- Seed Treatment:On-farm pelleting and commercial coating services address establishment-phase deficiencies in pulses and oilseeds.
Fertigation climbs fastest where drip networks expand; foliar spray retains volume anchor through equipment accessibility.
Crop Type:
Value per hectare dictates formulation grade tolerance, with export orientation amplifying micronutrient investment recovery.
- Vegetables:Protected cultivation and open-field export crops in Nashik and Pune corridors sustain chelated iron and specialty boron offtake. Contract farming arrangements with processing exporters standardize input specifications.
- Fruits:Grape, pomegranate, and mango orchards in Maharashtra and Karnataka deploy precision foliar programs to meet residue standards in European and Middle Eastern export channels.
- Cereals:Wheat and rice procurement through minimum support price mechanisms constrains input budgets, favoring zinc sulfate over chelated alternatives.
- Pulses:Molybdenum and boron requirements for nitrogen fixation remain underpenetrated outside Madhya Pradesh and Rajasthan commercial clusters.
Vegetables sustain premium grade absorption; cereals lock volume leadership through hectare scale.
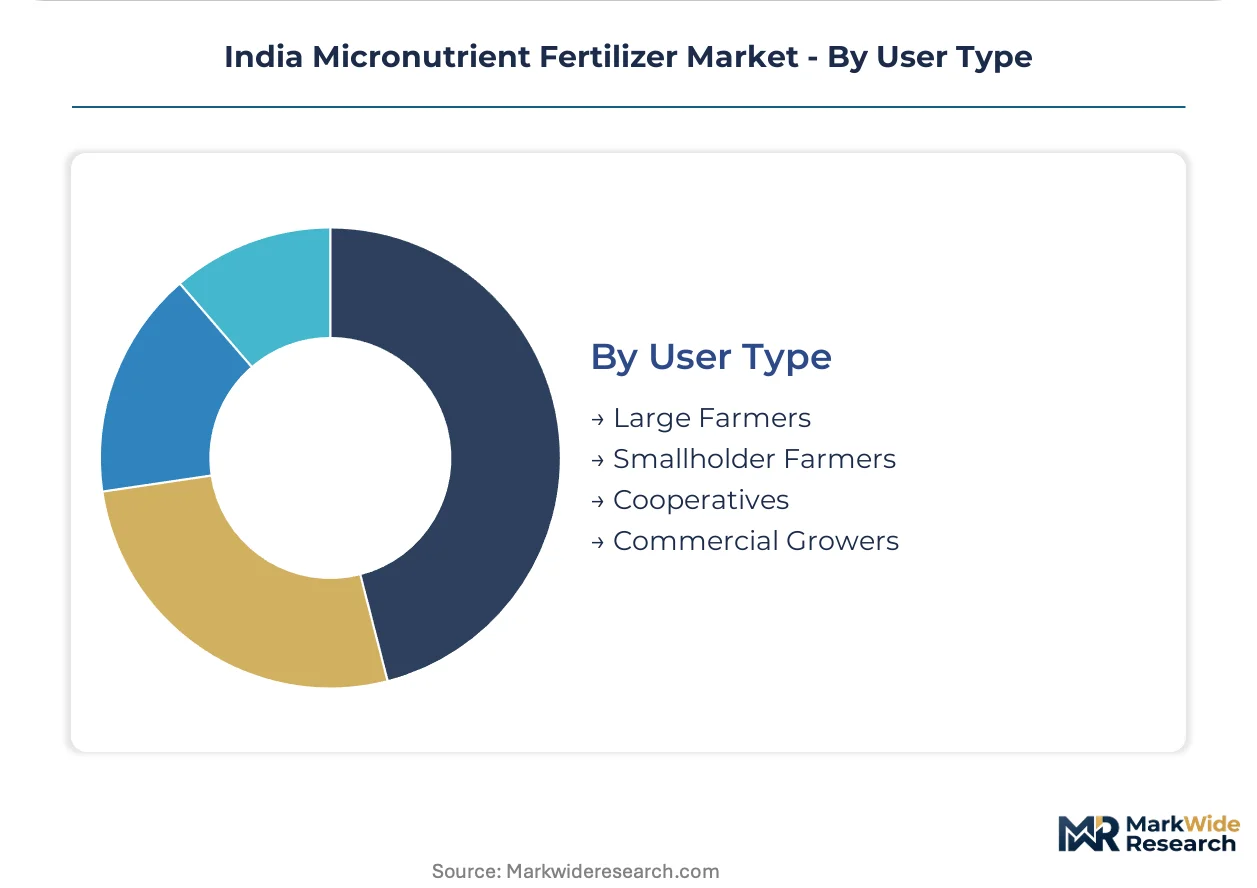
User Type:
Scale determines channel access and credit terms, fragmenting procurement between institutional aggregation and direct retail.
- Commercial Growers:Peri-urban horticulture operations around Bengaluru and Hyderabad leverage direct manufacturer relationships for bulk water-soluble procurement, bypassing distributor markups.
- Cooperatives:Maharashtra and Gujarat sugar and cotton federations aggregate member demand for seasonal micronutrient bundling with macro-fertilizer subsidies.
- Large Farmers:Mechanized holdings in Punjab and Haryana adopt soil testing prescriptions but remain price-sensitive on repeat applications.
- Smallholder Farmers:Fragmented landholdings below two hectares rely on district stockist credit and sachet packaging, with smartphone penetration enabling platform aggregation in southern states.
Commercial growers drive specification intensity; cooperatives concentrate volume through institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Indo-Gangetic plains anchor procurement volume through wheat and rice cultivation belts, while western and southern states concentrate precision agriculture adoption. State-level subsidy regimes and soil health card distribution networks fragment demand patterns across India's federal agricultural governance structure.
Maharashtra
Drip irrigation networks around Nashik and Pune generate concentrated demand for water-soluble micronutrient grades in grape and pomegranate orchards. The state's agricultural department enforces residue compliance protocols for export-oriented horticulture. Polyhouse clusters near Pune absorb chelated iron formulations at rates exceeding national averages for protected cultivation.
Gujarat
Vegetable exporters in the Saurashtra and Kheda belts drive premium-grade zinc and boron uptake for residue-sensitive European markets. The state's groundwater conservation regulations accelerate micro-irrigation adoption across commercial farms. Anand and Vadodara districts host the densest fertigation equipment penetration outside Maharashtra.
Karnataka
Bengaluru's peri-urban horticulture belt sustains specialty manganese and iron chelate demand through year-round vegetable production. The Karnataka Agricultural Prices Commission influences input subsidy bundling for high-value crop growers. Hassan and Chikkaballapur districts concentrate precision farming adoption among contract farming arrangements.
Punjab
Soil Health Card mandates drive zinc sulfate procurement across wheat and rice rotations despite alkaline soil lock-up challenges. The state's agricultural university extension network prescribes repeat application protocols for micronutrient-deficient districts. Ludhiana and Patiala districts concentrate cooperative procurement through institutional aggregation channels.
Tamil Nadu
Agri-input e-commerce penetration around Coimbatore and Salem accelerates sachet-pack foliar grade distribution to smallholder vegetable growers. The state's horticulture mission subsidizes protected cultivation infrastructure in the Nilgiris and Krishnagiri belts. Drip network expansion in Cauvery delta districts concentrates water-soluble micronutrient demand among sugarcane and banana cooperatives.
India Micronutrient Fertilizer Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution reach, producing a tiered structure where integrated phosphate manufacturers hold cost advantages in sulfate grades while specialty importers dominate chelated segments. Domestic cooperatives aggregate smallholder volume through subsidy-linked procurement, and regional blenders exploit state-level regulatory familiarity to defend channel positions. Capacity expansion in western coastal corridors and backward integration into sulfuric acid supply represent the dominant competitive vectors reshaping procurement economics.
Among domestic integrated manufacturers, Coromandel International Ltd anchors eastern and southern distribution through coastal manufacturing positioning, while Zuari Agro Chemicals Ltd exemplifies west coast phosphate-micronutrient complex integration. Haifa Group occupies the specialty water-soluble tier for protected cultivation channels. These three entities represent distinct archetypes: coastal-integrated domestic major, west coast chemical complex operator, and import-dependent specialty formulator.
| Leading Market Players |
|---|
| Zuari Agro Chemicals Ltd |
| Mangalore Chemicals & Fertilizers Ltd |
| Coromandel International Ltd |
| Haifa Group |
| Yara Fertilisers India Pvt Ltd |
| Chambal Fertilizers & Chemicals Ltd |
| Indian Farmers Fertiliser Cooperative Limited |
| Grupa Azoty S.A. (Compo Expert) |
| Deepak Fertilizers & Petrochemicals Corporation Ltd |
| Others |
Supply & Pricing Matrix
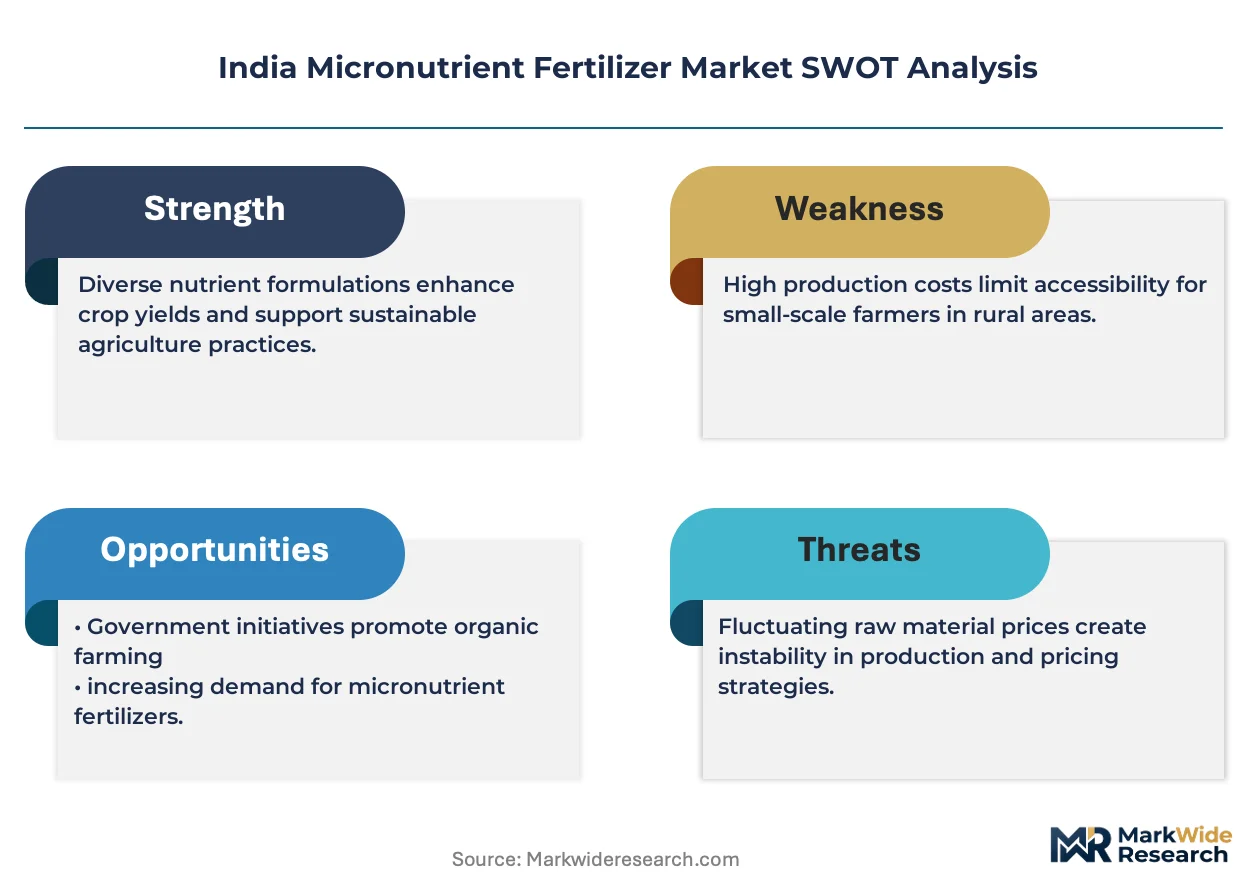
Family-owned mid-cap blenders operating across Maharashtra and Gujarat exercise disciplined pricing through captive sulfuric acid arrangements and long-term offtake contracts with phosphate manufacturers. Their ownership structure insulates working capital cycles from quarterly earnings pressure, enabling sustained investment in BIS certification upgrades that smaller informal competitors cannot match.
Pricing Analysis
Input-cost pass-through from Chinese EDTA chelating agent imports and domestic sulfuric acid supply contracts shapes pricing stratification across zinc sulfate, iron chelate, and specialty water-soluble grades. Three-tier pricing separates premium EDTA-chelated formulations for export horticulture from standard zinc sulfate for cereal belts and economy-grade mineral salts for subsistence growers. Cost compression in the standard tier is intensifying because integrated phosphate manufacturers leverage captive acid supply to undercut standalone blenders. Smallholder farmers in Bihar and eastern Uttar Pradesh exhibit highest price sensitivity, while commercial grape and pomegranate exporters in Nashik absorb premium-grade markups without volume elasticity.
Supply Chain Analysis
Dual-sourcing requirements mandated by state agricultural departments and export processors force blenders to qualify multiple EDTA suppliers from China and domestic sulfuric acid producers from Gujarat and Odisha. Geographic supply concentration centers on China's organic chelating agent manufacturers, India's integrated phosphate complexes along the western coast, and specialty water-soluble formulators in Israel and Europe. Raw material dependencies rest on imported EDTA and EDDHA ligands, sulfuric acid from phosphoric acid manufacturers, and zinc concentrate from Hindustan Zinc's Rajasthan mines. Single-source vulnerability on Chinese chelating agents exposes blenders to shipping disruption and currency fluctuation. Distribution runs through state-level agricultural department subsidy channels, cooperative procurement federations, and agri-input e-commerce platforms aggregating smallholder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through nano-encapsulation technology adoption and chelated-grade substitution in export horticulture, compressing per-dose costs while sustaining premium positioning.
For Market Incumbents: Anchor eastern and southern distribution corridors through backward integration into sulfuric acid supply and coastal manufacturing positioning that matches Coromandel International's footprint. Defend against nano-urea displacement by bundling micronutrient sachets with knapsack sprayer financing for smallholders. Prioritize BIS certification investment ahead of Fertiliser Control Order enforcement intensification. For New Entrants and Emerging Players: Capture Assam and Tripura tea estate demand for boron and manganese foliar programs, the most penetrable white-space outside saturated western markets. Target drone-based aerial application services in flood-prone Bihar rice belts through Kisan drone aggregator partnerships. Pursue white-label manufacturing for agri-input e-commerce platforms seeking sachet-pack foliar grades. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blenders with state-level regulatory familiarity but lacking integrated acid supply. Long-term viability favors acquisition targets with established BIS certification and existing relationships with Maharashtra and Gujarat cooperative federations. Watch nutrient-based subsidy regime integration as the signal for working capital cycle compression and distributor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive acid supply from phosphoric acid manufacturers locks in margin against standalone blenders. |
| Nano-Encapsulation Technology Licensing | Biodegradable polymer matrix embedding reduces leaching losses for Gujarat vegetable exporters. |
| BIS Certification Pre-Positioning | Third-party quality certification ahead of Fertiliser Control Order amendments disqualifies unregistered competitors. |
| Drone Application Service Partnership | Kisan drone aggregator alliances enable aerial micronutrient delivery in flood-prone eastern rice belts. |
| E-Commerce Platform White-Label Supply | Sachet-pack foliar grade manufacturing for Tamil Nadu and Telangana agri-input platforms aggregates fragmented smallholder demand. |
Research Methodology
Direct dialogue with fertilizer plant managers, state agricultural department procurement officers, cooperative federation agronomists, and agri-input e-commerce platform category heads grounded qualitative insights in operational reality. Secondary validation drew from Fertiliser Control Order amendments, BIS certification registries, Soil Health Card distribution databases, and PLI scheme beneficiary disclosures. Bottom-up triangulation across district-level stockist interviews and top-down reconciliation with state subsidy allocation records ensured demand estimation integrity.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between drip irrigation expansion rates, nano-urea adoption curves, and chelated-grade substitution elasticities in export horticulture. The analytical framework incorporated product type, application method, crop value tier, and farm scale as core segmentation dimensions. CAGRs emerged from iterative reconciliation of state-level agricultural department procurement forecasts with manufacturer capacity expansion announcements and import dependency ratio shifts.
PLI scheme disbursement delays, nano-urea mandate acceleration timelines, and Chinese EDTA supply disruption are the dominant revision risks to baseline projections. Forecasts embed assumptions regarding state subsidy continuity and Fertiliser Control Order enforcement intensity. Deviation in nutrient-based subsidy regime implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
South America Fertilizers Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Europe Micronutrient Fertilizer Market