
 Global Bioburden Testing Market | 2026-2036
Global Bioburden Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioburden Testing Market Foresight
Aftermarket service revenue for bioburden testing equipment is rewriting how vendors capture lifetime value from installed bases. Charles River Laboratories International, Inc. leverages its global lab network to anchor recurring validation contracts across pharmaceutical clients. Merck KGaA sustains competitive position through captive microbial culture media production that reduces third-party dependency. Thermo Fisher Scientific Inc. dominates the rapid detection systems segment with integrated platform-and-consumable bundling.
Bioburden testing quantifies viable microbial populations on surfaces, in raw materials, or within finished products using culture-based enumeration, ATP bioluminescence, or PCR amplification methods, with sensitivity thresholds typically spanning 10 to 100 colony-forming units per unit volume. Its primary commercial purpose is to validate sterilization efficacy and release batches for pharmaceutical, medical device, and food applications. Rapid detection systems command premium positioning as manufacturers seek same-day batch release, while ATP bioluminescence technology occupies the fastest-expanding technology tier due to its elimination of incubation periods. Contract research organizations represent the most concentrated end-user channel, absorbing disproportionate volumes from small and mid-sized biotech firms lacking in-house microbiology infrastructure.
FDA sterility testing guidelines, EMA good manufacturing practice annexes, and ISO 11737-1 standards collectively mandate bioburden enumeration as a precondition for terminal sterilization validation and ethylene oxide cycle qualification, creating non-negotiable demand floors. The EU Medical Device Regulation intensifies documentation burdens for manufacturers importing into Europe, shifting procurement toward testing partners with notified body relationships. Stakeholders must monitor how FDA's evolving guidance on rapid microbiological methods reshapes acceptable technology portfolios and capital allocation timelines.
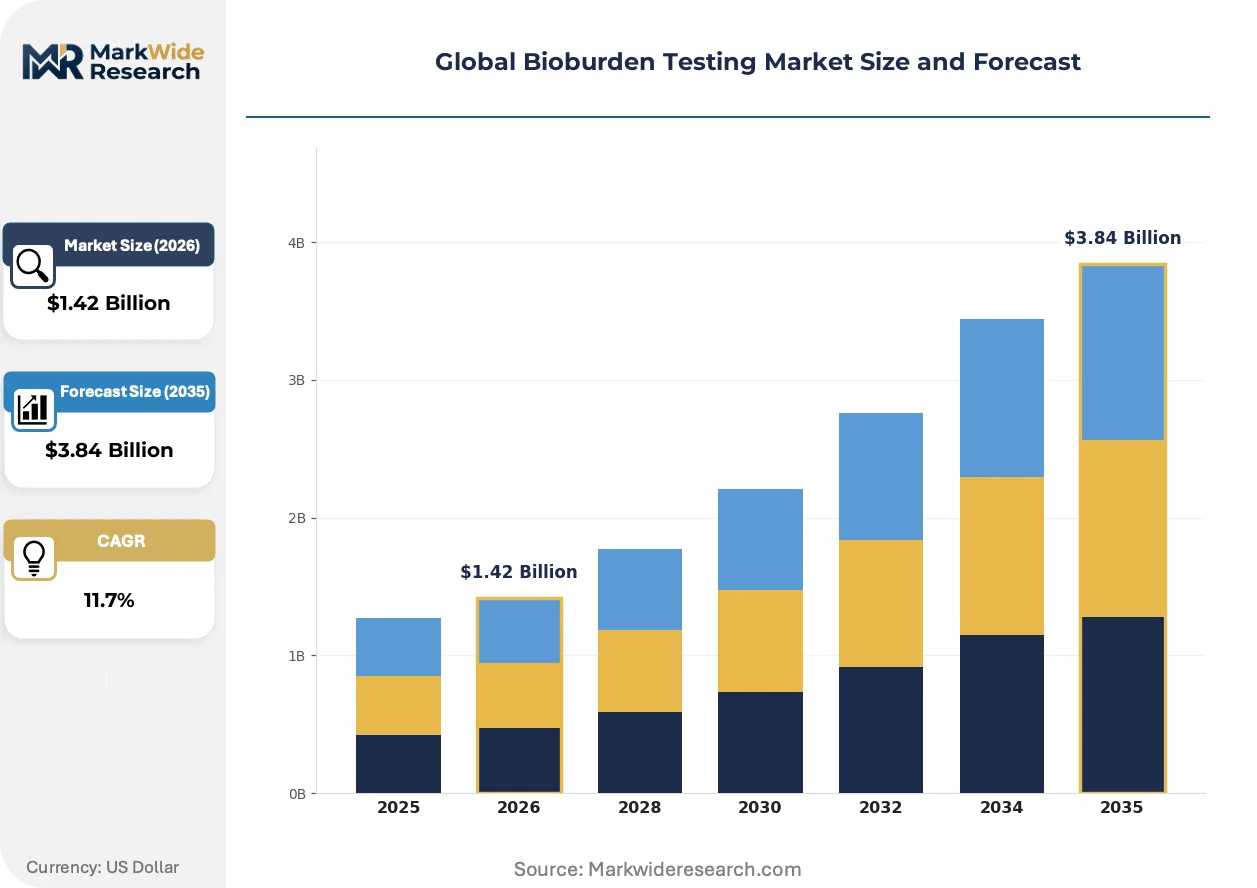
Market Dynamics
Contract research organizations are consolidating testing volumes as small and mid-sized biotech firms abandon in-house microbiology infrastructure, compressing demand into fewer high-throughput facilities near FDA and EMA inspection hubs.
Growth Catalysts
- FDA sterility guidance evolution:The agency's expanding acceptance of rapid microbiological methods validates ATP bioluminescence and PCR platforms for batch release, pulling pharmaceutical manufacturers toward same-day testing capabilities.
- EU Medical Device Regulation documentation mandates:MDR intensifies bioburden documentation burdens for European market entry, forcing manufacturers toward testing partners with notified body relationships.
- Ethylene oxide cycle qualification:ISO 11737-1 mandates bioburden enumeration as precondition for terminal sterilization validation, creating non-negotiable demand floors across medical device production.
Market Restraints
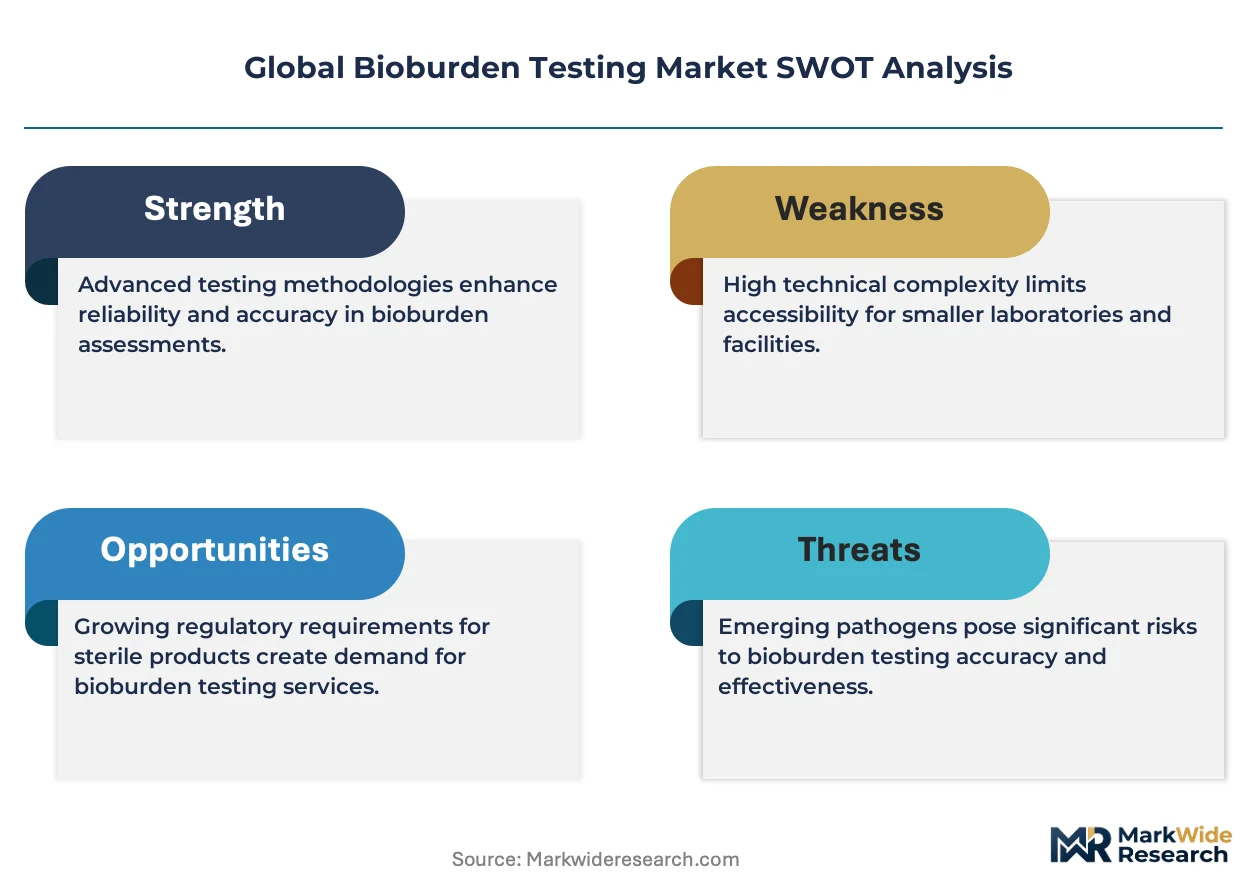
- Culture media supply concentration:Captive production of microbial growth media by integrated vendors like Merck KGaA limits third-party supplier options, constraining price competition for standalone testing labs.
- Equipment capex intensity:Rapid detection systems require substantial capital deployment, freezing out smaller contract labs from premium same-day release segments.
- Validation timeline friction:FDA method equivalence studies for alternative microbiological techniques extend qualification periods, delaying technology transitions even where guidance permits.
Strategic Opportunities
- India CDSCO alignment:India's pharmaceutical regulator is harmonizing with ICH microbiological standards, opening validation service opportunities for testing labs with US or EU accreditation.
- Cell and gene therapy applications:Autologous therapy manufacturing requires patient-specific bioburden monitoring at multiple production stages, expanding addressable testing points per therapeutic batch.
- Platform-and-consumable bundling:Integrated rapid detection systems with locked reagent contracts capture lifetime value from installed bases, mirroring Thermo Fisher Scientific's consumable-anchored model.
Industry Challenges
- Microbiology talent scarcity:Skilled aseptic technique specialists and rapid method validation scientists concentrate in established pharma hubs, constraining lab expansion into secondary markets.
- Legacy system integration:Paper-based colony counting workflows persist in older facilities, creating data integrity gaps during FDA inspections and delaying LIMS connectivity projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioburden Testing Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.84 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Culture Media, Sterility Testing Kits, Rapid Detection Systems, Membrane Filters, Automated Bioburden Testers Application: Pharmaceutical Manufacturing, Medical Device Sterilization, Cosmetic Production, Food Safety, Environmental Monitoring End User: Contract Research Organizations, Quality Control Labs, Biotechnology Firms, Diagnostic Centers, Academic Institutions Technology: ATP Bioluminescence, Polymerase Chain Reaction, Impedance Microbiology, Immunoassays, Fluorescence Microscopy |
| Companies Covered | Charles River Laboratories International, Inc., Merck KGaA, SGS SA, WuXi AppTec, Thermo Fisher Scientific Inc., BD, Nelson Laboratories, LLC, North American Science Associates, LLC, BIOMÉRIEUX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioburden Testing Market Shifts & Advancements
ATP bioluminescence is compressing incubation-dependent workflows, while regulatory harmonization across FDA, EMA, and PMDA reshapes acceptable technology portfolios. Procurement behavior is fragmenting as large pharma insources critical testing while mid-tier buyers consolidate through contract research networks.
ATP bioluminescence technology eliminates the 24- to 72-hour incubation periods required by culture-based enumeration, enabling same-day batch release decisions. Large pharmaceutical manufacturers with high-throughput sterilization operations are adopting these platforms fastest, displacing traditional colony-forming unit counts in release protocols. This incubation collapse is compressing working capital cycles and reducing quarantine inventory holding costs.
EMA's Annex 1 revision on sterile manufacturing intensifies environmental monitoring requirements, mandating more frequent bioburden sampling across Grade A and B cleanroom zones. European pharmaceutical and medical device manufacturers are expanding validation contracts to cover continuous monitoring rather than batch-end testing. German production hubs near Frankfurt and Munich are experiencing the steepest procurement acceleration as notified body inspection intensity rises.
Large pharmaceutical manufacturers are fragmenting their testing supplier bases, splitting routine bioburden monitoring between internal labs and strategic contract partners based on therapeutic risk classification. Mid-sized biotech firms lacking microbiology infrastructure are consolidating volumes through preferred provider agreements with Charles River Laboratories and similar networks. This bifurcation is most visible in the United States, where FDA inspection frequency differences between internal and outsourced testing drive site-selection decisions.
Global Bioburden Testing Market Segmentation
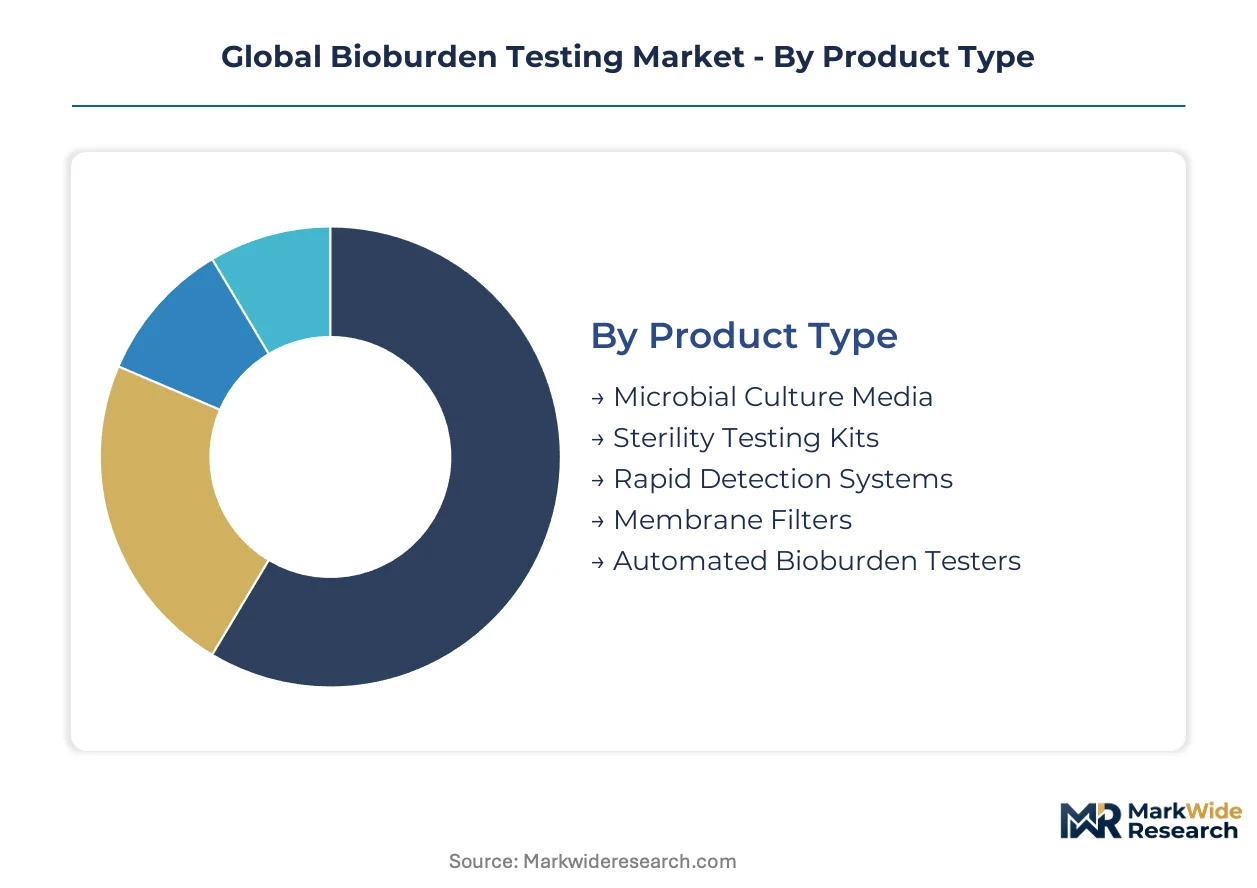
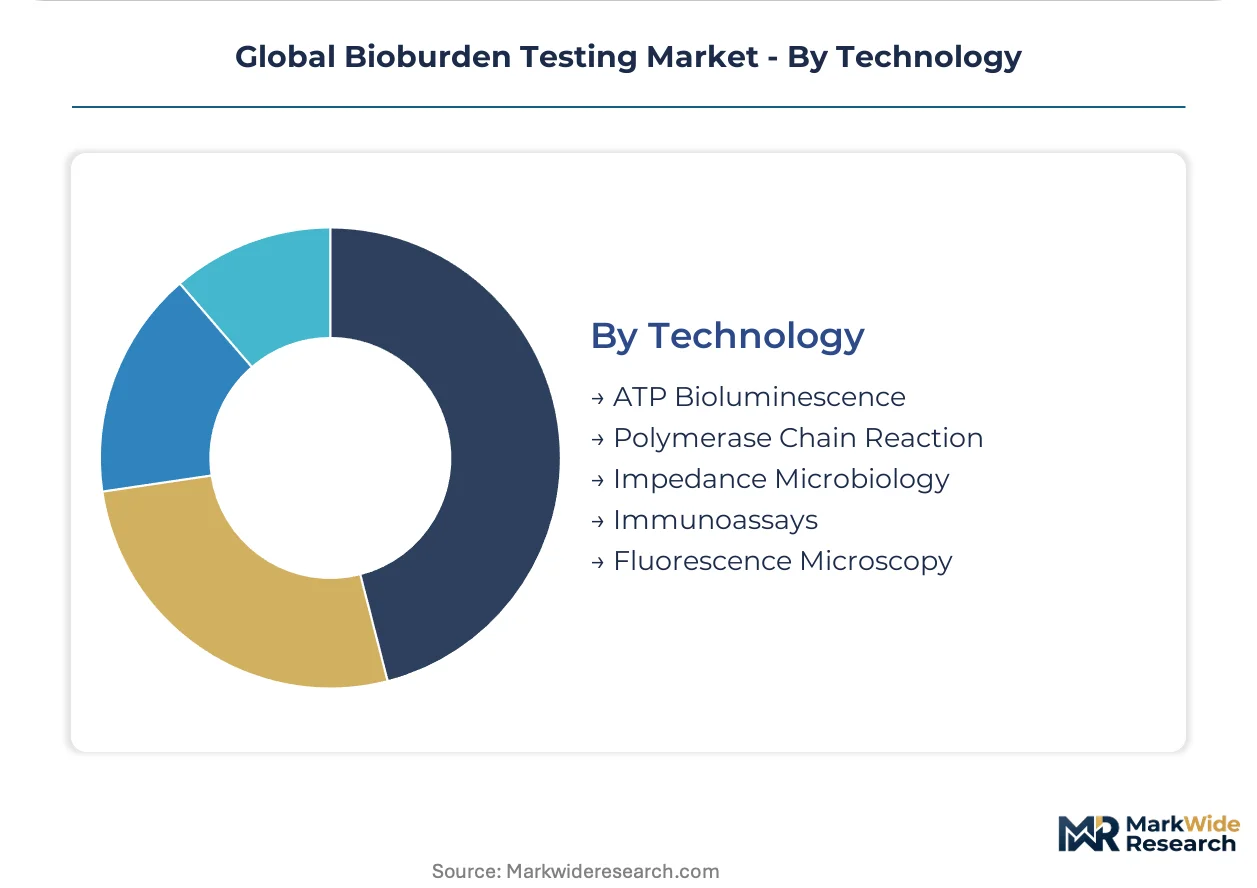
Bioburden testing demand fragments across product formats, end-user capabilities, and regulatory compliance tiers. Each segment carries distinct margin profiles and technology substitution risks that reshape vendor positioning.
Product Type:
Mature consumables dominate procurement volumes while emerging platforms capture capital expenditure growth.
- Microbial Culture Media:Dehydrated and ready-to-use formulations support colony-forming unit enumeration across pharmaceutical and medical device applications. Demand concentrates in Germany and the United States where contract testing labs maintain high-throughput sterility validation operations. Captive production by integrated chemical suppliers constrains third-party pricing flexibility.
- Rapid Detection Systems:Integrated ATP bioluminescence and PCR platforms eliminate incubation-dependent workflows for same-day batch release decisions. Large pharmaceutical manufacturers in the United States deploy these systems fastest to compress working capital cycles and reduce quarantine inventory holding costs.
- Sterility Testing Kits:Pre-validated reagent sets streamline regulatory compliance for mid-sized biotechnology firms lacking internal method development capabilities.
- Membrane Filters:Hydrophobic and hydrophilic membrane configurations enable bioburden capture from liquid samples per ISO 11737-1 protocols.
- Automated Bioburden Testers:Robotic liquid handling and colony counting systems address labor scarcity in high-volume contract testing facilities.
Microbial culture media retains volume leadership; rapid detection systems hold the steepest expansion curve.
Application:
Regulatory stringency tiers separate high-compliance pharmaceutical segments from faster-turn consumer product categories.
- Pharmaceutical Manufacturing:Sterile drug production mandates bioburden enumeration as precondition for terminal sterilization validation under FDA and EMA guidelines. German and United States production hubs absorb disproportionate testing volumes as notified body inspection intensity rises.
- Medical Device Sterilization:Ethylene oxide and radiation cycle qualification requires ISO 11737-1 compliant bioburden monitoring across implantable and invasive device categories. European manufacturers face intensified documentation burdens under EU Medical Device Regulation.
- Food Safety:Process validation and environmental monitoring applications drive ATP bioluminescence adoption for same-day hygiene verification.
- Cosmetic Production:Preservative efficacy testing and raw material qualification create recurring consumable demand.
- Environmental Monitoring:Cleanroom and water system surveillance expands under revised EMA Annex 1 sterile manufacturing requirements.
Pharmaceutical manufacturing commands the highest testing spend per facility; environmental monitoring is climbing fastest on regulatory sampling frequency mandates.
End User:
Outsourcing depth varies by organizational scale and therapeutic risk classification.
- Contract Research Organizations:High-throughput facilities near FDA and EMA inspection hubs consolidate volumes from small and mid-sized biotechnology firms abandoning in-house microbiology infrastructure. Charles River Laboratories and similar networks anchor recurring validation contracts across pharmaceutical clients.
- Quality Control Labs:Internal testing operations at large pharmaceutical manufacturers handle critical therapeutic categories while outsourcing routine monitoring.
- Biotechnology Firms:Cell and gene therapy manufacturers require patient-specific bioburden monitoring at multiple autologous production stages.
- Diagnostic Centers:Clinical laboratory settings deploy rapid detection for sterile fluid and tissue sample screening.
- Academic Institutions:Research applications drive specialized media and fluorescence microscopy procurement for method development studies.
Contract research organizations capture the largest outsourced volume; biotechnology firms are expanding testing points fastest on autologous therapy manufacturing complexity.
Technology:
Incubation elimination separates premium rapid platforms from established culture-dependent methods.
- ATP Bioluminescence:Enzymatic detection of adenosine triphosphate enables microbial quantification without 24- to 72-hour incubation periods. Large pharmaceutical sterilization operations in the United States adopt these platforms fastest for same-day batch release.
- Polymerase Chain Reaction:Nucleic acid amplification delivers species-specific identification and rapid enumeration for contamination source tracing.
- Impedance Microbiology:Electrical conductivity changes detect microbial metabolism in real-time for intermediate-speed screening applications.
- Immunoassays:Antibody-based detection targets specific pathogen classes in environmental and raw material monitoring.
- Fluorescence Microscopy:Direct visualization methods support research applications and reference method correlations for rapid technology validation.
ATP bioluminescence leads technology substitution; polymerase chain reaction is gaining fastest on identification specificity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across testing markets. Contract research organizations in India negotiate aggressively on consumable costs, while German pharmaceutical manufacturers absorb premium rapid detection pricing to compress batch release timelines.
United States
FDA inspection intensity and same-day batch release mandates drive rapid detection adoption. The agency's evolving guidance on rapid microbiological methods validates ATP bioluminescence platforms for pharmaceutical release protocols. Boston and San Diego biotech clusters concentrate demand as cell and gene therapy manufacturers expand patient-specific monitoring requirements.
Germany
EMA Annex 1 sterile manufacturing revisions intensify environmental monitoring frequency across Grade A and B cleanrooms. Notified body inspection intensity rises near Frankfurt and Munich production hubs, expanding validation contract volumes. Captive microbial culture media production by integrated chemical suppliers limits third-party pricing flexibility for standalone testing labs.
India
CDSCO harmonization with ICH microbiological standards opens validation service opportunities for labs with US or EU accreditation. Contract research organizations absorb volumes from domestic pharmaceutical exporters seeking FDA-compliant documentation. Hyderabad and Mumbai testing clusters expand capacity to serve small and mid-sized biotech firms abandoning in-house microbiology infrastructure.
Japan
PMDA alignment with FDA rapid method validation protocols accelerates ATP bioluminescence platform qualification. Pharmaceutical manufacturers near Osaka and Tokyo deploy same-day testing to reduce quarantine inventory holding costs. Domestic equipment vendors face pricing pressure from integrated global suppliers bundling platforms with locked reagent contracts.
Switzerland
Swissmedic oversight of sterile drug manufacturing maintains stringent bioburden documentation requirements for export-oriented pharmaceutical production. Basel and Zurich testing facilities serve as European validation hubs for multinational manufacturers. Premium rapid detection system penetration exceeds regional averages due to high-value therapeutic batch economics.
Global Bioburden Testing Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Integrated life science conglomerates with captive consumable production anchor premium rapid detection segments, while specialized contract testing networks consolidate outsourced volumes from infrastructure-constrained biotech firms. Three archetypes dominate: platform-and-consumable bundlers, high-throughput validation service networks, and captive media producers. Competitive moves center on M&A to acquire notified body relationships and capacity expansion near FDA and EMA inspection hubs.
Within the contract testing network tier, Charles River Laboratories International, Inc. and WuXi AppTec exemplify geographic coverage strategies that consolidate fragmented biotech demand. Among integrated conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions defined by consumable-anchored business models that capture lifetime value from installed rapid detection bases. These archetypes represent contrasting paths to margin defense: one through service density and regulatory proximity, the other through reagent lock-in and platform substitution resistance.
| Leading Market Players |
|---|
| Charles River Laboratories International, Inc. |
| Merck KGaA |
| SGS SA |
| WuXi AppTec |
| Thermo Fisher Scientific Inc. |
| BD |
| Nelson Laboratories, LLC |
| North American Science Associates, LLC |
| BIOMÉRIEUX |
| Others |
Supply & Pricing Matrix
Overcapacity in Indian contract testing clusters compresses consumable pricing for standalone labs while tightening margins on rapid detection equipment in German pharmaceutical hubs. Utilization differentials drive suppliers toward reagent-locked bundling in premium markets and aggressive consumable discounting in price-sensitive procurement channels.
Pricing Analysis
Aftermarket service revenue from validation contracts and extended maintenance agreements drives lifetime value capture for rapid detection platform vendors. Three-tier pricing structure across premium rapid-detection platforms, standard culture-based systems, and economy consumable bundles segments buyer tiers. Pricing pressure stems from CDSCO-aligned Indian labs negotiating aggressive consumable discounts for high-volume sterility testing. Contract research organizations in Hyderabad and Mumbai exhibit highest price sensitivity; Swiss pharmaceutical manufacturers near Basel absorb premium rapid-detection pricing to enable same-day batch release.
Supply Chain Analysis
Extended payment terms from German pharmaceutical manufacturers to culture media suppliers stretch working capital cycles for standalone testing labs. Captive production in Germany and the United States anchors supply for dehydrated and ready-to-use microbial formulations; India and China supply membrane filtration components and automated liquid handling subassemblies. Raw material dependencies center on specialized peptone sources, selective antibiotic supplements, and fluorescence detection reagents. Single-source vulnerability concentrates in ATP bioluminescence reagent chemistries locked to specific platform ecosystems. Distribution runs through direct vendor relationships with large pharmaceutical manufacturers and group purchasing organizations serving contract research networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mid-sized biotechnology firms abandoning in-house microbiology infrastructure, creating niches for validation service networks with regulatory proximity advantages.
For Market Incumbents: Build switching-cost moats through reagent-locked platform ecosystems that tether consumable procurement to installed rapid detection bases. Consolidate notified body relationships through targeted capacity expansion near Frankfurt and Munich inspection hubs. Defend against ATP bioluminescence substitution by embedding LIMS connectivity and data integrity compliance into service contracts.
For New Entrants and Emerging Players: Build out cell and gene therapy-specific bioburden monitoring capabilities targeting patient-specific autologous production stages. Penetrate the environmental monitoring segment fastest by aligning with EMA Annex 1 sampling frequency mandates. Pursue go-to-market partnerships with CDSCO-accredited Indian labs seeking FDA-equivalent validation documentation for domestic pharmaceutical exporters.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract testing networks anchoring multi-year validation contracts across pharmaceutical client portfolios. Long-term viability favors service density over equipment manufacturing given consumable-anchored margin compression from integrated conglomerates. Target acquisition archetype: regional validation labs with established FDA or EMA inspection relationships and underutilized rapid detection capacity. Monitor FDA guidance evolution on rapid microbiological methods as inflection signal for technology portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Acquisition | Secures EU MDR documentation pathways for medical device sterilization validation contracts. |
| Platform-and-Consumable Bundling | Mirrors Thermo Fisher's reagent-lock model to capture lifetime value from rapid detection installations. |
| Cell Therapy Monitoring Specialization | Expands addressable testing points per autologous therapeutic batch across multiple production stages. |
| CDSCO Accreditation Investment | Opens validation service opportunities for Indian pharmaceutical exporters seeking FDA-compliant documentation. |
| LIMS Integration Capability Buildout | Resolves data integrity gaps during FDA inspections for legacy paper-based colony counting workflows. |
Research Methodology
Desk research of FDA guidance documents, EMA Annex 1 revisions, ISO 11737-1 standards, and pharmaceutical regulatory filings preceded structured interviews with quality control directors, contract testing lab operations managers, rapid detection platform engineers, and sterility validation specialists. Secondary validation drew from SEC 10-K disclosures of listed life science conglomerates, notified body inspection databases, and pharmaceutical manufacturing capacity reports. Bottom-up testing volume estimates triangulated with top-down market sizing across product type, application, and end-user segments.
Assumptions held regulatory acceptance trajectories for ATP bioluminescence and PCR methods constant while varying pharmaceutical production growth rates and outsourcing depth across geographies. Segmentation modeling incorporated technology substitution curves, end-user capability tiers, and regional regulatory cluster stringency differentials. CAGRs derived from regression analysis of historical testing volume expansion correlated with sterilization operation growth and environmental monitoring mandate intensification. Forecast inputs included ethylene oxide cycle qualification volumes and cell therapy manufacturing facility buildout pipelines.
Practitioners should monitor FDA rapid microbiological methods guidance evolution, EMA Annex 1 enforcement intensity, and CDSCO-ICH harmonization progress for early signals. Forecasts reflect assumptions regarding regulatory acceptance timelines and outsourcing continuation patterns. Macroeconomic contraction affecting pharmaceutical capital expenditure, regulatory reversal on rapid method equivalence, or technological disruption in sterility assurance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Home Menopause Testing Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Fecal Occult Testing Market
Testing Services
Monkeypox Testing Market
Testing Services
Europe Newborn Screening Market
Testing Services
Zika Virus Testing Market
Testing Services
Retrovirus Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
Global Sterility Testing Market
Testing Services
Toxicology Testing Services Market