
 Pathogen Detection Market | 2026-2036
Pathogen Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Pathogen Detection Market Insights
Microbiology technologist shortages across reference laboratories is unwinding testing throughput and forcing automation investments. Thermo Fisher Scientific leverages its end-to-end PCR platform portfolio to anchor clinical diagnostics workflows. bioMérieux specializes in blood culture and sepsis detection systems that dominate hospital microbiology departments. QIAGEN competes through sample-to-answer automation that reduces hands-on time for strained laboratory staff.
Pathogen detection encompasses molecular, immunological, and culture-based methods for identifying bacterial, viral, fungal, and parasitic agents in clinical, environmental, and food matrices, with sensitivity thresholds often reaching single-digit colony-forming units per milliliter for regulatory compliance. PCR kits command the largest revenue share among product types due to established reimbursement pathways and reference laboratory adoption. Biosensors represent the fastest-expanding technology segment, driven by point-of-care decentralization and reduced turnaround time requirements. Food safety applications attract intensifying investment as supply chain traceability regulations harden across major economies.
The FDA enforces food safety modernization standards that mandate preventive pathogen controls, while the EPA oversees environmental monitoring protocols for waterborne contaminants. ISO 17025 accreditation requirements shape laboratory competence standards and cross-border test result acceptance. Stakeholders must weigh automation capital deployment against workforce constraints while anticipating how decentralized biosensor networks will redistribute testing economics between centralized laboratories and distributed care settings.
Market Dynamics
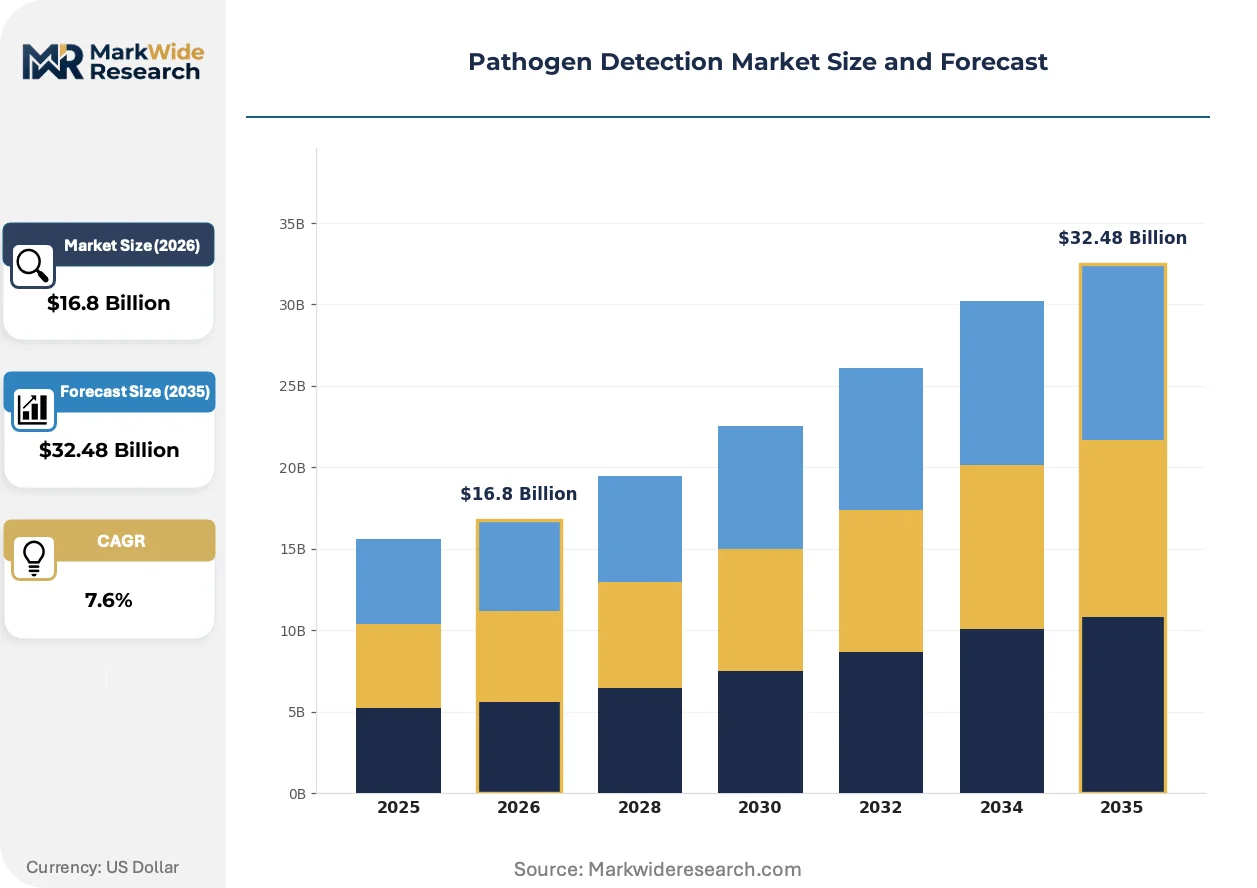
Laboratory automation is compressing turnaround times while antimicrobial resistance surveillance mandates expand testing volumes beyond staffing capacity. The collision between workforce shortages and regulatory testing obligations is restructuring procurement priorities across clinical and food safety applications.
Growth Catalysts
- Food Safety Modernization Act enforcement:The FDA's preventive control mandates require environmental monitoring and finished product testing across domestic and imported food supply chains, expanding contract laboratory service demand.
- Hospital-acquired infection surveillance programs:Medicare reimbursement penalties tied to infection rates compel US health systems to invest in rapid molecular diagnostics for outbreak containment and antibiotic stewardship.
- CRISPR-based detection platforms:Field-deployable gene-editing diagnostics reduce equipment footprint and technical training requirements, opening point-of-care applications in resource-limited settings.
Market Restraints
- Reagent supply concentration:Specialty polymerase and fluorescent probe production concentrates among German and Japanese chemical suppliers, exposing laboratories to allocation risk during demand surges.
- Capital intensity of full automation:Integrated sample-to-answer systems require seven-figure investments that strain independent reference laboratory balance sheets and extend payback periods.
- Culture-based method persistence:Regulatory gold-standard requirements for definitive species identification and antimicrobial susceptibility testing limit molecular method substitution in certain jurisdictions.
Strategic Opportunities
- Decentralized wastewater surveillance networks:Municipal utilities and public health agencies seek continuous pathogen monitoring infrastructure for early epidemic warning, creating recurring consumable revenue streams.
- Indian food export compliance market:FSSAI harmonization with Codex Alimentarius and EU import standards drives domestic laboratory accreditation and testing capability investments.
- Artificial intelligence-assisted image analysis:Machine learning algorithms applied to microscopy and chromatography readouts reduce specialist interpretation burden and enable technician-level operation.
Industry Challenges
- Clinical laboratory scientist pipeline collapse:Training program closures and wage competition from biotechnology sectors shrink qualified personnel availability for complex microbiology workflows.
- Multi-platform integration complexity:Laboratories operate heterogeneous instrument fleets from competing vendors, complicating data standardization and quality management system maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pathogen Detection Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $32.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Kits, Antigen Tests, Sequencing Tools, Sample Preparation Equipment Technology: Microarray, Mass Spectrometry, Nanotechnology, Biosensors Application: Clinical Diagnostics, Environmental Testing, Food Safety, Research Laboratories End User: Hospitals, Diagnostics Laboratories, Food Manufacturers, Research Institutions |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies, Inc., bioMérieux, BD, Danaher Corporation, QIAGEN, Roche Holding AG, Bio-Rad Laboratories, Inc., PerkinElmer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pathogen Detection Market Trends and Innovations
Digital biosensor miniaturization is collapsing the cost and skill barriers that historically confined pathogen testing to centralized laboratories. This technological trajectory is redistributing testing economics toward distributed deployment models.
Loop-mediated isothermal amplification (LAMP) chemistry operates without thermal cycling equipment, enabling battery-powered field instruments for veterinary and environmental applications. Agricultural inspectors and border control agencies in Southeast Asia and Latin America are adopting these platforms for rapid screening decisions. LAMP is supplanting conventional PCR in settings where infrastructure constraints previously excluded molecular diagnostics entirely.
The EPA's revised recreational water quality criteria mandate quantitative microbial risk assessment approaches, requiring more sensitive and specific detection methods than traditional indicator organism culture. Beach monitoring programs and wastewater treatment operators must upgrade analytical capabilities or face enforcement action. This regulatory shift most directly affects coastal states and Great Lakes jurisdictions with concentrated summer tourism exposure.
Subscription-based reagent provisioning is replacing capital-heavy instrument purchases among mid-sized food manufacturers and regional hospital networks. Third-party logistics providers now manage cold-chain inventory and calibration scheduling, converting fixed equipment costs into variable per-test expenses. This model has gained strongest traction in the United Kingdom and Netherlands where laboratory consolidation has concentrated buying power among fewer decision-makers.
Pathogen Detection Market Segmentation
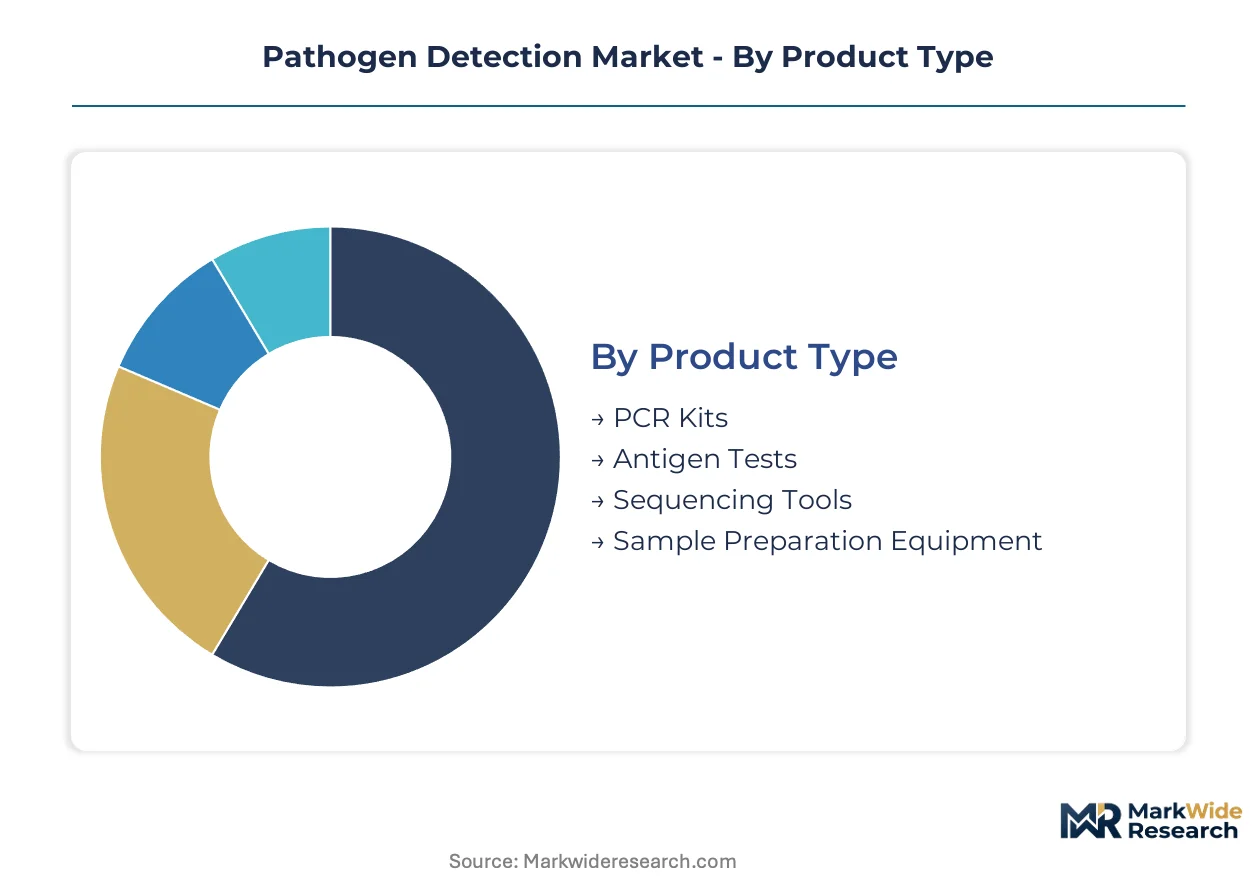
Pathogen detection procurement splits across four critical dimensions that determine regulatory compliance pathways, capital deployment intensity, and operational workflow integration. Each segmentation layer reveals distinct margin profiles and vendor competitive dynamics.
Product Type:
FDA's preventive control mandates and EPA water quality criteria create divergent equipment and consumable requirements across detection workflows.
- PCR Kits:Polymerase chain reaction reagents dominate reference laboratory procurement through established reimbursement codes and antimicrobial resistance surveillance protocols. United States hospital systems sustain volume concentration as Medicare penalty frameworks compel rapid turnaround testing for hospital-acquired infection containment.
- Antigen Tests:Lateral flow and ELISA-based immunoassays deliver point-of-care speed without thermal cycling infrastructure. Border control agencies and agricultural inspectors in Southeast Asia deploy these for field screening where laboratory access remains constrained.
- Sequencing Tools:Next-generation platforms enable outbreak source tracing and resistance gene mapping for public health agencies.
- Sample Preparation Equipment:Automated nucleic acid extraction systems reduce hands-on time for workforce-strained clinical laboratories.
PCR Kits handle the majority of throughput; Antigen Tests are the fastest mover on share.
Technology:
Cost tier differentiation separates capital-intensive centralized platforms from deployable field instruments reshaping testing economics.
- Biosensors:Electrochemical and optical transducers enable continuous monitoring without specialist interpretation. Wastewater surveillance networks across United States municipal utilities adopt these for epidemic early warning, generating recurring consumable revenue streams absent large upfront equipment purchases.
- Mass Spectrometry:MALDI-TOF systems deliver rapid species identification from culture isolates, dominating hospital microbiology departments where definitive antimicrobial susceptibility testing remains regulatory mandated.
- Microarray:High-plex nucleic acid detection supports research and surveillance applications requiring simultaneous pathogen panel screening.
- Nanotechnology:Quantum dot and plasmonic approaches promise single-molecule sensitivity for future point-of-care miniaturization.
Biosensors command premium pricing for distributed deployment; Mass Spectrometry anchors centralized laboratory revenue.
Application:
Customer type concentration varies sharply between mandated regulatory testing and discretionary research expenditure.
- Clinical Diagnostics:Hospital-acquired infection surveillance and sepsis detection drive molecular platform adoption. United States health systems concentrate procurement as CMS reimbursement penalties tied to infection rates compel rapid diagnostic capability investment.
- Food Safety:FDA enforcement of preventive controls across domestic and imported supply chains expands contract laboratory service demand. Food manufacturers face finished product testing obligations that sustain environmental monitoring program spending.
- Environmental Testing:EPA recreational water quality criteria mandate quantitative microbial risk assessment upgrades for beach monitoring programs.
- Research Laboratories:Academic and government institutions support method development and surveillance infrastructure advancement.
Clinical Diagnostics generates the largest absolute revenue; Food Safety is expanding most quickly on regulatory enforcement.
End User:
Volume scale and integration complexity separate institutional purchasers from mid-tier operators seeking variable cost structures.
- Diagnostics Laboratories:Reference and hospital-affiliated labs process high-throughput panels for antimicrobial resistance surveillance and outbreak investigation. United States laboratory consolidation concentrates buying power among fewer decision-makers negotiating subscription-based reagent provisioning models.
- Hospitals:In-house microbiology departments require rapid turnaround for antibiotic stewardship and infection control programs.
- Food Manufacturers:Mid-sized processors seek third-party logistics-managed cold-chain inventory to convert fixed equipment costs into per-test expenses.
- Research Institutions:Academic medical centers and public health agencies support surveillance method validation and platform development.
Diagnostics Laboratories absorb the greatest testing volume; Food Manufacturers are gaining share fastest on compliance mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States procurement channels while German and Japanese chemical suppliers capture reagent premiums, creating an asymmetry that favors instrument manufacturers with captive supply chains over pure-play diagnostics firms.
United States
Hospital-acquired infection surveillance and Medicare reimbursement penalties compel health system investment in rapid molecular platforms. FDA enforcement of Food Safety Modernization Act preventive controls expands contract laboratory demand across domestic and imported food supply chains. The Boston-Cambridge corridor anchors biodefense preparedness procurement and reference laboratory consolidation.
Germany
Specialty polymerase and fluorescent probe production concentrates among chemical suppliers serving European clinical diagnostics networks. EFSA harmonization with Codex Alimentarius standards drives food export compliance testing investments. The Rhine-Main industrial cluster houses precision chemistry manufacturing that underpins PCR reagent supply security.
China
Domestic food safety modernization and environmental water quality monitoring expand municipal testing infrastructure procurement. NMPA regulatory streamlining accelerates molecular diagnostic platform approvals for hospital microbiology departments. The Yangtze River Delta concentration of biotechnology manufacturing supports reagent localization initiatives.
India
FSSAI alignment with EU import standards and Codex Alimentarius drives food export laboratory accreditation investments. CDSCO regulatory pathways for point-of-care diagnostics open veterinary and agricultural screening applications. The Maharashtra-Gujarat pharmaceutical corridor concentrates contract research organization capacity for method validation services.
Japan
PMDA oversight of antimicrobial resistance surveillance protocols sustains hospital laboratory automation spending. METI industrial policy supports biosensor miniaturization for environmental and food safety monitoring applications. The Kanto region's precision instrument manufacturing base supplies electrochemical detection platforms for distributed deployment.
Pathogen Detection Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with end-to-end platform vendors commanding premium positioning while reagent specialists compete on consumable pricing. The market structure consolidates around diversified life sciences conglomerates with captive distribution networks. Three archetypes dominate: integrated platform providers, sample-to-answer automation specialists, and reagent-focused chemical suppliers. Competitive moves center on strategic partnerships for geographic expansion and portfolio diversification into adjacent diagnostics workflows.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify scale-driven consolidation strategies that span clinical, research, and applied market segments. Among European specialists, bioMérieux and QIAGEN occupy positions emphasizing workflow automation and reduced hands-on time for workforce-constrained laboratories. Roche Holding AG anchors the premium diagnostics tier through established reimbursement pathways and reference laboratory relationships.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies, Inc. |
| bioMérieux |
| BD |
| Danaher Corporation |
| QIAGEN |
| Roche Holding AG |
| Bio-Rad Laboratories, Inc. |
| PerkinElmer, Inc. |
| Others |
Pricing and Supply Chain Analysis
Platform-scale economies in automated sample-to-answer systems compress unit economics for high-throughput reference laboratories while elevating price floors for mid-tier buyers lacking procurement leverage. This scale asymmetry concentrates vendor pricing power among integrated conglomerates with captive reagent supply chains.
Pricing Analysis
Configured-to-order PCR platforms command substantial premiums over standard benchtop instruments. Three-tier pricing structure across premium, standard, and economy levels segments buyers by testing volume and integration complexity. Cost compression in the economy tier intensifies because subscription-based reagent provisioning converts capital expenditure into operational budgets. Mid-sized food manufacturers exhibit highest price sensitivity; hospital systems with Medicare penalty exposure demonstrate lowest.
Supply Chain Analysis
Germany and Japan anchor specialty polymerase and fluorescent probe production for molecular diagnostics workflows. Reagent supply draws from precision chemical manufacturing clusters in the Rhine-Main and Kanto regions. Single-source vulnerability concentrates among fluorescent probe suppliers serving FDA-validated assay protocols. Distribution runs through cold-chain logistics providers managing calibration scheduling and inventory replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring consumable revenue from wastewater surveillance networks and subscription reagent models expands faster than hardware sales, positioning service-attach capabilities as the primary value capture mechanism.
For Market Incumbents: Consolidate reagent supply security through backward integration into polymerase production or long-term offtake agreements with German and Japanese chemical suppliers. Lock in reference laboratory relationships via exclusive subscription provisioning that raises switching costs for competitors. For New Entrants and Emerging Players: Lead with CRISPR-based field-deployable platforms targeting veterinary and agricultural screening in Southeast Asia and Latin America where infrastructure constraints exclude conventional PCR. Pursue regulatory pathway partnerships with CDSCO in India for point-of-care diagnostic approvals. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sample-to-answer automation specialists with established reimbursement codes and reference laboratory relationships. Target acquisition archetypes include biosensor miniaturization firms with EPA environmental monitoring validation. The signal to watch is FDA enforcement intensity for Food Safety Modernization Act preventive controls.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Supply Integration | Captive polymerase production insulates margins from allocation risk during demand surges. |
| Subscription Provisioning Model | Third-party logistics-managed cold-chain inventory converts fixed costs to per-test expenses for mid-tier buyers. |
| Wastewater Surveillance Deployment | Continuous monitoring infrastructure generates recurring consumable revenue absent large capital purchases. |
| AI-Assisted Image Analysis | Machine learning algorithms reduce specialist interpretation burden and enable technician-level microscopy operation. |
| Point-of-Care Regulatory Pathway | CDSCO and NMPA streamlining accelerates molecular diagnostic platform approvals for decentralized settings. |
Research Methodology
Operator-level perspectives from clinical laboratory directors, food safety compliance officers, municipal utility managers, and biomedical procurement specialists anchored the qualitative base. Secondary validation incorporated FDA warning letters, EPA water quality criteria documents, ISO 17025 accreditation registries, and hospital GPO contract databases. Bottom-up instrument shipment analysis triangulated against top-down testing volume estimates across clinical, food safety, and environmental applications.
Sensitivity analysis tested forecast outputs against variable regulatory enforcement scenarios and antimicrobial resistance surveillance mandate expansion rates across the analysis window. Segmentation dimensions modeled include product type, technology platform, application vertical, and end-user procurement scale. CAGRs were derived from installed base growth, replacement cycles, and consumable pull-through coefficients specific to molecular diagnostics workflows.
Forecasts assume regulatory continuity in FDA preventive control mandates and EPA recreational water quality criteria; material policy shifts would require re-modeling. Specific risk factors include reagent supply disruption from geopolitical events and clinical laboratory scientist pipeline collapse affecting testing throughput. Recalibration cycles align with material shifts in Medicare reimbursement penalty frameworks and biosensor miniaturization cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Extraction Kits Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Liver Function Tests Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
LDL Test Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
In Vitro Diagnostics Test Kit Market