
 Europe Esoteric Testing Market | 2026-2036
Europe Esoteric Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Esoteric Testing Market Insights
Hospital procurement consolidation across Western Europe is hardening, with large integrated delivery networks demanding standardized esoteric test menus and volume commitments. Eurofins Scientific leverages its pan-European laboratory footprint to secure multi-year service contracts with these consolidated buyers. Nordic Laboratories anchors its position through specialized genetic testing capabilities that differentiate it from generalist competitors. Sonic Healthcare Limited competes by controlling extensive specialist pathology networks in France, Germany, and the United Kingdom.
Esoteric testing encompasses highly specialized clinical laboratory analyses that employ advanced methodologies such as mass spectrometry, next-generation sequencing, and fluorescence in situ hybridization to detect rare biomarkers, genetic mutations, and complex infectious agents not covered by routine diagnostics. Its primary commercial purpose lies in enabling precision medicine decisions for oncology therapeutic selection, hereditary disease risk stratification, and treatment monitoring in refractory conditions. Molecular diagnostics and genetic testing segments command premium pricing due to their technical complexity and limited reimbursement alternatives, while immunoassay-based esoteric panels represent a mature, high-volume category with thinner margins. Next-generation sequencing applications in oncology are expanding fastest as pharmaceutical pipelines demand companion diagnostic validation.
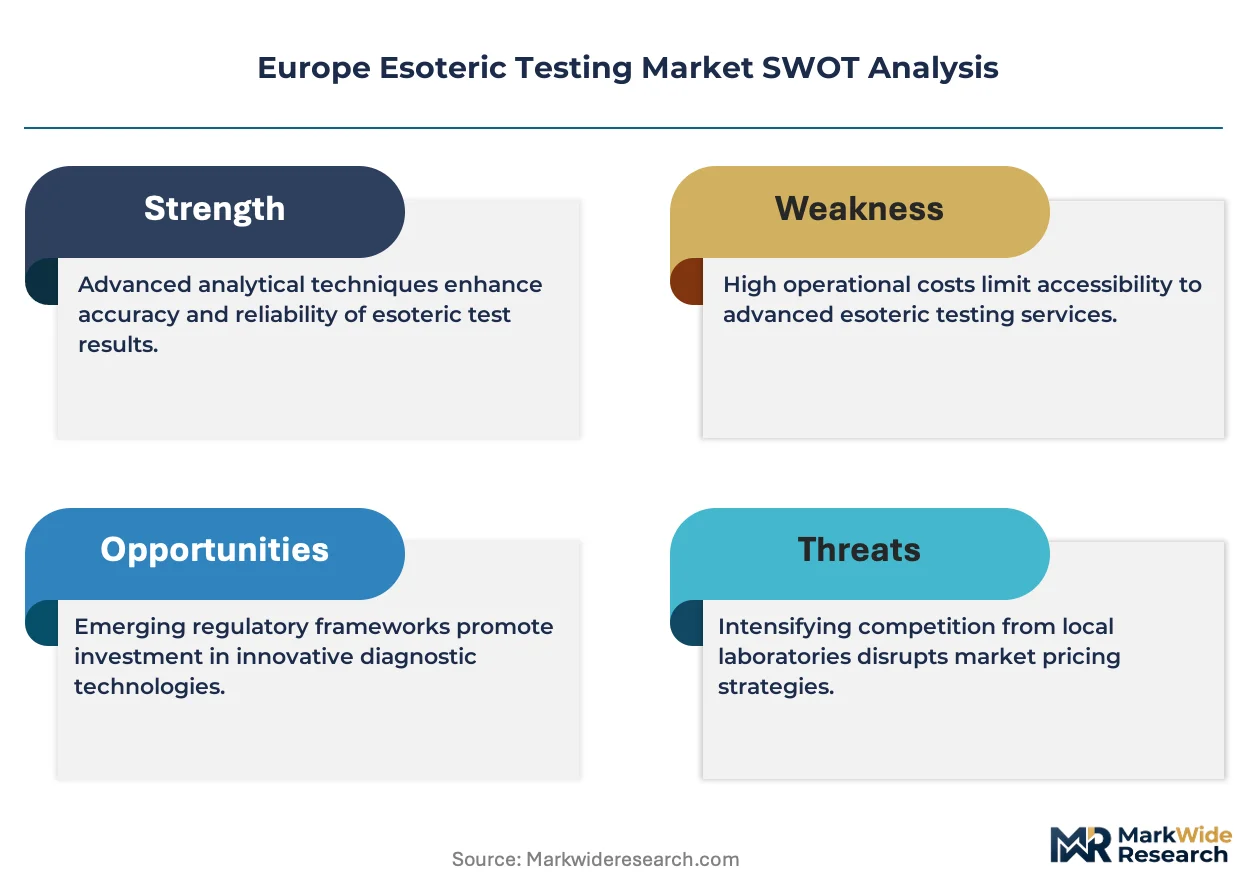
The European Medicines Agency coordinates centralized marketing authorization for companion diagnostics linked to oncology therapeutics, while the In Vitro Diagnostic Regulation mandates notified body certification for all but the lowest-risk test categories. REACH and RoHS frameworks constrain reagent manufacturing supply chains by restricting specific chemical substrates and hazardous substance use in diagnostic consumables. National health technology assessment bodies in Germany, France, and England determine reimbursement eligibility for novel esoteric tests, creating fragmented market access conditions. Stakeholders must monitor evolving companion diagnostic co-development requirements and decentralized manufacturing qualification standards to preserve commercial viability.
Market Dynamics
Hospital procurement consolidation across Germany, France, and the United Kingdom is compressing vendor margins while favoring laboratories with pan-European scale and standardized test menus.
Growth Catalysts
- Oncology companion diagnostics:Pharmaceutical pipelines require validated biomarker tests for targeted therapeutics, expanding molecular testing volumes in tertiary care centers.
- EU In Vitro Diagnostic Regulation:Mandatory notified body certification for Class C and D devices is elevating barriers for low-quality competitors and consolidating market share among established manufacturers.
- Next-generation sequencing platforms:Declining per-sample costs and automated library preparation are democratizing access to complex genetic analysis across mid-sized European hospitals.
Market Restraints
- Reimbursement fragmentation:Germany's G-BA, France's HAS, and England's NICE operate independent health technology assessment processes, delaying commercialization timelines for novel esoteric tests.
- Reagent supply concentration:Critical enzymes, fluorescent dyes, and synthetic oligonucleotides depend on concentrated manufacturing in Switzerland and the Netherlands, creating single-source vulnerability.
- Technical workforce scarcity:Clinical bioinformaticians and molecular geneticists face insufficient training pipeline capacity across Spanish, Italian, and Eastern European labor markets.
Strategic Opportunities
- Central and Eastern Europe:Poland, Czech Republic, and Romania exhibit significant underpenetration in hereditary cancer screening and pharmacogenomic testing relative to Western European benchmarks.
- Liquid biopsy oncology monitoring:Circulating tumor DNA analysis for minimal residual disease detection represents an emerging application with limited incumbent competition.
- EU Green Deal chemical restrictions:REACH and RoHS compliance requirements favor domestic European reagent manufacturers with established substitution capabilities over import-dependent competitors.
Industry Challenges
- Laboratory information system integration:Esoteric testing platforms require complex middleware development to interface with legacy hospital IT architectures, extending implementation timelines.
- Notified body certification queues:EMA-coordinated companion diagnostic pathways and IVDR technical documentation reviews face 12-18 month backlogs, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Esoteric Testing Market |
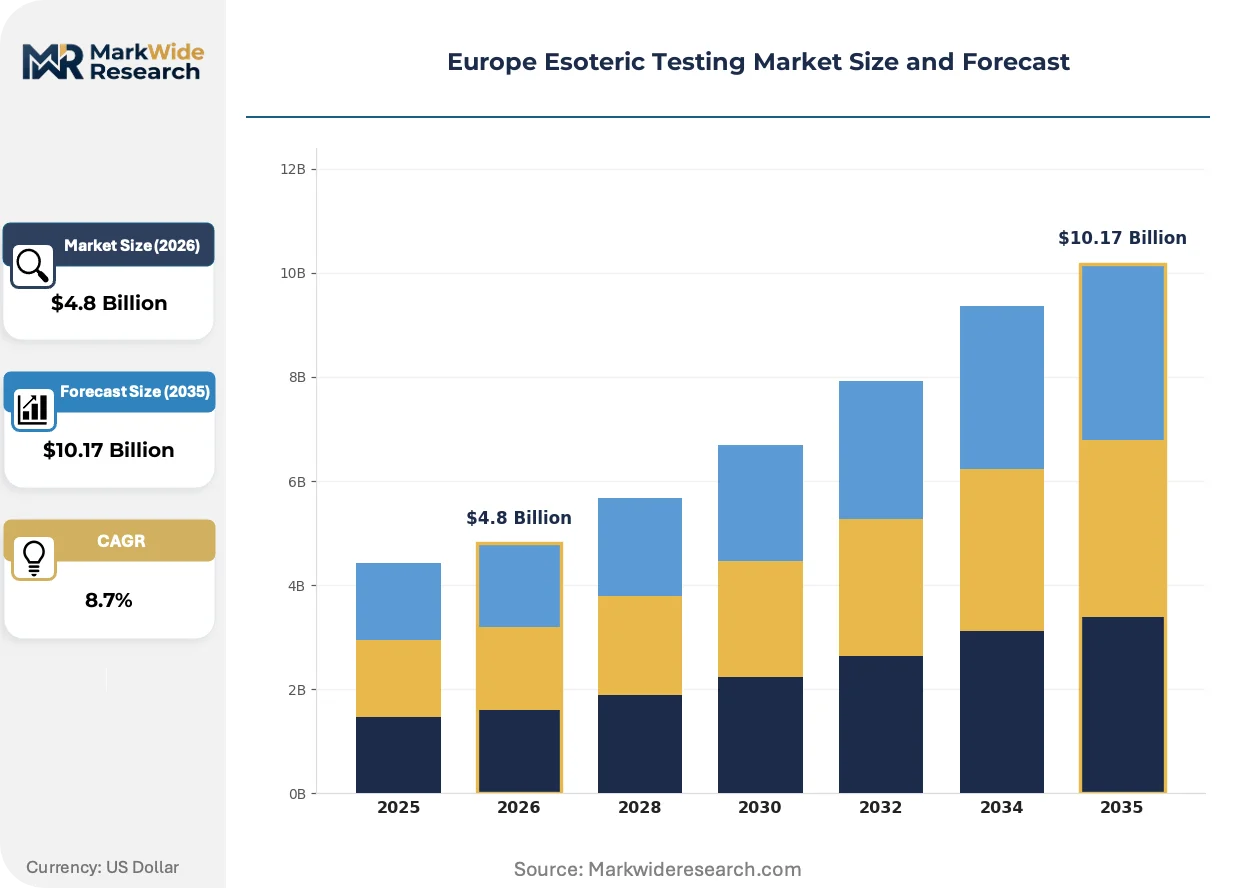
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Molecular Diagnostics, Immunoassays, Genetic Testing, Next-Generation Sequencing End User: Hospitals, Laboratories, Research Institutions, Specialty Clinics Application: Infectious Diseases, Genetic Disorders, Oncology, Cardiovascular Diseases Technology: RT-PCR, ELISA, Sanger Sequencing, Mass Spectrometry |
| Companies Covered | Eurofins Scientific, Nordic Laboratories, Buhlmann Diagnostics Corp, ACM Global Laboratories, Medical Laboratory Bremen, Quest Diagnostics Incorporated, Laboratory Corporation of America Holdings, Sonic Healthcare Limited, Mayo Foundation for Medical Education and Research, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Esoteric Testing Market Trends and Innovations
Automation, regulatory harmonization pressures, and buyer consolidation are restructuring how specialized diagnostics reach European patients.
Mass spectrometry-based steroid profiling and metabolic panel analysis is automating sample preparation workflows that previously required manual extraction and derivatization steps. Mid-sized hospital laboratories in France and the Netherlands are adopting these integrated platforms to expand in-house esoteric capabilities without proportional headcount increases. This compression of technical labor requirements is displacing referral patterns to centralized academic medical centers.
REACH authorization requirements for SVHC substances in diagnostic reagents are forcing manufacturers to reformulate chemiluminescence substrates and PCR master mixes ahead of sunset dates. The European Chemicals Agency's 2024-2027 restriction roadmap specifically targets phthalate plasticizers and perfluorinated compounds common in assay consumables. IVD manufacturers with captive chemical synthesis capabilities are accelerating substitution programs while competitors face supply discontinuities.
Integrated delivery networks in Germany and England are consolidating esoteric testing procurement through single-source framework agreements that bundle routine and specialized diagnostics. These multi-year contracts specify minimum volume commitments and penalize out-of-network referrals, compressing independent laboratory access to hospital-derived specimens. The purchasing transformation is most visible in oncology and prenatal testing categories where network-affiliated laboratories capture incremental share.
Europe Esoteric Testing Market Segmentation
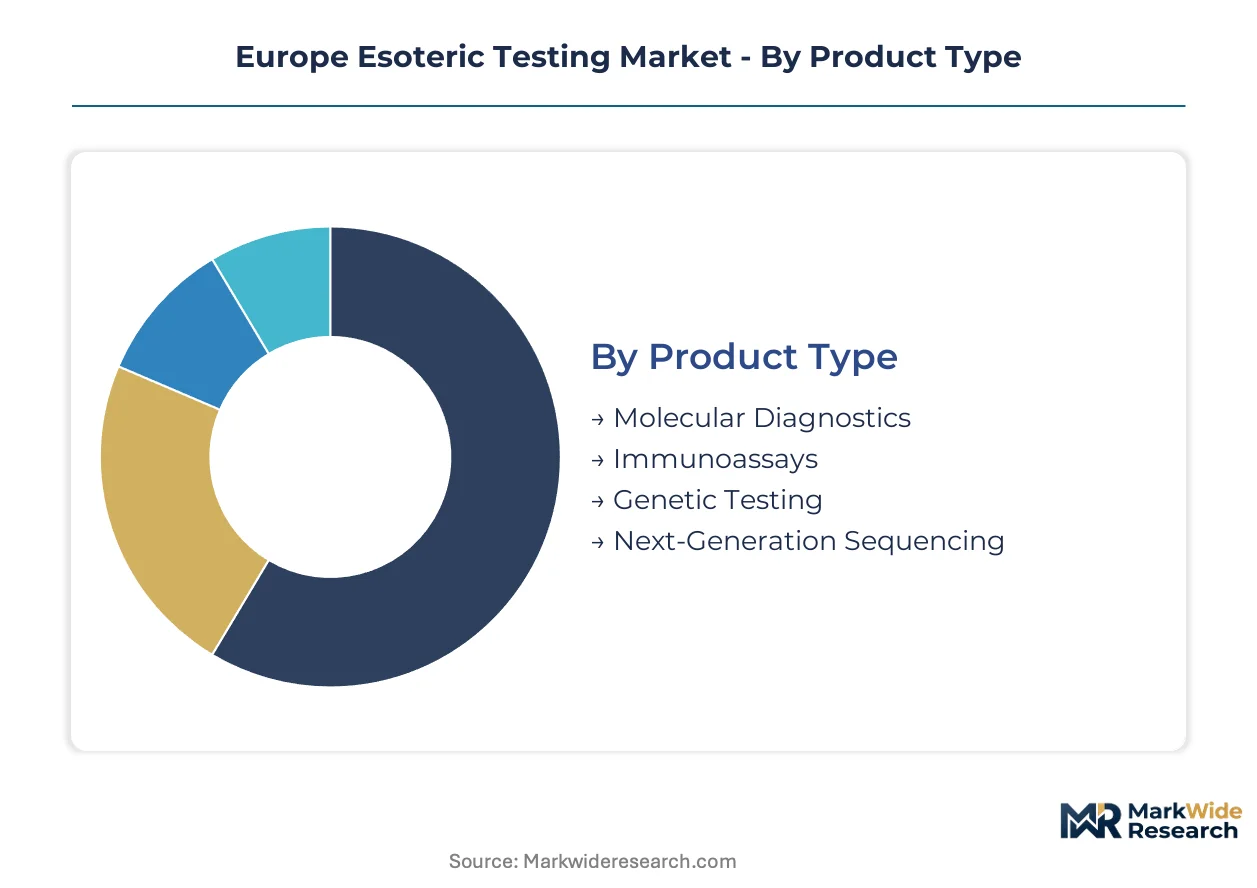
Esoteric testing segments stratify sharply by regulatory burden and reimbursement complexity across European markets. Certification requirements under IVDR and EMA companion diagnostic pathways create divergent commercial timelines and margin structures that reshape competitive positioning.
Product Type:
IVDR Class C and D certification mandates concentrate heaviest on molecular and genetic platforms, while immunoassay-based segments face lighter notified body scrutiny.
- Next-Generation Sequencing:High-complexity platforms employing massively parallel sequencing for oncology panels and hereditary disorder screening. Tertiary care centers in Germany and France drive procurement as pharmaceutical pipelines demand validated companion diagnostic outputs. IVDR technical documentation and EMA co-development pathways impose 18-24 month certification cycles that favor established manufacturers with dedicated regulatory affairs capacity.
- Molecular Diagnostics:Nucleic acid amplification and hybridization-based assays detecting infectious agents and cancer biomarkers. Hospital networks in England and the Netherlands prioritize standardized test menus that reduce inter-laboratory variability. Class C device classification mandates quality management system audits and clinical evidence requirements that elevate capital barriers for market entry.
- Genetic Testing:Cytogenetic and molecular analyses for hereditary disease risk stratification and carrier screening.
- Immunoassays:Antibody-based detection systems for endocrine, autoimmune, and allergy markers with established reimbursement codes.
Immunoassays sit at the top of the volume ranking, with next-generation sequencing climbing the fastest.
End User:
Procurement consolidation patterns differ markedly across customer types, with integrated delivery networks extracting steeper volume discounts than fragmented specialty providers.
- Hospitals:Tertiary and quaternary centers performing complex oncology and prenatal diagnostics in-house. German university hospitals and French CHU networks are consolidating esoteric testing into centralized laboratory medicine departments. Multi-year framework agreements with pan-European laboratory providers are displacing independent reference laboratory relationships.
- Laboratories:Independent and hospital-affiliated facilities processing referred specimens from primary care networks. Sonic Healthcare and Eurofins Scientific operate extensive hub-and-spoke networks across France, Germany, and the United Kingdom. REACH-compliant reagent sourcing and automated platform standardization determine competitive viability.
- Research Institutions:Academic medical centers and translational research facilities developing novel biomarker assays.
- Specialty Clinics:Fertility, oncology, and cardiovascular centers requiring rapid turnaround on targeted test panels.
Laboratories capture the highest specimen throughput, while specialty clinics are expanding their in-house capabilities most aggressively.
Application:
Companion diagnostic linkages to EMA-approved therapeutics create premium pricing tiers that separate oncology from commodity infectious disease testing.
- Oncology:Biomarker profiling for therapeutic selection, resistance monitoring, and minimal residual disease detection. Liquid biopsy applications for circulating tumor DNA analysis are penetrating mid-sized European hospitals as automated platforms reduce technical labor requirements. EMA centralized marketing authorization pathways mandate co-development evidence standards that synchronize test launch with drug approval.
- Genetic Disorders:Hereditary cancer screening, prenatal diagnostics, and rare disease identification. Nordic Laboratories anchors specialized capabilities in this segment across Denmark, Sweden, and Norway. National health technology assessment bodies operate independent reimbursement determinations that fragment commercialization timelines.
- Infectious Diseases:Molecular detection of resistant pathogens and emerging viral threats.
- Cardiovascular Diseases:Lipoprotein subfraction analysis and pharmacogenomic testing for anticoagulant response.
Oncology commands the steepest price premiums, with genetic disorders gaining share fastest in Central and Eastern European markets.
Technology:
Automation readiness and middleware integration complexity separate platforms suitable for distributed hospital deployment from centralized reference laboratory applications.
- Mass Spectrometry:High-sensitivity detection of steroids, metabolic intermediates, and therapeutic drug monitoring analytes. French and Dutch mid-sized hospitals are adopting integrated sample preparation platforms to expand in-house capabilities without proportional headcount expansion. REACH authorization requirements for solvent and derivatization reagents are forcing reformulation programs ahead of sunset dates.
- RT-PCR:Real-time nucleic acid amplification for infectious disease and oncology applications. Standardized instrument footprints and CE-IVD kit availability support deployment across diverse European laboratory settings. Supply concentration for thermostable polymerases and fluorescent probe chemistries in Switzerland creates single-source vulnerability.
- ELISA:Enzyme-linked immunosorbent assays for high-volume endocrine and infectious marker detection.
- Sanger Sequencing:Gold-standard confirmation sequencing for variant validation and forensic applications.
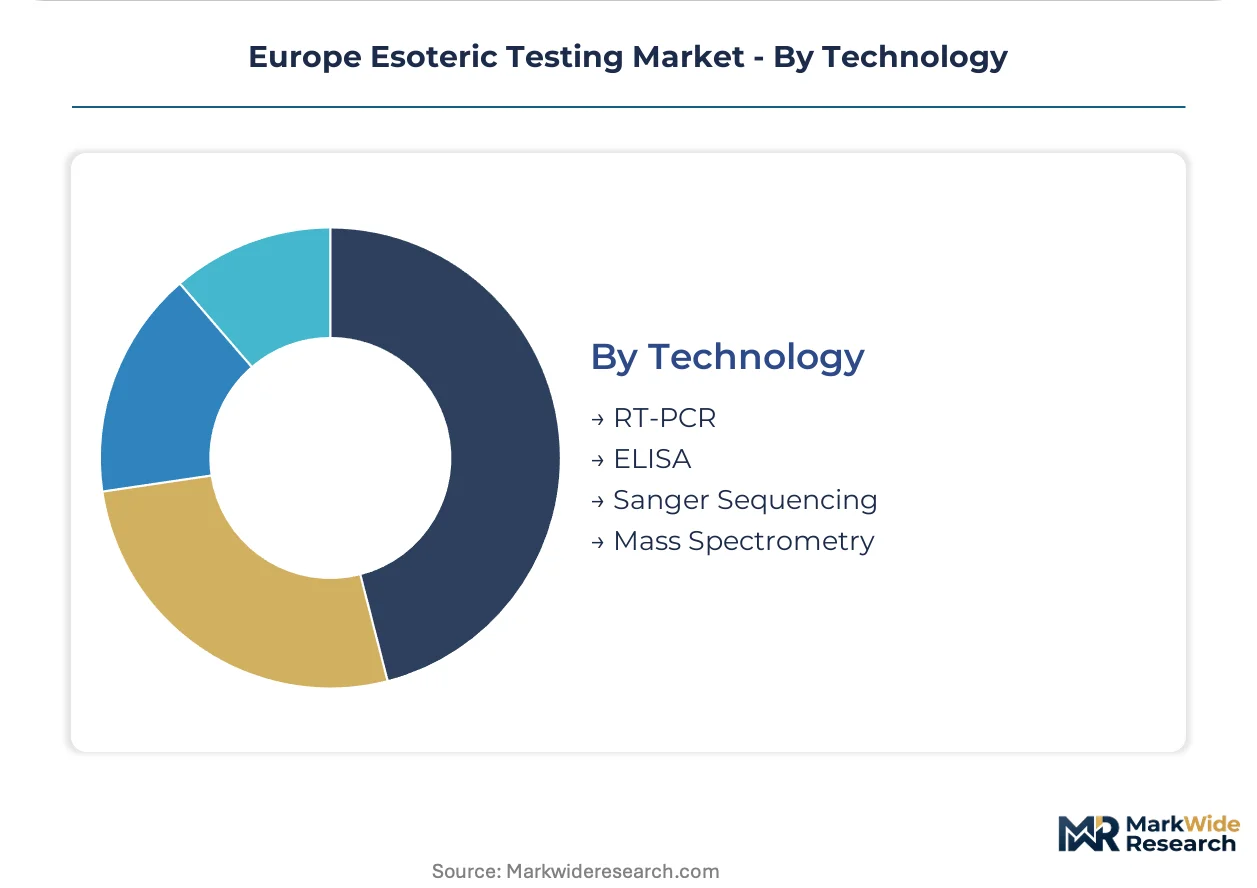
ELISA retains the highest installed base, with mass spectrometry posting the steepest expansion trajectory as automation compresses labor requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical bioinformaticians and molecular geneticists concentrate in university hospital clusters across Western Europe, anchoring regional testing capabilities and drawing pharmaceutical companion diagnostic development toward established academic medical centers.
Germany
University hospital networks in Berlin, Munich, and Heidelberg drive demand for oncology companion diagnostics and hereditary cancer screening. The Federal Joint Committee (G-BA) operates health technology assessment processes that determine reimbursement eligibility for novel molecular tests. Bavaria's Munich biotech cluster hosts concentrated pharmaceutical co-development activity linking diagnostic validation to therapeutic pipelines.
France
Public hospital networks (CHU) in Paris, Lyon, and Marseille consolidate procurement for specialized genetic and prenatal diagnostics. The National Authority for Health (HAS) evaluates clinical utility evidence for inclusion in national reimbursement schedules. The Île-de-France region anchors the densest concentration of IVD manufacturers and reference laboratory capacity serving both domestic and export markets.
United Kingdom
Integrated care systems in England and devolved health authorities in Scotland and Wales standardize test menus across hospital networks. The National Institute for Health and Care Excellence (NICE) issues technology appraisal guidance that shapes commercialization timelines for innovative assays. The Cambridge-Oxford-London golden triangle concentrates next-generation sequencing platform development and clinical validation infrastructure.
Netherlands
Mid-sized hospital laboratories in Utrecht, Rotterdam, and Eindhoven expand in-house mass spectrometry capabilities for metabolic and endocrine testing. The Dutch Healthcare Authority (NZa) negotiates tariff structures for novel diagnostics within statutory health insurance frameworks. The Eindhoven-Utrecht corridor hosts automated platform manufacturers serving distributed laboratory deployment models.
Poland
Tertiary centers in Warsaw, Kraków, and Wrocław develop molecular diagnostics capacity for oncology and infectious disease applications. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products oversees IVD conformity assessment under IVDR transitional provisions. The Mazovia region concentrates private laboratory investment targeting underpenetrated hereditary screening segments relative to Western European benchmarks.
Europe Esoteric Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, with pan-European laboratory networks capturing consolidated hospital contracts while regional specialists defend genetic testing niches. The vendor base stratifies into three archetypes: integrated diagnostic service providers with multi-country footprints, specialized reference laboratories with differentiated technical capabilities, and academic medical center affiliates with captive research-to-clinical pipelines. M&A activity concentrates on acquiring notified body certifications and established IVDR technical documentation, while strategic partnerships link pharmaceutical companion diagnostic co-development to centralized laboratory infrastructure.
Among pan-European service providers, Eurofins Scientific and Sonic Healthcare Limited exemplify scale-driven competitive positioning through extensive hub-and-spoke laboratory networks. Nordic Laboratories occupies a specialized tier focused on hereditary and genetic testing capabilities across Scandinavian markets. These three anchors represent divergent strategic postures: geographic breadth versus technical depth versus regional concentration.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Nordic Laboratories |
| Buhlmann Diagnostics Corp |
| ACM Global Laboratories |
| Medical Laboratory Bremen |
| Quest Diagnostics Incorporated |
| Laboratory Corporation of America Holdings |
| Sonic Healthcare Limited |
| Mayo Foundation for Medical Education and Research |
| Others |
Pricing and Supply Chain Analysis
Clinical bioinformatician concentration in the Cambridge-Oxford-London corridor and the Munich-Heidelberg cluster generates labor-cost differentials that widen pricing-tier spreads between premium companion diagnostic services and commoditized immunoassay panels.
Pricing Analysis
The bundled-vs-unbundled service split separates multi-year framework agreements from transactional referral testing. Three-tier pricing structure across premium, standard, and economy levels aligns with IVDR certification grades and EMA co-development status. Pricing pressure stems from hospital procurement consolidation demanding volume commitments and standardized menus. Integrated delivery networks exhibit highest price sensitivity; pharmaceutical companion diagnostic sponsors show lowest sensitivity due to regulatory co-dependency.
Supply Chain Analysis
Workforce availability constraints in Switzerland and the Netherlands concentrate critical enzyme and fluorescent dye manufacturing. Supply chains draw from Swiss thermostable polymerase production, Dutch oligonucleotide synthesis, and German precision optics fabrication. Single-source vulnerability pervades synthetic reagent categories. Distribution runs through pan-European laboratory networks with hub-and-spoke specimen logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on automation-driven labor compression and premium-tier shift toward companion diagnostic-linked oncology testing.
For Market Incumbents: Anchor market position through IVDR certification stockpiling and notified body relationship deepening before queue backlogs extend. Consolidate reagent manufacturing backward into captive chemical synthesis capabilities to offset REACH substitution deadlines. Defend against mid-sized hospital in-house automation adoption by embedding proprietary middleware into laboratory information systems. For New Entrants and Emerging Players: Launch via liquid biopsy oncology monitoring applications where incumbent competition remains sparse and technical barriers are falling. Target Poland, Czech Republic, and Romania for hereditary cancer screening white space with automated platform partnerships. Pursue pharmacogenomic testing contracts with Central European pharmacy chains as distribution anchor. For Investors and Strategic Acquirers: Pan-European laboratory service providers are the most active acquirer in this space, seeking notified body certifications and established IVDR technical documentation. Five-to-ten-year viability favors targets with EMA-coordinated companion diagnostic pathways already initiated. Monitor notified body certification queue lengths as inflection indicator for regulatory capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | Notified body certification accelerates market access for Class C and D devices under EMA coordination. |
| Pharmaceutical Companion Diagnostic Co-Development | EMA centralized marketing authorization synchronizes test launch with oncology therapeutic approval. |
| Automated Platform Deployment | Mass spectrometry and NGS automation reduces clinical bioinformatician headcount requirements in mid-sized hospitals. |
| REACH-Compliant Reagent Reformulation | Substitution programs for SVHC substances preserve supply continuity under ECHA restriction roadmaps. |
| Central and Eastern European Laboratory Partnership | Hub-and-spoke networks capture underpenetrated hereditary screening demand in Poland and Czech Republic. |
Research Methodology
Multiple input streams — laboratory operations directors, hospital procurement committee members, regulatory affairs specialists at IVD manufacturers, and clinical bioinformaticians — were reconciled against EMA companion diagnostic filings, IVDR notified body certification databases, G-BA and NICE health technology assessment records, and pan-European laboratory service contract disclosures. Bottom-up specimen volume modeling and top-down revenue triangulation anchored segmentation outputs.
Data-stream reconciliation across product type, end user, application, and technology dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from regression analysis of historical procurement patterns and pharmaceutical pipeline-stage biomarker demand. Forecast inputs incorporated IVDR transition timeline assumptions and REACH authorization sunset schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints and pharmaceutical pipeline failure rates. Practitioners should monitor EMA companion diagnostic co-development announcement velocity and notified body queue length reporting for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Cannabis Testing Services Market
Testing Services
West Nile Virus Testing Market
Testing Services
Dengue Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Sports Drug Testing Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Bimetallic Thermometer Market
Testing Services
North America Drug Screening Market
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Global Efficacy Testing Market
Testing Services
Europe Newborn Screening Market
Testing Services
Candida Vaginitis Rapid Testing Market