
 Global Lipid Panel Testing Market | 2026-2036
Global Lipid Panel Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lipid Panel Testing Market Foresight
Point-of-care testing revenue is reshaping margin distribution across the lipid panel testing value chain, pulling profitability from centralized lab services toward bedside and pharmacy-based diagnostics. Abbott Laboratories leverages its handheld i-STAT platform architecture to dominate near-patient lipid testing in physician offices. Quest Diagnostics anchors the high-volume reference lab segment through its national specimen logistics network. F. Hoffmann-La Roche Ltd differentiates via integrated cobas analyzer systems that sustain recurring reagent pull-through across hospital laboratories.
Lipid panel testing measures cholesterol fractions—total cholesterol, LDL, HDL, and triglycerides—through enzymatic colorimetric or direct homogeneous assays, typically requiring serum or plasma samples processed within four hours of collection to preserve analyte stability. The methodology serves cardiovascular risk stratification, metabolic syndrome monitoring, and therapeutic response tracking in clinical practice. Automated analyzers command the largest installed base but face margin compression as reagent and consumable sales generate the recurring revenue pools manufacturers prioritize. Diagnostic laboratories represent the fastest-growing end user segment as health systems consolidate testing volumes into regional hubs equipped with high-throughput platforms.
The US FDA regulates lipid assay systems as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for in vitro diagnostic kits sold under CE marking. CLIA-waived status under US CMS rules shapes point-of-care adoption by restricting operator training requirements. Stakeholders must monitor evolving payer coverage policies for preventive lipid screening and the trajectory of multi-analyte platform integration that could displace standalone lipid testing workflows.
Market Dynamics
Point-of-care lipid testing is fragmenting diagnostic workflows, pulling testing volumes from centralized hospital laboratories toward physician offices, retail pharmacies, and ambulatory settings where CLIA-waived platforms reduce operator certification burdens and accelerate turnaround times.
Growth Catalysts
- CLIA-waived platform expansion:The US CMS complexity classification enables non-laboratory personnel to operate lipid analyzers in physician offices and retail clinics, expanding addressable testing sites beyond traditional lab networks.
- Cardiovascular screening mandates:Preventive care protocols in Germany, Japan, and the United States now incorporate routine lipid panels for adults over 40, institutionalizing recurring demand.
- Enzymatic assay miniaturization:Microfluidic cartridge technologies reduce sample volume requirements to capillary blood draws, eliminating phlebotomy infrastructure and enabling fingerstick collection at the point of care.
Market Restraints
- Reagent cost volatility:Enzyme and chromogen inputs for colorimetric assays face price pressure from specialty chemical supply concentration in Switzerland and Germany.
- EU MDR compliance burden:The Medical Device Regulation imposes expanded clinical evidence requirements for IVD kit renewals, lengthening time-to-market for new lipid assay formulations.
- Direct LDL measurement substitution:Homogeneous direct assays are displacing calculated Friedewald estimates, forcing capital reinvestment in analyzer platforms incompatible with legacy reagent contracts.
Strategic Opportunities
- Retail pharmacy channel penetration:MinuteClinic-style models in the United States and similar pharmacy-based screening programs in the United Kingdom create new specimen collection nodes outside traditional healthcare facilities.
- Multi-analyte platform convergence:Integration of lipid panels with HbA1c, hs-CRP, and renal function markers on single cartridge formats captures metabolic syndrome monitoring workflows.
- Japan's aging demographic tailwind:METI-promoted preventive health initiatives for cardiovascular disease in adults over 65 expand reimbursable testing frequency in the world's oldest population.
Industry Challenges
- Cross-training laboratory personnel:Consolidation of hospital networks into regional lab hubs requires technicians proficient across chemistry, immunoassay, and molecular platforms, stretching specialized lipid assay expertise thin.
- Legacy analyzer integration:Health systems with installed bases of 10-15 year-old automated chemistry systems face middleware compatibility barriers when adopting novel direct LDL or small dense LDL assay methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lipid Panel Testing Market |
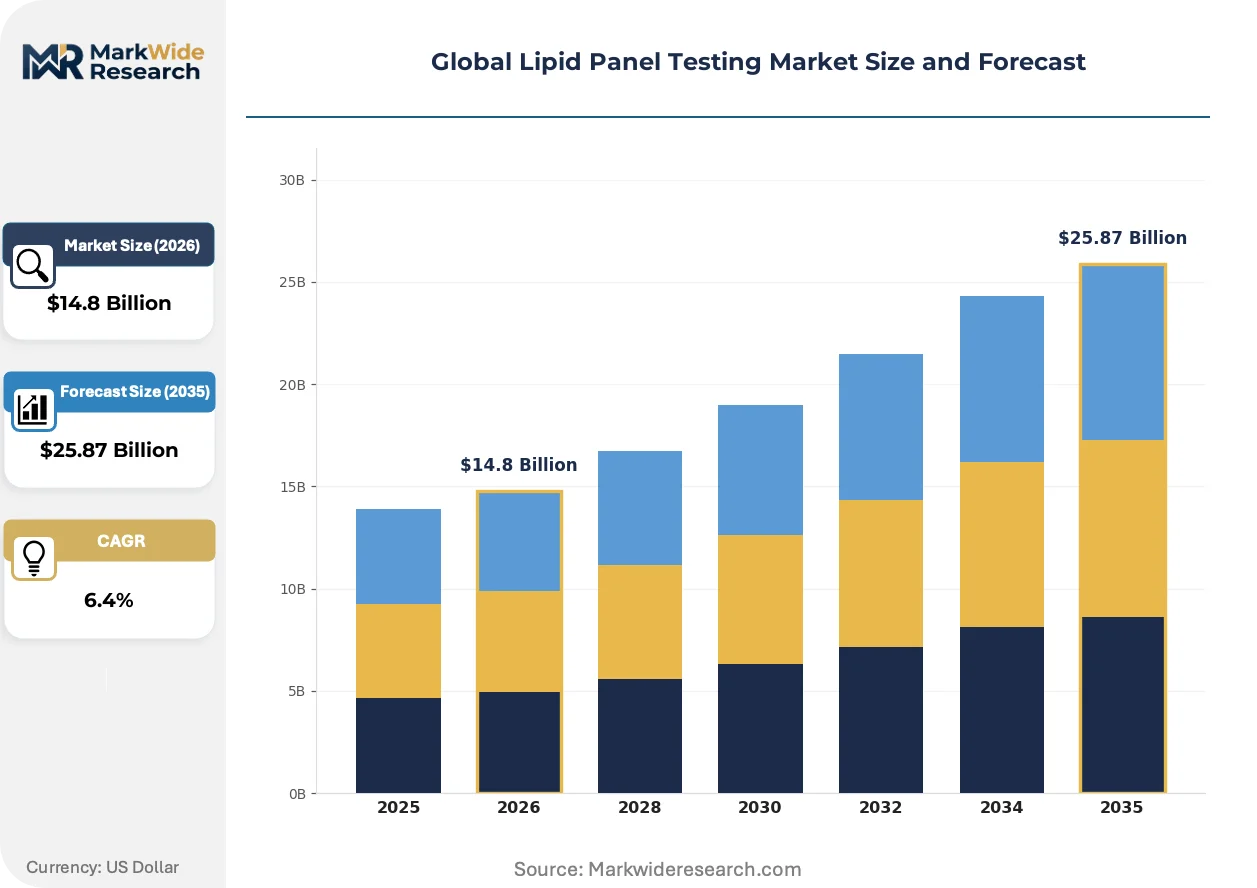
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Reagents, Kits, Consumables Application: Cardiovascular Risk Assessment, Diabetes Management, Metabolic Disorder Screening, Preventive Health Checkups End User: Hospitals, Diagnostic Laboratories, Specialty Clinics, Physician Offices Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Pharmacies |
| Companies Covered | Abbott Laboratories, Quest Diagnostics, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Randox Laboratories Ltd., Beckman Coulter Inc., Siemens Healthcare GmbH, Bio-Rad Laboratories Inc., PTS Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lipid Panel Testing Market Shifts & Advancements
Digital connectivity and assay multiplexing are redefining how lipid results reach clinical decision-makers, with cloud-integrated devices and algorithmic risk scoring displacing paper-based reporting and isolated analyzer outputs.
Microfluidic cartridge technology is hybridizing lipid testing workflows by embedding sample preparation, reaction chemistry, and optical detection into single-use disposable units. Community health centers and employer wellness programs are adopting these platforms to bypass cold-chain logistics and centrifugation requirements. The structural consequence is compression of the reference laboratory's monopoly on STAT lipid results, with bedside devices now matching central lab precision for routine panels.
The EU Medical Device Regulation's clinical evidence requirements for IVD performance claims are forcing manufacturers to generate prospective validation data rather than relying on literature-based equivalence. This regulatory burden disproportionately affects mid-size assay developers lacking dedicated clinical affairs infrastructure. German and French notified bodies are prioritizing lipid panel reviews due to high submission volumes, creating approval queue bottlenecks that favor established players with regulatory operations scale.
Health system procurement departments are consolidating analyzer contracts into multi-year enterprise agreements spanning chemistry, immunoassay, and hematology platforms. This bundling behavior displaces standalone lipid analyzer purchases and locks reagent commitments to single manufacturer ecosystems. The United States exhibits the most pronounced concentration, with integrated delivery networks in Texas and California leveraging purchasing volume to extract total cost-of-ownership concessions across ten-year contract horizons.
Global Lipid Panel Testing Market Segmentation
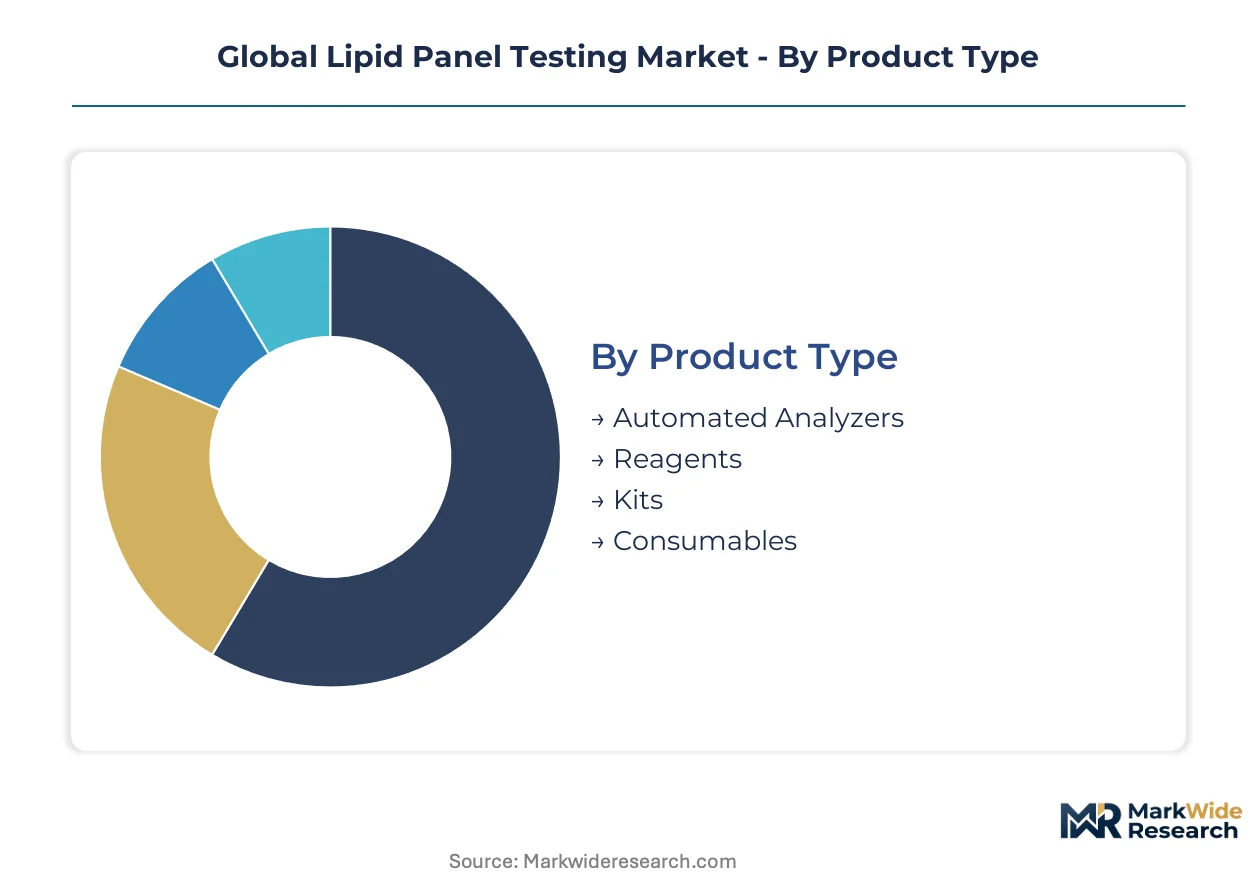
Lipid panel testing market segmentation reveals how technology form factors, clinical use cases, and procurement channels create distinct competitive arenas with divergent margin profiles and regulatory requirements. Understanding these divides explains why manufacturers pursue divergent strategies across automated platforms versus point-of-care consumables.
Product Type:
Cost tier separates the product landscape, with capital equipment at the premium end and recurring consumables driving volume economics.
- Automated Analyzers:High-throughput chemistry platforms process 400-800 tests per hour using wet chemistry or dry slide technology. Hospital laboratories in the United States and Germany anchor demand as health systems consolidate testing into regional hubs requiring enterprise-scale throughput.
- Reagents:Enzymatic colorimetric formulations for cholesterol, triglyceride, and lipoprotein fraction quantification constitute the recurring revenue backbone. Swiss and German specialty chemical suppliers concentrate production of chromogen substrates, creating supply vulnerability for assay manufacturers.
- Kits:Lyophilized or liquid-stable reagent packs for specific analyzer platforms.
- Consumables:Cuvettes, sample cups, and microfluidic cartridges.
Automated analyzers command the established base. The steepest expansion runs through reagents as test volumes migrate toward preventive screening protocols.
Application:
Clinical workflow integration determines where lipid testing sits within patient pathways, from acute cardiovascular events to routine wellness visits.
- Cardiovascular Risk Assessment:Primary indication encompassing Framingham risk scoring and ACC/AHA guideline implementation. Physician offices in the United States deploy CLIA-waived platforms to capture same-visit prescribing decisions for statin therapy.
- Diabetes Management:Metabolic syndrome monitoring combines lipid panels with HbA1c testing in integrated workflows. Japanese diabetes centers drive multi-analyte platform adoption under METI-promoted preventive health initiatives.
- Metabolic Disorder Screening:Dyslipidemia detection in inherited lipid disorders.
- Preventive Health Checkups:Occupational wellness and insurance-mandated screening programs.
Cardiovascular risk assessment anchors installed capacity. Preventive health checkups are climbing the fastest as employer wellness programs expand reimbursable screening access.
End User:
Customer type fragmentation reflects the decentralization of diagnostic authority from hospital core laboratories toward distributed care settings.
- Hospitals:Acute care facilities requiring STAT turnaround for emergency department chest pain protocols. German university hospitals maintain the highest per-site test volumes through integrated cardiovascular centers.
- Diagnostic Laboratories:Independent and hospital-affiliated reference labs consolidating regional testing volumes. Quest Diagnostics and similar networks in the United States exploit logistics scale to capture specimens from physician offices lacking in-house capabilities.
- Specialty Clinics:Cardiology and endocrinology-focused outpatient facilities.
- Physician Offices:Primary care sites adopting CLIA-waived point-of-care devices.
Hospitals retain the highest absolute test volumes. Physician offices represent the steepest expansion trajectory as waived testing platforms reduce infrastructure barriers.
Distribution Channel:
Supply chain configuration shapes how manufacturers capture margin and control end-user relationships across fragmented geographic markets.
- Direct Sales:Manufacturer field forces negotiate enterprise contracts with integrated delivery networks. Abbott Laboratories and Roche Diagnostics deploy dedicated account teams for hospital system analyzer placements in Texas and California.
- Distributors:Regional medical supply intermediaries serving mid-size laboratories and clinics. McKesson and Cardinal Health in the United States consolidate procurement for facilities lacking direct manufacturer relationships.
- Online Platforms:E-procurement portals for consumables replenishment.
- Retail Pharmacies:MinuteClinic-style models for patient-initiated screening.
Direct sales dominate analyzer placements. Distributors capture the steepest expansion in consumables as mid-tier laboratories seek procurement efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States favors decentralized point-of-care deployment, while Germany and Japan concentrate testing in consolidated laboratory hubs under stringent regulatory frameworks.
United States
Employer wellness programs and Medicare preventive screening mandates drive volume. The FDA's CLIA-waived classification under CMS rules enables pharmacy-based testing at MinuteClinic locations. Texas and California integrated delivery networks negotiate enterprise analyzer contracts spanning multi-hospital systems.
Germany
Statutory health insurance mandates routine cardiovascular screening for adults over 35. The EU Medical Device Regulation imposes clinical evidence requirements for IVD kit renewals through notified bodies in Berlin and Munich. Bavarian university hospitals maintain the highest per-site lipid test volumes through centralized cardiovascular centers.
Japan
METI-promoted preventive health initiatives target cardiovascular disease in adults over 65. The PMDA regulates lipid assay systems under pharmaceutical affairs law with streamlined approval for designated medical devices. Tokyo and Osaka metropolitan areas concentrate high-throughput diagnostic laboratory capacity.
Switzerland
Specialty chemical suppliers concentrate production of chromogen substrates for enzymatic assays. Swissmedic oversees IVD performance claims with requirements for prospective clinical validation data. Basel and Zurich anchor reagent manufacturing clusters serving European assay developers.
United Kingdom
NHS Long Term Plan targets cardiovascular disease prevention through primary care lipid screening. The MHRA post-Brexit regulatory framework maintains alignment with EU MDR standards for CE-marked devices. London and Manchester health systems pilot pharmacy-based testing programs outside traditional hospital networks.
Global Lipid Panel Testing Market Competitive Landscape
Capability concentration sits with specialized assay developers; scale advantage sits with diversified diagnostics conglomerates. The market structures around three tiers: integrated laboratory service networks, automated platform manufacturers, and point-of-care device specialists. Strategic moves center on multi-analyte platform convergence and enterprise contract bundling across chemistry and immunoassay portfolios.
Among diversified diagnostics conglomerates, Abbott Laboratories, F. Hoffmann-La Roche Ltd, and Siemens Healthcare GmbH occupy positions spanning analyzer hardware, reagent supply, and point-of-care deployment. These entities exemplify the scale-driven tier through integrated platform ecosystems that lock reagent commitments across hospital network contracts. Specialists in enzymatic assay chemistry and microfluidic cartridge technology represent the capability-focused tier, competing on assay performance rather than installed base breadth.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Quest Diagnostics |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Randox Laboratories Ltd. |
| Beckman Coulter Inc. |
| Siemens Healthcare GmbH |
| Bio-Rad Laboratories Inc. |
| PTS Diagnostics |
| Others |
Supply & Pricing Matrix
Single-source dependency on Swiss and German chromogen substrate suppliers determines both the three-tier pricing structure across premium, standard, and economy levels and the elongated procurement timelines that favor enterprise contract bundling over spot purchasing. Reagent cost volatility feeds directly into analyzer placement economics, pressuring manufacturers to lock multi-year reagent commitments through integrated platform ecosystems rather than transactional consumables sales.
Pricing Analysis
Long-term enterprise contracts spanning chemistry, immunoassay, and hematology platforms dominate analyzer placements, with pricing stratifying across premium, standard, and economy tiers based on throughput capacity and after-sales service bundling. Price differentiation hinges on CLIA-waived certification tier and geographic delivery infrastructure, with integrated delivery networks in Texas and California extracting total cost-of-ownership concessions. Cost compression in consumables is intensifying because health system procurement departments consolidate vendor relationships. Mid-tier diagnostic laboratories exhibit the highest price sensitivity, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates supply chain risk planning for enzymatic assay manufacturers. Production of chromogen substrates and specialty enzymes concentrates in Switzerland, Germany, and Japan, with microfluidic cartridge fabrication anchored in East Asian electronics manufacturing clusters. Raw material dependencies span porcine-derived enzymes, synthetic chromogens, and precision-molded plastics. Single-source vulnerability persists for Friedewald-equivalent reagent formulations facing substitution pressure from direct LDL assays. Distribution runs through regional medical supply intermediaries serving mid-size laboratories, with direct manufacturer field forces capturing enterprise analyzer placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care testing decentralization fragments diagnostic authority, creating white-space opportunities for specialized assay developers and microfluidic platform specialists outside consolidated laboratory service networks. Preventive cardiovascular screening mandates in aging populations generate niche demand for CLIA-waived devices and multi-analyte cartridge formats.
For Market Incumbents: Harden analyzer platform ecosystems against reagent margin erosion by deepening backward integration into chromogen substrate production and securing captive supply agreements with Swiss specialty chemical suppliers. Defend installed base positions through middleware compatibility layers that bridge legacy chemistry systems with novel direct LDL assay methods, reducing customer switching incentives. For New Entrants and Emerging Players: Establish a beachhead in employer wellness programs and retail pharmacy screening nodes where CLIA-waived fingerstick platforms bypass cold-chain logistics requirements. Target community health centers in the United States and United Kingdom pharmacy-based testing pilots as the most penetrable end-user segment. Pursue regulatory sandbox pathways through FDA 510(k) premarket notification for microfluidic cartridge formats combining lipid panels with HbA1c quantification. For Investors and Strategic Acquirers: EU MDR clinical evidence requirements for IVD kit renewals reshape the acquisition landscape, favoring targets with dedicated regulatory affairs infrastructure and prospective validation datasets over literature-based equivalence claims. Five-to-ten year viability hinges on multi-analyte platform convergence capabilities. Prioritize mid-cap assay developers with integrated microfluidic cartridge technology and established notified body relationships. Monitor German and French notified body approval queue bottlenecks as the inflection signal indicating regulatory operations scale advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Analyte Platform Integration | Captures metabolic syndrome monitoring workflows by combining lipid panels with HbA1c and hs-CRP on single cartridges. |
| CLIA-Waived Device Development | Expands addressable testing sites to physician offices and retail clinics under CMS complexity classification rules. |
| Enterprise Contract Bundling | Locks reagent commitments across ten-year analyzer placements through integrated delivery network purchasing agreements. |
| Backward Integration into Chromogen Supply | Reduces exposure to Swiss and German specialty chemical supplier concentration and price volatility. |
| Cloud-Integrated Device Deployment | Displaces paper-based reporting through algorithmic risk scoring and electronic health record connectivity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR submission records through notified bodies in Berlin and Munich, and CMS Medicare reimbursement policy documents. The research team conducted structured interviews with hospital laboratory directors, point-of-care device product managers, GPO contracts managers, and Swiss specialty chemical procurement leads. Secondary validation drew from SEC 10-K filings of diversified diagnostics conglomerates, PMDA designated medical device approval registers, and METI preventive health initiative white papers. Bottom-up test volume modeling triangulated against top-down market sizing through analyzer installed base estimates and reagent consumption rates.
Forecast inputs include preventive screening protocol expansion trajectories, CLIA-waived platform adoption curves in physician offices, and multi-analyte cartridge penetration rates across metabolic syndrome monitoring workflows. Segmentation dimensions span product type, application, end user, and distribution channel, with geographic regulatory cluster as an additional modeling layer. CAGRs were derived through regression analysis of historical test volume growth against demographic aging indicators and reimbursement policy shifts. Industry-specific inputs incorporate EU MDR compliance timeline delays and Japan's METI-promoted cardiovascular screening frequency targets.
Stress conditions across reagent supply disruption scenarios, CLIA-waived classification scope revisions, and direct LDL assay substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory approval queue durations and enterprise contract renewal cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Bioburden Testing Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Monkeypox Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Europe Point-Of-Care-Testing (POCT) Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
Healthcare Testing, Inspection, and Certification Outsourcing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market