
 Blood Borne Testing Market | 2026-2036
Blood Borne Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Borne Testing Market Analytics
Polymerase chain reaction chemistries is broadening the addressable test menu beyond serological confirmation. Abbott Laboratories leverages integrated instrument-software platforms to sustain high-throughput screening workflows. F. Hoffmann-La Roche Ltd anchors its position through deep menu expansion in viral load quantification. Siemens Healthineers AG differentiates with decentralized analyzer footprints suited for blood bank satellite sites.
Blood borne testing encompasses laboratory and near-patient diagnostic procedures designed to detect pathogens transmissible through blood contact or transfusion, typically requiring sensitivity thresholds below one copy per milliliter for nucleic acid targets and specificity exceeding 99.5% to prevent false-positive donor deferrals. Its primary commercial purpose is safeguarding blood supply integrity while enabling clinical infectious disease management. Reagents and assays command the largest revenue share due to recurring consumption tied to every test execution, while molecular diagnostics represents the fastest-expanding technology segment as laboratories replace serological screening with nucleic acid amplification protocols. Instruments face longer replacement cycles but generate captive reagent demand that locks in multi-year revenue streams.
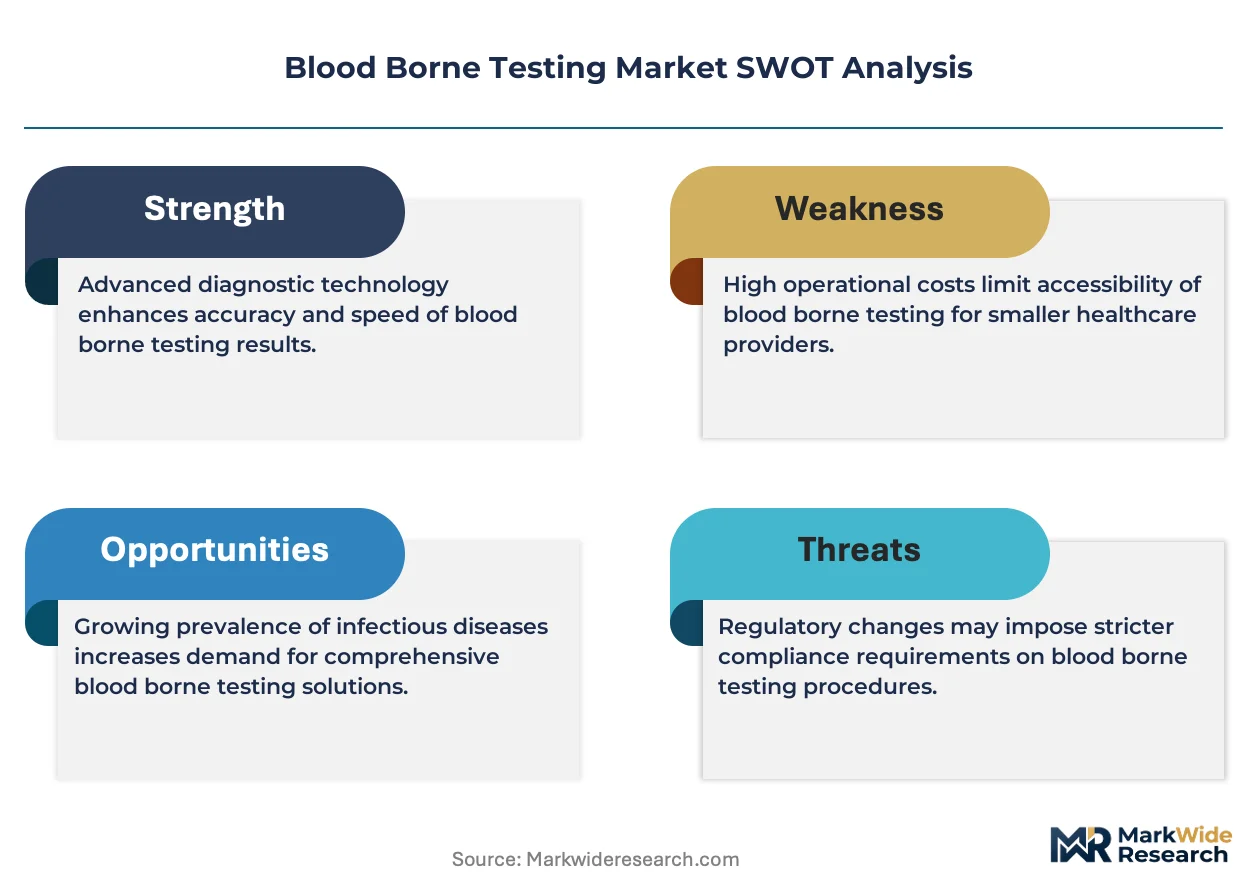
FDA, EMA, and WHO blood safety standards collectively determine product approval pathways, manufacturing quality benchmarks, and post-market surveillance obligations for manufacturers seeking multi-regional commercialization. CLIA complexity requirements in the United States and IVDR classification shifts in Europe are tightening performance documentation demands, favoring firms with established regulatory infrastructure. Stakeholders must weigh instrument placement strategies against the accelerating preference for modular molecular platforms that accommodate emerging pathogen panels without full system replacement.
Market Dynamics
Automated nucleic acid testing platforms are compressing serological screening cycles while CLIA-waived rapid test authorizations from FDA are fragmenting procurement authority between centralized hospital laboratories and satellite blood bank sites.
Growth Catalysts
- CLIA-waived rapid test expansion:FDA authorization pathways for point-of-care diagnostics are pulling screening capacity into emergency departments and mobile collection units.
- Hospital laboratory automation:Integrated instrument-software platforms are eliminating manual batch preparation steps and reducing technician touchpoints per sample.
- Hemovigilance program deepening:National surveillance systems in the United States, Germany, and Japan are mandating nucleic acid confirmation for all reactive serological screens.
Market Restraints
- Reagent cost concentration:Proprietary chemistries from dominant platform manufacturers lock blood banks into multi-year consumable contracts with limited generic substitution.
- IVDR performance documentation:Europe's In Vitro Diagnostic Regulation is extending technical file preparation timelines and elevating clinical evidence requirements for Class C devices.
- Specialized technician scarcity:Molecular diagnostics workflows require certified clinical laboratory scientists with nucleic acid amplification expertise that training pipelines cannot replenish.
Strategic Opportunities
- Emerging pathogen panel expansion:Modular platform architectures accommodate arbovirus and Babesia screening without full system replacement.
- Decentralized analyzer placement:Compact footprints suited for blood bank satellite sites in rural catchment areas are opening procurement conversations outside metropolitan hospital networks.
- WHO prequalification alignment:Blood safety standard harmonization across low- and middle-income country procurement frameworks is creating consolidated tender opportunities for multi-regional manufacturers.
Industry Challenges
- Legacy LIS integration friction:Hospital information systems built for serological reporting require middleware development to ingest quantitative viral load data streams.
- Proficiency testing logistics:External quality assessment programs for ultra-low copy number detection demand frozen panel distribution chains that maintain nucleic acid stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Borne Testing Market |
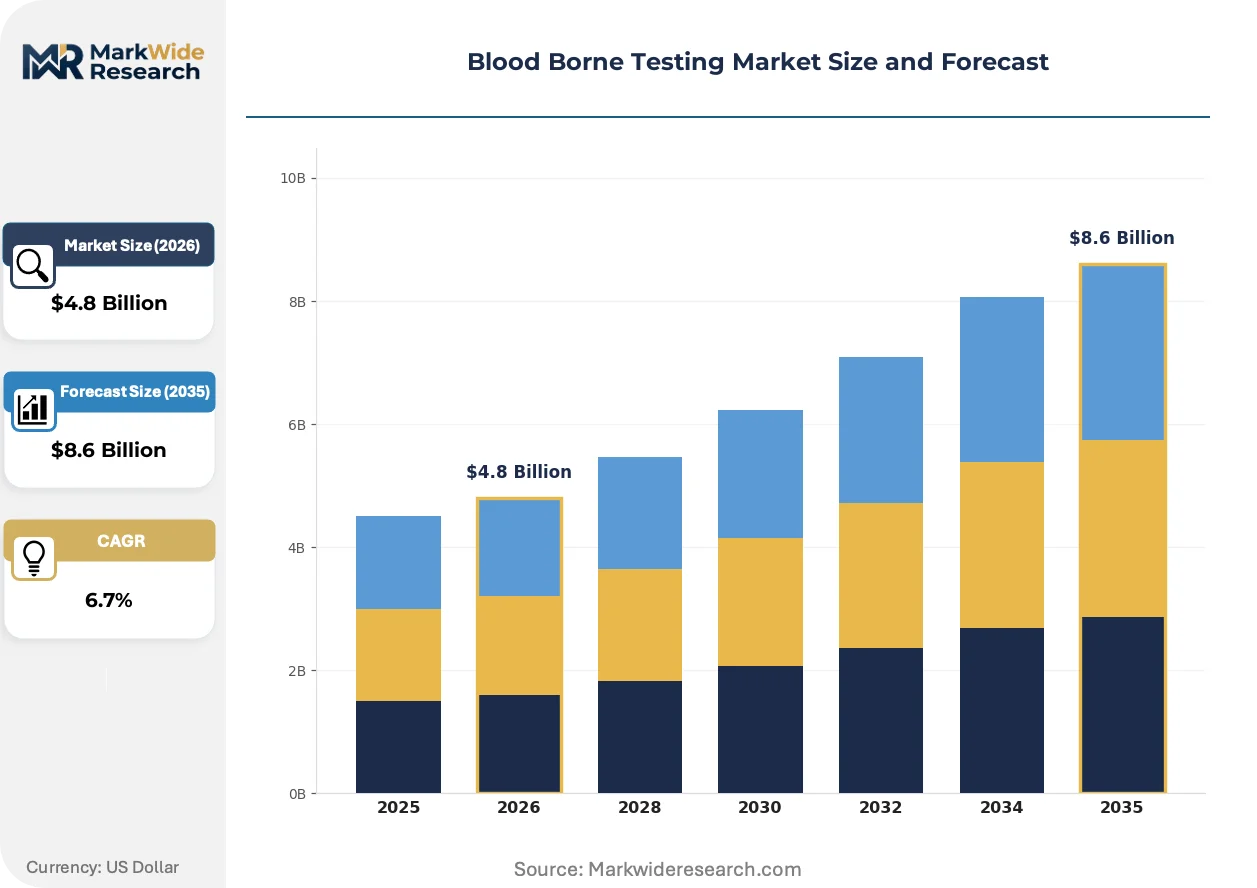
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Instruments, Consumables Application: Infectious Diseases, Blood Screening, Diagnostic Testing, Transfusion Services End User: Hospitals, Blood Banks, Diagnostic Laboratories, Clinics Technology: Molecular Diagnostics, ELISA, Rapid Testing, PCR |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, Bio-Rad Laboratories, Inc., Becton Dickinson and Company, Thermo Fisher Scientific Inc., bioMérieux SA, Grifols S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Borne Testing Market Evolving Landscape
Multiplexed molecular diagnostics are collapsing the sequential testing paradigm while regulatory pressure for donor safety documentation intensifies performance verification standards across procurement cycles.
Real-time PCR chemistries with simultaneous fluorescent detection of HIV, HBV, and HCV targets are consolidating previously discrete screening workflows into single-reaction protocols. Large hospital transfusion services in the United States and Germany are adopting these triplex assays to compress turnaround times for urgent surgical cases. This consolidation is eliminating redundant instrument footprints and concentrating purchasing power with platform-integrated reagent suppliers.
EMA's IVDR classification shift for blood screening devices is elevating clinical performance studies to mandatory status for CE marking renewal. Manufacturers must now submit diagnostic sensitivity data from prospectively collected donor samples rather than archived retrospective panels. European blood establishments are responding by consolidating supplier relationships with firms possessing established notified body rapport and post-market surveillance infrastructure.
Outcome-based reagent contracting is displacing transactional volume pricing in multi-hospital systems. Procurement committees in integrated delivery networks now negotiate cost-per-negative-screen metrics that transfer false-positive rate risk to diagnostic vendors. This model is most visible in United States regional blood centers serving consolidated health systems across multiple states.
Blood Borne Testing Market Segmentation
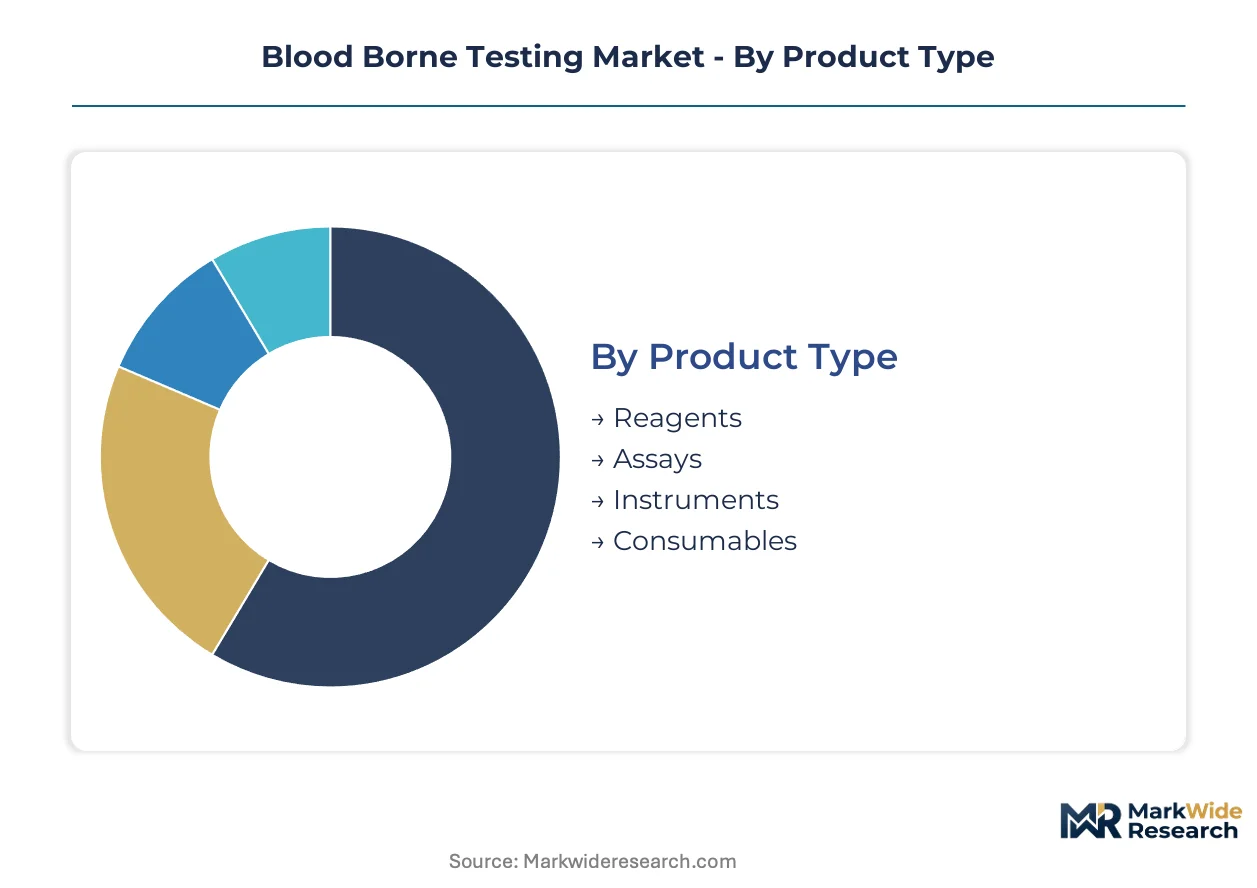
Segmentation in blood borne testing reflects divergent procurement logics across centralized transfusion services and decentralized clinical sites. Technology choice, consumable dependency, and regulatory complexity tier the addressable market into distinct commercial battlegrounds.
Product Type:
Proprietary chemistries and instrument footprints lock blood establishments into multi-year consumable commitments.
- Reagents:Enzyme conjugates, nucleic acid extraction buffers, and master mixes constitute the highest-recurring revenue stream. United States hospital laboratories consume these in continuous batch workflows tied to donor screening volumes.
- Assays:Pre-formulated test kits with calibrators and controls simplify regulatory compliance for mid-sized diagnostic laboratories. Demand concentrates in Germany as blood establishments consolidate supplier relationships under IVDR documentation pressure.
- Instruments:Automated nucleic acid platforms and random-access analyzers require capital allocation cycles spanning five to seven years.
- Consumables:Pipette tips, reaction vessels, and sample collection tubes face price pressure from generic manufacturers.
Mature deployment sits with Reagents. Newer deployment is concentrated in Assays.
Application:
Screening intensity varies by patient population risk stratification and surgical urgency.
- Infectious Diseases:HIV, HBV, and HCV viral load monitoring demands quantitative sensitivity below one copy per milliliter. Japan's national health insurance reimbursement structure favors high-sensitivity molecular protocols in tertiary hospital infectious disease departments.
- Blood Screening:Donor eligibility determination requires serological and nucleic acid dual testing algorithms. United States regional blood centers are the primary procurement authority for high-throughput triplex assays.
- Diagnostic Testing:Symptomatic patient workups in emergency departments use rapid immunoassay formats.
- Transfusion Services:Pre-transfusion compatibility testing and pathogen-reduced product verification occur in hospital-based blood banks.
Revenue scale favors Blood Screening. Volume expansion is climbing the fastest in Infectious Diseases.
End User:
Procurement authority fragments between centralized laboratory networks and satellite collection facilities.
- Hospitals:Integrated delivery networks negotiate multi-year reagent contracts covering transfusion services, emergency departments, and outpatient clinics. United States health systems with captive blood donor centers command the steepest volume discounts.
- Blood Banks:Independent regional centers and American Red Cross affiliates maintain dedicated quality management systems for donor screening. Germany's hemovigilance reporting mandates drive nucleic acid confirmation adoption.
- Diagnostic Laboratories:Commercial reference laboratories process send-out samples from physician offices and smaller hospitals.
- Clinics:Federally qualified health centers and mobile collection units deploy CLIA-waived rapid tests.
Installed instrument base concentrates in Hospitals. Procurement flexibility is expanding most quickly in Clinics.
Technology:
Detection chemistry determines sensitivity thresholds, throughput capacity, and technician skill requirements.
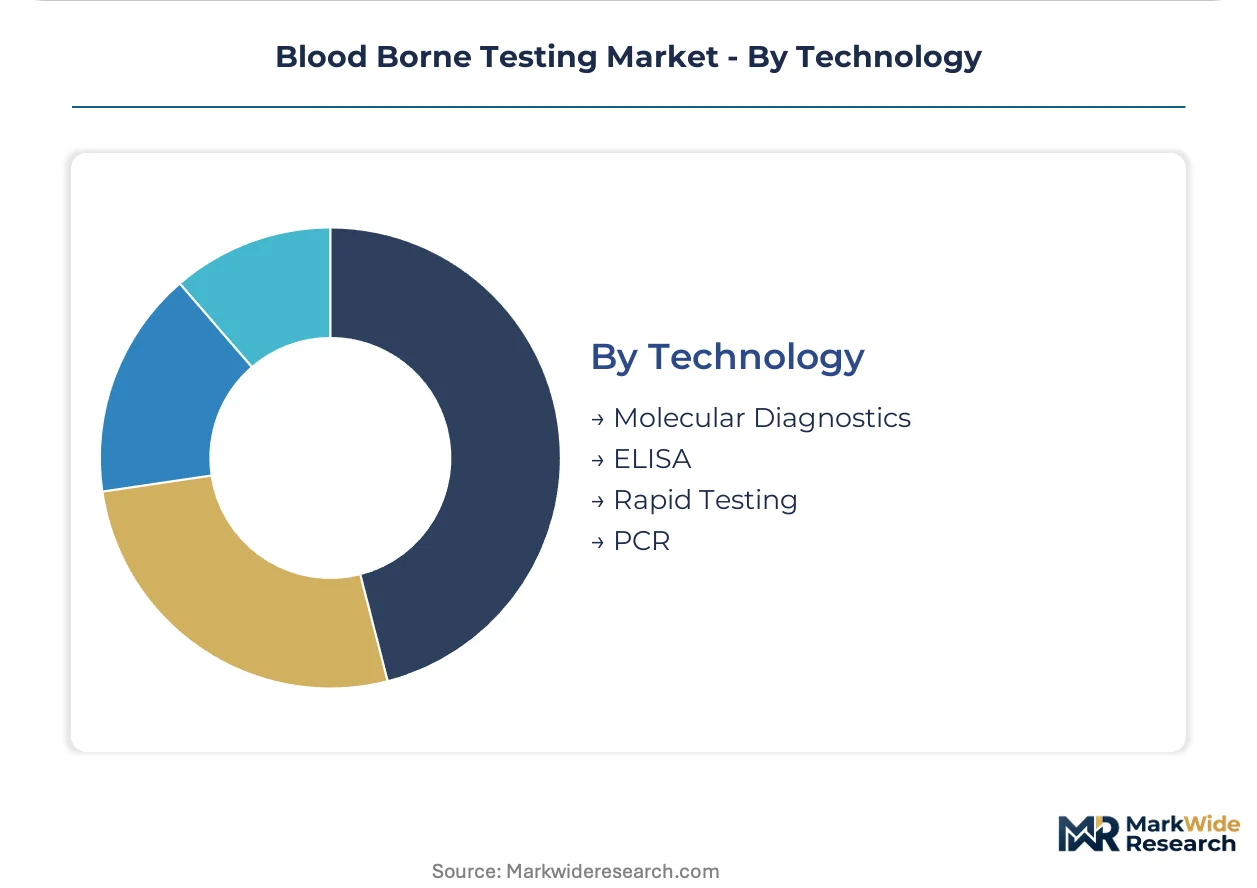
- Molecular Diagnostics:Real-time PCR and transcription-mediated amplification enable simultaneous multi-pathogen detection with quantitative viral load reporting. United States academic medical centers are replacing standalone serological workflows with integrated molecular platforms.
- ELISA:Enzyme-linked immunosorbent assays remain the cost benchmark for high-volume antibody screening in resource-constrained settings. Japan's regional blood centers maintain these for initial donor triage.
- Rapid Testing:Lateral flow immunoassays deliver results in fifteen minutes without laboratory infrastructure.
- PCR:Conventional thermal cycling with gel-based detection persists in research and surveillance applications.
Regulatory validation depth sits with ELISA. Platform consolidation is gaining share fastest in Molecular Diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital laboratory automation and national hemovigilance mandates are concentrating procurement authority in three countries. Blood bank infrastructure spending follows regulatory enforcement intensity rather than population scale alone.
United States
FDA blood donor deferral policy revisions and CLIA-waived rapid test authorizations are fragmenting procurement between centralized laboratories and satellite collection sites. The country's national pharmaceutical regulator maintains nucleic acid testing as mandatory for all reactive serological screens. Regional blood centers across the Midwest and Southeast are consolidating supplier relationships under outcome-based reagent contracting models.
Germany
EMA's IVDR classification shift is extending technical file preparation timelines for blood screening device manufacturers. The country's notified body infrastructure favors firms with established post-market surveillance capabilities. Blood establishments in Bavaria and North Rhine-Westphalia are deepening nucleic acid confirmation adoption under federal hemovigilance reporting mandates.
Japan
METI-coordinated national health insurance reimbursement structures favor high-sensitivity molecular protocols in tertiary hospital infectious disease departments. PMDA regulatory pathways maintain stringent performance documentation requirements for viral load quantification assays. Academic medical centers in the Kanto region are replacing standalone serological workflows with integrated molecular platforms.
United Kingdom
NHS Blood and Transplant procurement frameworks are consolidating screening capacity into fewer high-throughput regional hubs. The country's national pharmaceutical regulator aligns device approval pathways with EMA technical standards while maintaining sovereign post-market surveillance authority. Blood processing facilities in Greater London and the Midlands are prioritizing modular platform architectures for emerging pathogen panel expansion.
Switzerland
Swissmedic's convergence with EU regulatory standards is streamlining multi-regional commercialization pathways for blood safety device manufacturers. The country's precision diagnostics cluster leverages proximity to German and French manufacturing networks. Basel-area transfusion services are adopting decentralized analyzer footprints suited for blood bank satellite sites in Alpine catchment areas.
Blood Borne Testing Market Competitive Landscape
Integrated instrument-software platform development dominates the current landscape as manufacturers seek to lock blood establishments into captive reagent demand. The vendor base concentrates around three strategic archetypes: diversified life science conglomerates with regulatory infrastructure depth, specialized diagnostics firms with modular molecular expertise, and blood bank automation specialists with decentralized deployment capabilities. Platform consolidation and outcome-based contracting represent the two dominant competitive moves reshaping procurement relationships.
Within the diversified conglomerate tier, Abbott Laboratories, F. Hoffmann-La Roche Ltd, and Siemens Healthineers AG occupy positions defined by instrument placement scale and multi-regional approval pathway navigation. Abbott exemplifies the integrated platform archetype through its sustained high-throughput screening workflow focus. Roche anchors the viral load quantification specialization vector with deep menu expansion capabilities. Siemens represents the decentralized analyzer footprint strategy suited for blood bank satellite site penetration. These three firms collectively shape procurement committee evaluation criteria across United States regional blood centers and German hospital networks.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Becton Dickinson and Company |
| Thermo Fisher Scientific Inc. |
| bioMérieux SA |
| Grifols S.A. |
| Others |
Value Network & Pricing Analysis
United States regional blood centers and German hospital networks command concentrated purchasing power that locks suppliers into multi-year reagent contracts with outcome-based pricing clauses. This buyer concentration enables volume-tiered negotiation leverage while squeezing margins on standalone instrument sales.
Pricing Analysis
High-throughput screening volumes run on razor-thin per-test margins while specialized viral load quantification retains premium pricing power. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform-locked reagents from generic consumables and rapid immunoassay formats. Cost compression in standard-tier ELISA reagents is intensifying because blood establishments consolidate supplier relationships under IVDR documentation pressure. Mid-sized diagnostic laboratories exhibit highest price sensitivity, whereas academic medical centers prioritize sensitivity thresholds over unit economics.
Supply Chain Analysis
Proprietary enzyme conjugates and nucleic acid extraction buffers rest on United States, German, and Japanese specialty chemical producers with FDA-inspected manufacturing facilities. Master mix formulations, fluorescent probe chemistries, and automated reaction vessels feed from concentrated life science conglomerates with captive polymer synthesis capabilities. Single-source vulnerability in CLIA-waived rapid test membrane materials exposes procurement committees to tariff exposure on lateral flow components. Distribution runs through regional blood center consortia and integrated delivery network central warehouses with temperature-controlled logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-integrated reagent suppliers as IVDR performance documentation requirements force weaker players without established notified body rapport toward exit or acquisition.
For Market Incumbents: Cement captive reagent demand through modular platform architectures that accommodate emerging pathogen panels without full system replacement. Deepen post-market surveillance infrastructure to accelerate CE marking renewals under EMA's elevated clinical evidence requirements. Defend against specialized diagnostics firms by anchoring viral load quantification specialization with deep menu expansion.
For New Entrants and Emerging Players: Blood bank satellite sites in rural Alpine and Midwest catchment areas represent the most penetrable deployment opportunity given decentralized analyzer footprint gaps. Target CLIA-waived rapid test procurement conversations with mobile collection units and federally qualified health centers outside metropolitan hospital networks. Pursue WHO prequalification alignment to unlock consolidated tender opportunities across low- and middle-income country procurement frameworks.
For Investors and Strategic Acquirers: The window for entry favors modular molecular expertise specialists with established regulatory infrastructure depth. Long-term viability hinges on nucleic acid amplification protocol replacement cycles extending five to ten years as laboratories phase out serological screening. Watch FDA blood donor deferral policy revisions as the primary inflection signal for procurement authority fragmentation between centralized and satellite sites.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Architecture Development | Enables arbovirus and Babesia panel expansion without full instrument replacement for blood establishments. |
| IVDR Technical File Preparation Acceleration | Shortens CE marking timelines through prospectively collected donor sample performance studies. |
| Outcome-Based Reagent Contracting | Transfers false-positive rate risk to vendors under cost-per-negative-screen metrics in United States regional centers. |
| Decentralized Analyzer Footprint Expansion | Opens procurement conversations with blood bank satellite sites in rural German and Swiss Alpine catchment areas. |
| WHO Prequalification Alignment | Creates consolidated tender access across harmonized blood safety standards in low- and middle-income procurement frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with blood bank quality managers, hospital laboratory directors, clinical laboratory scientists, and GPO contracts managers combined with FDA 510(k) summaries, EMA IVDR technical documentation, and WHO prequalification listings. Bottom-up instrument placement counts and top-down hemovigilance program spending estimates underwent cross-validation.
Data-stream reconciliation across the analysis window triangulated reagent consumption volumes, instrument installed base depreciation schedules, and national screening mandate enforcement timelines. Segmentation modeling incorporated technology type, product category, end-user procurement authority, and geographic regulatory cluster dimensions. CAGRs derived from weighted average of historical volume trajectories and policy-driven adoption curve projections, with nucleic acid confirmation mandate implementation schedules and CLIA-waiver expansion pathways as key forecast inputs.
Caveats apply where IVDR notified body capacity constraints or FDA blood donor deferral policy reversals could materially shift the outlook. Forecasts reflect assumptions regarding hemovigilance program deepening continuity and molecular platform replacement cycle stability. A small set of named triggers—regulatory approval pathway delays, proficiency testing logistics disruptions, and specialized technician training pipeline shortfalls—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Ovulation Test Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
Global Endotoxin and Pyrogen Testing Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Active B12 Test Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Europe IVD Regulatory Affairs Outsourcing Market
Testing Services
Bioprocess Integrity Testing Systems Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
Nipah Virus Testing Market
Testing Services
Esoteric Testing Market