
 Asia Pacific Sterility Testing Market | 2026-2036
Asia Pacific Sterility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Sterility Testing Market Outlook
Modular service bundling is hardening as the dominant procurement pattern across Asia Pacific sterility testing. Thermo Fisher Scientific leverages its integrated analytical instrument and consumables portfolio to anchor multi-year contracts with biopharma manufacturers. WuXi AppTec sustains competitive positioning through captive laboratory networks spanning China and Singapore. Charles River Laboratories differentiates by specializing in complex biologics sterility validation for cell and gene therapy developers.
Asia Pacific sterility testing encompasses microbiological validation protocols that detect viable and non-viable contaminants in pharmaceutical, biologic, and medical device products, typically employing membrane filtration with pore sizes of 0.45 micrometers or smaller followed by incubation in fluid thioglycollate medium and soybean-casein digest broth. These methods ensure compliance with pharmacopeial standards for parenteral drug release and implantable device safety. Membrane filtration dominates current revenue pools due to its regulatory acceptance for low-turbidity samples, while rapid testing methods represent the fastest-expanding segment as ATP bioluminescence and PCR-based approaches shorten batch release timelines. Pharmaceutical applications command the largest share of testing volume, though biotechnology applications are widening fastest as monoclonal antibody and vaccine manufacturing scales across the region.
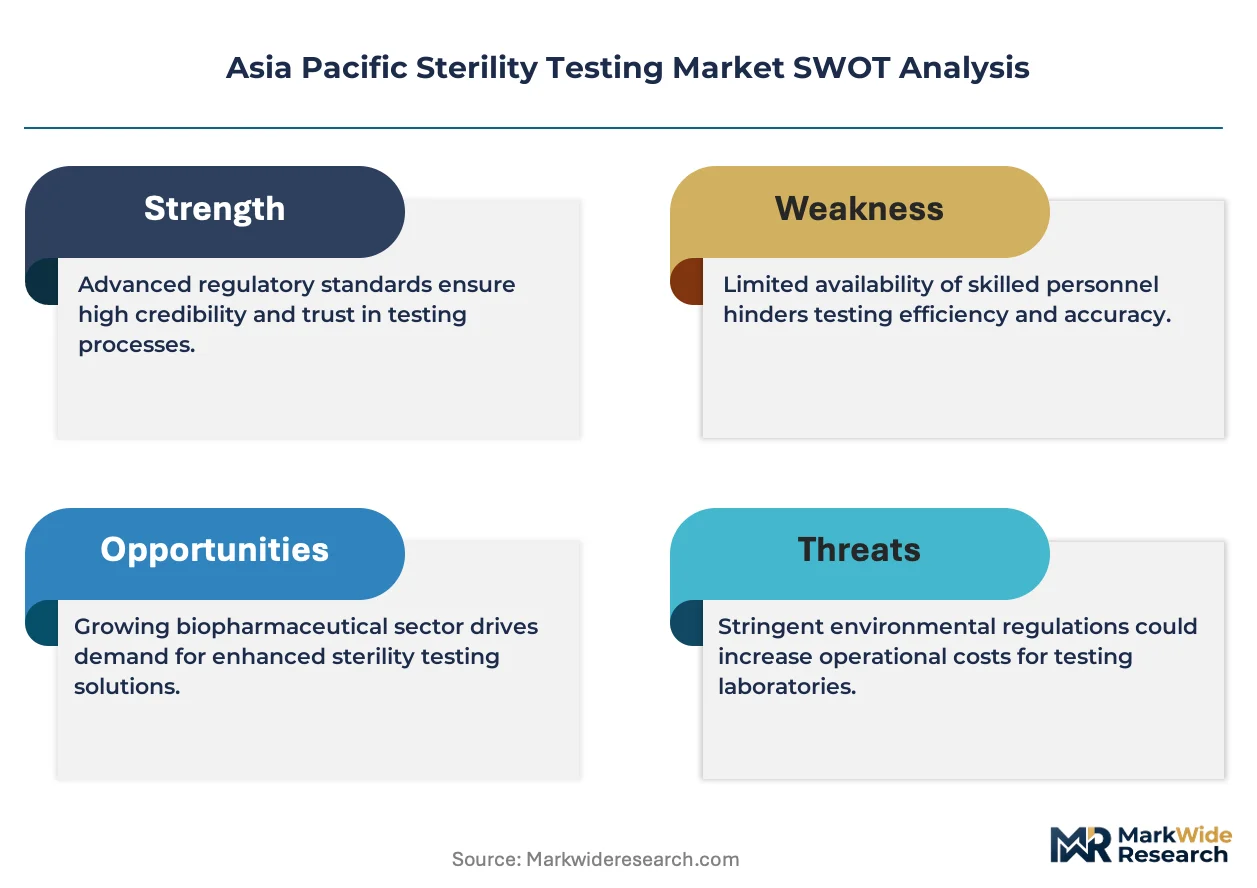
China's NMPA and India's CDSCO enforce harmonized pharmacopeial standards that mandate sterility validation for all parenteral drug approvals, directly shaping laboratory accreditation requirements and capital equipment demand. Japan's PMDA and South Korea's MFDS maintain stringent GMP inspection regimes that compel domestic manufacturers to maintain in-house sterility testing capacity or contract with certified providers. Stakeholders must monitor evolving regulatory convergence between national pharmacopeias and ICH Q5A guidelines to anticipate shifts in acceptable rapid method validation pathways.
Market Dynamics
Membrane filtration equipment suppliers in South Korea and Singapore are consolidating quality control budgets as biologics contract testing organizations demand faster batch release timelines. This concentration is compressing testing protocol development cycles and reshaping vendor selection criteria across the region.
Growth Catalysts
- NMPA GMP Enforcement:China's tightened pharmacopeial compliance mandates are compelling domestic pharmaceutical manufacturers to expand in-house sterility validation capacity or secure multi-year contracts with certified testing providers.
- Cell and Gene Therapy Manufacturing:The expansion of advanced therapy medicinal product facilities in Japan and South Korea is generating specialized sterility testing demand for complex biologics with non-standard contamination profiles.
- Membrane Filtration Automation:Automated membrane filtration systems are reducing technician handling errors and shortening incubation-to-result intervals for high-volume parenteral drug manufacturers.
Market Restraints
- Fluoropolymer Membrane Supply Concentration:Japan and Germany dominate specialized 0.22-micrometer membrane production, exposing Asia Pacific laboratories to currency volatility and extended lead times for critical consumables.
- CDSCO Validation Timeline Friction:India's phased implementation of harmonized pharmacopeial standards creates uncertainty for contract testing organizations awaiting formal recognition of rapid microbiological methods.
- Rapid Method Substitution Threat:ATP bioluminescence and PCR-based approaches are displacing traditional culture-based protocols in early-stage bioprocessing, threatening revenue pools for established membrane filtration service providers.
Strategic Opportunities
- Vietnam and Indonesia Biopharma Expansion:Underpenetrated markets in Southeast Asia are attracting contract testing organizations seeking to anchor regional hub operations ahead of domestic manufacturing scale-up.
- ICH Q5A Convergence:Alignment between national pharmacopeias and international guidelines is creating regulatory tailwinds for rapid method validation pathways, reducing time-to-market for novel testing technologies.
- Digital Twin Integration:Convergence of laboratory information management systems with real-time environmental monitoring is enabling predictive contamination risk modeling for continuous manufacturing lines.
Industry Challenges
- Aseptic Technique Certification Bottlenecks:MFDS and PMDA inspection regimes demand documented technician competency programs that extend onboarding timelines for new laboratory staff in Japan and South Korea.
- Legacy System Integration Complexity:Paper-based batch records and standalone incubation monitoring equipment in established facilities complicate data integrity compliance with ALCOA+ principles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Sterility Testing Market |
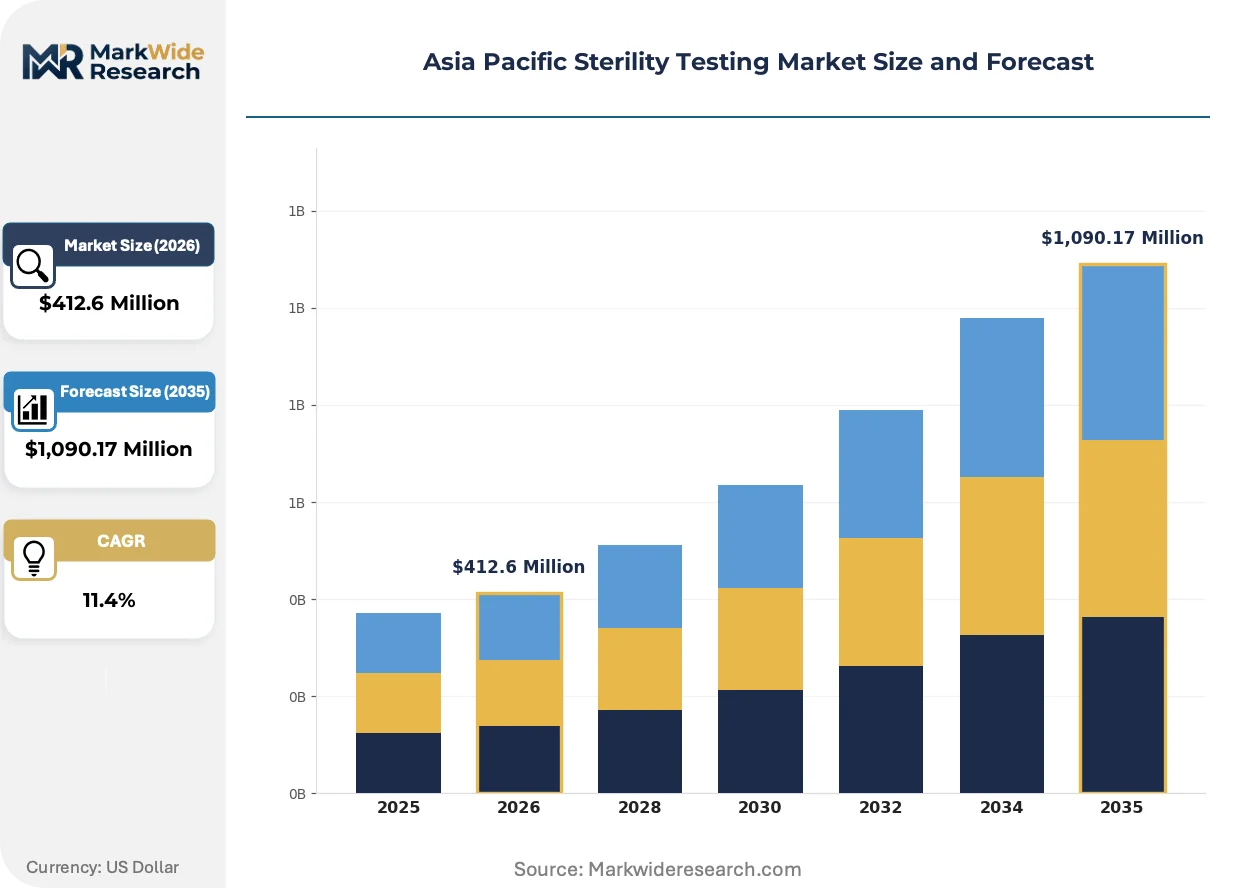
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,090.17 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filtration, Direct Transfer, Viable Method, Non-Viable Method Application: Pharmaceuticals, Biotechnology, Medical Devices, Diagnostics End User: Hospitals, Laboratories, Research Institutions, Quality Control Technology: Automation, Manual Testing, Rapid Testing, Advanced Sterilization |
| Companies Covered | Sartorius AG, Auriga Research, Thermo Fisher Scientific, Inc., WuXi AppTec Co., Ltd., Samsung Biologics Co., Ltd., Charles River Laboratories International, Inc., STERIS AST, SGS S.A., Merck KGaA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Sterility Testing Market Strategic Shifts
Rapid microbiological methods are compressing sterility confirmation timelines from fourteen days to under seventy-two hours, forcing established testing protocols to demonstrate equivalence or risk displacement. This acceleration is reshaping capital allocation across pharmaceutical quality control functions.
Automated membrane filtration workstations are unifying sample preparation, filtration, and incubation initiation into continuous processing sequences. Biologics contract manufacturers in Singapore and South Korea are deploying these systems to eliminate technician transfer steps. This unification is reducing contamination risk while enabling real-time environmental monitoring integration.
PMDA's implementation of ICH Q5A guidelines for viral safety evaluation is mandating enhanced sterility validation documentation for cell and gene therapy products. Japanese manufacturers must now demonstrate process-specific contamination control strategies beyond standard pharmacopeial methods. Cell therapy developers are responding by embedding rapid sterility testing earlier in manufacturing workflows.
Multi-year analytical service contracts are displacing transactional testing arrangements as biopharma procurement teams consolidate vendor panels. Contract testing organizations in China and India are capturing volume through integrated instrument-consumables-service bundles. This concentration is most visible among mid-sized biotechnology companies lacking captive laboratory infrastructure.
Asia Pacific Sterility Testing Market Segmentation
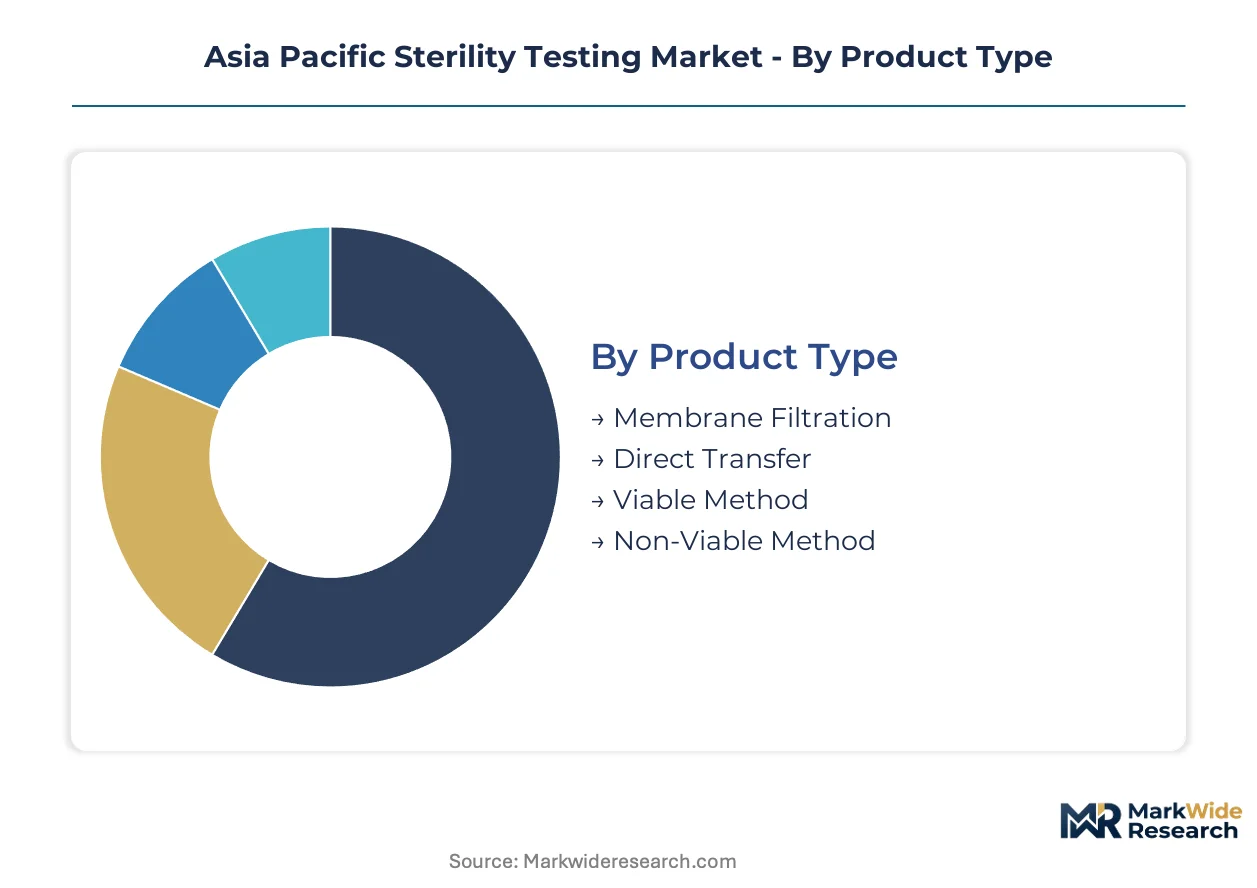
Sterility testing procurement in Asia Pacific fragments across equipment intensity, regulatory complexity, and end-user sophistication. Capital allocation patterns differ sharply between automated membrane filtration systems for high-volume pharmaceutical manufacturers and manual protocols for research institutions with intermittent testing needs.
Product Type:
Membrane filtration commands the heaviest upfront capital burden, with automated workstations requiring six-figure equipment investments alongside specialized consumables supply chains.
- Membrane Filtration:Pore sizes of 0.45 micrometers or smaller capture viable contaminants from low-turbidity parenteral solutions, followed by incubation in fluid thioglycollate medium and soybean-casein digest broth. Pharmaceutical manufacturers in India and China are expanding membrane filtration capacity as NMPA and CDSCO tighten GMP enforcement timelines.
- Direct Transfer:Direct inoculation of test articles into growth media suits high-turbidity samples and medical devices with complex geometries unsuited to filtration. South Korean biologics contract manufacturers favor direct transfer for cell therapy products with non-standard contamination profiles.
- Viable Method:Culture-based detection of living microorganisms remains the regulatory default for final batch release documentation across Asia Pacific pharmacopeias.
- Non-Viable Method:Particle counting and environmental monitoring support process control but require correlation to viable methods for regulatory acceptance.
Most installed capacity flows through membrane filtration. Expansion is steepest in direct transfer.
Application:
Volume concentration varies by manufacturing scale and regulatory scrutiny intensity, with biotechnology applications showing the most rapid capacity additions.
- Pharmaceuticals:Parenteral drug manufacturing generates the largest absolute testing volume across Asia Pacific, driven by sterile injectable production for domestic and export markets. Chinese and Indian manufacturers are consolidating quality control functions to meet harmonized pharmacopeial standards.
- Biotechnology:Monoclonal antibody and vaccine manufacturing scales are widening fastest, with Singapore and South Korean facilities embedding sterility testing earlier in continuous bioprocessing workflows. Cell and gene therapy developers in Japan face PMDA-mandated enhanced validation documentation.
- Medical Devices:Implantable device sterilization validation requires demonstration of sterility assurance levels per ISO standards, with testing concentrated in manufacturing hubs rather than clinical settings.
- Diagnostics:In vitro diagnostic reagent manufacturing requires sterility confirmation for culture media and control materials, representing a specialized niche with distinct accreditation requirements.
Pharmaceuticals anchor current revenue pools. Biotechnology is climbing the fastest.
End User:
Customer type determines service model preferences, with integrated manufacturers favoring captive laboratories and emerging biotechs outsourcing to contract testing organizations.
- Hospitals:Compounding pharmacies and central sterile supply departments perform environmental monitoring and product sterility checks, though regulatory complexity drives outsourcing for specialized validations.
- Laboratories:Contract testing organizations in China and Singapore capture multi-year analytical service contracts through integrated instrument-consumables bundles, displacing transactional arrangements.
- Research Institutions:Academic and government laboratories employ manual testing protocols with lower throughput requirements, prioritizing flexibility over automation.
- Quality Control:In-house pharmaceutical quality functions maintain sterility testing capacity for batch release, with capital investment decisions shaped by MFDS and PMDA inspection regimes in Japan and South Korea.
Laboratories concentrate commercial service revenue. Quality control functions are gaining share fastest through insourcing trends.
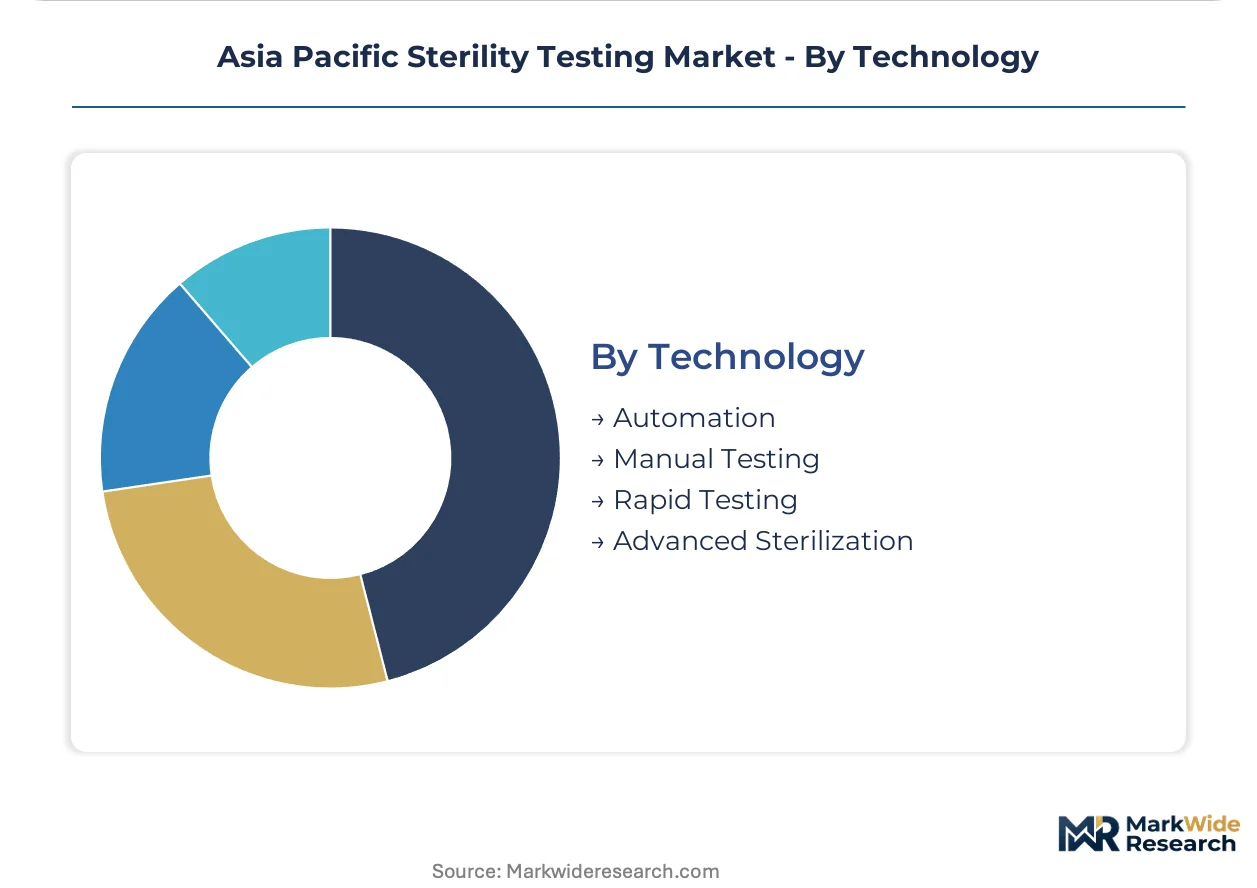
Technology:
Automation intensity separates capital deployment strategies, with rapid testing methods demanding novel validation pathways against established pharmacopeial references.
- Automation:Automated membrane filtration workstations unify sample preparation, filtration, and incubation initiation, eliminating technician transfer steps. Biologics contract manufacturers in Singapore deploy these systems for real-time environmental monitoring integration.
- Manual Testing:Technician-dependent protocols persist where volume variability or regulatory conservatism delays automation adoption, particularly in research and early-phase manufacturing settings.
- Rapid Testing:ATP bioluminescence and PCR-based approaches compress confirmation timelines from fourteen days to under seventy-two hours, though CDSCO and NMPA recognition of rapid method validation pathways remains uneven.
- Advanced Sterilization:Vaporized hydrogen peroxide and nitrogen dioxide sterilization validation for isolators and restricted access barrier systems supports continuous manufacturing line qualification.
Automation dominates capital expenditure. Rapid testing is expanding most quickly as regulatory convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sterility validation originated in post-war Japan before spreading to manufacturing hubs across East Asia. The Asia Pacific market now fragments across regulatory jurisdictions with divergent pharmacopeial recognition timelines.
China
Domestic vaccine and biologics manufacturers are expanding membrane filtration capacity ahead of NMPA's 2025 GMP inspection surge. The regulator's harmonization with ICH Q5A guidelines is accelerating rapid method validation submissions. Shanghai and Suzhou biotech clusters host the densest concentration of new contract testing facilities.
Japan
PMDA's stringent aseptic technique certification requirements are extending technician onboarding timelines for cell therapy developers. The regulator mandates enhanced sterility documentation for advanced therapy medicinal products beyond standard pharmacopeial methods. Osaka and Kobe manufacturing corridors are embedding rapid testing earlier in continuous bioprocessing workflows.
India
CDSCO's phased pharmacopeial harmonization is creating validation timeline friction for contract testing organizations adopting ATP bioluminescence. Domestic injectable manufacturers are consolidating quality control functions to meet tightened GMP enforcement. Hyderabad and Bangalore pharmaceutical clusters are driving membrane filtration equipment procurement.
South Korea
MFDS inspection regimes compel domestic manufacturers to maintain documented technician competency programs for aseptic operations. Samsung Biologics and domestic CDMOs are deploying automated membrane filtration workstations to eliminate technician transfer steps. Songdo and Incheon biologics hubs are unifying sample preparation with real-time environmental monitoring.
Singapore
Tuas Biomedical Park and one-north research corridors are attracting contract testing organizations seeking regional hub status ahead of Southeast Asian manufacturing scale-up. The city-state's alignment with international pharmacopeial standards is reducing regulatory friction for rapid method adoption. Biologics contract manufacturers are capturing multi-year analytical service contracts through integrated instrument-consumables bundles.
Asia Pacific Sterility Testing Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory complexity and automation intensity. The vendor base stratifies into three tiers: integrated analytical instrument conglomerates, captive laboratory network operators, and specialized biologics validation providers. Consolidation is compressing around multi-year service contracts and integrated consumables supply. Dominant competitive moves include geographic hub anchoring in underpenetrated Southeast Asian markets and rapid method validation pathway development.
Among diversified analytical conglomerates, Thermo Fisher Scientific, Inc. and Merck KGaA occupy positions anchored by instrument-consumables-service integration. Sartorius AG exemplifies the membrane filtration equipment archetype with German engineering heritage. Within the Asia Pacific contract testing tier, WuXi AppTec Co., Ltd. and Charles River Laboratories International, Inc. represent divergent strategies: the former through captive laboratory network density across China and Singapore, the latter through complex biologics specialization for cell and gene therapy developers.
| Leading Market Players |
|---|
| Sartorius AG |
| Auriga Research |
| Thermo Fisher Scientific, Inc. |
| WuXi AppTec Co., Ltd. |
| Samsung Biologics Co., Ltd. |
| Charles River Laboratories International, Inc. |
| STERIS AST |
| SGS S.A. |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Fluoropolymer membrane spot prices in Japan and Germany cascade through Asia Pacific sterility testing supply chains, compressing margins for contract laboratories while amplifying pricing power for integrated instrument-consumables bundlers. NMPA and CDSCO inspection timelines intensify cost pressure on domestic manufacturers seeking rapid method validation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automated membrane filtration workstations from manual protocols and rapid testing service bundles. Certification grade under MFDS and PMDA regimes commands substantial premiums over baseline pharmacopeial compliance. Cost compression in economy-tier manual testing is intensifying because of CDSCO's phased harmonization delays. Emerging biotechs without captive infrastructure exhibit highest price sensitivity; multinational pharmaceutical manufacturers with consolidated vendor panels show lowest.
Supply Chain Analysis
Direct-to-biopharma channels handle high-volume contract testing demand while distributor networks serve research institutions with intermittent procurement patterns. Specialized 0.22-micrometer membrane production concentrates in Japan and Germany, with secondary fluoropolymer processing in South Korea and Singapore. Consumables supply rests on perfluoroalkoxy resin and polytetrafluoroethylene feedstock availability. Single-source vulnerability around German membrane engineering exposes Asia Pacific laboratories to extended lead times. Distribution runs through integrated analytical conglomerates with captive logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific sterility testing has entered late-cycle quality differentiation, with PMDA's ICH Q5A implementation and NMPA's 2025 inspection surge shifting procurement toward premium rapid method validation capabilities.
For Market Incumbents: Cement multi-year service contract renewal rates by embedding predictive contamination risk modeling into continuous manufacturing workflows. Capture backward integration into fluoropolymer membrane distribution to offset supply concentration risk. Defend against ATP bioluminescence substitution by accelerating rapid method equivalence documentation ahead of regulatory convergence.
For New Entrants and Emerging Players: Begin with Vietnam and Indonesia biopharma clusters where domestic manufacturing scale-up has outpaced local testing infrastructure. Target cell and gene therapy developers in Japan facing PMDA-mandated enhanced validation documentation as the most penetrable segment. Lead with digital twin integration capabilities that incumbent laboratories have delayed deploying.
For Investors and Strategic Acquirers: Asymmetric upside sits with contract testing organizations possessing rapid method validation pathways already recognized by MFDS or PMDA. Long-term viability centers on regulatory convergence acceleration across the analysis window. Target acquisition archetype: mid-sized laboratories with established technician competency programs in Songdo or Tuas Biomedical Park. Watch CDSCO's formal recognition of ATP bioluminescence as inflection indicator for rapid method substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Rapid Method Validation Pathway Development | CDSCO and NMPA recognition of ATP bioluminescence shortens batch release timelines for biologics manufacturers. |
| Backward Integration into Membrane Distribution | Captive fluoropolymer supply chains insulate laboratories from Japanese and German production volatility. |
| Digital Twin Integration for Continuous Manufacturing | Predictive contamination risk modeling aligns with PMDA's ICH Q5A documentation requirements. |
| Regional Hub Anchoring in Southeast Asia | Vietnam and Indonesia facilities capture biopharma manufacturing migration ahead of domestic testing scale-up. |
| Technician Competency Program Certification | MFDS and PMDA-mandated aseptic technique documentation extends competitive moats for established laboratories. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with quality control directors, regulatory affairs managers at NMPA and CDSCO, contract testing organization procurement leads, and biologics manufacturing executives with secondary validation. Bottom-up and top-down triangulation incorporated pharmacopeial harmonization documentation, GMP inspection disclosure databases, membrane filtration equipment import records, and clinical trial sterility validation protocols.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-inspection surge demand spikes. Segmentation dimensions modeled include product type, application, end user, technology tier, and regulatory jurisdiction cluster. CAGRs were derived from equipment procurement pipelines and consumables replenishment cycles across the analysis window. Forecast inputs incorporated NMPA inspection schedule density and ICH Q5A implementation timelines.
Several conditions sit outside the modeled scope, including geopolitical disruption to fluoropolymer trade flows and unscheduled regulatory delays beyond published harmonization roadmaps. Forecasts reflect assumptions about technician certification throughput and rapid method equivalence study completion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Vials Leak Testing Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Tablet Hardness Testers Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Ovulation Test Kit Market
Testing Services
US Viral Clearance Market
Testing Services
Americas Sterility Testing Market