
 Urodynamic Testing Market | 2026-2036
Urodynamic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Urodynamic Testing Market Analytics
Aftermarket service revenue is reshaping margin distribution across the urodynamic testing landscape. Laborie leverages its installed base of diagnostic platforms to sustain recurring calibration and maintenance contracts. Medtronic anchors its position through deep integration of pressure-sensing catheters with proprietary software ecosystems.
Urodynamic testing encompasses the physiological measurement of bladder and urethral function during filling and voiding phases, employing pressure transducers, flowmeters, and electromyography electrodes to quantify detrusor pressure, urine flow rate, and sphincter activity for diagnosing lower urinary tract dysfunction. Cystometry equipment dominates capital expenditure budgets due to its complexity and disposable catheter consumption, while remote monitoring delivery modes are gaining fastest traction as telemedicine reimbursement codes mature and patients seek alternatives to repeated clinic visits. Uroflowmetry remains the most mature product segment with commoditized pricing and limited differentiation among manufacturers.
FDA 510(k) clearance requirements and the EU MDR's clinical evidence standards shape product development timelines and market access barriers for new urodynamic device entrants. Japan's PMDA enforces stringent electrical safety and biocompatibility testing protocols that filter out smaller manufacturers lacking dedicated regulatory affairs teams. Stakeholders must monitor evolving digital health classification guidance from multiple regulators as software-enabled urodynamic analysis tools blur traditional hardware-software regulatory boundaries.
Market Dynamics
Specialty clinics are consolidating diagnostic workflows around software-integrated urodynamic platforms, compressing procurement cycles and elevating aftermarket service contracts as the primary margin lever for equipment vendors.
Growth Catalysts
- Aging Demographics in Developed Economies:Japan, Germany, and the United States face expanding patient pools with lower urinary tract dysfunction, sustaining procedural volume growth in hospital outpatient departments and ambulatory surgery centers.
- EU MDR Performance Validation:The Medical Device Regulation's tightened clinical evidence standards are filtering out marginal competitors, creating market access advantages for manufacturers with dedicated regulatory affairs infrastructure.
- Telemedicine Reimbursement Maturation:Remote monitoring delivery modes gain traction as CMS and private payers establish coverage codes for asynchronous urodynamic data review, reducing patient visit burden.
Market Restraints
- Capital Equipment Intensity:Cystometry systems require substantial upfront investment in pressure transducers, flowmeters, and EMG interfaces, constraining adoption among independent urology practices.
- Supply Concentration in Disposable Catheters:Single-use pressure-sensing catheters dominate recurring costs, with manufacturing concentrated among specialized polymer converters in Germany and the United States.
- Technical Limitation in Home-Based Testing:Patient-operated uroflowmetry devices lack standardized calibration protocols, producing variable data quality that limits clinical acceptance.
Strategic Opportunities
- Underpenetrated Ambulatory Settings:United States-based urology group practices represent expansion potential for compact, cart-based urodynamic systems with simplified operator training requirements.
- AI-Enabled Pressure Curve Analysis:Machine learning algorithms are hybridizing with conventional urodynamic software to automate detrusor pressure pattern recognition and reduce interpretation time.
- Japan PMDA Streamlined Review:Japan's Pharmaceuticals and Medical Devices Agency offers priority review pathways for software-as-medical-device urodynamic tools, accelerating market entry.
Industry Challenges
- Specialized Technician Scarcity:Urodynamic procedure performance requires certified urodynamic technologists, with training program capacity lagging demand in the United States and Germany.
- Legacy System Integration Friction:Hospital IT departments face interoperability challenges connecting proprietary urodynamic software with electronic health record systems.
- Extended FDA 510(k) Timelines:Digital health classification uncertainty for AI-augmented diagnostic features is prolonging regulatory review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urodynamic Testing Market |
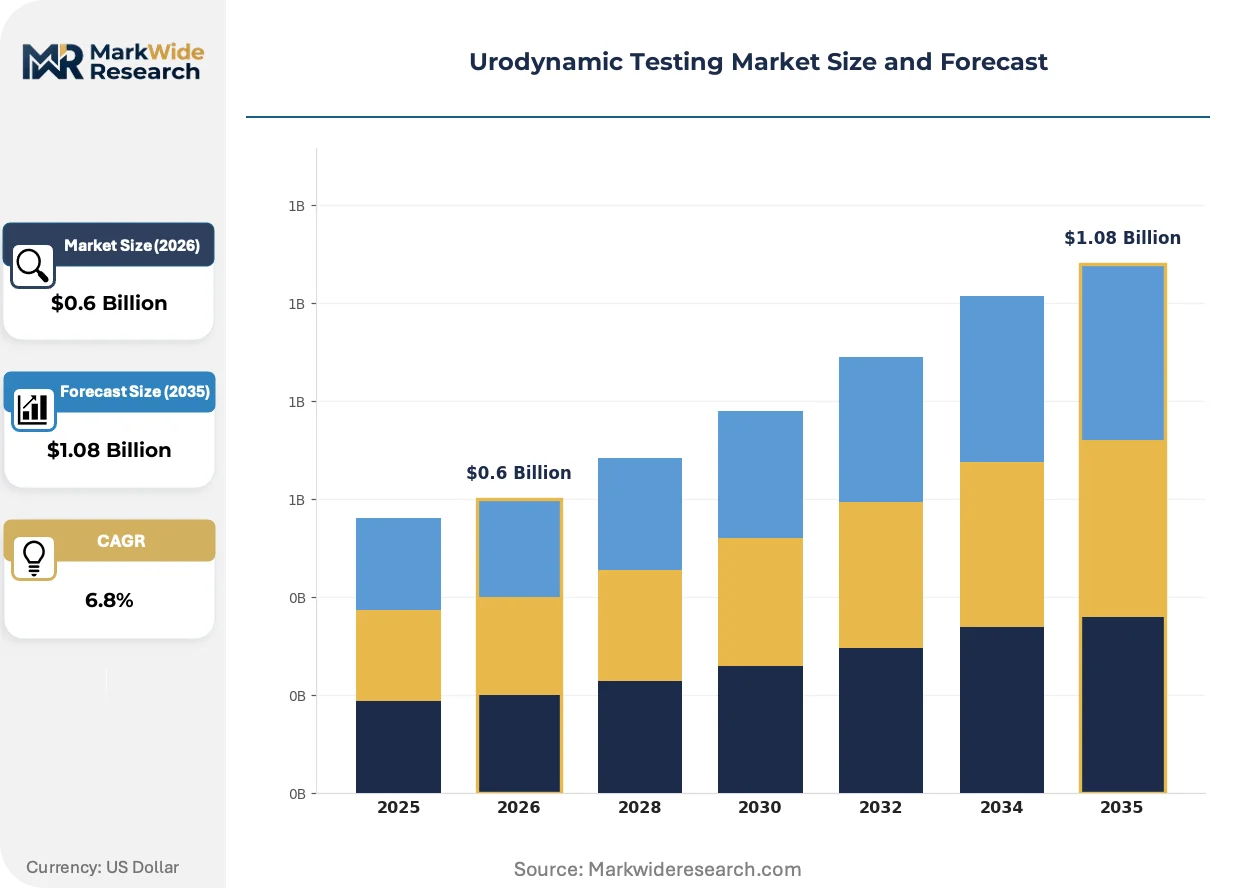
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uroflowmetry, Cystometry, Electromyography, Pressure Flow Studies Application: Incontinence, Prostate Cancer, Bladder Dysfunction, Neurogenic Bladder End User: Hospitals, Diagnostic Labs, Specialty Clinics, Research Institutions Delivery Mode: In-Clinic, Home Care, Remote Monitoring, Telemedicine |
| Companies Covered | Laborie, Boston Scientific Corporation, Medtronic, CooperSurgical, Verathon, Inc., Albyn Medical, SRS Medical, Karl Storz, Coloplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urodynamic Testing Market Evolving Landscape
Diagnostic workflows are fragmenting across care settings as manufacturers embed connectivity features and analytics capabilities directly into urodynamic hardware platforms.
Wireless pressure transducer technology is hybridizing with conventional catheter-based measurement systems, enabling real-time data transmission to tablet-based interfaces. Ambulatory surgery centers in the United States are adopting these platforms to streamline patient throughput. The structural consequence is compression of capital equipment replacement cycles as software updates substitute for hardware refreshes.
EU MDR clinical evidence requirements are reshaping product development resource allocation for urodynamic device manufacturers. The regulation mandates post-market surveillance systems and periodic safety update reports that extend time-to-market for novel catheter designs. European urology clinics are responding by consolidating purchases around established vendors with proven MDR technical documentation.
Subscription-based software licensing is displacing perpetual ownership models for urodynamic analysis platforms. Hospital procurement departments in Germany are negotiating multi-year service agreements that bundle hardware maintenance with algorithm updates. This shift concentrates purchasing authority within health system central offices and reduces vendor switching flexibility.
Urodynamic Testing Market Segmentation
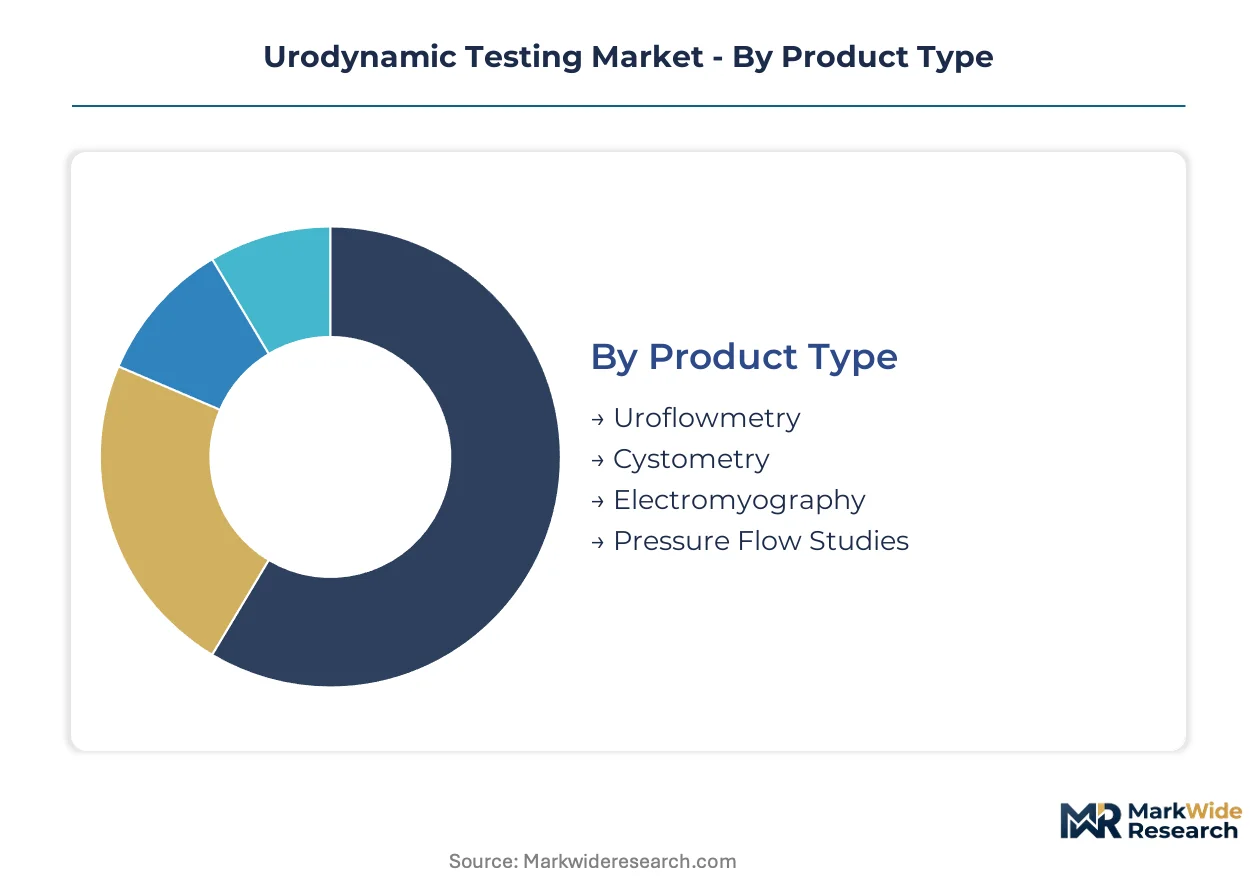
Urodynamic testing equipment manufacturers calibrate R&D pipelines and pricing architectures around four distinct segmentation axes. Product complexity and disposable consumption patterns vary dramatically across cystometry versus uroflowmetry platforms, while delivery mode selection increasingly determines reimbursement pathway eligibility.
Product Type:
Cost tier stratification separates capital-intensive pressure-sensing platforms from commoditized flow measurement devices.
- Cystometry:Multi-channel pressure transducer systems with integrated EMG interfaces quantify detrusor compliance and bladder capacity during controlled filling protocols. United States hospital outpatient departments concentrate procurement authority for these six-figure systems, with disposable catheter contracts extending vendor lock-in over seven-year depreciation cycles.
- Uroflowmetry:Gravimetric or rotating disc flowmeters measure voided volume and maximum flow rate through non-invasive urine collection. German urology group practices deploy compact desktop units in high-throughput screening workflows, though per-test reimbursement compression limits hardware refresh frequency to decade-plus intervals.
- Electromyography:Needle or surface electrode configurations assess external urethral sphincter coordination during voiding.
- Pressure Flow Studies:Synchronized urethral pressure profilometry combined with voiding pressure recording isolates bladder outlet obstruction etiology.
Cystometry commands the established base. The steepest expansion runs through pressure flow studies as prostate cancer staging protocols intensify.
Application:
Clinical indication priority determines equipment specification requirements and procedure reimbursement codes.
- Incontinence:Stress, urge, and mixed incontinence subtypes drive the majority of urodynamic referrals in aging populations. Japanese tertiary hospitals maintain dedicated urodynamic suites for complex incontinence phenotyping, with PMDA reimbursement codes favoring multi-channel pressure studies over simplified uroflowmetry.
- Neurogenic Bladder:Spinal cord injury, multiple sclerosis, and diabetic neuropathy produce detrusor-sphincter dyssynergia requiring comprehensive pressure-flow-EMG correlation. United States spinal cord injury centers concentrate demand for ambulatory urodynamic systems that accommodate wheelchair transfer protocols.
- Prostate Cancer:Pre-operative baseline and post-prostatectomy follow-up urodynamics guide surgical approach selection.
- Bladder Dysfunction:Interstitial cystitis and bladder pain syndrome presentations utilize urodynamics to exclude outlet obstruction.
Incontinence anchors current procedural volume. Neurogenic bladder applications are climbing the fastest as spinal cord injury survival rates improve.
End User:
Customer type dictates sales cycle length, service contract structure, and regulatory documentation burden.
- Specialty Clinics:Urology and urogynecology group practices in the United States consolidate purchasing through GPOs, negotiating bundled hardware-software-service agreements. These ambulatory settings prioritize compact footprint systems with simplified technician training requirements.
- Hospitals:Integrated delivery networks in Germany centralize urodynamic procurement within radiology or urology service lines, requiring HL7 FHIR connectivity and multi-language software interfaces.
- Diagnostic Labs:Independent reference laboratories offer urodynamic interpretation as outsourced service to rural urology practices.
- Research Institutions:Academic medical centers validate novel pressure-sensing catheter materials and wireless transmission protocols.
Hospitals retain the installed base majority. Specialty clinics are gaining share fastest as United States reimbursement shifts toward site-neutral payment.
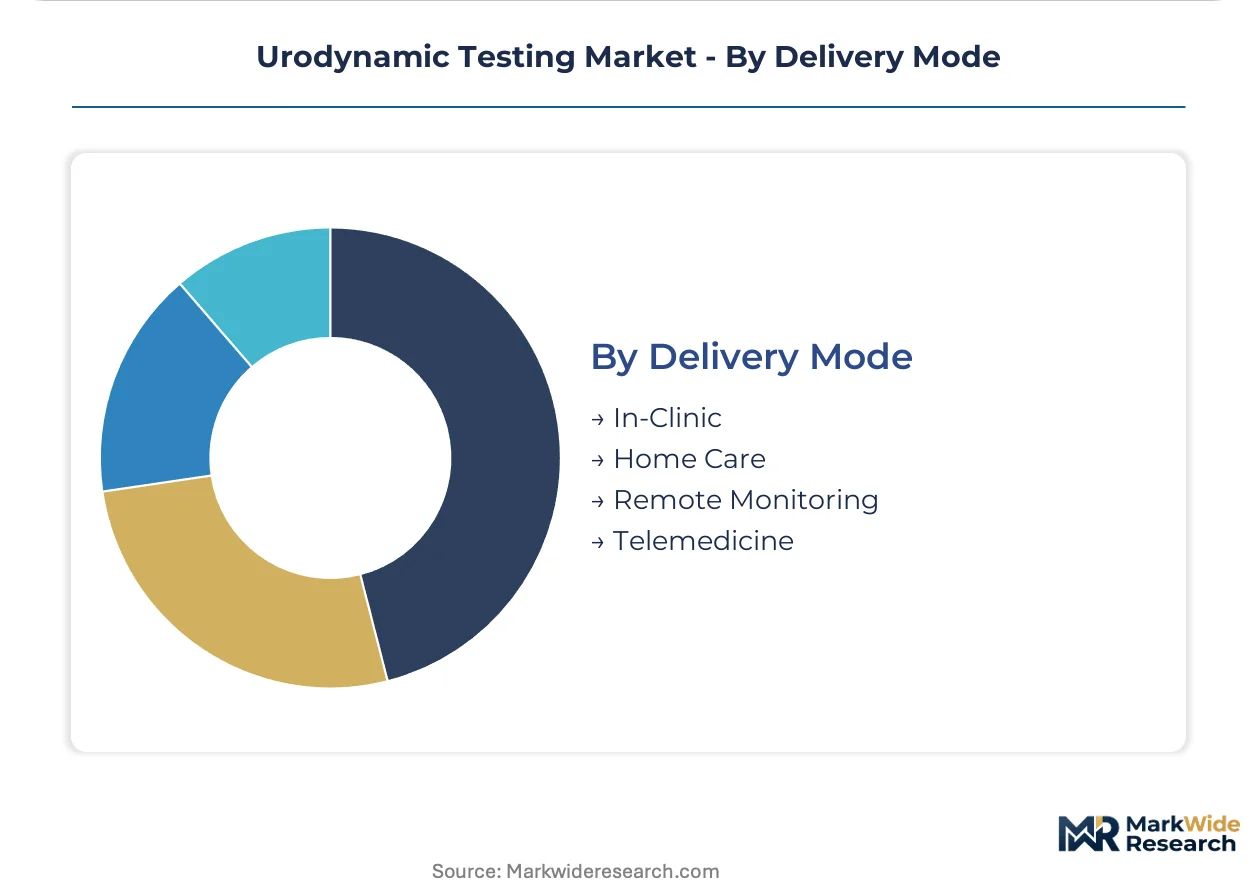
Delivery Mode:
Physical location of data capture and clinical interpretation defines regulatory classification and payer coverage.
- Remote Monitoring:Bluetooth-enabled uroflowmeters transmit voiding data to cloud-based analytics platforms for asynchronous physician review. CMS established Category III CPT codes for remote urodynamic monitoring, catalyzing pilot deployments in Medicare Advantage networks.
- In-Clinic:Traditional attended urodynamic studies with physician or technologist supervision maintain gold-standard status for complex cases requiring real-time catheter repositioning.
- Home Care:Patient-operated uroflowmetry devices lack standardized calibration, producing variable data quality that limits clinical acceptance.
- Telemedicine:Synchronous video consultation combined with patient-reported outcomes substitutes for select follow-up urodynamic interpretations.
In-clinic delivery dominates revenue. Remote monitoring represents the steepest expansion trajectory as asynchronous reimbursement codes mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized catheter manufacturing clusters in Germany and the United States concentrate supply for pressure-sensing components, while procedural demand disperses across aging populations in Japan, Germany, and the United States where reimbursement frameworks sustain diagnostic volume.
United States
Medicare Advantage networks and site-neutral payment policies are shifting urodynamic procedures toward ambulatory surgery centers. FDA 510(k) clearance pathways govern software-enabled diagnostic features, with review timelines extending for AI-augmented pressure curve analysis. Hospital outpatient departments in the Northeast Corridor maintain the highest procedural density.
Germany
Integrated delivery networks centralize procurement authority within urology service lines, negotiating multi-year hardware-software-service bundles. EU MDR clinical evidence standards filter out marginal competitors, advantaging manufacturers with dedicated regulatory affairs infrastructure. The Baden-Württemberg medical technology cluster hosts polymer converter facilities for disposable catheter production.
Japan
PMDA priority review pathways accelerate market entry for software-as-medical-device urodynamic tools. Super-aging demographics expand the patient pool with lower urinary tract dysfunction, particularly in Kanto region tertiary hospitals. Tokyo metropolitan medical centers maintain dedicated urodynamic suites for complex incontinence phenotyping.
United Kingdom
NHS England referral patterns concentrate complex urodynamic studies within specialized urogynecology centers. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements shapes manufacturer market access strategies. London and Southeast England hospital trusts pilot remote monitoring reimbursement models.
China
NMPA Class II medical device registration requirements for urodynamic equipment are tightening biocompatibility testing protocols. Private hospital chains in the Yangtze River Delta are importing European cystometry platforms to differentiate urology service offerings. Shanghai tertiary hospitals lead domestic validation of wireless pressure transducer technology.
Urodynamic Testing Market Competitive Landscape
Integrated diagnostic platform vendors and specialized disposable catheter manufacturers split the market into distinct capability tiers. The vendor base concentrates around established regulatory affairs infrastructure, with EU MDR compliance costs filtering smaller entrants. Three strategic archetypes dominate: full-stack platform providers bundling hardware-software-service, component specialists supplying pressure-sensing catheters to multiple OEMs, and regional distributors with localized technical service networks. Competitive moves center on aftermarket service contract extension and AI-enabled software licensing transitions.
Within the full-stack platform tier, Laborie and Medtronic exemplify divergent strategic positions. Laborie leverages its installed base to sustain recurring calibration and maintenance revenue streams. Medtronic anchors its market presence through proprietary software ecosystem integration. Boston Scientific Corporation occupies a position spanning therapeutic and diagnostic urology portfolios. These three entities represent the dominant archetypes: pure-play diagnostics, diversified medtech conglomerates, and urology-focused device manufacturers.
| Leading Market Players |
|---|
| Laborie |
| Boston Scientific Corporation |
| Medtronic |
| CooperSurgical |
| Verathon, Inc. |
| Albyn Medical |
| SRS Medical |
| Karl Storz |
| Coloplast |
| Others |
Value Network & Pricing Analysis
The trans-Atlantic freight corridor linking polymer converter facilities in Baden-Württemberg to United States hospital procurement hubs transmits cost volatility directly into cystometry system pricing. Downstream price differentiation intensifies as EU MDR compliance costs concentrate manufacturing among fewer catheter suppliers capable of sustaining technical documentation burdens.
Pricing Analysis
EU MDR dictates the pricing tier structure across urodynamic equipment categories. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multi-channel systems from basic uroflowmetry units. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because disposable catheter commoditization limits hardware margin expansion. Independent urology practices exhibit highest price sensitivity; integrated delivery networks absorb premium tier costs through centralized procurement.
Supply Chain Analysis
Export-control restrictions on pressure-sensing microelectronics constrain component flows to urodynamic device assemblers. Manufacturing concentrates in Germany, the United States, and Japan. Raw material dependencies include medical-grade polymers, MEMS pressure sensors, and biocompatible catheter coatings. Single-source vulnerability in specialized polymer converters creates supply chain risk. Distribution runs through group purchasing organizations and direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urodynamic testing sits in early-cycle expansion as remote monitoring reimbursement codes unlock ambulatory penetration previously blocked by site-of-service restrictions.
For Market Incumbents: Harden regulatory affairs infrastructure against extended FDA 510(k) timelines for AI-augmented diagnostic features. Deepen backward integration into pressure-sensing catheter production to offset supply concentration risk from German polymer converters. Anchor installed base retention through multi-year calibration contracts that embed software update entitlements.
For New Entrants and Emerging Players: Build out compact, cart-based systems targeting United States urology group practices with simplified technician training requirements. Japan PMDA priority review pathways for software-as-medical-device tools offer the most penetrable regulatory entry point. Pursue asynchronous data review partnerships with Medicare Advantage networks as the primary go-to-market angle.
For Investors and Strategic Acquirers: Regional distributors with localized technical service networks represent the most defensible acquisition target archetype. Long-term viability hinges on aftermarket service contract density rather than hardware shipment volume. Watch CMS remote monitoring reimbursement expansion as the inflection signal for ambulatory setting penetration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance timelines for AI-augmented pressure curve analysis are extending due to digital health classification uncertainty. |
| CE Marking Pathway | EU MDR technical documentation requirements filter marginal competitors and advantage established regulatory affairs teams. |
| Hospital System Partnership | Integrated delivery networks in Germany centralize procurement authority and demand HL7 FHIR connectivity. |
| Software Companion Development | Subscription licensing for urodynamic analysis platforms displaces perpetual ownership models in German hospital procurement. |
| Reimbursement Strategy | CMS Category III CPT codes for remote urodynamic monitoring catalyze pilot deployments in Medicare Advantage networks. |
Research Methodology
Operator-level perspectives from urodynamic technologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS reimbursement code updates, and hospital procurement contract records. Bottom-up equipment shipment estimates and top-down healthcare expenditure triangulation converged on segment-level outputs.
Scenario-bracketing across regulatory approval delays and reimbursement code expansion timelines bounded the forecast range. Segmentation dimensions modeled include product type complexity tiers, delivery mode reimbursement pathways, end-user procurement structures, and regional regulatory clusters. CAGRs were derived from procedural volume elasticity to demographic aging and payer coverage evolution. Forecast inputs incorporated catheter disposable consumption rates and software licensing transition velocities.
Stress conditions across FDA review timeline extension, EU MDR compliance cost inflation, and telemedicine reimbursement code stagnation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about aging demographic trajectories and payer behavior. Material shifts in CMS site-neutral payment policy or PMDA software-as-medical-device classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Thrombophilia Testing Market
Testing Services
Fertility Testing Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
STD Testing Devices Market
Testing Services
Diagnostic Shipper Market
Testing Services
Calprotectin Testing Market
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Radiographic Testing Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Urine Testing Cups Market
Testing Services
Leukocyte Count Testing Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Hospital Microbiology Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
Cell Line Authentication and Characterization Tests Market