
 Passive Dosimetry Equipment and Service Market | 2026-2036
Passive Dosimetry Equipment and Service Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Dosimetry Equipment and Service Market Insights
Capital-intensity divergence between in-house manufacturing and outsourced assembly is rotating competitive advantage toward vertically integrated suppliers. Landauer sustains its dominance through captive production of thermoluminescent detector crystals. Mirion Technologies leverages its nuclear instrumentation heritage to anchor service contracts across North American utilities. Thermo Fisher Scientific competes on analytical calibration credibility, extending its laboratory equipment brand into dosimetry verification workflows.
Passive dosimetry equipment measures cumulative ionizing radiation exposure using materials that trap energy for later readout, typically employing lithium fluoride or aluminum oxide crystals with detection thresholds below one millisievert. These devices serve occupational safety compliance by providing legally admissible exposure records for workers in radiological environments. Optically stimulated luminescence dosimeters command the premium product tier due to their reusability and precision at low doses, while film badge dosimeters retain share in cost-sensitive industrial workplaces where quarterly replacement cycles suffice. Monitoring services generate recurring revenue that exceeds equipment margins, with calibration services forming a concentrated profit pool tied to accreditation requirements.
The US Nuclear Regulatory Commission enforces 10 CFR Part 20 personnel monitoring rules, while the International Atomic Energy Agency publishes safety standards that national regulators transpose into licensing conditions. OSHA's ionizing radiation standard for general industry, 29 CFR 1910.1096, compels employers to maintain individual exposure records, directly sustaining demand for third-party dosimetry services. Stakeholders must track how the EPA's proposed updates to environmental radiation standards and the IAEA's revision cycle for safety guides will reshape accreditation burdens and service pricing structures.
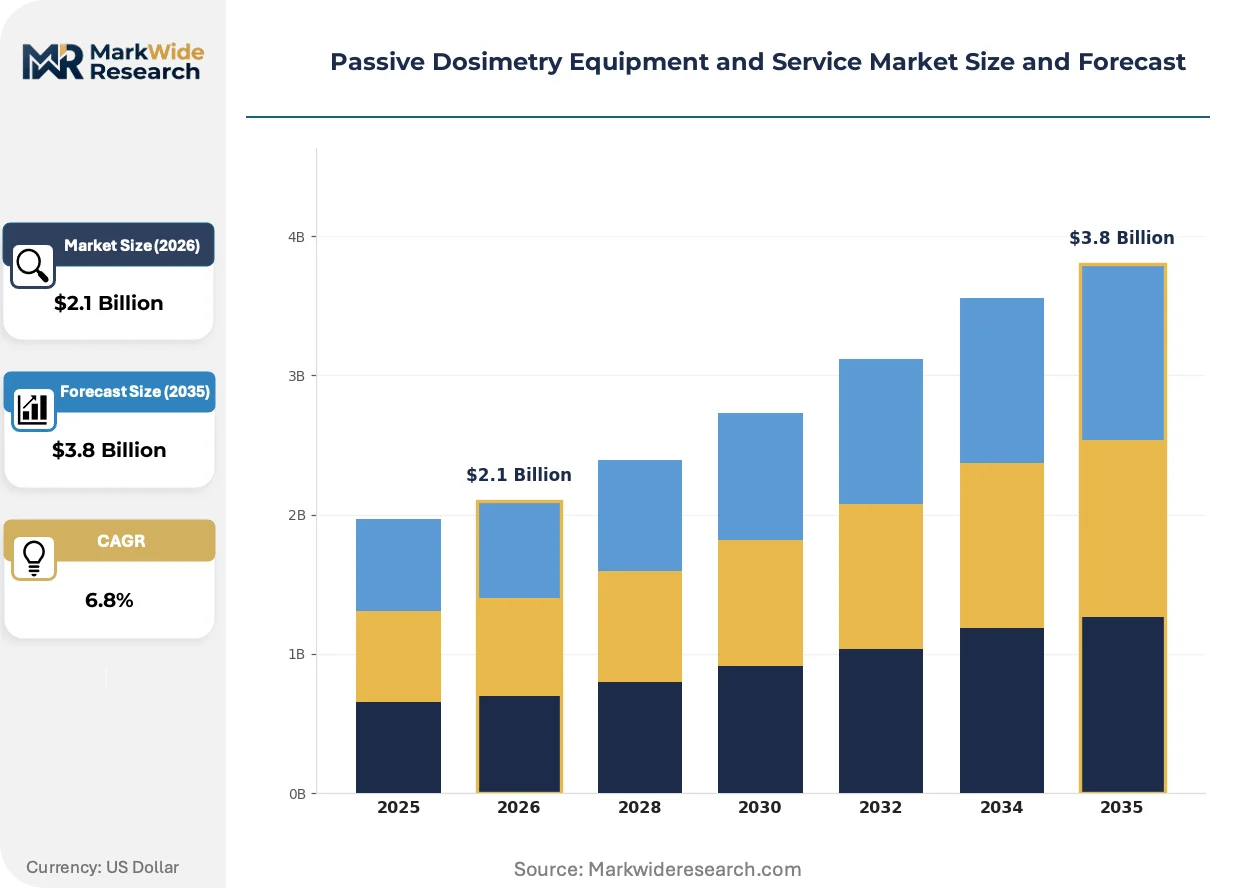
Market Dynamics
The passive dosimetry market is consolidating around captive crystal production capabilities as thermoluminescent material supply constraints intensify competitive pressure on non-integrated service providers.
Growth Catalysts
- OSHA 29 CFR 1910.1096 Recordkeeping Mandates:US employers must maintain individual radiation exposure histories, creating perpetual demand for third-party monitoring services that archive legally admissible dose records.
- Proton Therapy Center Expansion:North American cancer treatment facilities are installing particle accelerator systems that require expanded personnel monitoring programs for cyclotron and beamline operators.
- Aluminum Oxide Crystal Advances:Newer optically stimulated luminescence materials achieve sub-millisievert detection thresholds that satisfy nuclear medicine department accreditation standards.
Market Restraints
- TLD Crystal Supply Concentration:High-purity lithium fluoride production concentrates among a handful of specialty chemical suppliers, exposing dosimeter manufacturers to raw material allocation risk.
- Digital Dosimetry Substitution:Active electronic personal dosimeters with real-time readout capability are capturing high-dose industrial applications where immediate alarm functionality outweighs passive archival requirements.
- IAEA Safety Guide Revision Cycles:Pending updates to international monitoring protocols create compliance uncertainty that delays hospital procurement committee approvals for multi-year service contracts.
Strategic Opportunities
- India Diagnostic Imaging Growth:The country's expanding PET-CT and SPECT installation base outpaces trained medical physicist availability, opening outsourced dosimetry management contracts.
- Decommissioning Workforce Surge:US reactor closure schedules are generating temporary monitoring demand from remediation contractors who lack permanent radiation safety infrastructure.
- Blockchain-Verified Exposure Records:Distributed ledger technology integration with dosimetry databases offers tamper-proof credentialing for mobile healthcare workers crossing institutional boundaries.
Industry Challenges
- Medical Physicist Talent Scarcity:Hospital radiation safety officer positions remain unfilled as academic training programs fail to match imaging department expansion rates.
- NVLAP Accreditation Timelines:New laboratory entrants face eighteen-month National Voluntary Laboratory Accreditation Program approval cycles before qualifying for commercial monitoring contracts.
- Legacy Film Badge Archive Migration:Industrial facilities with decades of historical exposure data require costly digitization to satisfy modern electronic recordkeeping audit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Dosimetry Equipment and Service Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoluminescent Dosimeters, Quartz Fiber Dosimeters, Film Badge Dosimeters, Optically Stimulated Luminescence Dosimeters End User: Healthcare Facilities, Research Laboratories, Nuclear Power Plants, Industrial Workplaces Service Type: Calibration Services, Monitoring Services, Training Services, Consulting Services Deployment Mode: On-Premises, Remote, Hybrid, Mobile |
| Companies Covered | Landauer, Mirion Technologies, Thermo Fisher Scientific, Fuji Electric, Ludlum Measurements, Chiyoda Technol Corporation, Tracerco, Fortive, Polimaster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Dosimetry Equipment and Service Market Trends and Innovations
Passive dosimetry is bifurcating into precision laboratory instruments for healthcare and ruggedized field units for industrial decommissioning, with each trajectory demanding distinct materials science investments.
Optically stimulated luminescence technology is supplanting thermoluminescent dosimetry in hospital radiology departments. The aluminum oxide-based systems permit automated readout without heating elements, reducing laboratory capital requirements. Major academic medical centers in the United States are completing this transition within compressed procurement cycles, compressing service provider margins on legacy TLD infrastructure.
EPA's proposed environmental radiation standard updates are tightening dose reporting granularity for nuclear power licensees. The regulatory revision would mandate monthly rather than quarterly reporting intervals for certain worker categories. US utilities are pre-positioning higher-frequency monitoring contracts to avoid compliance gaps when the rule finalizes.
Consolidated procurement through group purchasing organizations is displacing direct hospital-dosimetry vendor relationships. Healthcare systems with ten-plus imaging sites are centralizing radiation safety oversight under single-source national agreements. This concentration is most visible in the southeastern United States where hospital network mergers have accelerated since 2022.
Passive Dosimetry Equipment and Service Market Segmentation
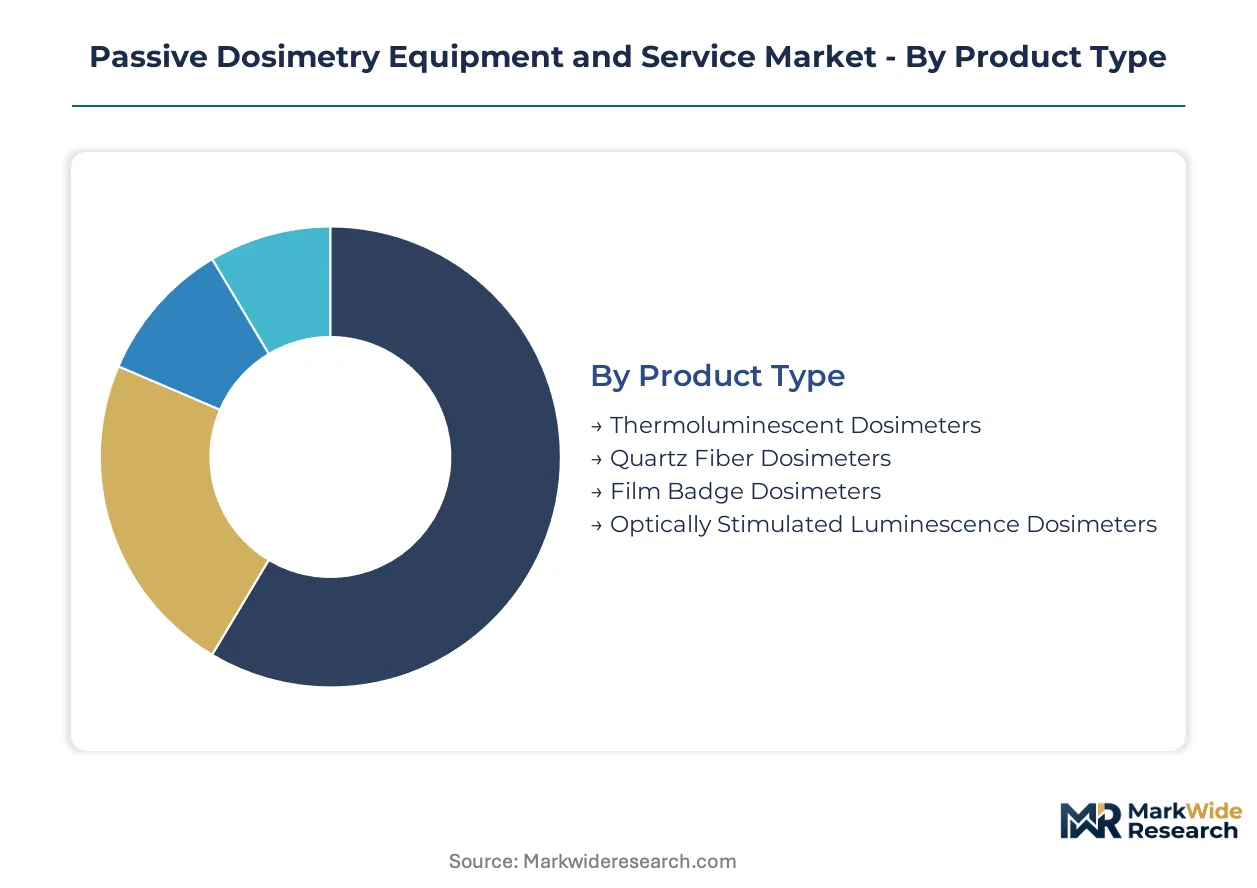
Segmentation in passive dosimetry reveals where substitution pressures and regulatory mandates reshape procurement patterns. Product technology choices determine laboratory capital requirements, while service bundling separates compliance-focused buyers from those seeking full radiation safety outsourcing.
Product Type:
Electronic personal dosimeters exert substitution pressure most acutely on film-based systems, while thermoluminescent platforms face margin compression from optically stimulated luminescence automation.
- Optically Stimulated Luminescence Dosimeters:Aluminum oxide crystals enable automated readout without heating infrastructure, cutting laboratory equipment costs. US academic medical centers concentrate procurement here, driven by Joint Commission accreditation standards for nuclear medicine departments.
- Thermoluminescent Dosimeters:Lithium fluoride crystals require thermal processing but retain legal admissibility across all NRC licensing jurisdictions. Demand persists in nuclear power utilities where historical dose record continuity outweighs equipment upgrade incentives.
- Film Badge Dosimeters:Silver halide emulsion systems serve cost-sensitive industrial radiography contractors with quarterly replacement tolerances.
- Quartz Fiber Dosimeters:Electrostatic charge measurement suits high-dose industrial inspection with immediate visual readout requirements.
Film badge dosimeters retain volume leadership in legacy industrial installations; optically stimulated luminescence dosimeters hold the steepest expansion curve.
End User:
Procurement scale diverges sharply between capital-intensive healthcare systems and project-based decommissioning contractors.
- Healthcare Facilities:Hospital radiation safety officers manage multi-site imaging department compliance across PET-CT, SPECT, and interventional radiology suites. The segment concentrates spend in US metropolitan markets where proton therapy center construction accelerates personnel monitoring program expansion.
- Nuclear Power Plants:Licensees maintain 10 CFR Part 20 compliant programs with decade-long service contract horizons. Procurement centralizes through utility holding companies that negotiate enterprise pricing across reactor fleets.
- Research Laboratories:Cyclotron facilities and particle physics installations require specialized neutron-sensitive dosimetry configurations.
- Industrial Workplaces:Non-destructive testing contractors and uranium mining operations prioritize ruggedized field units over laboratory precision.
Healthcare facilities command the highest service contract values; nuclear power plants provide the most predictable renewal revenue.
Service Type:
Accreditation requirements concentrate profit in calibration while commoditization pressures monitoring.
- Calibration Services:NVLAP-accredited laboratories perform traceable source comparisons that satisfy regulatory audit requirements. Revenue concentrates among providers with captive crystal production, as thermoluminescent material purity directly determines measurement uncertainty budgets.
- Monitoring Services:Third-party archiving of legally admissible dose records generates recurring revenue exceeding equipment margins. OSHA 29 CFR 1910.1096 recordkeeping mandates sustain perpetual demand from employers lacking in-house radiation safety infrastructure.
- Training Services:Medical physicist certification programs address talent scarcity in expanding imaging departments.
- Consulting Services:Regulatory interpretation support guides procurement committees through IAEA safety guide revision uncertainty.
Monitoring services generate the broadest customer base; calibration services capture the highest margin concentration.
Deployment Mode:
Healthcare consolidation favors centralized oversight while decommissioning projects demand field mobility.
- Hybrid:Combines on-premises readout infrastructure with cloud-based record archiving, serving hospital networks centralizing radiation safety oversight across ten-plus imaging sites. Southeastern US health systems accelerated this procurement pattern following 2022 merger activity.
- Mobile:Trailer-mounted laboratories deploy to temporary decommissioning workforces lacking permanent dosimetry infrastructure. US reactor closure schedules generate episodic demand from remediation contractors.
- On-Premises:Dedicated laboratory equipment serves high-volume utilities with continuous monitoring obligations.
- Remote:Mail-in dosimeter processing suits low-volume research laboratories without capital equipment budgets.
On-premises retains share in nuclear utilities with steady throughput; hybrid deployment is gaining share fastest among consolidating healthcare networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where regulatory enforcement and healthcare consolidation sustain premium service contracts, while cost-sensitive procurement in emerging markets compresses margins for standardized equipment.
United States
Proton therapy center construction in Houston, Boston, and Philadelphia drives personnel monitoring program expansion. OSHA 29 CFR 1910.1096 mandates individual exposure record maintenance, perpetuating third-party service demand. The southeastern hospital network consolidation since 2022 accelerates single-source national contract centralization.
Germany
Industrial radiography contractors in the Ruhr region and Bavarian manufacturing clusters sustain film badge volume. The country's national radiation protection regulator enforces strict occupational exposure limits under the StrlSchG framework. Munich and Stuttgart academic medical centers transition toward optically stimulated luminescence automation.
Japan
Cyclotron facilities at Osaka University and KEK Tsukuba require specialized neutron-sensitive dosimetry configurations. METI oversees nuclear facility decommissioning workforce safety standards. The Chubu region around Nagoya hosts concentrated non-destructive testing operations for automotive supply chains.
India
PET-CT and SPECT installation growth in Mumbai, Delhi-NCR, and Bangalore outpaces trained medical physicist availability. The Atomic Energy Regulatory Board mandates personnel monitoring for diagnostic imaging facilities. Hyderabad's pharmaceutical radiation sterilization sector generates industrial dosimetry procurement.
United Kingdom
Sellafield decommissioning contractors require temporary mobile monitoring infrastructure. The Health and Safety Executive enforces Ionising Radiations Regulations 2017 compliance across nuclear and healthcare sectors. Oxford and Cambridge research cyclotrons anchor specialized neutron dosimetry demand.
Passive Dosimetry Equipment and Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision laboratory instrument specialists commanding premium pricing while industrial field unit suppliers compete on volume throughput. The market structure consolidates around captive crystal production capabilities, squeezing non-integrated service providers on material access. Three archetypes dominate: vertically integrated detector manufacturers, analytical calibration laboratories extending into dosimetry verification, and nuclear instrumentation heritage firms anchoring utility service contracts. Competitive moves center on backward integration into thermoluminescent material supply and strategic partnerships with proton therapy center developers.
Among North American heritage players, Landauer and Mirion Technologies exemplify the integrated manufacturer archetype, while Thermo Fisher Scientific represents the laboratory equipment brand extension model. These three occupy positions where analytical credibility or captive crystal production creates defensive moats against pricing pressure from lower-tier competitors.
| Leading Market Players |
|---|
| Landauer |
| Mirion Technologies |
| Thermo Fisher Scientific |
| Fuji Electric |
| Ludlum Measurements |
| Chiyoda Technol Corporation |
| Tracerco |
| Fortive |
| Polimaster |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month NVLAP accreditation timelines for new laboratory entrants concentrate pricing power among established providers with captive thermoluminescent crystal production, while aluminum oxide supply constraints reshape procurement economics across service tiers.
Pricing Analysis
The customization-premium spread between configured-to-order optically stimulated luminescence systems and standard film badge subscriptions reaches three-to-one multiples, with Joint Commission accreditation-grade laboratory services commanding the upper tier. Price differentiation hinges on NVLAP certification status and after-sales calibration bundling, where traceable source comparisons justify sustained premiums. Cost compression in legacy TLD infrastructure is intensifying because academic medical centers complete rapid OSL transitions, squeezing margins on heated-readout equipment. Industrial radiography contractors exhibit highest price sensitivity, while proton therapy center developers accept premium positioning for sub-millisievert detection thresholds.
Supply Chain Analysis
The United States and Germany anchor high-purity lithium fluoride crystal production for thermoluminescent dosimetry, while Japan and South Korea feed optically stimulated luminescence substrate manufacturing. Raw material dependencies center on specialty-grade aluminum oxide wafers, lithium fluoride ingots, and precision optical components for automated readout systems. Single-source vulnerability concentrates in thermoluminescent material purification, where three specialty chemical suppliers allocate output across competing dosimeter manufacturers. Distribution runs through NVLAP-accredited laboratory networks that archive legally admissible dose records under OSHA mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-verified exposure credentialing is transforming passive dosimetry from equipment transaction toward interoperable safety-platform economics, with distributed ledger integration enabling mobile healthcare workers to port tamper-proof records across institutional boundaries.
For Market Incumbents: Secure captive lithium fluoride supply through long-term offtake agreements with specialty chemical producers, insulating against raw material allocation risk that threatens non-integrated service providers. Deepen backward integration into aluminum oxide crystal growth to capture OSL automation margins as academic medical centers compress procurement cycles. Defend against digital dosimetry substitution by embedding real-time alarm partnerships into passive archival contracts. For New Entrants and Emerging Players: Medical physicist talent scarcity in India's expanding PET-CT and SPECT markets creates immediate white-space for outsourced radiation safety management contracts, where trained personnel shortages outpace imaging infrastructure installation. Target decommissioning workforce surge zones around US reactor closure schedules with mobile laboratory deployments, offering trailer-mounted processing to remediation contractors lacking permanent infrastructure. Pursue blockchain-integrated credentialing as a differentiated go-to-market angle for cross-institutional healthcare staffing platforms. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-recurring-revenue play because OSHA recordkeeping mandates and NRC licensing requirements perpetuate third-party monitoring demand regardless of equipment technology cycles. Acquisition targets should prioritize NVLAP-accredited laboratories with established utility service contracts and captive crystal production capabilities. Watch IAEA safety guide revision timing as the critical inflection signal, with finalization triggering compressed hospital procurement committee approvals for multi-year service agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Production | Captive lithium fluoride supply insulates margins against specialty chemical allocation constraints. |
| Blockchain-Verified Exposure Records | Distributed ledger integration enables tamper-proof credentialing for mobile healthcare workers. |
| Mobile Laboratory Deployment | Trailer-mounted processing captures episodic decommissioning demand from reactor closure schedules. |
| OSL Automation Transition | Aluminum oxide readout without heating elements cuts laboratory capital requirements for hospital networks. |
| Proton Therapy Center Partnerships | Particle accelerator construction in Houston, Boston, and Philadelphia expands personnel monitoring programs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital radiation safety officers, nuclear utility licensing managers, medical physicists, industrial radiography contractors, and NVLAP laboratory directors. Secondary validation drew from NRC regulatory filings, OSHA enforcement databases, IAEA safety standards documentation, and hospital procurement records. Bottom-up equipment shipment analysis and top-down service contract value estimation were triangulated to construct market size estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning detector technology type, end-user vertical, service tier, and deployment mode, with particular attention to healthcare consolidation patterns and decommissioning project cyclicality. CAGRs were derived from regression analysis against regulatory mandate implementation timelines and imaging infrastructure installation curves, incorporating proton therapy center construction pipelines and reactor closure schedules as industry-specific demand inputs.
Material uncertainties — IAEA safety guide revision timing, EPA environmental standard finalization, and lithium fluoride supply allocation shifts — sit outside the modeled envelope. Forecasts reflect assumptions regarding accreditation timeline stability and healthcare merger momentum continuation. Recalibration cycles align with material shifts in regulatory enforcement intensity and crystal production capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Cholesterol Test Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Test Strips Market
Testing Services
Global Sleep Testing Services Market
Testing Services
US Cannabis Testing Market
Testing Services
Urine Sediment Testing Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Bioprocess Integrity Testing Systems Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Americas Sterility Testing Market
Testing Services
Global Forensic Testing Services Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Global GMP Testing Service Market
Testing Services
Allergy Skin Test Market