
 In-Vitro Diagnostic Services Market | 2026-2036
In-Vitro Diagnostic Services Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vitro Diagnostic Services Market Analysis
Aftermarket service revenue is fragmenting across decentralized laboratory networks and point-of-care testing sites. Quest Diagnostics Incorporated sustains broad geographic coverage through its national reference laboratory footprint. bioMérieux SA specializes in automated microbiology diagnostic platforms for hospital laboratories.
In-vitro diagnostic services encompass the analytical testing of biological specimens outside the living organism, employing reagent-based chemical reactions, immunoassay detection thresholds measured in picograms per milliliter, and molecular amplification cycles to identify disease markers or metabolic states. These services deliver clinical decision support for patient triage, treatment selection, and disease monitoring across healthcare systems. Reagents capture recurring revenue through consumable replenishment tied to installed instrument bases. Molecular diagnostics commands premium positioning due to complex assay development and specialized technician requirements. Hospitals represent the most consolidated buyer segment, leveraging centralized laboratory operations to negotiate volume-based service contracts.
The FDA oversees Laboratory Developed Test validation and quality standards, while the Clinical Laboratory Improvement Amendments establish personnel competency and proficiency testing requirements for US-based facilities. ISO 15189 accreditation shapes international market access for cross-border diagnostic service providers. Stakeholders must monitor evolving regulatory distinctions between traditional laboratory services and software-enabled algorithmic diagnostics.
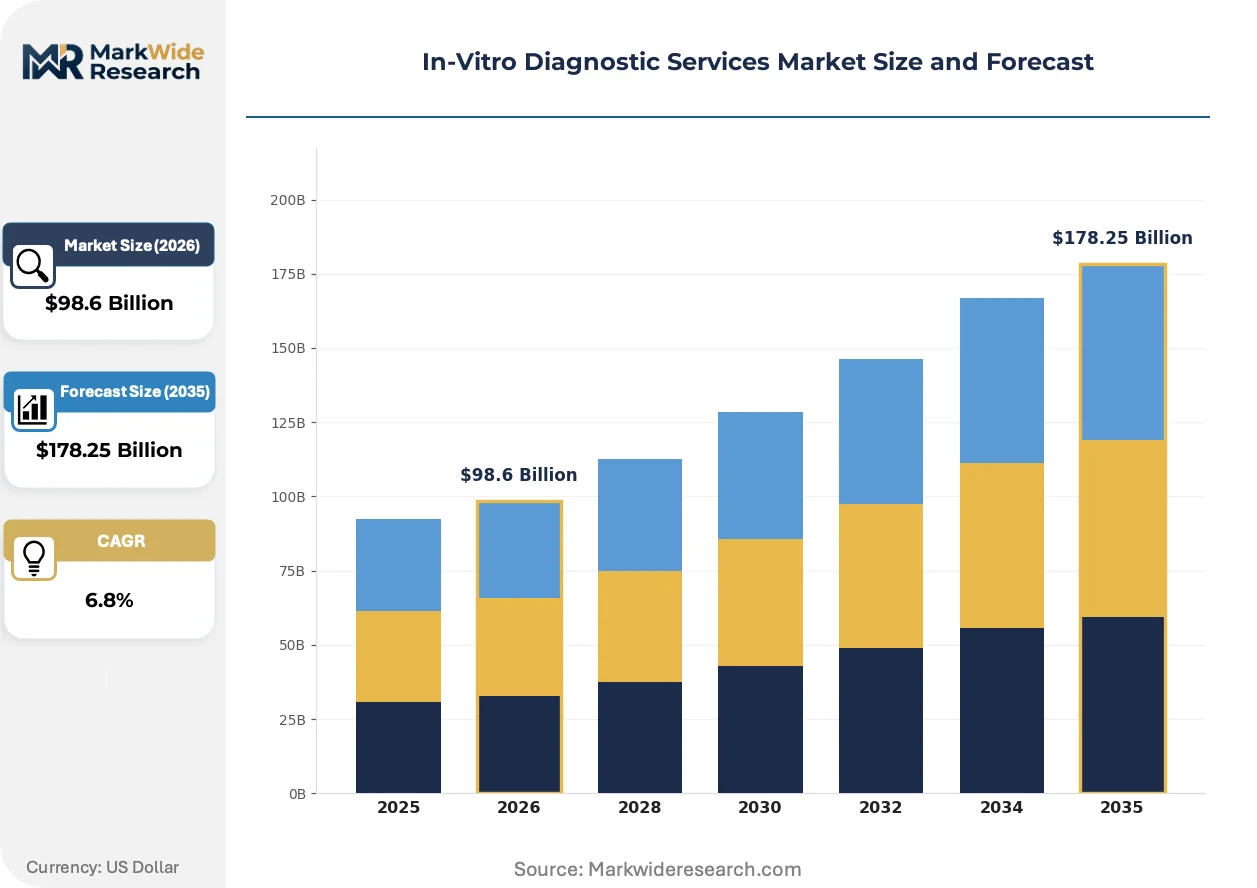
Market Dynamics
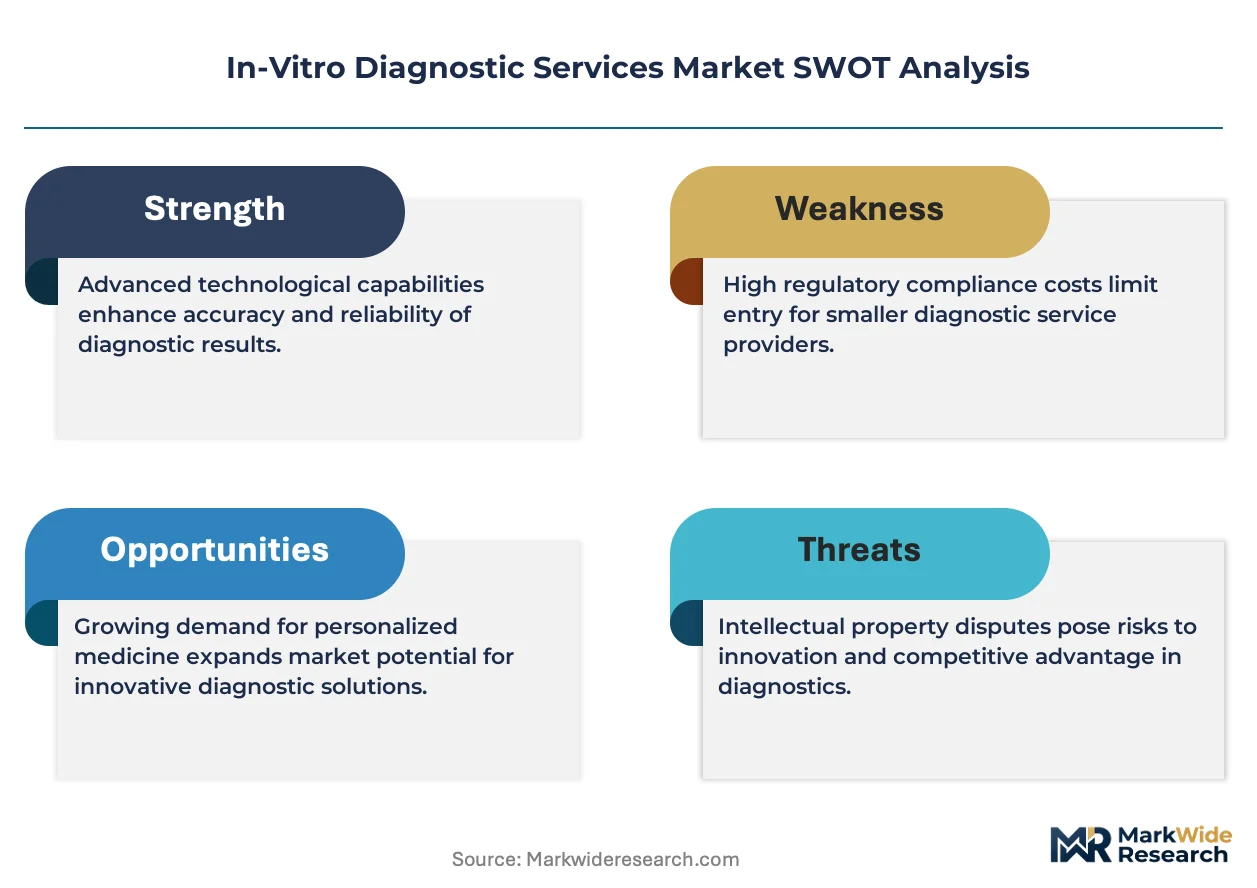
Centralized hospital laboratory networks are consolidating purchasing power while the FDA's Laboratory Developed Test oversight framework forces service providers to rebuild compliance infrastructure around analytical validity requirements.
Growth Catalysts
- CLIA personnel mandates:The Clinical Laboratory Improvement Amendments drive demand for credentialed technicians, expanding third-party staffing services for hospital outreach programs.
- Microbiology automation:Automated culture identification systems reduce turnaround times for sepsis protocols, pulling capital investment into diagnostic service infrastructure.
- India's diagnostic expansion:Tier-2 and tier-3 cities in India are building reference laboratory capacity, creating pull-through demand for reagent supply contracts and technical training services.
Market Restraints
- Reagent supply concentration:Specialty biochemical inputs rely on a narrow base of European and North American chemical manufacturers, exposing service providers to input cost volatility.
- FDA validation timelines:The updated Laboratory Developed Test framework extends analytical validation requirements, compressing margin structures for mid-scale reference laboratories.
- Point-of-care substitution:CLIA-waived rapid antigen tests displace low-complexity send-out volumes from hospital emergency departments.
Strategic Opportunities
- Brazil's regulatory opening:ANVISA is streamlining import registration for molecular diagnostic platforms, reducing market entry friction for international service providers.
- AI-assisted pathology:Convergence of digital imaging algorithms with traditional histopathology creates new service revenue streams in oncology diagnostics.
- Direct-to-consumer channel:Retail pharmacy partnerships for routine health screening bypass traditional physician-referral pathways.
Industry Challenges
- Molecular technician scarcity:Nucleic acid amplification expertise concentrates in metropolitan academic medical centers, constraining rural laboratory expansion.
- ISO 15189 accreditation timelines:International accreditation bodies face application backlogs, delaying cross-border service contract execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vitro Diagnostic Services Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Consumables End User: Hospitals, Laboratories, Diagnostic Centers, Research Institutions Technology: Molecular Diagnostics, Immunoassays, Clinical Chemistry, Hematology Application: Oncology, Infectious Diseases, Cardiology, Metabolic Disorders |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, Thermo Fisher Scientific Inc., bioMérieux SA, Bio-Rad Laboratories Inc., Quest Diagnostics Incorporated, QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vitro Diagnostic Services Market Emerging Trajectories
Digital pathology platforms and algorithmic diagnostic interpretation are compressing the traditional anatomical pathology workflow while regulatory bodies scramble to define oversight boundaries for software-enabled clinical decision support.
Next-generation sequencing panels for oncology companion diagnostics are migrating from research-grade protocols to standardized clinical service offerings. Community hospital laboratories are adopting these platforms through managed service partnerships rather than capital purchase. This migration from capital ownership to operational expenditure models is reshaping vendor-customer relationships toward reagent rental and per-test pricing structures.
The EU's In Vitro Diagnostic Regulation is forcing service providers to rebuild technical documentation around performance evaluation and post-market surveillance. Manufacturers must now generate clinical evidence for existing assays, creating compliance bottlenecks. European reference laboratories are responding by consolidating validation studies across multi-site networks to distribute regulatory costs.
Hospital procurement departments are unbundling diagnostic service contracts from equipment maintenance agreements, treating analytical testing as a distinct spend category. Group purchasing organizations are inserting themselves between manufacturers and hospital laboratories, extracting administrative fees for contract aggregation. This disintermediation is most visible in the United States, where health system consolidation has concentrated buying power within ten major integrated delivery networks.
In-Vitro Diagnostic Services Market Segmentation
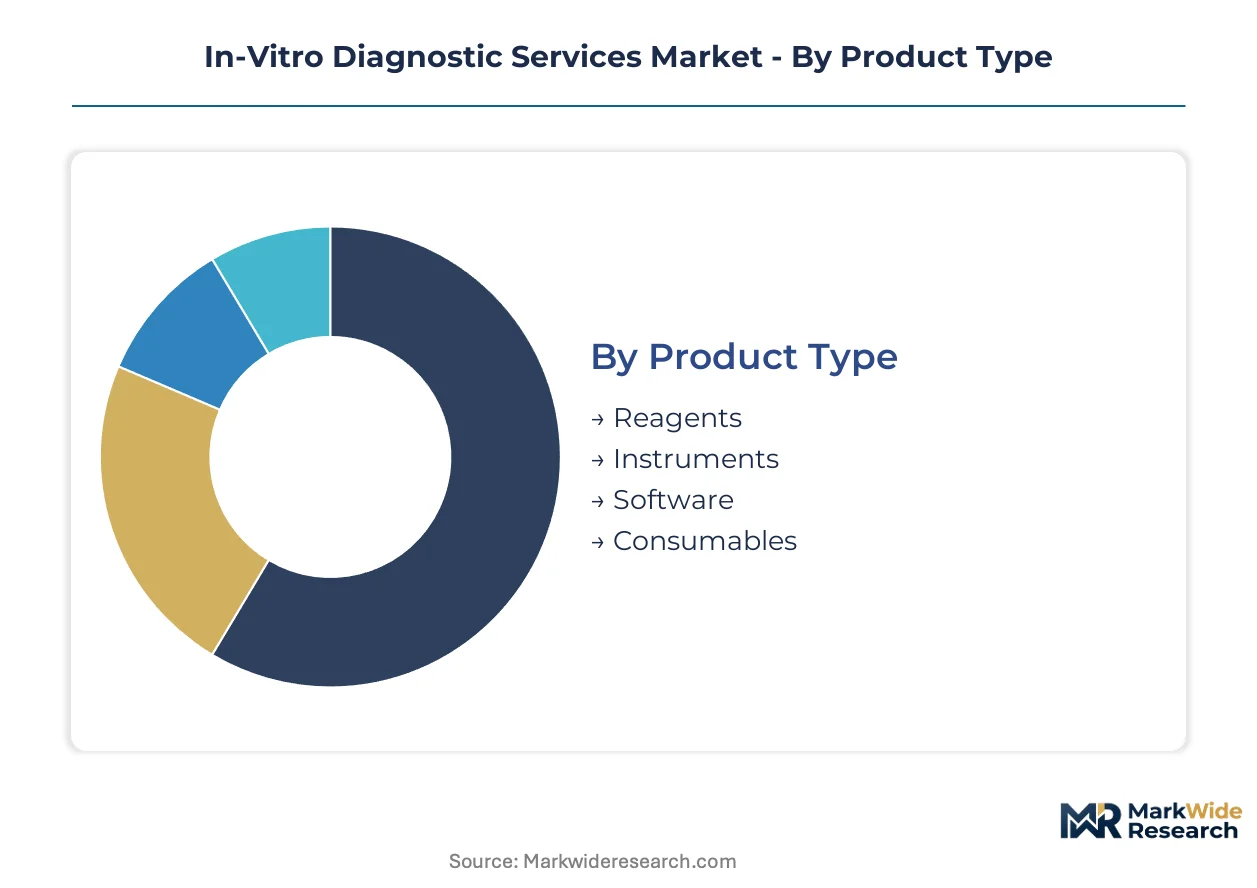
Segmentation in in-vitro diagnostic services reveals distinct margin profiles and regulatory exposure across product categories and customer channels. Understanding these divides enables precise resource allocation for compliance infrastructure and commercial targeting.
Product Type:
Cost tier stratification separates recurring consumable revenue from capital-intensive instrument placements and software licensing arrangements.
- Reagents:Biochemical and immunological reaction substrates with defined stability windows and cold-chain storage requirements. Demand concentrates in high-throughput hospital laboratories across the United States, where CLIA-mandated quality controls drive consistent replenishment cycles.
- Instruments:Automated analyzers and sample processing platforms with multi-year depreciation schedules and service contract attachments. Academic medical centers in Germany and Japan anchor procurement volumes, prioritizing throughput capacity and LIS integration over per-unit acquisition cost.
- Software:Laboratory information systems and algorithmic interpretation modules for workflow management and regulatory documentation. Cloud-native deployments are gaining preference among mid-scale reference laboratories seeking reduced IT overhead.
- Consumables:Disposable pipette tips, reaction vessels, and specimen collection devices with standardized dimensions. Group purchasing organizations in the United States negotiate these as commodity categories, compressing supplier margins.
Reagents command the established base. The steepest expansion runs through software.
End User:
Customer type determines contract structure complexity, with consolidated health systems demanding outcome guarantees that fragmented diagnostic centers cannot negotiate.
- Hospitals:Integrated delivery networks operating centralized laboratories with 24-hour stat testing capabilities. The Cleveland Clinic and Mayo Clinic anchor reference laboratory outsourcing partnerships, driving volume-based pricing for molecular oncology panels.
- Laboratories:Independent reference facilities and hospital outreach programs competing on turnaround time and specialized assay menus. Quest Diagnostics and LabCorp network dominance in the United States shapes competitive dynamics for regional players.
- Diagnostic Centers:Focused outpatient facilities emphasizing convenience and rapid result delivery. India's Metropolis Healthcare and Thyrocare are expanding tier-2 city footprints, creating distributed demand for reagent supply contracts.
- Research Institutions:Academic and pharmaceutical R&D operations utilizing investigational protocols with flexible validation standards. These buyers prioritize customization over regulatory pre-clearance, accepting higher per-test costs.
Hospitals command the established base. The steepest expansion runs through diagnostic centers.
Technology:
Technical maturity separates established automated platforms from amplification-based methods requiring specialized personnel and controlled environments.
- Molecular Diagnostics:Nucleic acid amplification and hybridization techniques detecting genetic mutations and pathogen sequences at picogram sensitivity. Oncology companion diagnostics in the United States and infectious disease surveillance in Brazil concentrate demand, with ANVISA streamlining import registration for these platforms.
- Immunoassays:Antibody-antigen binding reactions for hormone, cardiac marker, and infectious disease detection. High-throughput chemiluminescence systems dominate hospital core laboratory menus.
- Clinical Chemistry:Spectrophotometric and ion-selective electrode methods for metabolic panel analysis. These assays represent the most automated and cost-competitive segment.
- Hematology:Automated cell counting and morphological classification for complete blood count parameters. Sysmex and Beckman Coulter instrument placements anchor recurring reagent revenue.
Clinical chemistry commands the established base. Molecular diagnostics is gaining share fastest.
Application:
Disease prevalence and reimbursement density determine which therapeutic areas support premium assay development and specialized service infrastructure.
- Oncology:Companion diagnostic testing for targeted therapy selection and minimal residual disease monitoring. Next-generation sequencing panels are migrating from research protocols to standardized clinical offerings through managed service partnerships rather than capital purchase.
- Infectious Diseases:Pathogen identification and antimicrobial susceptibility testing with rapid turnaround requirements for sepsis protocols. Automated microbiology platforms from bioMérieux reduce time-to-result in hospital emergency departments.
- Cardiology:Troponin and natriuretic peptide assays for acute coronary syndrome and heart failure diagnosis. Point-of-care testing is displacing send-out volumes for chest pain evaluation.
- Metabolic Disorders:Glucose, lipid, and thyroid function testing for chronic disease management. High testing frequency supports reagent rental and per-test pricing structures.
Metabolic disorders command the established base. Oncology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic service buyers in Germany and Switzerland demonstrate low price elasticity for molecular oncology panels, while procurement teams in India and Brazil negotiate aggressively on reagent contracts. Hospital systems in the United States occupy a middle position, trading volume commitments for service-level guarantees. This demand-elasticity gradient shapes vendor pricing architecture across geographies.
United States
Integrated delivery networks in the United States consolidate laboratory purchasing through group purchasing organizations, extracting administrative fees from reagent contracts. The FDA's updated Laboratory Developed Test oversight framework forces mid-scale reference laboratories to rebuild compliance infrastructure around analytical validity requirements. The Cleveland Clinic and Mayo Clinic anchor reference laboratory outsourcing partnerships in the Midwest, driving volume-based pricing for specialized assay menus.
Germany
Academic medical centers in Germany prioritize throughput capacity and LIS integration over per-unit acquisition cost for automated analyzers. The EU In Vitro Diagnostic Regulation forces service providers to rebuild technical documentation around performance evaluation and post-market surveillance. Bavaria and Baden-Württemberg host dense clusters of university hospital laboratories consolidating validation studies across multi-site networks to distribute regulatory costs.
India
Tier-2 and tier-3 cities in India are building reference laboratory capacity, creating pull-through demand for reagent supply contracts and technical training services. The Central Drugs Standard Control Organization regulates import registration for molecular diagnostic platforms. Metropolis Healthcare and Thyrocare expand footprints in Maharashtra and Karnataka, generating distributed demand for consumable replenishment tied to installed instrument bases.
Brazil
ANVISA is streamlining import registration for molecular diagnostic platforms, reducing market entry friction for international service providers. Infectious disease surveillance programs concentrate demand for nucleic acid amplification techniques in São Paulo and Rio de Janeiro. Hospital emergency departments in these metropolitan areas adopt automated microbiology platforms to reduce turnaround times for sepsis protocols.
Japan
Academic medical centers in Japan anchor procurement volumes for automated analyzers with multi-year depreciation schedules. The Ministry of Economy, Trade and Industry influences domestic manufacturing incentives for diagnostic instrument production. The Kanto region around Tokyo and the Kansai region around Osaka host concentrated hospital laboratory networks competing on stat testing capabilities and specialized assay menus.
In-Vitro Diagnostic Services Market Vendor Landscape
Reference laboratory networks and diagnostic platform manufacturers split the market into distinct competitive arenas with limited overlap. Hospital procurement departments unbundle service contracts from equipment maintenance agreements, treating analytical testing as a distinct spend category. Three archetypes dominate: national reference laboratory chains, automated platform specialists, and reagent-centric consumable suppliers. Consolidation through health system mergers and managed service partnerships represents the dominant competitive moves, alongside geographic expansion into tier-2 city clusters.
Within the reference laboratory tier, Quest Diagnostics Incorporated occupies a position exemplifying broad geographic coverage through national footprint scale. bioMérieux SA represents the automated platform specialist archetype, with company structure indicating French S.A. status. Siemens Healthineers AG anchors the diversified conglomerate segment, with German AG suffix indicating public corporate form. These three entities collectively illustrate how vendor-customer relationships reshape toward reagent rental and per-test pricing structures as community hospital laboratories migrate from capital ownership to operational expenditure models.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| bioMérieux SA |
| Bio-Rad Laboratories Inc. |
| Quest Diagnostics Incorporated |
| QIAGEN N.V. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in molecular diagnostics technician training programs across the United States and Western Europe simultaneously inflates labor costs for specialized assay services and compresses margin structures for mid-scale reference laboratories competing on turnaround time.
Pricing Analysis
Aftermarket service revenue through multi-year reagent rental contracts and per-test pricing arrangements drives lifetime value for diagnostic platform manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-certified molecular oncology panels from CLIA-waived rapid antigen tests and commodity metabolic chemistry assays. Pricing pressure stems from group purchasing organization administrative fee extraction and hospital procurement unbundling of service contracts from equipment maintenance agreements. Diagnostic centers in India and Brazil exhibit highest price sensitivity, while academic medical centers in Germany and Switzerland demonstrate lowest elasticity for specialized assay menus.
Supply Chain Analysis
Contract manufacturing concentration for automated analyzers rests with Siemens Healthineers AG in Germany, Danaher Corporation facilities in the United States, and bioMérieux SA production sites in France. Reagent biochemical inputs draw from European and North American chemical manufacturers, while disposable consumables source from polymer processing clusters in China and India. Single-source vulnerability concentrates in specialty enzyme suppliers for nucleic acid amplification protocols. Distribution runs through national reference laboratory networks and hospital outreach programs, with group purchasing organizations inserting administrative layers between manufacturers and end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized nucleic acid amplification expertise concentrates in metropolitan academic medical centers, constraining rural laboratory expansion and creating acquisition premiums for credentialed technician teams.
For Market Incumbents: Harden compliance infrastructure around FDA Laboratory Developed Test analytical validity requirements before mid-scale competitors complete rebuilds. Deepen captive supply of specialty biochemical reagents through backward integration into European chemical manufacturer partnerships to buffer input cost volatility from concentration risk. For New Entrants and Emerging Players: Pursue tier-2 and tier-3 city diagnostic center partnerships in India and Brazil where reference laboratory capacity is expanding fastest. Target CLIA-waived rapid antigen test displacement of low-complexity send-out volumes from United States hospital emergency departments as the most penetrable white space. Lead with technical training services bundled with reagent supply contracts to secure installed instrument base lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-enabled algorithmic diagnostics as cloud-native laboratory information systems reduce IT overhead for mid-scale reference laboratories. Long-term viability favors platforms with recurring consumable revenue tied to installed bases rather than capital-intensive instrument placements. Watch FDA validation timeline extensions for Laboratory Developed Tests as the signal indicating margin compression inflection for mid-scale reference laboratory acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Contract Expansion | Shifts hospital laboratories from capital ownership to operational expenditure models, locking in recurring revenue. |
| AI-Assisted Pathology Partnership | Creates new service revenue streams in oncology diagnostics through digital imaging algorithm convergence. |
| EU IVDR Technical Documentation Rebuild | Forces multi-site validation study consolidation across European reference laboratory networks to distribute regulatory costs. |
| Direct-to-Consumer Retail Pharmacy Channel | Bypasses traditional physician-referral pathways for routine health screening volume capture. |
| Molecular Diagnostics Technician Training Program | Addresses nucleic acid amplification expertise scarcity constraining rural laboratory expansion. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, Clinical Laboratory Improvement Amendments enforcement records, and hospital procurement databases. Primary interviews captured perspectives from clinical laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at diagnostic platform manufacturers. Secondary validation drew from SEC 10-K disclosures, CMS Medicare reimbursement data, and ISO 15189 accreditation body reports. Bottom-up test volume modeling and top-down healthcare expenditure allocation provided cross-check triangulation.
Forecast inputs span reagent consumption rates by installed instrument base, CLIA personnel mandate compliance costs, and automation adoption curves across hospital core laboratories. Segmentation dimensions include product type tier, end user consolidation level, technology maturity grade, and application reimbursement density. CAGRs derive from regression against historical test volume growth and forward projection of regulatory cost pass-through. Molecular diagnostics platform placement cycles and group purchasing organization contract renewal calendars inform timing assumptions across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement rates, diagnostic test utilization patterns, or specialty chemical input costs would shift the trajectory. Forecasts reflect documented assumptions regarding FDA Laboratory Developed Test framework implementation pace and EU In Vitro Diagnostic Regulation transition timelines. Quarterly review of CLIA waiver expansion decisions and reference laboratory M&A activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Service Laboratory Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Global Sterility Testing Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
Monkeypox Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Prothrombin Time Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Friability Tester Market
Testing Services
Lab Screening Test Kit Market
Testing Services
Fecal Pancreatic Elastase Testing Market