
 Clinical Trials Outsourcing Market | 2026-2036
Clinical Trials Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trials Outsourcing Market Insights
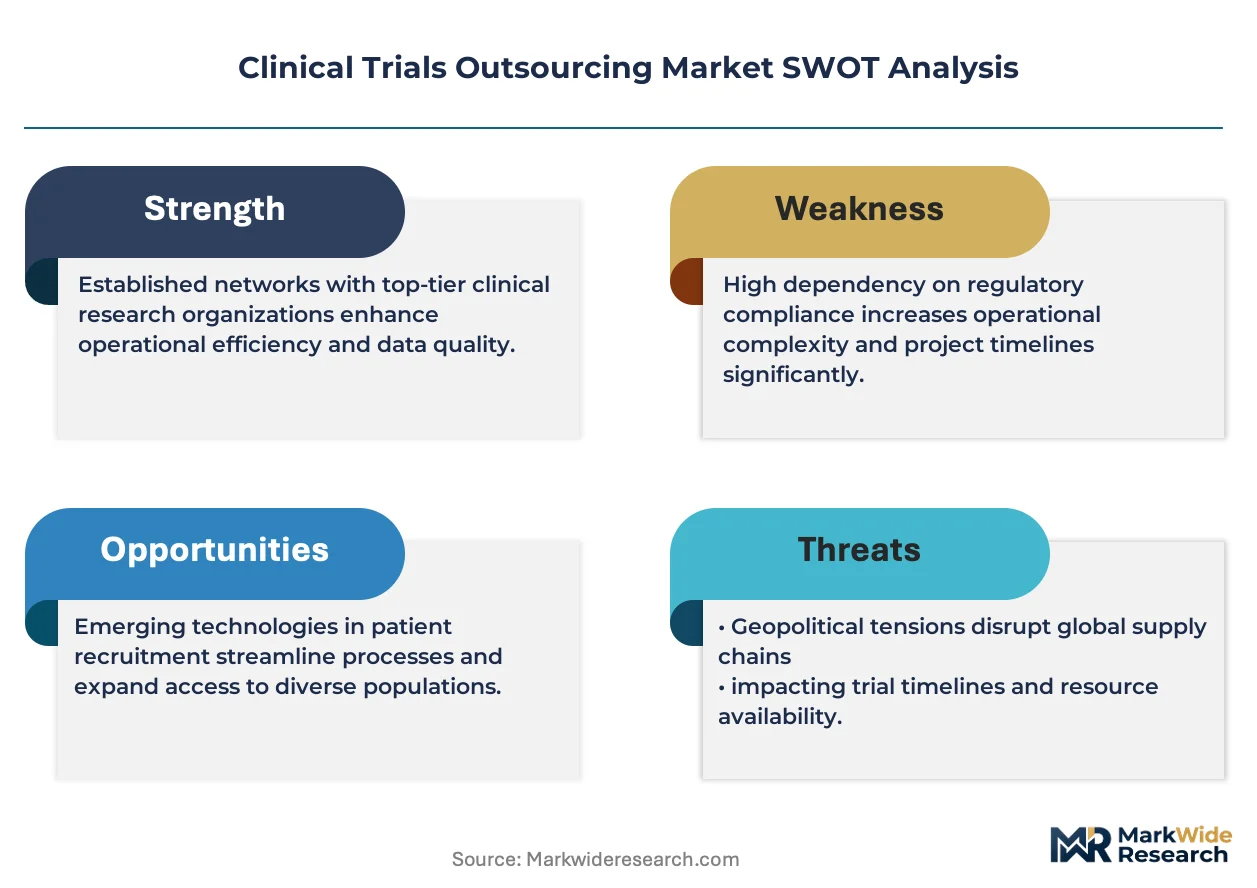
Synthetic biomaterials and digital endpoints are rebalancing cost structures across patient recruitment and data capture. IQVIA leverages its real-world evidence platform to anchor large-scale oncology outsourcing contracts. Charles River Laboratories sustains preclinical-to-clinical continuity through integrated laboratory services. Medpace differentiates via therapeutic specialization in metabolic and cardiovascular indications.
Clinical trials outsourcing encompasses the transfer of study design, site management, patient monitoring, regulatory submission, and data analytics functions to third-party service providers, typically governed by Good Clinical Practice guidelines and ISO 14155 standards for medical device studies. Its primary purpose is to compress development timelines, access specialized investigator networks, and distribute regulatory risk across geographic jurisdictions. Functional outsourcing dominates service-type revenue by allowing sponsors to retain strategic control while delegating execution-heavy monitoring and data-management tasks. Phase III studies represent the largest value pool given their scale and complexity, though Phase II segments expand fastest as adaptive trial designs proliferate. Hybrid delivery models gain share as sponsors blend retained capabilities with external expertise to preserve institutional knowledge.
FDA's risk-based monitoring guidance and EMA's Clinical Trial Regulation reshape provider qualification requirements and site-selection protocols across transatlantic studies. The EU AI Act introduces algorithmic-audit obligations for machine-learning tools used in patient stratification and adverse-event prediction. Stakeholders must weigh regulatory divergence against operational standardization when configuring multi-regional trial architectures.
Market Dynamics
FDA's risk-based monitoring guidance and EMA's Clinical Trial Regulation are compressing site-selection timelines while elevating data-integrity standards across transatlantic studies. Biopharmaceutical sponsors now face a structural imperative to externalize execution-heavy functions without ceding strategic control over trial design.
Growth Catalysts
- Adaptive trial designs:Bayesian protocols and master protocols allow mid-study modifications that reduce patient exposure while preserving statistical power. Contract research organizations with biostatistical depth capture expanded Phase II mandates.
- EMA Clinical Trial Regulation harmonization:The EU's unified submission portal and safety reporting standards accelerate multi-country study activation. Sponsors consolidate European site networks through single-CRO relationships.
- Real-world evidence integration:Synthetic control arms and external comparator datasets reduce placebo-arm requirements in oncology and rare disease studies. Providers with claims-data partnerships differentiate on recruitment speed.
Market Restraints
- Investigator site concentration:Principal investigator availability concentrates in established academic medical centers across the United States, Germany, and the United Kingdom. Site activation timelines extend where competing studies saturate high-performing locations.
- Data localization requirements:China's NMPA and Russia's data-sovereignty rules fragment cloud-based clinical data management architectures. Multi-regional trials require redundant hosting infrastructure that elevates fixed costs.
- Patient recruitment cost inflation:Digital advertising rates for rare disease and pediatric indications have risen sharply on Meta and Google platforms. Recruitment budgets consume disproportionate shares of Phase II study expenditures.
Strategic Opportunities
- Decentralized trial infrastructure in Japan:PMDA's 2023 guidance on remote monitoring and electronic informed consent enables home nursing and direct-to-patient drug shipment. First-mover CROs secure metabolic and cardiovascular study contracts.
- EU AI Act algorithmic-audit services:Machine learning tools for patient stratification and adverse-event prediction require documented bias testing and performance validation. Specialized compliance units represent attachable revenue streams.
- Gene therapy manufacturing integration:Viral vector production and patient-cell processing demand proximity between clinical sites and manufacturing facilities. Providers with in-house GMP capabilities capture end-to-end cell-and-gene therapy contracts.
Industry Challenges
- Clinical data scientist scarcity:Biostatisticians with Bayesian modeling and adaptive design expertise command premium compensation. Talent retention requires equity participation and remote-work flexibility that conflicts with site-based monitoring cultures.
- Legacy CTMS integration:Sponsor investments in on-premise clinical trial management systems resist API-based connectivity with modern eCOA and ePRO platforms. Middleware development consumes implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trials Outsourcing Market |
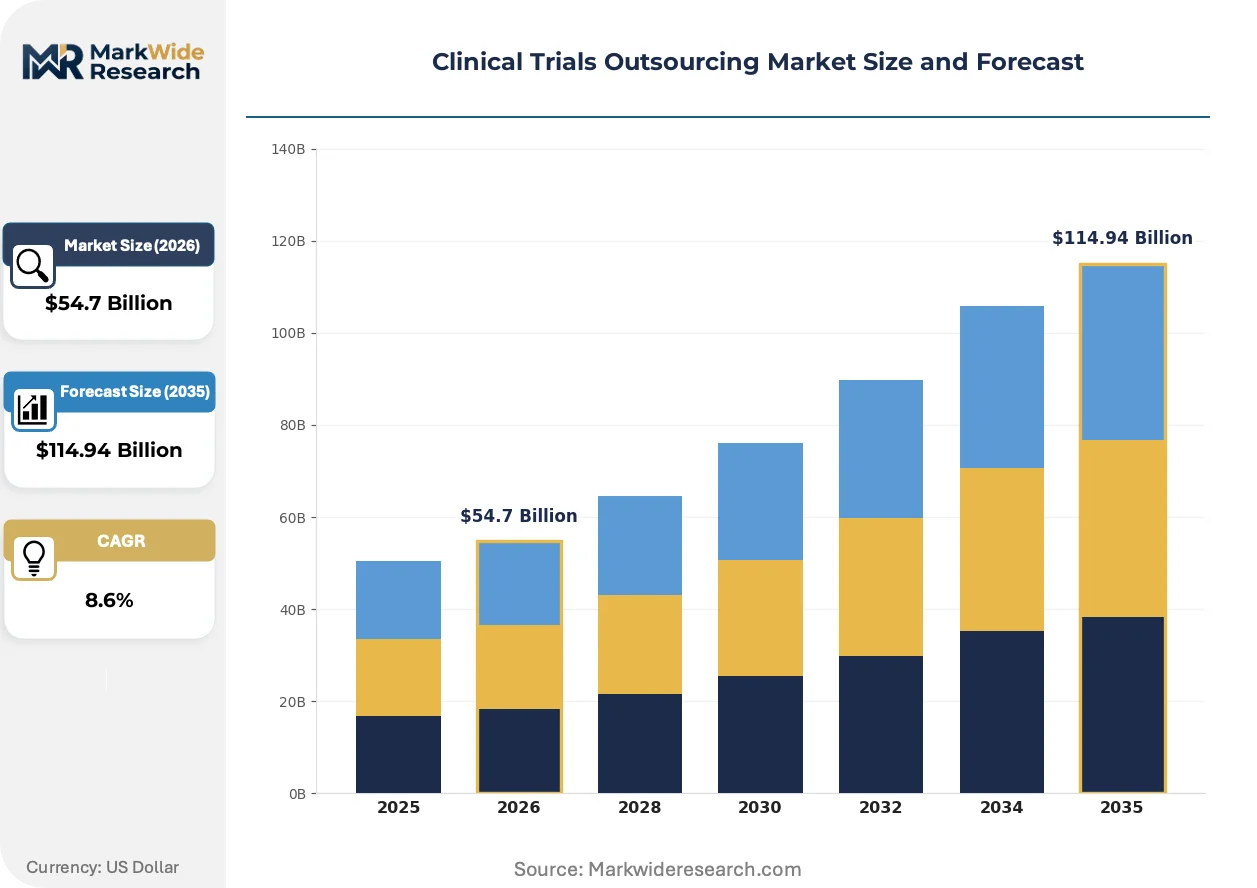
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $114.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Management, Monitoring, Regulatory Affairs, Clinical Project Management End User: Pharmaceutical Companies, Biotechnology Firms, Medical Device Manufacturers, Contract Research Organizations Study Phase: Phase I, Phase II, Phase III, Phase IV Delivery Model: Fully Outsourced, Hybrid Model, Functional Outsourcing, In-House |
| Companies Covered | ICON plc, IQVIA, Thermo Fisher Scientific Inc., Parexel, Syneos Health, Medpace, Charles River Laboratories, SGS Life Sciences, LabCorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trials Outsourcing Market Trends and Innovations
Digital biomarkers and distributed data capture are restructuring how endpoints are measured, validated, and submitted to regulators. The convergence of wearable sensors, cloud infrastructure, and machine learning is compressing traditional site-centric models.
Artificial intelligence is automating adverse-event narrative generation and medical coding workflows that previously required manual clinical research associate review. Mid-tier CROs deploy natural language processing tools to reduce pharmacovigilance staffing ratios. The technology is automating case processing timelines from intake to regulatory submission, compressing safety database lock intervals by standardizing narrative structures.
EU AI Act algorithmic-audit obligations now extend to machine-learning tools deployed for patient stratification and predictive safety analytics. Providers must document training-data provenance, performance metrics across demographic subgroups, and human-oversight protocols. Oncology studies utilizing AI-derived eligibility criteria face heightened scrutiny in France and Germany, where national regulators layer supplemental validation requirements atop the EU framework.
Biopharmaceutical procurement teams now unbundle monitoring, data management, and biostatistics functions to optimize cost-performance ratios across therapeutic areas. Large sponsors retain strategic biostatistical capabilities in-house while outsourcing execution-heavy site monitoring to regional specialists. This pattern concentrates most visibly in the United States, where sponsor procurement organizations have established preferred-provider tiers based on therapeutic-area track records and technology-platform compatibility.
Clinical Trials Outsourcing Market Segmentation
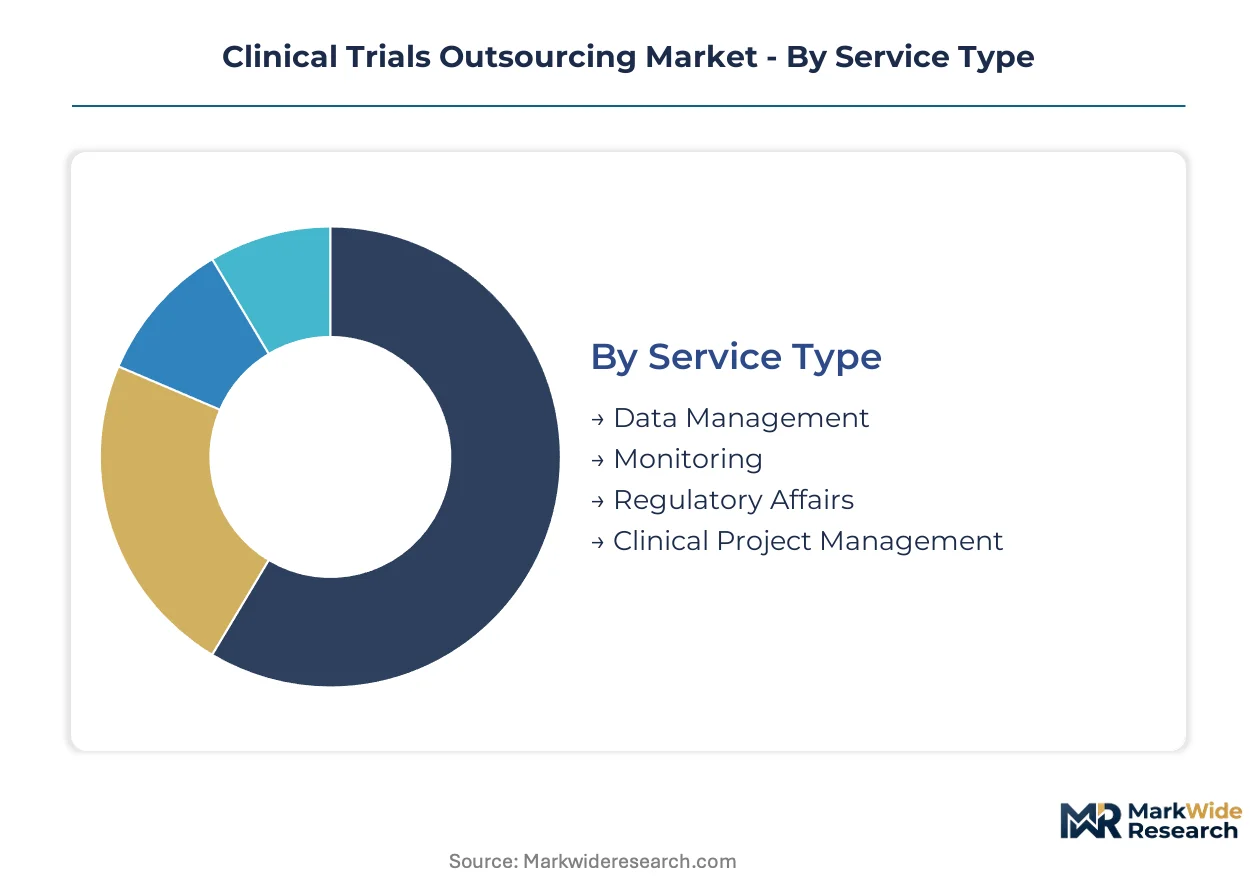
Clinical trials outsourcing segments reflect sponsor decisions about which capabilities to retain versus externalize. Procurement teams configure service bundles based on therapeutic complexity, regulatory geography, and internal capacity constraints.
Service Type:
Upgrade cycles in clinical technology platforms are forcing sponsors to reassess which service layers justify in-house investment versus vendor delegation.
- Data Management:Electronic data capture systems and clinical databases require continuous platform modernization to maintain FDA 21 CFR Part 11 compliance. Pharmaceutical sponsors in the United States concentrate demand here as real-world evidence integration becomes standard for oncology submissions.
- Monitoring:Risk-based monitoring protocols reduce on-site visit frequency while elevating data-quality thresholds for remote oversight. Site activation bottlenecks in Germany and the United Kingdom drive demand for specialized monitoring networks that compress study startup timelines.
- Regulatory Affairs:Submission dossier preparation and health authority correspondence demand jurisdiction-specific expertise.
- Clinical Project Management:Cross-functional coordination of investigational sites, vendors, and sponsor teams.
Data Management sits at the top of the volume ranking, with Monitoring climbing the fastest.
End User:
Cost tier differentiation separates large-cap sponsors with retained capabilities from emerging players requiring full-service partnerships.
- Pharmaceutical Companies:Global drug developers maintain internal clinical operations teams while outsourcing execution-heavy site monitoring and data management for specific therapeutic programs. United States-based sponsors lead functional unbundling trends, retaining strategic biostatistics while delegating operational tasks.
- Biotechnology Firms:Venture-backed developers lack scale for captive clinical infrastructure and depend on CROs for end-to-end study execution. Rare disease and gene therapy pipelines in Massachusetts and California clusters generate concentrated demand for specialized providers.
- Medical Device Manufacturers:ISO 14155 compliance requirements and notified body coordination.
- Contract Research Organizations:Tier-2 and regional CROs subcontract specialized functions to niche providers.
Pharmaceutical Companies command the largest share of outsourced spend, though Biotechnology Firms are expanding most quickly.
Study Phase:
Application complexity escalates from safety-focused early phases to large-scale efficacy demonstrations.
- Phase III:Randomized controlled trials enrolling thousands of patients across multiple countries represent the highest-value outsourcing contracts. Complexity around adaptive design implementation and interim analysis planning drives sponsor reliance on CRO biostatistical depth.
- Phase II:Proof-of-concept and dose-ranging studies increasingly deploy Bayesian protocols and master protocols that allow mid-study modifications. Adaptive design proliferation in immuno-oncology and rare disease programs accelerates outsourcing demand.
- Phase I:First-in-human and dose-escalation studies in healthy volunteers or specific patient populations.
- Phase IV:Post-marketing surveillance and real-world evidence generation.
Phase III dominates absolute contract value, with Phase II gaining share fastest.
Delivery Model:
Customer type and internal capability maturity determine whether sponsors pursue full delegation or selective supplementation.
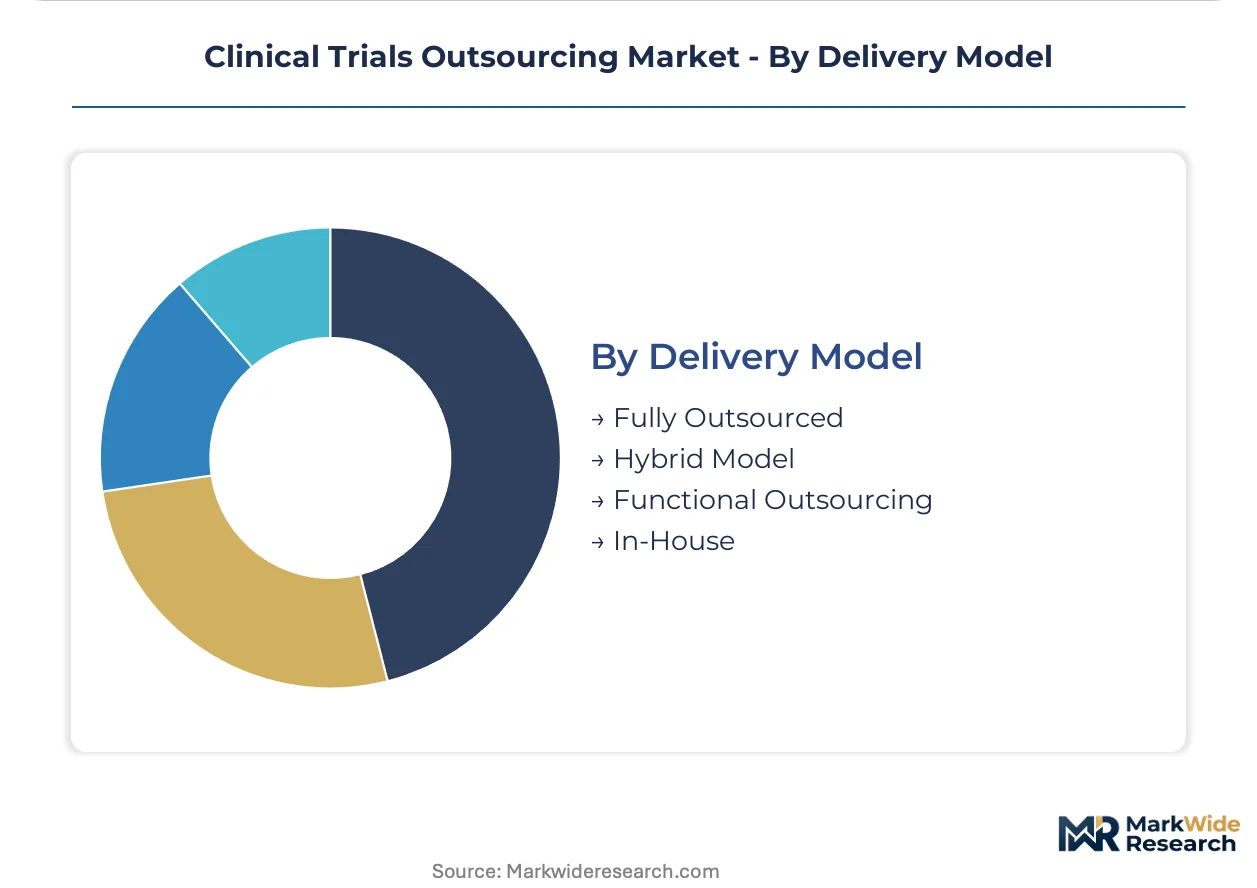
- Functional Outsourcing:Sponsors retain strategic control over trial design and regulatory strategy while delegating execution-heavy monitoring, data management, and biostatistics to specialized vendors. This model preserves institutional knowledge while accessing operational scale.
- Hybrid Model:Blended configurations combine retained project management with externalized site networks and technology platforms. Large United States sponsors favor this approach to maintain direct investigator relationships.
- Fully Outsourced:Complete delegation of study execution to a single CRO partner.
- In-House:Captive clinical operations with minimal external support.
Functional Outsourcing holds the leading position in contract volume, while Hybrid Model adoption is accelerating most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors sponsor spending on decentralized trial infrastructure, with FDA risk-based monitoring guidance accelerating provider consolidation across transatlantic study networks.
United States
Massachusetts and California clusters generate concentrated demand for gene therapy and rare disease outsourcing. FDA's 2023 guidance on remote data capture enables direct-to-patient drug shipment models. The Research Triangle Park in North Carolina anchors large-scale Phase III site activation networks.
Germany
EMA Clinical Trial Regulation harmonization accelerates multi-country study activation through the unified CTIS portal. BfArM and PEI coordinate on advanced therapy medicinal products. The Munich and Berlin metropolitan areas concentrate investigator sites for oncology adaptive trials.
United Kingdom
MHRA post-Brexit recognition agreements with FDA sustain transatlantic study continuity. The Golden Triangle between London, Oxford, and Cambridge hosts specialized providers for cell-and-gene therapy manufacturing integration. NHS Digital infrastructure supports real-world evidence partnerships.
Japan
PMDA's 2023 guidance on electronic informed consent and remote monitoring enables home nursing deployment. The Kanto region around Tokyo concentrates metabolic and cardiovascular study contracts. Osaka-based sponsors accelerate hybrid delivery model adoption for Asia-Pacific expansion.
India
CDSCO streamlined approval timelines for bioequivalence studies attract Phase I outsourcing from US sponsors. The Hyderabad-Bengaluru corridor anchors data management and biostatistics delivery centers. Gujarat's pharmaceutical manufacturing zones support integrated clinical-to-commercial pathways.
Clinical Trials Outsourcing Market Competitive Landscape
Global majors compete with regional champions across therapeutic specialization and technology platform depth. The market structure tiers into full-service integrators, therapeutic specialists, and functional boutiques. Three archetypes dominate: scale-driven clinical research organizations with integrated laboratory networks, boutique providers with metabolic or cardiovascular concentration, and technology-enabled platforms with real-world evidence partnerships. Competitive intensity centers on M&A for biostatistical talent and strategic partnerships for decentralized trial infrastructure.
Among full-service integrators, IQVIA and Thermo Fisher Scientific occupy positions anchored by real-world evidence platforms and integrated laboratory services respectively. Charles River Laboratories exemplifies the preclinical-to-clinical continuity archetype through captive GMP capabilities. Medpace represents therapeutic specialization, with concentration in metabolic and cardiovascular indications distinguishing its competitive position.
| Leading Market Players |
|---|
| ICON plc |
| IQVIA |
| Thermo Fisher Scientific Inc. |
| Parexel |
| Syneos Health |
| Medpace |
| Charles River Laboratories |
| SGS Life Sciences |
| LabCorp |
| Others |
Pricing and Supply Chain Analysis
Captive GMP manufacturing capabilities anchor both supply security and pricing power for cell-and-gene therapy contracts, where viral vector production proximity to clinical sites commands premium positioning against functionally outsourced competitors.
Pricing Analysis
Input-cost pass-through from biostatistical talent scarcity and digital platform licensing reshapes contract economics across service tiers. Project-based pricing with outcome-linked milestones dominates Phase II adaptive trials, while subscription-tiered SaaS models govern data management and eCOA platform access. Price differentiation hinges on therapeutic-area specialization depth and FDA 21 CFR Part 11 certification tier. Pricing pressure stems from sponsor procurement unbundling that fragments monitoring, data management, and biostatistics into competitive bidding. Biotechnology firms exhibit highest price sensitivity given venture-backed budget constraints, whereas large pharmaceutical sponsors prioritize speed-to-insight over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from sponsor risk-management protocols mandate multi-CRO qualification for critical functions across transatlantic studies. Geographic supply concentrates in the United States, India, and Germany, with Hyderabad-Bengaluru data centers and Boston-Cambridge site networks serving distinct workflow layers. Raw material dependencies span cloud infrastructure services, wearable sensor hardware, and specialized laboratory reagents. Supply chain risk centers on data-localization mandates from China's NMPA and Russia's data-sovereignty rules that fragment cloud architectures. Distribution runs through direct sponsor-CRO relationships with limited intermediary presence, though tier-2 CROs increasingly subcontract to niche functional boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, where EMA Clinical Trial Regulation harmonization and FDA risk-based monitoring guidance continuously expand compliance-driven outsourcing demand.
For Market Incumbents: Deepen therapeutic-area concentration in metabolic and cardiovascular indications where investigator network relationships resist commoditization. Invest in captive GMP manufacturing capabilities to capture end-to-end gene therapy contracts from emerging biotechnology sponsors. Defend against mid-tier CROs deploying natural language processing tools for pharmacovigilance automation by embedding real-world evidence platform partnerships that accelerate oncology recruitment timelines.
For New Entrants and Emerging Players: The premium-economy price-point gap in decentralized trial infrastructure creates entry space for technology-enabled platforms targeting mid-cap biotechnology firms. Japan's PMDA 2023 guidance on electronic informed consent offers first-mover positioning for home nursing and direct-to-patient deployment. Target EU AI Act algorithmic-audit services as a white-space attachable revenue stream, leveraging bias-testing documentation capabilities that larger CROs have not productized.
For Investors and Strategic Acquirers: Roll-up economics work for regional monitoring specialists because sponsor procurement consolidation demands geographic coverage breadth that fragmented site networks cannot deliver independently. Five-to-ten year viability favors CROs with demonstrated adaptive trial design biostatistical depth and established CTIS portal navigation capabilities. Monitor FDA guidance evolution on synthetic control arms as the inflection signal for real-world evidence integration maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Capability Buildout | Bayesian protocol expertise captures Phase II expansion mandates from immuno-oncology sponsors. |
| EU AI Act Compliance Service Launch | Algorithmic-audit documentation addresses PMDA and BfArM supplemental validation requirements. |
| Decentralized Trial Infrastructure Partnership | Home nursing networks in Japan's Kanto region compress metabolic study activation timelines. |
| Real-World Evidence Platform Integration | Claims-data partnerships differentiate recruitment speed for rare disease oncology programs. |
| Gene Therapy Manufacturing Co-location | Proximity between viral vector production and clinical sites secures cell-and-gene therapy contracts. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and CRO procurement officers; secondary validation through FDA filings, EMA CTIS submissions, ClinicalTrials.gov records, and sponsor 10-K disclosures; plus bottom-up service-type segmentation and top-down market sizing — were reconciled to produce volume and value estimates across the analysis window.
Cross-referencing historical outsourcing penetration patterns against panel input from site activation directors and biostatistics hiring managers shaped the analytical framework. Segmentation dimensions modeled include service type, study phase, delivery model, therapeutic area concentration, and regional regulatory cluster. CAGRs were derived from sponsor spending intention surveys and CRO capacity expansion announcements, with gene therapy pipeline velocity and decentralized trial adoption curves serving as industry-specific forecast inputs.
Caveats apply where FDA guidance revisions on remote data capture, EMA CTIS portal operational disruptions, or sudden shifts in biostatistical labor markets could materially shift the outlook. Deviation in sponsor unbundling intensity or data-localization enforcement rigor would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
India CRO Market
Clinical Research
AI-Based Clinical Trial Solutions for Patient Matching Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
HIV Clinical Trials Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Healthcare Europe Clinical Data Analytics Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Real World Evidence Linkage Services Market