
 Europe Blood Screening Market | 2026-2036
Europe Blood Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Blood Screening Market Insights
German diagnostic manufacturers is pivoting toward automated high-throughput screening platforms to serve centralized blood service networks across Central Europe. Grifols leverages its plasma-derived expertise to sustain specialized reagent supply chains for European transfusion centers. Abbott Laboratories anchors its position through integrated instrument-reagent systems that dominate hospital laboratory workflows. Bio-Rad Laboratories, Inc. differentiates via quality control panels and independent assay validation tools that blood banks require for regulatory compliance.
Europe blood screening encompasses laboratory and point-of-care analytical methods designed to detect pathogens, blood group antigens, and transfusion-transmissible infections in donor and patient samples, typically operating with analytical sensitivities below one copy per milliliter for nucleic acid targets. The primary purpose is ensuring infectious disease safety in transfusion medicine and solid organ transplantation protocols. Nucleic acid testing commands premium positioning due to its window-period reduction capabilities for HIV and hepatitis C detection, while serological testing retains substantial volume in routine blood typing and antibody screening. Molecular diagnostics represents the fastest-expanding technology dimension as European laboratories adopt multiplex PCR and next-generation sequencing for emerging pathogen surveillance.
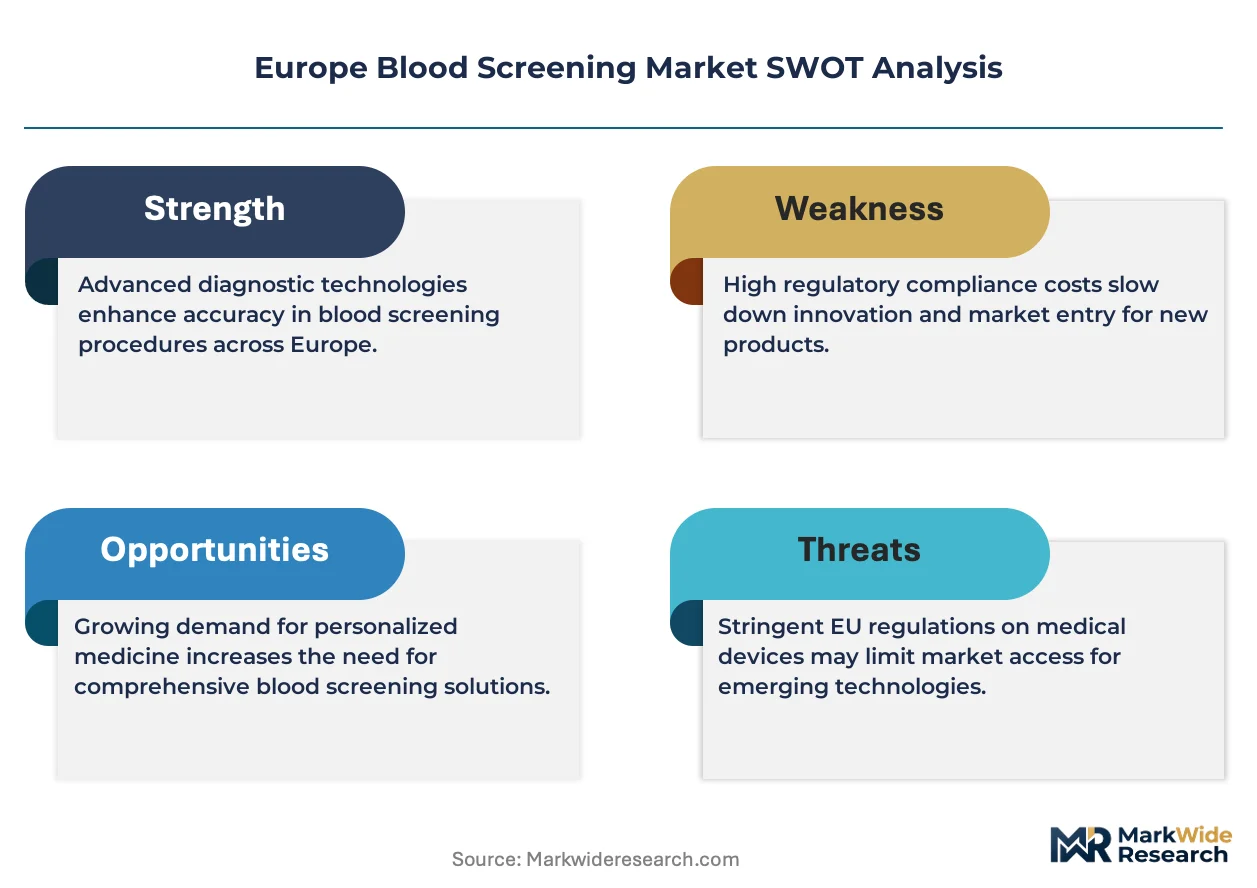
EMA coordinates centralized marketing authorization pathways for novel blood screening assays, while the EU IVDR imposes strengthened clinical evidence and post-market surveillance obligations on diagnostic manufacturers. The EU Green Deal indirectly shapes procurement criteria through sustainability requirements for single-use consumables and instrument energy efficiency. Blood banks and hospital transfusion services must monitor evolving pathogen emergence patterns and corresponding regulatory guidance updates to align capital investment cycles with compliance deadlines.
Market Dynamics
The EU In Vitro Diagnostic Regulation (IVDR) is compressing compliance timelines for blood screening assay manufacturers, forcing rapid revalidation of existing product portfolios and reshaping procurement criteria across European transfusion networks.
Growth Catalysts
- IVDR compliance mandates:Strengthened clinical evidence requirements under the EU regulation are accelerating replacement cycles for legacy serological assays, creating pull-through demand for validated nucleic acid testing platforms in German and French blood service networks.
- Centralized procurement models:Germany's unified blood service structure concentrates volume purchasing power, enabling standardization on high-throughput screening instruments that reduce per-test operational costs.
- Multiplex PCR adoption:European hospital laboratories are integrating simultaneous pathogen detection capabilities for HIV, hepatitis B and C, and emerging arboviruses into routine donor screening workflows.
Market Restraints
- Reagent supply concentration:Specialized enzyme and primer manufacturing for nucleic acid testing concentrates among a limited supplier base in Southern Germany and the Netherlands, creating vulnerability to single-source disruptions.
- IVDR transition friction:The regulation's tightened post-market surveillance obligations impose documentation burdens that delay new assay launches by 18-24 months for mid-tier manufacturers lacking established quality management systems.
- Capital intensity barriers:Automated high-throughput screening platforms require substantial upfront instrument investment that fragments purchasing authority between hospital laboratories and centralized blood services.
Strategic Opportunities
- Eastern European network expansion:Poland and Romania are consolidating fragmented regional blood services into national procurement structures, creating entry points for integrated screening platform vendors.
- Next-generation sequencing integration:Convergence of targeted amplicon sequencing with existing nucleic acid testing workflows enables surveillance for unknown or emerging transfusion-transmissible pathogens without assay redevelopment.
- EU Green Deal procurement criteria:Sustainability requirements for single-use consumables and instrument energy efficiency are creating preference differentiation for manufacturers with circular economy-certified reagent supply chains.
Industry Challenges
- IVDR technical documentation capacity:The regulation's expanded clinical evidence requirements have created acute scarcity of regulatory affairs specialists with diagnostic device experience across European manufacturers.
- Legacy instrument interoperability:Blood banks operating mixed-vendor instrument fleets face integration complexity when connecting new nucleic acid testing platforms to existing laboratory information management systems.
- Competency-based staffing gaps:Molecular diagnostics expertise remains concentrated in academic medical centers, limiting operational readiness at smaller regional transfusion services transitioning from serological to nucleic acid testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Blood Screening Market |
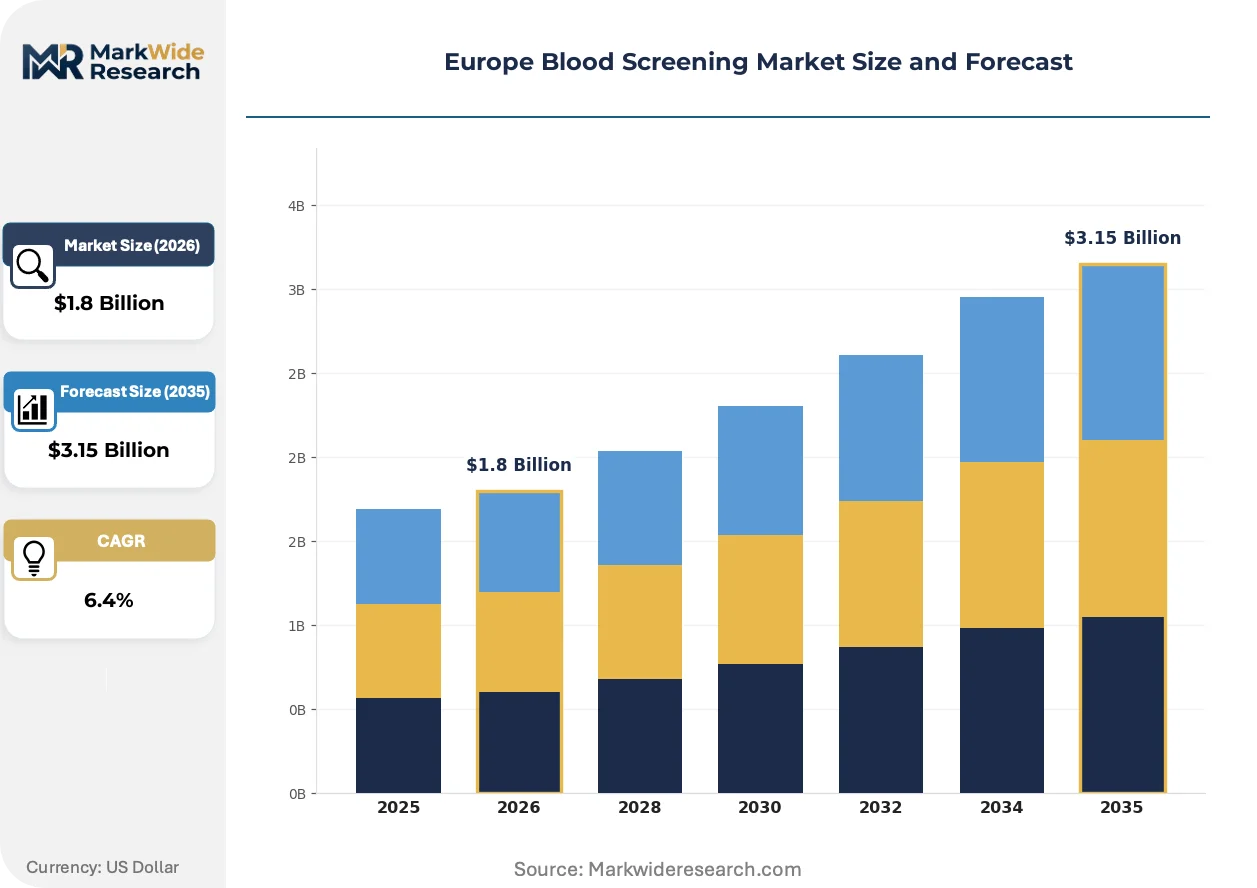
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Immunoassays, Nucleic Acid Testing, Rapid Tests, Western Blot Technology: Serological Testing, Molecular Diagnostics, Microarray, Next-Generation Sequencing Application: Transfusion, Infectious Disease Testing, Organ Transplantation, Hematology End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutions |
| Companies Covered | F. Hoffmann-La Roche Ltd., Grifols, Danaher Corporation, Abbott Laboratories, Bio-Rad Laboratories, Inc., Thermo Fisher Scientific Inc., Becton, Dickinson and Company, Siemens AG, bioMérieux, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Blood Screening Market Trends and Innovations
European blood screening is experiencing technology convergence between molecular diagnostics and automated sample handling, compressing turnaround times while expanding pathogen detection breadth beyond traditional transfusion-transmissible infection panels.
Multiplex PCR platforms are modularizing assay development for blood screening laboratories. These systems enable simultaneous detection of multiple viral targets within single reaction wells. German and French centralized blood services are standardizing procurement on such platforms to reduce instrument footprint. The technology is modularizing how regional laboratories configure screening menus without complete platform replacement.
The EU IVDR's strengthened post-market surveillance obligations are reshaping manufacturer business models. Diagnostic companies must now maintain active clinical follow-up for approved assays rather than episodic renewal submissions. Blood banks in Benelux and Nordic countries are most affected, as they had relied on grandfathered legacy assays with minimal ongoing clinical documentation.
Transfusion services are consolidating reagent purchasing through multi-year total-cost-of-ownership contracts rather than transactional instrument-reagent bundling. This displaces traditional per-test pricing models in Spanish and Italian hospital networks. The shift is most visible in Germany, where centralized blood services negotiate directly with manufacturers for supply security guarantees spanning entire instrument lifecycles.
Europe Blood Screening Market Segmentation
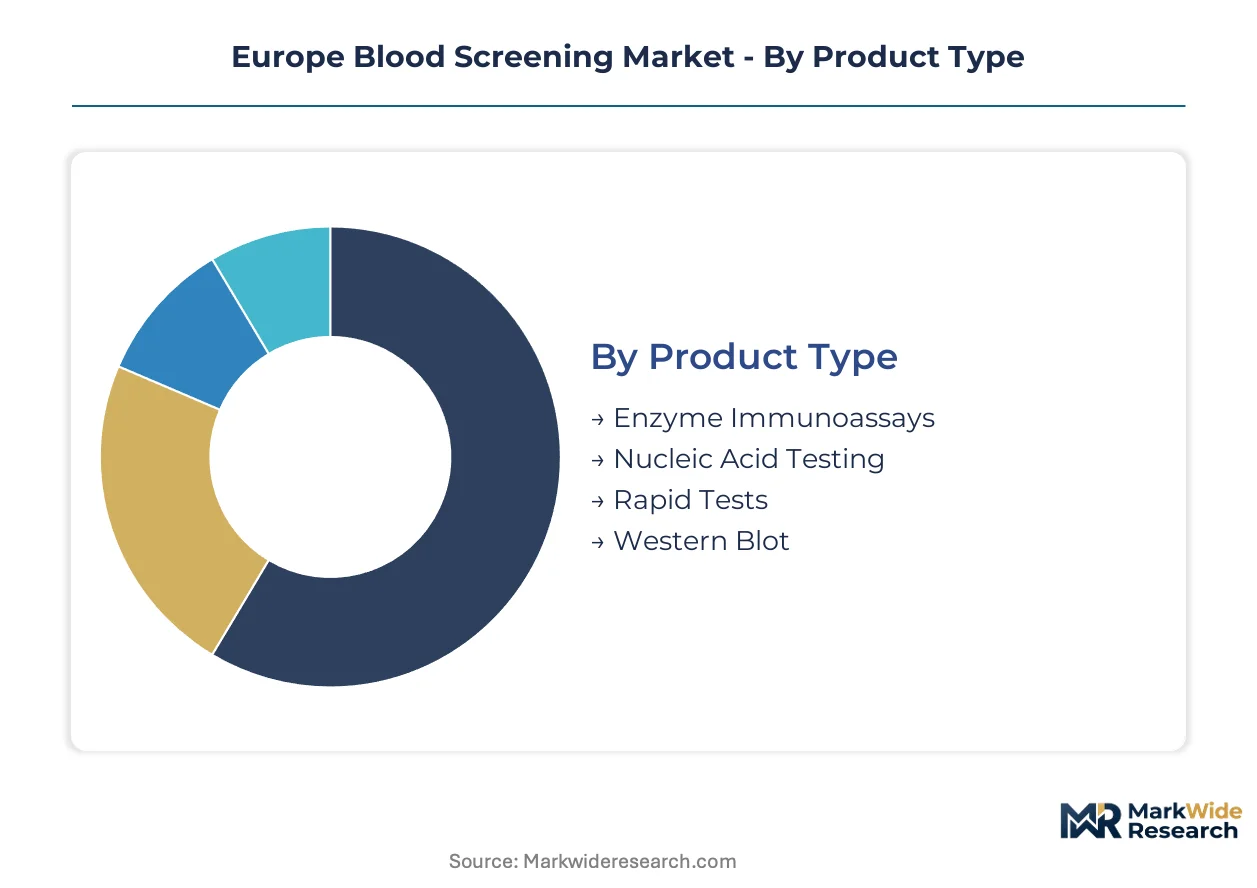
Segmentation in the Europe Blood Screening Market reflects divergent capital deployment patterns across diagnostic modalities. Procurement decisions hinge on throughput requirements, regulatory compliance burdens, and the transition from serological to molecular platforms mandated by EU IVDR timelines.
Product Type:
Nucleic acid testing platforms demand the steepest upfront capital commitment, with automated high-throughput instruments requiring dedicated laboratory infrastructure and specialized technical staffing.
- Nucleic Acid Testing:Polymerase chain reaction and transcription-mediated amplification platforms detect viral genetic material at sensitivities below one copy per milliliter. German centralized blood services concentrate procurement for HIV and hepatitis C window-period reduction, driven by EU IVDR mandates for enhanced clinical evidence.
- Enzyme Immunoassays:Colorimetric antibody detection systems process high sample volumes on automated analyzers with lower per-test reagent costs. French hospital laboratories retain substantial installed bases for routine blood typing, constrained by IVDR revalidation timelines that compress replacement cycles.
- Rapid Tests:Lateral flow immunochromatographic assays enable point-of-care screening without laboratory infrastructure. Emergency departments in Italian and Spanish hospitals deploy these for urgent transfusion decisions.
- Western Blot:Confirmatory protein detection method with high specificity for antibody validation. Reference laboratories in the Netherlands maintain limited capacity for indeterminate serological result resolution.
Nucleic acid testing absorbs the bulk of installed capacity; rapid tests are expanding most quickly in point-of-care settings.
Technology:
Technology selection correlates directly with laboratory scale, where larger facilities amortize molecular platform costs across higher test volumes while smaller sites retain serological workflows.
- Molecular Diagnostics:PCR and nucleic acid amplification technologies dominate pathogen detection with multiplexing capabilities. Benelux blood services standardize on these platforms for simultaneous HIV, hepatitis B and C screening.
- Next-Generation Sequencing:Targeted amplicon sequencing enables surveillance for unknown transfusion-transmissible pathogens without assay redevelopment. Academic medical centers in Germany and Switzerland pilot integration with existing nucleic acid testing workflows.
- Serological Testing:Antibody and antigen detection methods using agglutination, precipitation, and complement fixation reactions. Eastern European blood banks maintain these for cost-constrained routine screening.
- Microarray:Solid-phase multiplex immunoassays for extended blood group antigen phenotyping. Specialized transfusion services in France and the UK deploy these for complex alloimmunized patients.
Molecular diagnostics commands the greatest capital allocation; next-generation sequencing is gaining share fastest in reference laboratory networks.
Application:
Application segmentation tracks divergent reimbursement and liability frameworks, with transfusion medicine commanding the most stringent screening protocols.
- Transfusion:Pre-donation and pre-transfusion screening for infectious markers and blood group compatibility. German and Austrian blood services enforce the continent's most comprehensive nucleic acid testing panels.
- Infectious Disease Testing:Surveillance for HIV, hepatitis viruses, syphilis, and emerging arboviruses in donor populations. Southern European programs extend screening to West Nile virus and dengue seasonally.
- Organ Transplantation:Extended pathogen screening for solid organ and hematopoietic stem cell donors. Nordic transplant networks coordinate standardized protocols across national boundaries.
- Hematology:Coagulation factor and platelet function testing for transfusion-refractory patients. Specialized centers in France and Italy maintain dedicated laboratory capacity.
Transfusion applications anchor procurement volume; infectious disease testing is broadening fastest with emerging pathogen inclusion.
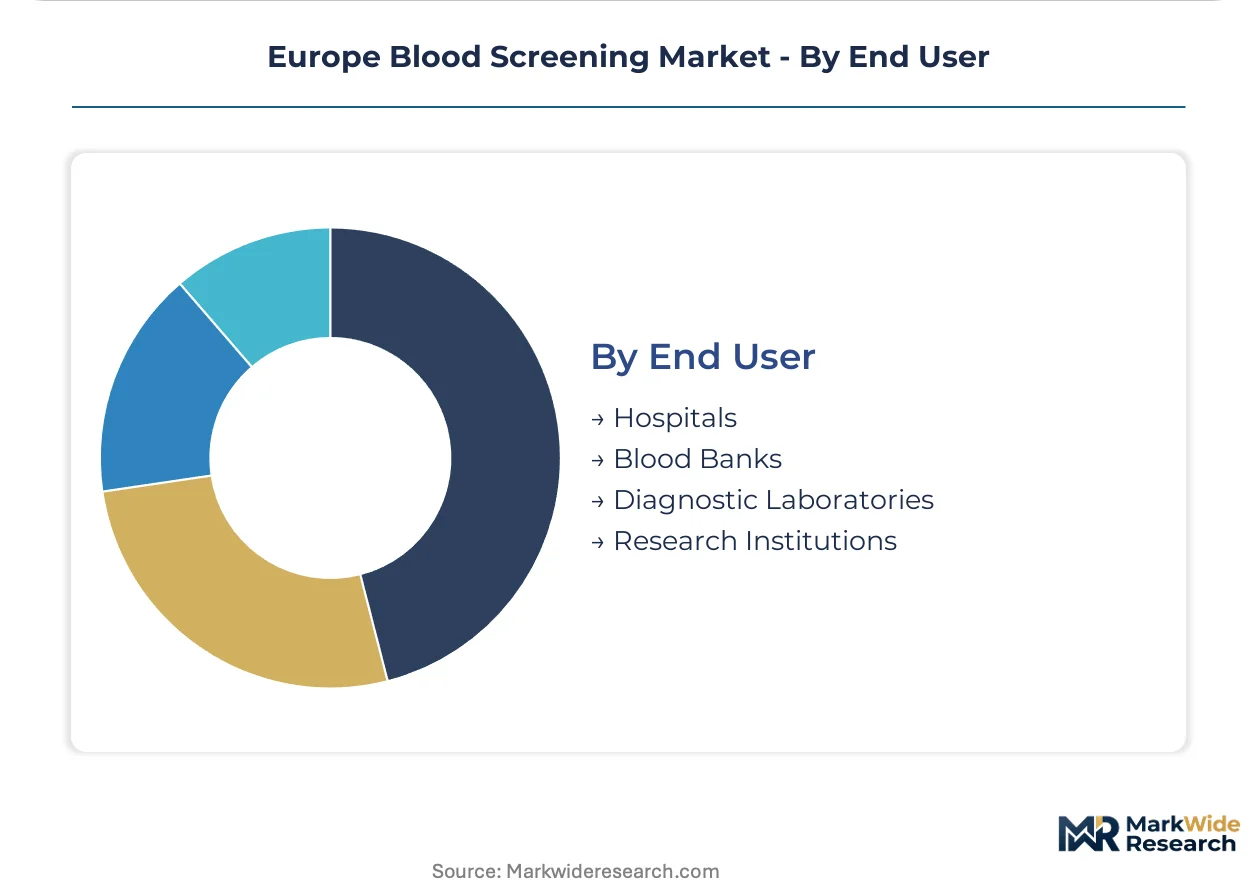
End User:
End user structure concentrates purchasing authority in centralized blood services, fragmenting only in markets with hospital-dominated transfusion medicine.
- Blood Banks:Centralized collection and processing facilities with high-throughput screening mandates. Germany's unified blood service structure enables volume procurement negotiations directly with manufacturers.
- Hospitals:Transfusion services and clinical laboratories with mixed serological and molecular capabilities. Spanish and Italian hospital networks fragment purchasing across regional health authorities.
- Diagnostic Laboratories:Independent and hospital-affiliated reference facilities offering specialized confirmatory testing. Commercial laboratories in the UK and France compete on turnaround time and extended test menus.
- Research Institutions:Academic medical centers and transfusion medicine research units developing novel screening assays. Swiss and Dutch universities concentrate EU-funded pathogen discovery programs.
Blood banks command the dominant share of instrument installations; diagnostic laboratories are scaling fastest with outsourced screening contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern Germany's enzyme and primer manufacturing belt anchors European nucleic acid testing supply chains, concentrating specialized reagent production in Baden-Württemberg and Bavaria that feeds screening networks across the continent.
Germany
Centralized blood service networks in Frankfurt and Munich drive volume procurement of automated high-throughput platforms. The EU IVDR mandates accelerated revalidation timelines for legacy assays. Mannheim and Heidelberg host specialized diagnostic clusters where manufacturers coordinate directly with the Paul-Ehrlich-Institut on compliance pathways.
France
Hospital laboratory networks in Paris and Lyon retain substantial enzyme immunoassay installed bases for routine blood typing. ANSM enforces strengthened post-market surveillance obligations that compress replacement cycles. The Île-de-France region concentrates reference laboratory capacity for confirmatory western blot testing.
United Kingdom
Commercial diagnostic laboratories in London and Manchester compete on turnaround time for outsourced screening contracts. The Medicines and Healthcare products Regulatory Agency aligns with EMA guidance on novel assay authorizations. Cambridge anchors academic medical center pilot programs for next-generation sequencing integration.
Spain
Regional health authorities in Madrid and Barcelona fragment purchasing authority across hospital transfusion services. The Spanish Agency for Medicines and Health Products enforces IVDR documentation requirements that delay mid-tier manufacturer entries. Catalonia's diagnostic cluster specializes in rapid test production for emergency department deployment.
Netherlands
Benelux blood services standardize procurement on multiplex PCR platforms for simultaneous pathogen detection. The Dutch Healthcare Authority coordinates with EMA on centralized marketing authorization pathways. Rotterdam and Utrecht host quality control panel manufacturing that blood banks require for regulatory compliance.
Europe Blood Screening Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care and next-generation sequencing adjacencies. The vendor base concentrates among integrated instrument-reagent systems providers and specialized reagent manufacturers. Three archetypes dominate: multinational conglomerates with full workflow integration, regional specialists with captive reagent supply, and quality control vendors with independent validation tools. Competitive moves center on multi-year total-cost-of-ownership contracting and IVDR compliance acceleration partnerships.
Within the multinational tier, F. Hoffmann-La Roche Ltd. and Abbott Laboratories occupy positions defined by automated platform dominance in hospital laboratory workflows. Grifols exemplifies the specialized reagent archetype, anchoring supply security for European transfusion centers through plasma-derived expertise. Bio-Rad Laboratories, Inc. represents the quality control segment, sitting within regulatory compliance tooling that blood banks require for IVDR-mandated assay validation.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Grifols |
| Danaher Corporation |
| Abbott Laboratories |
| Bio-Rad Laboratories, Inc. |
| Thermo Fisher Scientific Inc. |
| Becton, Dickinson and Company |
| Siemens AG |
| bioMérieux |
| Others |
Pricing and Supply Chain Analysis
Regulatory affairs specialists with IVDR documentation expertise concentrate in Mannheim and Heidelberg, where labor-cost differentials between German diagnostic clusters and Eastern European support centers drive pricing-tier spreads across nucleic acid testing platforms.
Pricing Analysis
Extended warranty and calibration service bundling separates premium-tier automated platforms from standard instruments sold with unbundled maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU IVDR and volume scale commitments from centralized blood services. Cost compression in economy-tier rapid tests is intensifying because Spanish and Italian hospital networks fragment purchasing authority. Regional blood banks in Eastern Europe exhibit highest price sensitivity; German unified blood services leverage consolidated procurement for least sensitivity.
Supply Chain Analysis
Instrument refurbishment and reagent cartridge remanufacturing flows remain underdeveloped, creating reverse-logistics gaps that concentrate waste disposal costs with end users. Specialized enzyme and primer manufacturing concentrates in Southern Germany and the Netherlands, drawing from rare-earth stabilized polymerases and fluorophore-labeled oligonucleotides. Single-source vulnerability pervades thermostable DNA polymerase supply. Distribution runs through manufacturer-direct contracts with centralized blood services and regional distributor networks serving hospital laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe blood screening market sits in a technology-transition phase as multiplex PCR and next-generation sequencing displace legacy enzyme immunoassay platforms under IVDR compliance pressure.
For Market Incumbents: Extend service-contract penetration to lock in multi-year revenue streams before IVDR revalidation cycles accelerate platform replacement. Deepen backward integration into specialized reagent manufacturing to secure supply chains against Southern Germany concentration risk. Consolidate position through quality control panel standardization that blood banks require for regulatory compliance.
For New Entrants and Emerging Players: Enter via point-of-care rapid test segments in Spanish and Italian emergency departments where procurement fragmentation creates accessible entry points. Target outsourced screening contracts from UK commercial diagnostic laboratories competing on turnaround time. Pursue EU Green Deal sustainability certification as differentiation lever for circular economy-certified reagent supply chains.
For Investors and Strategic Acquirers: The window for entry favors quality control and independent assay validation tool providers ahead of IVDR post-market surveillance obligation expansion. Long-term viability hinges on molecular diagnostics expertise concentration shifting from academic medical centers toward operational readiness at regional transfusion services. Monitor EMA guidance updates on emerging pathogen surveillance as inflection indicator for next-generation sequencing adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Acceleration Partnership | Paul-Ehrlich-Institut coordination compresses assay revalidation timelines for manufacturers. |
| Multi-Year Total-Cost-of-Ownership Contracting | German centralized blood services negotiate supply security spanning entire instrument lifecycles. |
| Next-Generation Sequencing Integration | Academic medical centers in Cambridge and Heidelberg pilot targeted amplicon sequencing workflows. |
| Eastern European Network Expansion | Poland and Romania consolidate fragmented regional blood services into national procurement structures. |
| EU Green Deal Procurement Certification | Sustainability requirements for single-use consumables differentiate circular economy-certified supply chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with blood bank procurement directors, hospital transfusion service managers, diagnostic manufacturer regulatory affairs leads, and EMA compliance officers. EMA centralized marketing authorization databases, EU IVDR technical documentation registries, Paul-Ehrlich-Institut guidance documents, and hospital laboratory procurement databases supplied validation layers. Bottom-up instrument installation tracking and top-down blood service expenditure analysis enabled cross-verification.
Granularity-level modeling addressed nucleic acid testing versus serological platform splits, centralized blood service versus hospital laboratory end-user distinctions, and transfusion versus infectious disease testing application segments across the projection horizon. CAGRs derived from instrument replacement cycle analysis, IVDR compliance deadline impact assessment, and emerging pathogen surveillance program expansion trajectories. Pricing trajectories incorporated multi-year contract renegotiation patterns and reagent supply concentration risk premiums.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IVDR transition timeline delays or novel pathogen emergence requiring assay redevelopment. Practitioners should monitor EMA guidance updates on multiplex PCR validation requirements and EU Green Deal procurement criteria implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Global Antinuclear Antibody Test Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Sperm Count Test Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Global Transplant Diagnostics Market