
 Super Generics Market | 2026-2036
Super Generics Market Size, Share, and Industry Trends Forecast 2026-2036
Super Generics Market Analytics
Project finance tied to dedicated manufacturing facilities is rewriting competitive entry barriers in complex generics. Teva Pharmaceutical Industries leverages its vertically integrated sterile injectable network to sustain supply security for hospital systems. Sun Pharmaceutical Industries anchors its position through concentrated R&D spending on dermatological and oncology super generics. Dr. Reddy's Laboratories differentiates via specialized API-to-finished-dosage capabilities in controlled-release platforms.
Super generics comprise pharmaceutically enhanced versions of off-patent drugs that incorporate modified release kinetics, improved bioavailability, alternative delivery routes, or complex formulation architectures requiring specialized manufacturing equipment. These products command premium positioning over conventional generics while avoiding the full development burden of novel molecular entities. The injectables segment leads margin pools due to sterility assurance requirements and limited qualified manufacturing capacity. Oncology within therapy areas represents the fastest-growing application as patent cliffs on biologic adjuvants create openings for complex generic substitutes. Oral administration dominates volume throughput across retail and institutional channels, though subcutaneous delivery formats are gaining share in outpatient cancer protocols.
FDA's ANDA suitability petitions and EMA's hybrid marketing authorization pathways shape product development priorities by defining the evidentiary threshold for therapeutic equivalence claims. The EPA and national environmental regulators impose solvent recovery and waste handling standards that filter out smaller API manufacturers lacking capital-intensive compliance infrastructure. WHO prequalification requirements for procurement eligibility in low-income countries add a parallel compliance layer for companies targeting institutional tenders. Stakeholders must monitor evolving bioequivalence study design guidance from FDA and EMA as these agencies refine acceptance criteria for complex absorption profiles.

Market Dynamics
Hospital systems are consolidating purchasing power around sterile injectable super generics, forcing manufacturers to dedicate capital to specialized aseptic filling lines or exit the segment entirely. This procurement concentration is compressing margins for undifferentiated players while rewarding vertically integrated suppliers with captive API supply.
Growth Catalysts
- FDA ANDA Suitability Petitions:The streamlined pathway for complex generics reduces evidentiary burdens for modified-release formulations, accelerating product development timelines for sponsors with established bioequivalence capabilities.
- Oncology Department Expansion:Hospital systems in the United States, Germany, and India are scaling inpatient chemotherapy units, creating dedicated demand for complex generic substitutes to patent-expired biologic adjuvants.
- Specialized Manufacturing Clusters:Concentrated investment in controlled-release platform technology in Hyderabad, Ahmedabad, and the New Jersey corridor is generating qualified capacity pools that attract institutional procurement contracts.
Market Restraints
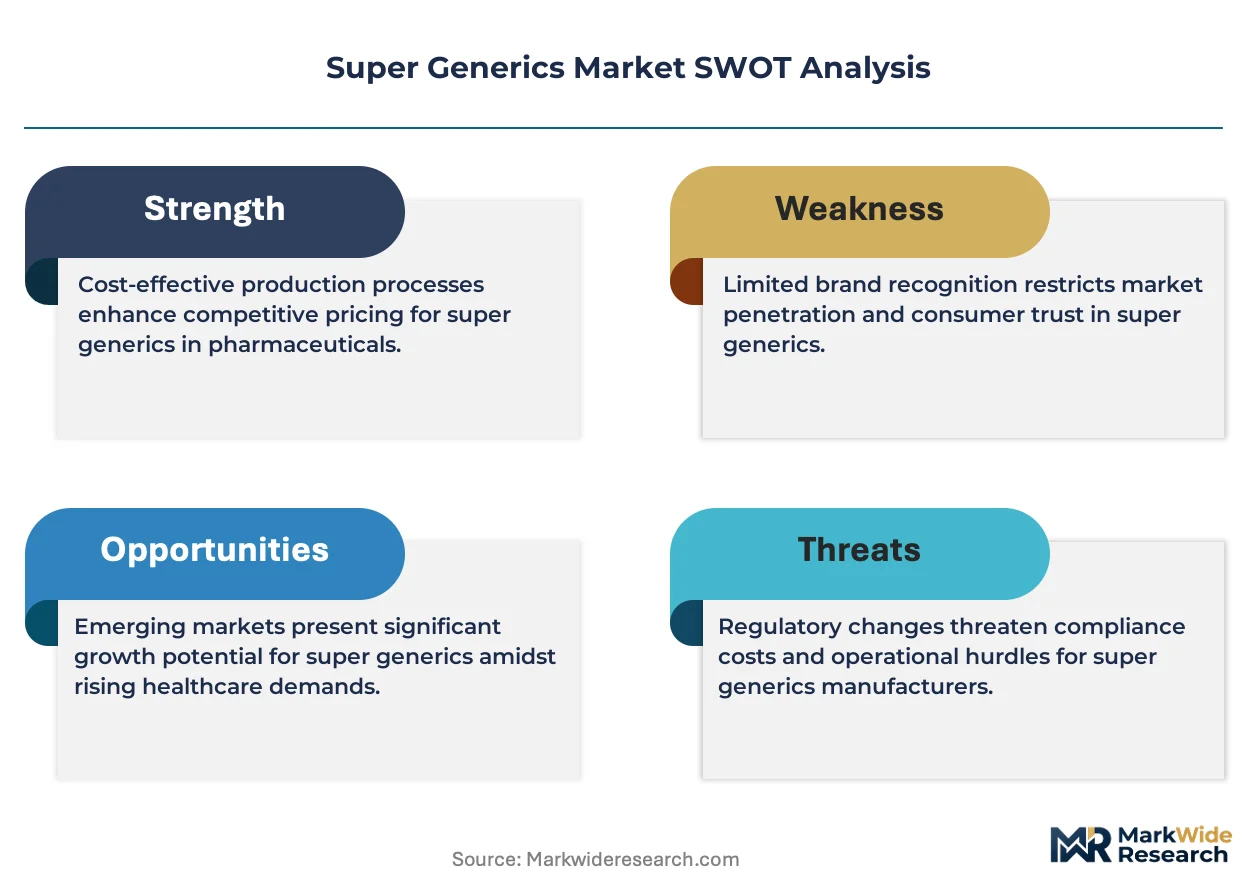
- Solvent Recovery Compliance:EPA and national environmental regulators impose capital-intensive waste handling standards that filter out smaller API manufacturers lacking recovery infrastructure.
- Sterile Injectable Capacity Concentration:Limited qualified aseptic filling facilities in North America and Western Europe create supply security vulnerabilities during equipment failure or contamination events.
- Complex Bioequivalence Requirements:Evolving FDA and EMA guidance on absorption profile acceptance criteria extends development timelines and increases clinical study costs for modified-release platforms.
Strategic Opportunities
- Subcutaneous Delivery Formats:Outpatient cancer protocols in the United States are shifting from intravenous to subcutaneous administration, opening formulation development opportunities for complex generic developers with depot injection expertise.
- WHO Prequalification Pathway:Institutional tenders in low-income countries require procurement eligibility certification, creating first-mover advantages for sponsors investing in parallel compliance infrastructure.
- Dermatological Super Generics:Modified-release topical formulations represent an underdeveloped category with limited qualified competitors and premium pricing potential in retail pharmacy channels.
Industry Challenges
- Formulation Scientist Scarcity:Controlled-release platform expertise concentrates among specialists with experience at established complex generic sponsors, constraining talent availability for emerging entrants.
- Aseptic Line Validation Timelines:FDA facility inspections and process performance qualification protocols extend commercialization schedules for sterile injectable capacity expansions.
- API Supply Security:Single-source dependencies for specialized controlled-release excipients create vulnerability to supplier manufacturing disruptions or quality holds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Generics Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Oral Dosage, Topicals, Biosimilars Therapy Area: Oncology, Cardiovascular, Neurology, Psychiatry Delivery Mode: IV Administration, Subcutaneous, Oral Administration, Transdermal End User: Hospitals, Retail Pharmacies, Online Pharmacies, Clinics |
| Companies Covered | Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Dr. Reddy’s Laboratories, Lupin Limited, Cipla Limited, Viatris, Aurobindo Pharma, Hikma Pharmaceuticals, Accord Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Generics Market Evolving Landscape
Formulation architecture is diverging from conventional immediate-release tablets toward multi-layer matrix systems and nanosuspension platforms that enable patent differentiation without novel molecular entity investment. This technological pivot is reshaping R&D resource allocation across the competitive set.
Hot-melt extrusion technology is migrating from oral solid dosage applications into implantable and long-acting injectable formats. Oncology-focused CDMOs in Germany and the United States are adopting twin-screw extrusion lines for amorphous solid dispersion manufacturing. This equipment transition is compressing development timelines for poorly soluble APIs while raising the capital threshold for competitive entry.
EMA hybrid marketing authorization guidelines are formalizing evidentiary standards for complex generic equivalence claims across modified-release and alternative route products. The framework requires more extensive clinical pharmacology data than conventional generics, elevating development costs. Sponsors targeting European hospital procurement are responding by front-loading pharmacokinetic study investment before formulation finalization.
Hospital pharmacy directors are consolidating formulary decisions through centralized therapeutic class reviews, displacing individual physician prescribing autonomy for oncology supportive care agents. This committee-based purchasing concentrates volume with suppliers demonstrating supply security and lot-to-lot consistency. The United States exhibits the most pronounced consolidation, with three national GPOs controlling the majority of institutional super generic procurement.
Super Generics Market Segmentation

Segmentation in super generics reveals how formulation complexity, sterility requirements, and procurement concentration create divergent margin profiles across product architectures. Cycle times vary dramatically: sterile injectables demand 18-24 month validation timelines while oral solids compress to 8-12 months, reshaping capital allocation priorities for sponsors.
Product Type:
Injectables turn inventory slowest due to aseptic line validation and sterility assurance protocols, while oral solids rotate fastest through commercial channels. Topicals occupy intermediate cycle positions driven by seasonal demand patterns and dermatology prescribing cycles.
- Injectables:Sterile formulations requiring specialized aseptic filling infrastructure and endotoxin testing protocols. Hospital systems in the United States consolidate procurement around qualified suppliers with captive API supply, compressing margins for undifferentiated entrants.
- Oral Dosage:Modified-release tablets and capsules utilizing multi-layer matrix or osmotic pump technologies. Retail pharmacy channels in Germany and India absorb volume throughput, though subcutaneous alternatives are displacing share in outpatient oncology protocols.
- Topicals:Transdermal patches and semisolid formulations with localized pharmacokinetic profiles. CDMOs in Hyderabad specialize in adhesive matrix manufacturing for pain management applications.
- Biosimilars:Complex biologic substitutes requiring immunogenicity assessment and extensive analytical comparability. EMA hybrid pathway guidelines extend development timelines relative to conventional generic ANDAs.
Oral dosage anchors the volume base while injectables gain share at the steepest rate as hospital formulary consolidation favors suppliers with sterile manufacturing depth.
Therapy Area:
Cost tiers stratify sharply: oncology commands premium positioning due to biologic adjuvant substitution opportunities, while cardiovascular operates at compressed margins with mature prescribing patterns.
- Oncology:Complex generic substitutes for patent-expired chemotherapeutic and supportive care agents. Inpatient chemotherapy unit expansion across hospital systems in India and the United States concentrates demand for sterile injectable alternatives.
- Cardiovascular:Modified-release antihypertensive and anticoagulant formulations with established bioequivalence pathways. Retail pharmacy volume in Germany sustains throughput for controlled-release platform manufacturers.
- Neurology:Long-acting injectable antipsychotics and extended-release formulations for chronic disease management. Depot injection expertise differentiates sponsors targeting outpatient psychiatric protocols.
- Psychiatry:Controlled-release formulations addressing adherence challenges in chronic mental health conditions. FDA ANDA suitability petitions streamline entry for modified-release versions of immediate-reference products.
Cardiovascular sustains the broadest volume footprint while oncology climbs the fastest as patent cliffs on biologic adjuvants create substitution openings.
Delivery Mode:
Application context determines equipment requirements: IV administration demands centralized compounding infrastructure while subcutaneous formats enable decentralized outpatient administration.
- IV Administration:Intravenous infusion requiring hospital-based administration and specialized pharmacy compounding. Aseptic filling capacity concentration in North America creates supply security vulnerabilities during contamination events.
- Subcutaneous:Depot injections and prefilled syringes enabling self-administration in outpatient settings. Oncology protocols in the United States are shifting from intravenous to subcutaneous delivery, opening formulation development opportunities.
- Oral Administration:Conventional and modified-release tablets and capsules for self-administered therapy. Volume throughput dominates retail and institutional channels across all therapy areas.
- Transdermal:Patch-based delivery with sustained release kinetics and reduced dosing frequency. Limited qualified competitors in adhesive matrix manufacturing preserve premium positioning.
Oral administration maintains volume dominance while subcutaneous delivery expands most quickly as outpatient cancer protocols favor patient-administered alternatives.
End User:
Customer procurement concentration varies: hospital GPOs aggregate purchasing power around sterile injectables while retail pharmacies fragment across multiple generic suppliers.
- Hospitals:Institutional procurement through centralized therapeutic class reviews and national GPO contracts. Three national GPOs in the United States control the majority of super generic procurement for inpatient settings.
- Retail Pharmacies:Dispensing channels for oral solids and topicals with formulary decisions influenced by payer reimbursement tiers. Germany's pharmacy network sustains volume for dermatological super generics.
- Online Pharmacies:Direct-to-patient dispensing platforms expanding share in chronic disease maintenance therapies. WHO prequalification requirements filter eligible suppliers for cross-border procurement.
- Clinics:Outpatient facilities administering injectable therapies and prescribing chronic disease formulations. Subcutaneous delivery adoption concentrates procurement with depot injection specialists.
Hospitals anchor institutional procurement volume while online pharmacies gain share at the steepest rate as direct-to-patient channels expand chronic disease medication access.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in super generics tilt toward net manufacturing outflows from India and Germany, while the United States absorbs the largest import volume of sterile injectable formulations. Trade balances concentrate around specialized controlled-release API precursors and finished dosage forms.
United States
Hospital GPO consolidation drives procurement concentration for oncology injectables, with three national purchasing organizations controlling institutional formulary access. FDA ANDA suitability petitions streamline pathway entry for modified-release developers. The New Jersey corridor anchors sterile manufacturing capacity, with specialized aseptic filling lines serving hospital system contracts.
Germany
EMA hybrid marketing authorization guidelines shape development investment for European hospital tenders, elevating pharmacokinetic study requirements. CDSCO-equivalent national standards filter procurement eligibility for complex generic entrants. The Rhine-Ruhr and Bavarian pharmaceutical clusters concentrate twin-screw extrusion capacity for amorphous solid dispersion manufacturing.
India
Hyderabad and Ahmedabad manufacturing clusters generate qualified controlled-release platform capacity that attracts institutional export contracts. CDSCO facility inspections and WHO prequalification requirements govern procurement eligibility for low-income country tenders. Domestic oncology department expansion concentrates demand for complex generic substitutes to patent-expired biologics.
United Kingdom
Post-Brexit regulatory divergence from EMA frameworks creates parallel compliance pathways for hybrid marketing authorizations. NHS procurement consolidation favors suppliers with demonstrated supply security for sterile injectable formularies. The Southeast England corridor maintains formulation development capabilities for modified-release platform technologies.
Japan
PMDA bioequivalence study requirements for complex absorption profiles extend development timelines for modified-release entrants. Domestic hospital pharmacy consolidation concentrates purchasing power around qualified sterile injectable suppliers. The Kanto region sustains specialized manufacturing infrastructure for controlled-release oral solid dosage forms.
Super Generics Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive API supply and specialized aseptic filling infrastructure. Tiered competitive positioning separates global diversified pharmaceutical conglomerates from mid-cap specialists concentrated in dermatological and oncology platforms. Two dominant competitive moves define current dynamics: backward integration into controlled-release excipient supply and strategic partnerships with hospital GPOs for formulary security.
Within the diversified pharmaceutical tier, Teva Pharmaceutical Industries and Sun Pharmaceutical Industries occupy positions anchored by sterile injectable network depth and concentrated R&D allocation respectively. Dr. Reddy's Laboratories exemplifies the API-to-finished-dosage specialist archetype, representing capabilities in controlled-release platform integration. These three entities collectively illustrate how manufacturing depth and therapeutic focus differentiate competitive positioning in procurement-concentrated channels.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Lupin Limited |
| Cipla Limited |
| Viatris |
| Aurobindo Pharma |
| Hikma Pharmaceuticals |
| Accord Healthcare |
| Others |
Value Network & Pricing Analysis
Undercapacity in North American aseptic filling facilities is driving procurement concentration among hospital GPOs and amplifying pricing power for qualified sterile injectable suppliers with captive API production.
Pricing Analysis
Hospital GPO buyers anchor contract-based long-term offtake pricing across sterile injectable formularies. Three-tier pricing structure across premium, standard, and economy levels segments by sterility assurance grade and FDA establishment inspection history. Cost compression in the oral solids tier is intensifying because of retail pharmacy formulary commoditization. Retail pharmacy chains exhibit highest price sensitivity; hospital systems with supply security mandates show lowest.
Supply Chain Analysis
Specialized CDMOs in India, Germany, and the United States hold concentrated capacity for controlled-release platform manufacturing. API supply draws from Indian and Chinese chemical synthesis clusters, while specialized excipients for modified-release matrices rest on European and Japanese suppliers. Single-source vulnerability for controlled-release polymers creates supply security exposure during quality holds. Distribution runs through hospital GPO consolidated procurement and retail pharmacy wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Super generics function as a service-attach opportunity where formulation development partnerships and bioequivalence consulting services expand faster than commodity finished dosage margins.
For Market Incumbents: Build regulatory filing moats through preemptive FDA ANDA suitability petition submissions for modified-release platforms. Deepen backward integration into controlled-release excipient supply to neutralize single-source API vulnerabilities. Consolidate sterile filling capacity in the New Jersey corridor to capture hospital GPO volume concentration. For New Entrants and Emerging Players: Geographic underpenetration in subcutaneous depot injection formats for outpatient oncology protocols offers accessible entry. Dermatological super generics present white-space with limited qualified competitors and premium retail pharmacy positioning. Pursue WHO prequalification pathway to unlock institutional tenders in low-income country procurement. For Investors and Strategic Acquirers: Capital is best deployed toward API-to-finished-dosage specialists with controlled-release platform integration capabilities. Long-term viability centers on manufacturing depth rather than pure-play marketing assets. Watch FDA facility inspection backlog clearance as inflection signal for capacity-constrained sterile injectable supply.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA ANDA suitability petitions compress development timelines for modified-release sponsors with bioequivalence capabilities. |
| Backward Integration | Captive controlled-release excipient production neutralizes supplier quality-hold vulnerabilities in sterile injectable supply. |
| Hospital System Partnership | GPO formulary security contracts lock in volume concentration for qualified aseptic filling capacity holders. |
| Manufacturing Scale-Up | Twin-screw extrusion line investment in Hyderabad and Bavarian clusters attracts amorphous solid dispersion contracts. |
| Geographic Expansion | WHO prequalification investment opens procurement eligibility for institutional tenders across low-income country hospital systems. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up volume modeling triangulated with top-down market sizing across dosage form, therapy area, administration route, and regional regulatory cluster segments.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapy area, delivery mode, and end-user procurement channel. CAGRs derived from regression analysis of historical approval velocity and capacity expansion patterns, incorporating bioequivalence study cost inflation and aseptic line validation timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated injectable specialists or unexpected FDA facility inspection acceleration would shift outcomes. Quarterly review of ANDA approval velocity, hospital GPO contract awards, and sterile injectable capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generics and Biosimilars
Europe Specialty Generics Market
Generics and Biosimilars
Europe Branded Generics Market
Generics and Biosimilars
West Africa Generic Drug Market
Generics and Biosimilars
US Specialty Injectable Generics Market
Generics and Biosimilars
Adalimumab Market
Generics and Biosimilars
Latin America Generic Drug Market
Generics and Biosimilars
Global Adalimumab Drugs Market
Generics and Biosimilars
GCC Generic Drug Market