
 Home Care Testing Market | 2026-2036
Home Care Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Home Care Testing Market Analytics
Diagnostic reagent manufacturing in Germany is rebalancing toward consumer-grade output as European healthcare budgets shift preventive screening into households. Abbott leverages integrated glucose-sensor supply chains to sustain cost leadership in diabetes strips across North American retail pharmacies. F. Hoffmann-La Roche Ltd. anchors high-margin cholesterol testing through professional-grade accuracy packaged for home use. Siemens Healthcare GmbH competes on Bluetooth-connected platforms that stream biometric data directly to electronic health records.
Home care testing comprises self-administered diagnostic devices that measure physiological biomarkers through capillary blood, urine, or non-invasive sensors with clinical-grade precision, typically achieving ±15% coefficient of variation comparable to laboratory analyzers. These systems serve the primary purpose of enabling chronic disease surveillance and acute condition verification without clinical infrastructure. Glucose meters occupy the deepest installed base among product types, reflecting decades of diabetes self-management protocols and insurance-covered strip replenishment. Digital testing with Bluetooth connectivity commands the fastest expansion trajectory as mobile applications transform passive readings into longitudinal health datasets that insurers and providers increasingly require. Blood pressure monitors retain mature volume profiles in developed economies while pregnancy test kits generate concentrated margin pools through pharmacy impulse-placement and direct-to-consumer e-commerce channels.
FDA 510(k) clearances and CLIA-waived designations govern market entry for home-use diagnostics in the United States, while the EU Medical Device Regulation imposes post-market surveillance and clinical evidence requirements that lengthen approval timelines for European launches. HIPAA interoperability rules and FTC health-claim advertising standards further constrain how Bluetooth-enabled devices collect, transmit, and describe consumer data. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring as payors determine whether connected home testing warrants parity with in-clinic diagnostics.
Market Dynamics
Bluetooth-enabled diagnostic platforms are compressing the traditional separation between consumer wellness tracking and clinical-grade monitoring, forcing reimbursement frameworks to recalibrate what constitutes billable care.
Growth Catalysts
- Medicare Remote Patient Monitoring codes:CMS reimbursement for connected glucose and blood pressure devices pulls chronic disease management out of clinics into US households.
- Capillary blood sampling miniaturization:Micro-needle arrays and microliter volume requirements reduce user error rates and expand self-testing to pediatric and geriatric populations.
- India:PLI scheme incentives for domestic medical electronics manufacturing accelerate localized production of low-cost digital thermometers and pulse oximeters.
Market Restraints
- Sensor electrode palladium and gold inputs:Precious metal price volatility in electrochemical glucose strips squeezes gross margins for strip-dependent business models.
- EU MDR clinical evidence requirements:Post-market surveillance obligations and notified body capacity constraints extend European launch timelines by 18-24 months compared to FDA 510(k) pathways.
- Smartphone-dependent connectivity:Digital test kits requiring iOS/Android integration exclude populations with device incompatibility or limited data plans, capping addressable market penetration.
Strategic Opportunities
- Brazil ANVISA over-the-counter reclassification:Expanded self-test categories for cholesterol and HbA1c create pharmacy channel expansion in Latin America's largest healthcare market.
- Salivary cortisol and hormone panels:Non-invasive biomarker extraction opens chronic stress and fertility tracking applications beyond traditional blood-based diagnostics.
- Direct-to-consumer subscription models:Recurring replenishment of test strips and lancets through e-commerce platforms captures lifetime value and reduces pharmacy intermediary dependence.
Industry Challenges
- HIPAA interoperability rule implementation:Health data exchange standards require firmware updates and cloud architecture redesigns for legacy Bluetooth devices lacking API compatibility.
- CLIA-waived manufacturing scale-up:Quality control staffing and cleanroom capacity constraints bottleneck production ramps for high-volume waived test kit launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Care Testing Market |
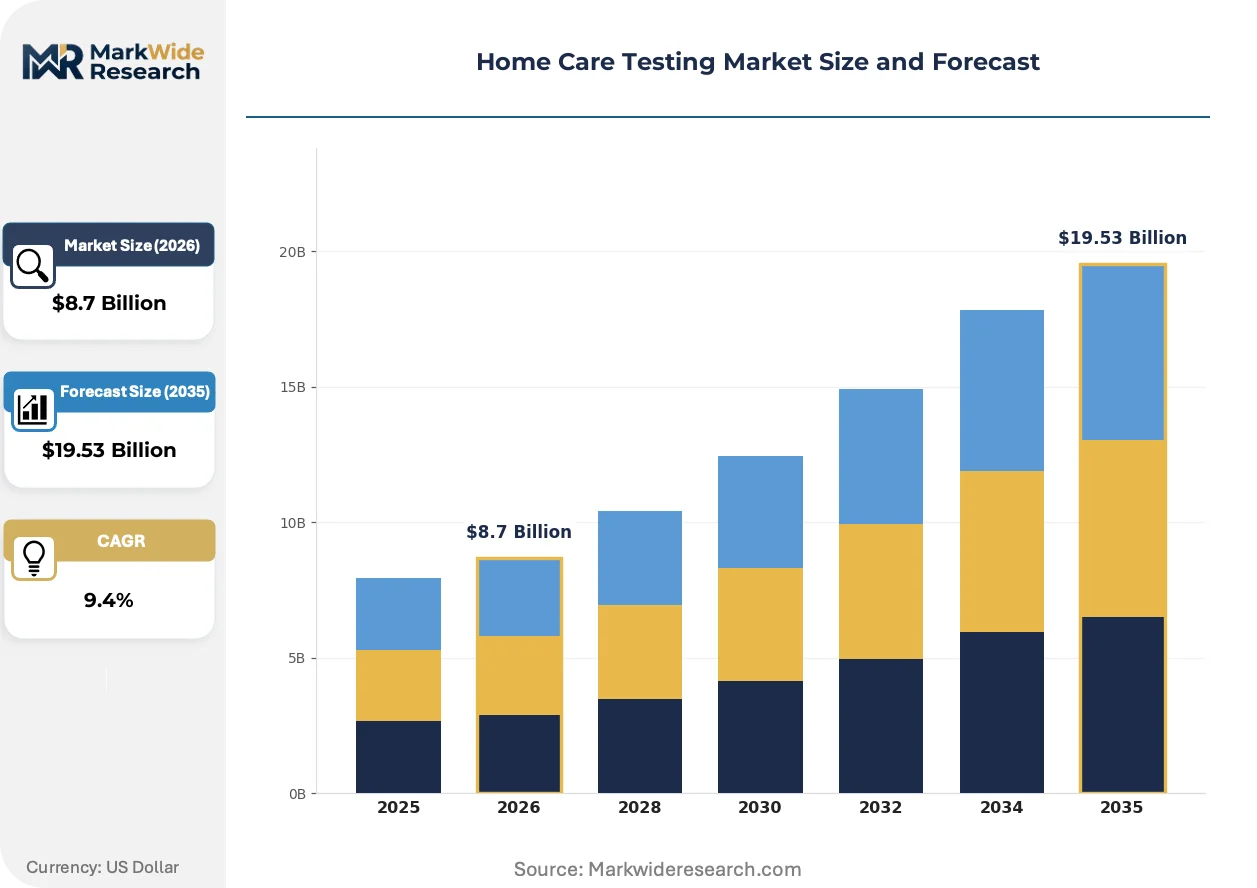
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Pregnancy Test Kits, Cholesterol Testing Kits, Blood Pressure Monitors Application: Diabetes Management, Cardiovascular Monitoring, Pregnancy Confirmation, Chronic Disease Management End User: Patients, Caregivers, Clinics, Home Health Agencies Technology: Digital Testing, Bluetooth Connectivity, Mobile Applications, Non-invasive Tests |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd., Quidel Corp., BD, Siemens Healthcare GmbH, ACON Laboratories, Inc., OraSure Technologies, Inc., Chembio Diagnostics, Inc., LifeScan IP Holdings, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Care Testing Market Evolving Landscape
Diagnostic hardware is shedding its standalone identity as software layers and data infrastructure become the primary value capture mechanism in home testing.
Microfluidic cartridge systems is modularizing point-of-care chemistry into interchangeable analyte panels. Diagnostic OEMs in Germany and Massachusetts are adopting open-architecture cartridge slots that accept third-party reagent inserts. This architecture is modularizing the traditional integrated device model and enabling platform economics previously reserved to laboratory analyzers.
EU MDR Article 10 post-market clinical follow-up requirements now mandate continuous safety and performance data collection for Class IIa and above home-use devices. Manufacturers must embed real-world evidence generation into product design or face certificate suspension. Connected glucose meters with automated data transmission to notified bodies are responding earliest, converting regulatory burden into competitive differentiation.
Hospital procurement departments are unbundling device purchases from consumable supply agreements that previously locked systems for 3-5 year terms. Pharmacy benefit managers and home health agencies now negotiate strip and reagent contracts separately from meter hardware. This disintermediation is most visible in United States Medicare Advantage plans, where competitive bidding for remote monitoring bundles favors interchangeable platform ecosystems over proprietary closed loops.
Home Care Testing Market Segmentation
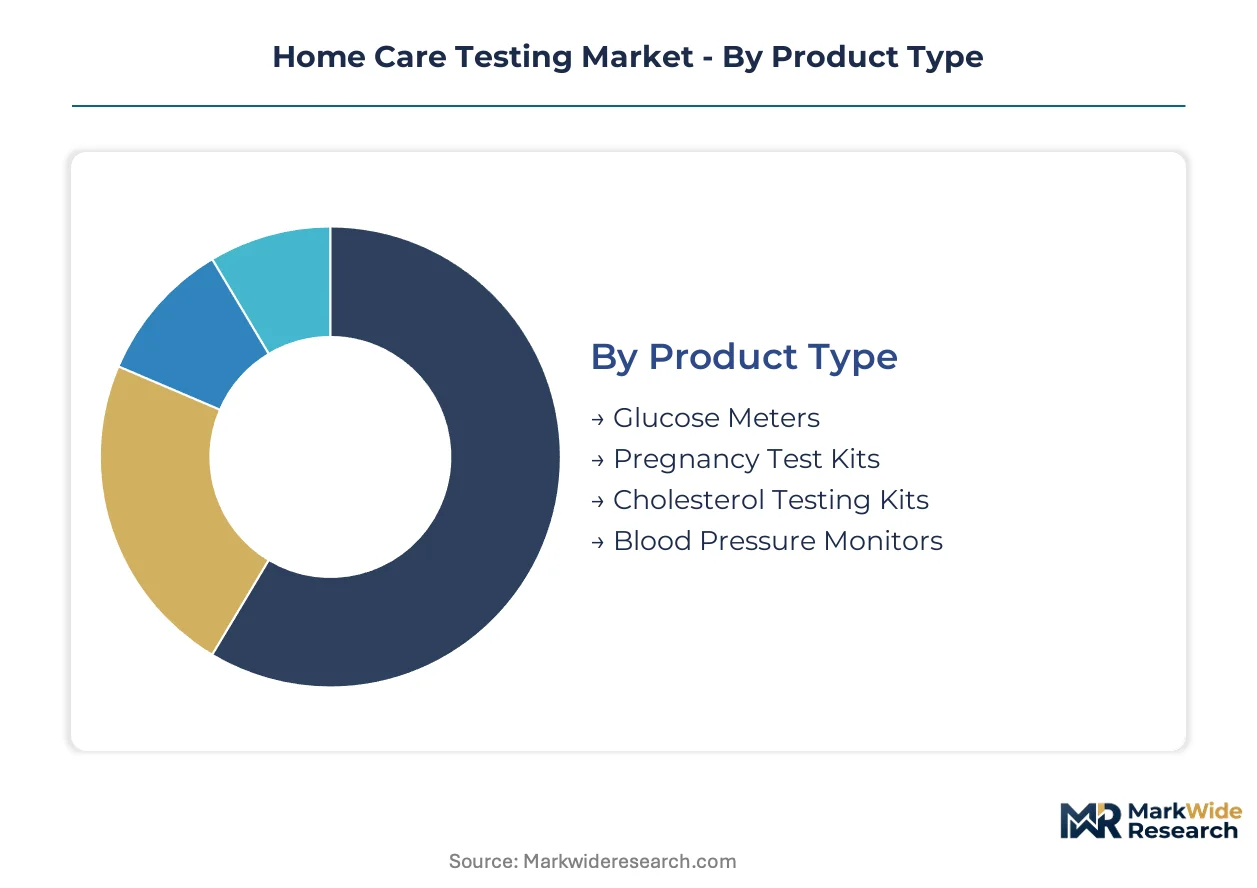
Home care testing markets fragment across four distinct dimensions that determine reimbursement pathways, regulatory classification, and commercial channel strategy. Each segmentation layer reveals different margin structures and competitive moats, from consumable-driven glucose economics to platform-based digital subscriptions.
Product Type:
Standalone diagnostic hardware dominates pharmacy shelf placement, while embedded sensor systems increasingly bundle into smartphone ecosystems and telehealth platforms.
- Glucose Meters:Electrochemical biosensors utilizing glucose oxidase chemistry on palladium-doped electrodes achieve ±15% coefficient of variation matching laboratory standards. United States Medicare Advantage plans drive volume through bundled remote monitoring contracts that subsidize meter hardware while profiting from recurring strip replenishment.
- Pregnancy Test Kits:Lateral flow immunoassay strips detecting hCG in urine samples at 20-25 mIU/mL sensitivity thresholds. Pharmacy impulse-placement and direct-to-consumer e-commerce channels generate concentrated margin pools through high turnover and minimal post-sale support requirements.
- Cholesterol Testing Kits:Enzymatic dry chemistry systems measuring total cholesterol, HDL, and calculated LDL from capillary blood samples.
- Blood Pressure Monitors:Oscillometric upper-arm and wrist-worn devices with automated inflation and Bluetooth data transmission.
Volume placements concentrate in glucose meters; the faster expansion belongs to Bluetooth-connected blood pressure monitors gaining remote patient monitoring reimbursement codes.
Application:
Cost tier stratification separates acute episodic testing from longitudinal disease surveillance, with the latter commanding premium pricing through data integration services.
- Diabetes Management:Continuous glucose monitoring integration and time-in-range analytics transform discrete fingerstick readings into actionable glycemic pattern data. Germany's DiGA fast-track approval pathway accelerates reimbursement for connected meters streaming data to electronic health records.
- Cardiovascular Monitoring:Ambulatory blood pressure tracking with automated morning-evening protocols detects masked hypertension and white-coat syndromes missed in clinical settings. United Kingdom NHS long-term plan incentives push hypertension screening into community pharmacies, expanding home monitor deployment.
- Pregnancy Confirmation:Early detection applications prioritize sensitivity and ease-of-use over connectivity features.
- Chronic Disease Management:Multi-parameter platforms combining glucose, ketone, and lipid panels for metabolic syndrome surveillance.
Revenue concentration sits with diabetes management; cardiovascular monitoring climbs fastest as hypertension prevalence rises among aging populations.
End User:
Customer type determines purchasing authority, with institutional procurement favoring platform interoperability while individual buyers prioritize simplicity and price.
- Patients:Direct consumers selecting devices based on insurance formulary coverage, smartphone compatibility, and pharmacy loyalty programs. India's PLI scheme for domestic medical electronics manufacturing reduces out-of-pocket costs for pulse oximeters and digital thermometers in tier-2 and tier-3 cities.
- Caregivers:Family members managing testing protocols for elderly or pediatric populations requiring assistance with capillary blood sampling technique.
- Clinics:Primary care practices dispensing CLIA-waived test kits for home monitoring between visits.
- Home Health Agencies:Skilled nursing providers integrating connected devices into remote patient monitoring bundles billed under CMS reimbursement codes.
Patient self-purchase generates the largest unit volumes; home health agencies deliver the steepest revenue-per-device through subscription monitoring contracts.
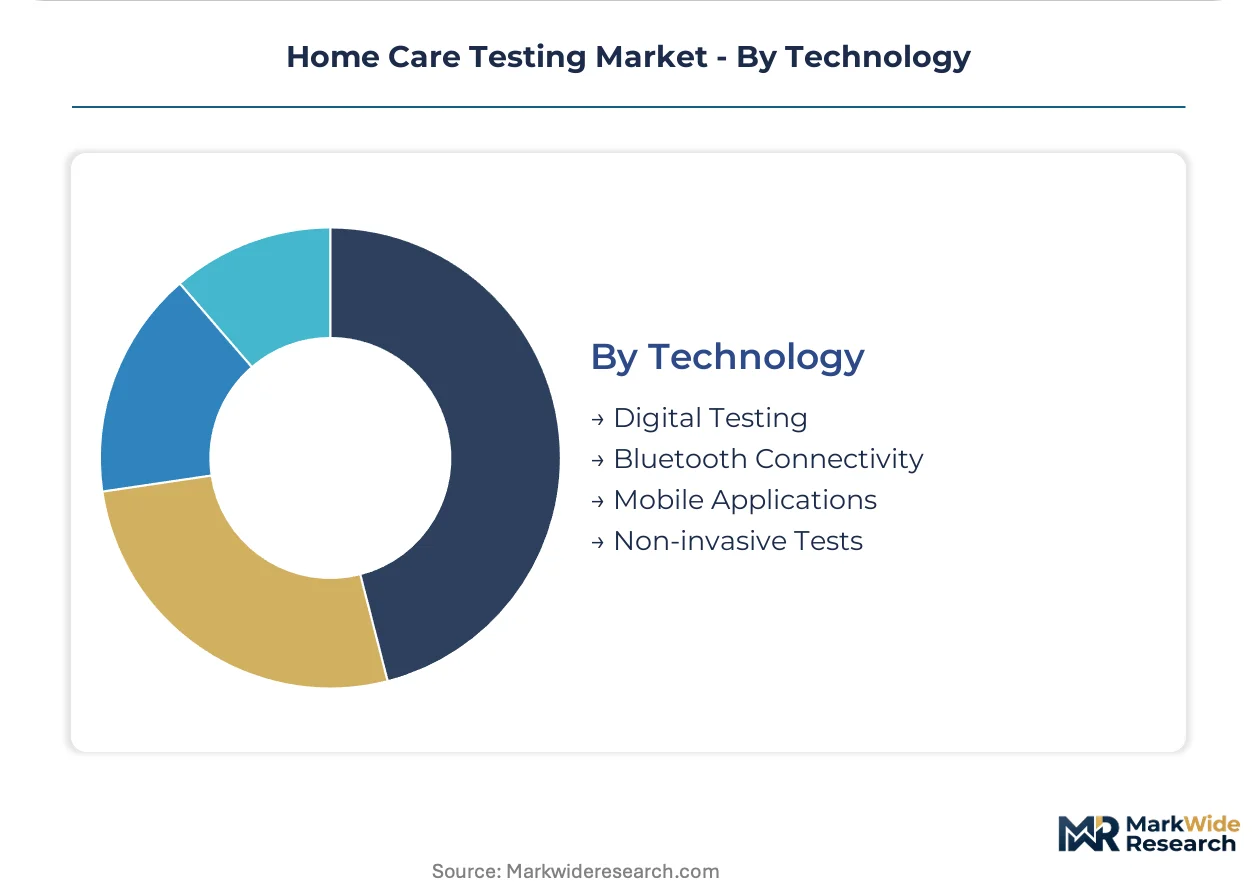
Technology:
Supply concentration in semiconductor and sensor manufacturing shapes which connectivity standards achieve scale economics first.
- Digital Testing:Microcontroller-based systems with LCD displays and onboard memory storing 100-500 historical readings. Brazil ANVISA over-the-counter reclassification for digital cholesterol and HbA1c meters expands pharmacy channel penetration in Latin America's largest healthcare market.
- Bluetooth Connectivity:Low-energy wireless protocols transmitting encrypted biometric data to paired smartphones and cloud platforms. EU MDR Article 10 post-market surveillance requirements favor connected devices with automated real-world evidence generation capabilities.
- Mobile Applications:iOS and Android software layers transforming raw sensor outputs into trend visualization, medication reminders, and provider-facing reports.
- Non-invasive Tests:Optical, electrical, and spectroscopic methods eliminating capillary blood sampling through interstitial fluid or breath analysis.
Digital testing retains the deepest installed base; non-invasive technologies gain share fastest as optical sensor miniaturization improves correlation with laboratory reference methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Palladium and gold electrode supply chains from Russian and South African mining operations concentrate sensor manufacturing in Germany and the United States, where electrochemical strip production anchors regional cost structures.
United States
Medicare Remote Patient Monitoring reimbursement codes pull chronic disease surveillance into households, with CMS expanding coverage for connected glucose and blood pressure devices. FDA 510(k) clearances and CLIA-waived designations compress approval timelines compared to European pathways. Minneapolis and San Diego host dense clusters of diagnostic OEMs manufacturing Bluetooth-enabled platforms for pharmacy retail distribution.
Germany
Diagnostic reagent manufacturing rebalances toward consumer-grade output as healthcare budgets shift preventive screening into households. EU MDR Article 10 post-market surveillance requirements favor connected devices with automated real-world evidence generation. Mannheim and Mannheim-Rhine-Neckar metropolitan region anchor high-margin cholesterol testing production for home-use applications.
India
PLI scheme incentives for domestic medical electronics manufacturing accelerate localized production of low-cost digital thermometers and pulse oximeters in tier-2 and tier-3 cities. CDSCO streamlined approval pathways for Class A and B home-use devices reduce time-to-market for local manufacturers. Bangalore and Hyderabad semiconductor clusters supply microcontroller components for glucose meter assembly.
Brazil
ANVISA over-the-counter reclassification for cholesterol and HbA1c meters expands pharmacy channel penetration in Latin America's largest healthcare market. Expanded self-test categories create new retail opportunities for digital diagnostic platforms. São Paulo state concentrates distribution infrastructure for imported and locally assembled testing devices.
Japan
PMDA streamlined approval for smartphone-connected home diagnostics accelerates digital platform launches for aging populations managing hypertension and diabetes. METI subsidies for preventive healthcare technology adoption support household monitoring device penetration. Kansai region Osaka-Kobe manufacturing belt produces precision electrochemical sensors for glucose monitoring strips.
Home Care Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-layer differentiation and direct-to-consumer subscription models. The vendor base stratifies across multinational conglomerates with integrated glucose-sensor supply chains, mid-scale diagnostic specialists, and digital health platforms bundling hardware with data services. Three archetypes dominate: consumable-dependent strip manufacturers, Bluetooth-connected platform builders, and non-invasive optical sensor developers. Competitive moves concentrate on M&A for cartridge technology access and strategic partnerships with pharmacy benefit managers for remote monitoring bundle contracts.
Within the integrated supply chain tier, Abbott and F. Hoffmann-La Roche Ltd. occupy positions exemplifying cost leadership through captive electrode manufacturing and professional-grade accuracy packaging for home use. Siemens Healthcare GmbH anchors the connected platform archetype with Bluetooth-enabled systems streaming biometric data to electronic health records. These three entities represent contrasting strategic postures: strip-dependent recurring revenue models, high-margin precision diagnostics, and interoperability-first platform architectures.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd. |
| Quidel Corp. |
| BD |
| Siemens Healthcare GmbH |
| ACON Laboratories, Inc. |
| OraSure Technologies, Inc. |
| Chembio Diagnostics, Inc. |
| LifeScan IP Holdings, LLC |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up diagnostic specialists have consolidated glucose strip manufacturing in the United States and Germany, tightening pricing discipline through captive electrode production while squeezing independent reagent suppliers on volume commitments. This ownership concentration links palladium cost hedging directly to meter hardware subsidies, with bundled remote monitoring contracts masking strip profitability through multi-year patient lock-in.
Pricing Analysis
Warranty and calibration service bundling separates premium Bluetooth-connected platforms from economy-tier standalone meters, with subscription-based data analytics commanding recurring fees absent from pharmacy impulse purchases. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, smartphone interoperability grade, and strip volume scale. Cost compression in economy glucose strips intensifies as Indian PLI-subsidized manufacturers undercut legacy suppliers on lancet and strip bundles. Home health agencies exhibit lowest price sensitivity due to CMS reimbursement coverage, while uninsured direct consumers in tier-2 Indian cities drive hardest bargain negotiations.
Supply Chain Analysis
Cleanroom technician shortages in Mannheim and Minneapolis constrain electrochemical sensor production ramps, forcing OEMs to automate glucose oxidase deposition lines or relocate assembly to Bangalore semiconductor clusters. Palladium and gold electrode fabrication concentrates in Germany, the United States, and Japan, with strip lamination and packaging drawing from Chinese and Mexican contract manufacturers. Single-source vulnerability in Russian and South African precious metal mining feeds raw material price volatility through glucose strip cost structures. Distribution runs through pharmacy retail chains and hospital procurement departments, with direct-to-consumer e-commerce gaining fastest share in pregnancy test and fertility tracker categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home care testing sits at a technology-transition inflection where Bluetooth-enabled platforms displace standalone digital meters, with software-layer monetization replacing consumable-dependent revenue models as the primary value capture mechanism.
For Market Incumbents: Cement platform stickiness through backward integration into cloud data infrastructure and exclusive pharmacy benefit manager contracts for remote monitoring bundles. Threat from salivary cortisol and optical non-invasive alternatives demands R&D investment in multi-analyte cartridge compatibility. Capacity addition in Indian semiconductor corridors secures microcontroller supply for cost-competitive meter production.
For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models for fertility and chronic stress hormone panels, bypassing pharmacy intermediary margins entirely. Brazil ANVISA over-the-counter reclassification for cholesterol and HbA1c represents most penetrable regulatory opening in Latin America. Go-to-market angle: partner with telehealth platforms for physician-ordered home testing kits with automated results integration.
For Investors and Strategic Acquirers: FDA 510(k) clearance for smartphone-connected glucose meters with automated EHR transmission is the leading indicator that reimbursement parity between home and clinic diagnostics has arrived. Five-to-ten year viability favors acquisition targets with cartridge-based open architecture and real-world evidence generation capabilities embedded in firmware. Signal to watch: CMS expansion of remote therapeutic monitoring codes beyond diabetes and hypertension into renal and respiratory disease surveillance.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates time-to-market for Bluetooth-enabled diagnostic platforms against EU MDR timelines. |
| Hospital System Partnership | Locks in remote patient monitoring bundle contracts with Medicare Advantage plans and GPOs. |
| Software Companion Development | Transforms passive glucose readings into longitudinal datasets required by insurers and providers. |
| CE Marking Pathway | Opens European pharmacy channels under MDR Article 10 post-market surveillance requirements. |
| Reimbursement Strategy | Secures CMS remote therapeutic monitoring codes for connected blood pressure and glucose devices. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement filings underwrites the qualitative findings in this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at diagnostic OEMs combined with secondary validation from FDA 510(k) filings, EU MDR notified body registrations, and CDSCO approval records. Bottom-up strip volume modeling and top-down platform revenue estimates triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from pricing trajectory across product type, application, end user, and technology segmentation dimensions. CAGRs derive from installed base replacement cycles, reimbursement code expansion schedules, and smartphone penetration curves. Forecast inputs include palladium price volatility indices, notified body capacity constraints, and PLI scheme subsidy disbursement timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR certificate suspension events or CMS reimbursement code retraction. Forecasts reflect assumptions on regulatory pathway efficiency, precious metal cost stabilization, and Bluetooth interoperability standard adoption. Material deviation in FDA 510(k) backlog duration or ANVISA reclassification timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Platelet Function Testing Market
Testing Services
Global Endotoxin and Pyrogen Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Blood Sugar Tester Market
Testing Services
Solid Tumor Testing Market
Testing Services
Urodynamic Testing Market
Testing Services
Zika Virus Testing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Nicotine Testing Market
Testing Services
Urine Sediment Testing Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Tuberculosis Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Sterilization Monitoring Technologies Market