
 Haptoglobin Reagent Market | 2026-2036
Haptoglobin Reagent Market Size, Share, and Industry Trends Forecast 2026-2036
Haptoglobin Reagent Market Foresight
North America is rewriting competitive dynamics in haptoglobin reagent supply as domestic manufacturing capacity expands to reduce import dependency. Sekisui Diagnostics leverages its vertically integrated polymer chemistry capabilities to control raw material quality for assay substrates. Randox Laboratories anchors its position through proprietary biochip arrays that multiplex haptoglobin with acute-phase protein panels. Beckman Coulter Inc. competes on instrument-reagent bundling strength across high-throughput clinical chemistry platforms.
Haptoglobin reagents comprise purified antibodies, calibrators, and substrate formulations designed to quantify haptoglobin protein concentration in serum or plasma through immunochemical reaction, typically achieving analytical sensitivity below 0.1 g/L for clinical diagnostic utility. Immunoassay kits command the largest revenue share due to their integration into automated analyzers, while lateral flow assay formats represent the fastest-expanding technology segment for point-of-care hemolysis screening. Blood banks generate concentrated demand for control materials that validate transfusion-monitoring protocols, and ELISA-based diagnostic reagents sustain dominant placement in research institutions conducting inflammation biomarker studies.
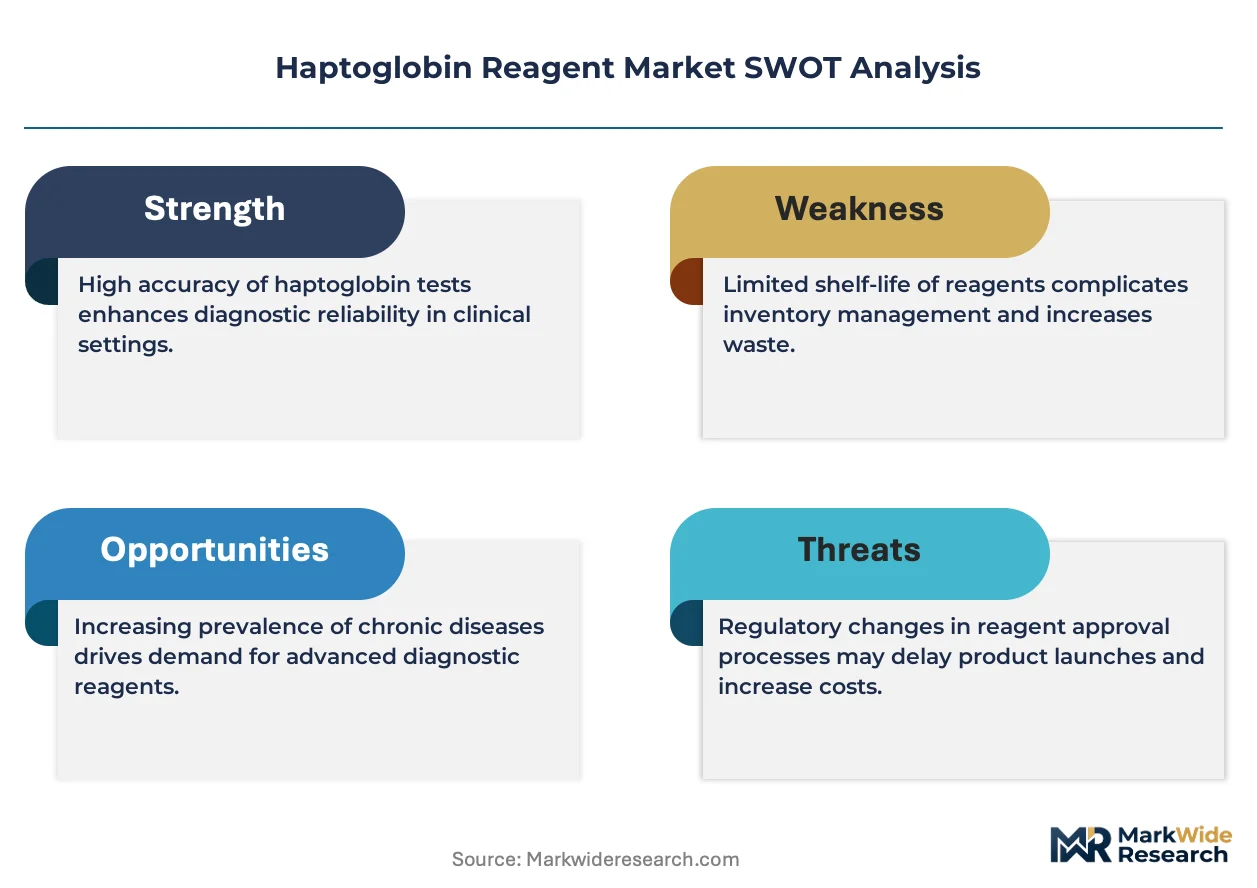
FDA oversight of Class II in vitro diagnostics and IVDR conformity requirements in Europe are elevating analytical validation burdens and post-market surveillance obligations for haptoglobin assay manufacturers. Clinical laboratories must now document traceability to certified reference materials under ISO 17511 standards, tightening supplier qualification criteria. Stakeholders should monitor evolving IVDR notified body capacity constraints and CMS reimbursement determinations for novel hemolysis markers as decisive variables for regional market access and portfolio prioritization.
Market Dynamics
IVDR conformity assessments and ISO 17511 traceability mandates are compressing supplier qualification timelines while fragmenting the notified body landscape across European markets.
Growth Catalysts
- Hemolytic anemia screening protocols:Blood banks in Germany and Japan are expanding haptoglobin panels for transfusion safety validation. Automated chemistry analyzers integrate these assays into routine coagulation workflows.
- REACH-compliant substrate chemistry:European reagent manufacturers are reformulating assay components to eliminate hazardous classification triggers. This accelerates cross-border distribution approvals.
- Cardiovascular risk stratification:Clinical laboratories in the United States are adding haptoglobin to acute-phase protein panels for diabetic patient monitoring. Payers are recognizing the biomarker's prognostic utility.
Market Restraints
- Purified antibody input costs:Recombinant monoclonal antibody production requires mammalian cell culture facilities with multi-year capacity constraints. Price volatility in fetal bovine serum feeds into calibrator manufacturing costs.
- Notified body bottleneck:European IVDR technical documentation reviews now exceed 18 months for Class B in vitro diagnostics. Manufacturers face frozen product registrations and revenue recognition delays.
- Lateral flow substitution threat:Point-of-care hemolysis screening devices are capturing emergency department volumes previously served by laboratory immunoassays. These devices trade analytical sensitivity for turnaround speed.
Strategic Opportunities
- India's diagnostic infrastructure expansion:The country's PLI scheme for medical device manufacturing is attracting contract reagent producers. Tier-2 cities present untapped demand for affordable ELISA kits.
- Multiplex biochip convergence:Acute-phase protein panels combining haptoglobin with CRP and serum amyloid A are displacing single-analyte workflows. This technology captures premium pricing in reference laboratories.
- CMS reimbursement tailwinds:Novel hemolysis marker coding proposals under review could expand Medicare coverage for haptoglobin testing. Commercial payers typically follow CMS determinations within 24 months.
Industry Challenges
- ISO 17511 metrology expertise gap:Clinical laboratories lack personnel trained in certified reference material traceability documentation. Manufacturers must provide technical support that strains field application scientist capacity.
- Legacy analyzer integration friction:Reagent kit modifications to accommodate discontinued instrument platforms require software validation cycles. Hospital capital budgeting constraints delay analyzer fleet refresh programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Haptoglobin Reagent Market |
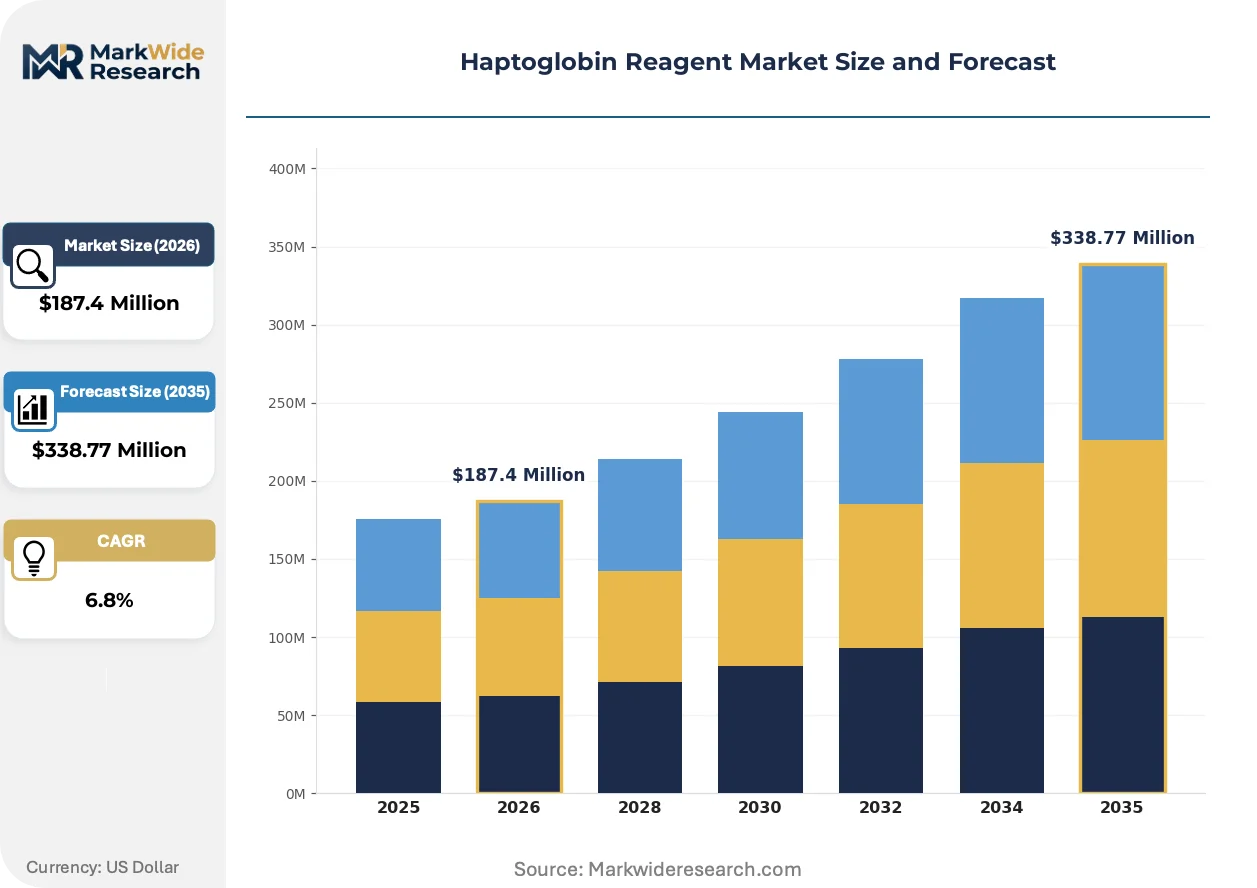
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay Kits, Diagnostic Reagents, Control Materials, Blood Typing Reagents End User: Clinical Laboratories, Research Institutions, Hospitals, Blood Banks Application: Disease Diagnosis, Biomedical Research, Blood Chemistry Analysis, Genetic Testing Technology: ELISA, Western Blot, Mass Spectrometry, Lateral Flow Assay |
| Companies Covered | Sekisui Diagnostics, Randox Laboratories, Beckman Coulter Inc., Abbott Laboratories, IBL International, Analytik Jena AG, SDIX, LLC, Kamiya Biomedical Company, BioGenex Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Haptoglobin Reagent Market Shifts & Advancements
Automated platform miniaturization and regulatory data science investments are compressing assay development cycles while elevating analytical performance benchmarks for clinical chemistry reagents.
Magnetic bead-based solid-phase extraction is collapsing sample preparation bottlenecks in high-throughput haptoglobin quantification. Reference laboratories in the United States are adopting this substrate technology to reduce manual pipetting errors and technician hands-on time. The resulting workflow compression enables same-day result reporting for hemolysis panels.
EMA's IVDR guidance on common specifications for IVD performance evaluation is forcing manufacturers to expand clinical evidence packages. European notified bodies are rejecting legacy CE-marked products lacking prospective analytical validation studies. Reagent suppliers are responding by establishing dedicated post-market surveillance teams and clinical affairs functions.
Blood bank purchasing cooperatives are consolidating procurement decisions across multi-hospital systems. These centralized contracts favor reagent vendors offering instrument-agnostic formulations with long shelf stability. The shift disadvantages single-platform suppliers and is most visible in German and Japanese transfusion service networks.
Haptoglobin Reagent Market Segmentation
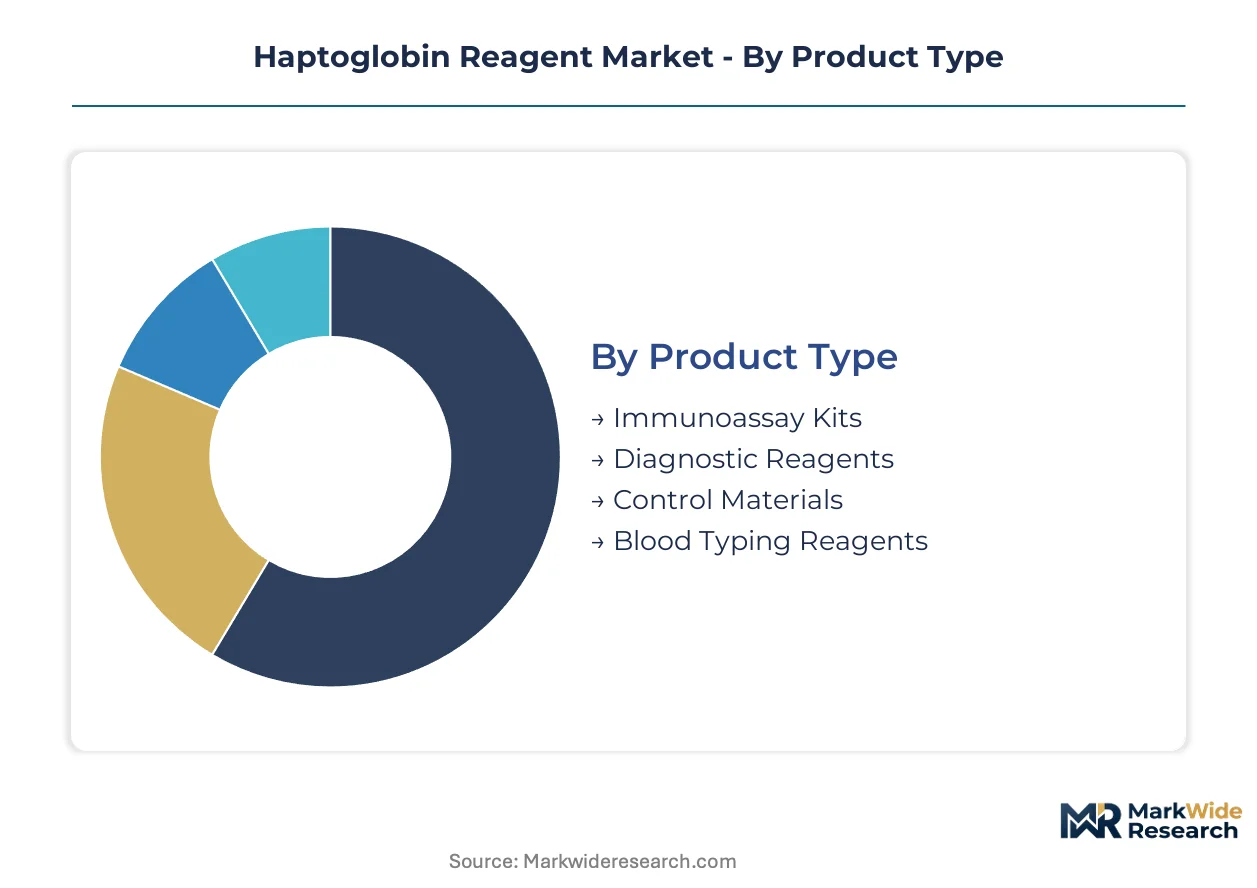
Haptoglobin reagent purchasing patterns diverge sharply across product formats and testing environments. Laboratory procurement teams prioritize automation compatibility and shelf stability, while research buyers emphasize lot-to-lot consistency and custom formulation flexibility.
Product Type:
After-sales service intensity peaks with immunoassay kits requiring analyzer calibration support and technical troubleshooting, while control materials demand minimal ongoing vendor interaction beyond certificate updates.
- Immunoassay Kits:Pre-configured antibody-calibrator sets designed for automated clinical chemistry platforms. German and Japanese hospital networks concentrate procurement for hemolytic anemia screening workflows integrated into coagulation panels. Manufacturers maintain field application scientists for instrument-specific troubleshooting.
- Diagnostic Reagents:Bulk antibody preparations and substrate formulations enabling laboratory-developed test protocols. Research institutions in the United States drive demand for customizable concentrations supporting inflammation biomarker studies. ISO 17511 traceability documentation requirements elevate supplier qualification burdens.
- Control Materials:Certified reference-grade haptoglobin preparations for assay validation and quality control. Blood bank cooperatives in Germany consolidate multi-hospital procurement around long-stability formulations.
- Blood Typing Reagents:Specialized formulations supporting transfusion-monitoring protocols and hemolysis detection in donor screening. Japanese transfusion services specify stringent endotoxin thresholds.
By volume, immunoassay kits lead. By growth pace, diagnostic reagents are expanding most quickly.
End User:
Cost tier stratification separates high-throughput automation buyers from price-sensitive research purchasers, with capital equipment ownership determining reagent contract structures.
- Clinical Laboratories:High-throughput diagnostic facilities processing thousands of samples daily. United States reference laboratories anchor demand for multiplex acute-phase protein panels combining haptoglobin with CRP. CMS reimbursement coding for hemolysis markers shapes test menu expansion decisions.
- Research Institutions:Academic and biotechnology laboratories conducting inflammation and cardiovascular biomarker studies. ELISA-based workflows dominate procurement for protocol flexibility and publication-grade sensitivity requirements.
- Hospitals:Inpatient and emergency departments requiring rapid turnaround for hemolysis assessment. Point-of-care lateral flow devices are capturing volumes previously served by central laboratory immunoassays.
- Blood Banks:Transfusion services monitoring donor hemolysis and transfusion reactions. German and Japanese purchasing cooperatives favor instrument-agnostic formulations with extended shelf stability.
Clinical laboratories generate the largest revenue pool. Research institutions show the steepest expansion trajectory.
Application:
Application maturity varies from established disease diagnosis protocols to emerging genetic testing applications where haptoglobin phenotyping supports pharmacogenomic research.
- Disease Diagnosis:Hemolytic anemia detection and cardiovascular risk stratification in diabetic patients. United States clinical laboratories are adding haptoglobin to standard acute-phase panels as payer recognition of prognostic utility expands.
- Biomedical Research:Inflammation pathway studies and biomarker discovery programs. Academic institutions prioritize lot-to-lot consistency for longitudinal study reproducibility.
- Blood Chemistry Analysis:Routine coagulation and transfusion-monitoring workflows. Automated chemistry analyzer integration drives specification requirements.
- Genetic Testing:Haptoglobin phenotyping for pharmacogenomic applications and population genetics research. Emerging demand from precision medicine initiatives.
Disease diagnosis commands the largest installed base. Genetic testing is gaining share fastest.
Technology:
Technology selection reflects the fundamental trade-off between analytical sensitivity and operational speed, with platform choice locking in reagent procurement for multi-year instrument lifecycles.
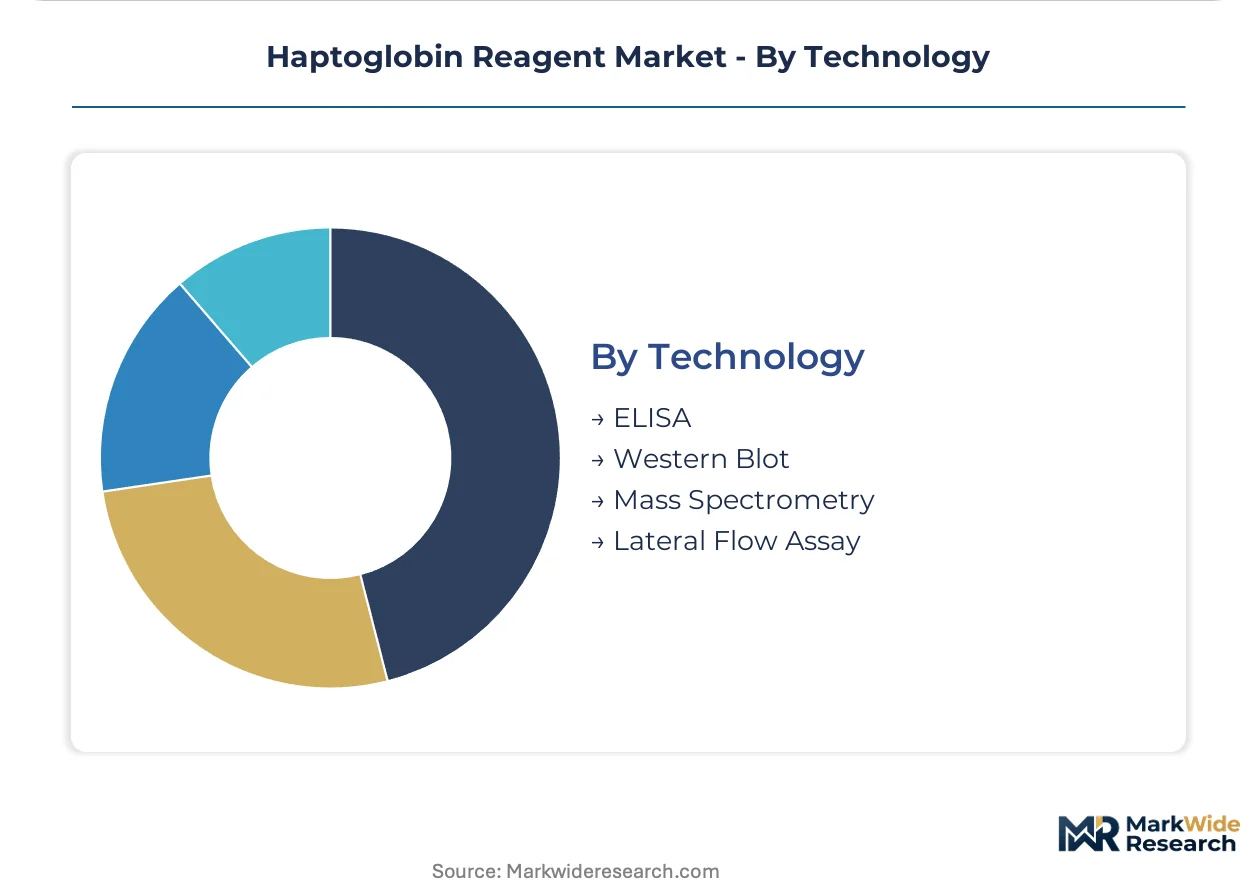
- ELISA:Enzyme-linked immunosorbent assay formats dominating research and reference laboratory applications. Magnetic bead-based solid-phase extraction variants are collapsing sample preparation bottlenecks in United States high-throughput facilities.
- Lateral Flow Assay:Point-of-care formats enabling rapid hemolysis screening without laboratory infrastructure. Emergency departments are adopting these devices for turnaround speed despite reduced analytical sensitivity.
- Western Blot:Confirmatory testing and research applications requiring molecular weight resolution. Limited clinical diagnostic adoption due to workflow complexity.
- Mass Spectrometry:High-specificity quantification for reference method development and protein isoform characterization. Specialized deployment in metrology laboratories supporting certified reference material production.
ELISA maintains the broadest installed base. Lateral flow assay climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulatory modernization anchors the United States market, while IVDR conformity assessments reshape European access pathways and Japan's PMDA maintains stringent transfusion-monitoring standards.
United States
Clinical laboratories in Massachusetts and North Carolina are expanding acute-phase protein panels for cardiovascular risk stratification in diabetic populations. CMS reimbursement determinations for novel hemolysis markers are shaping test menu expansion decisions at reference laboratories. Boston-area research institutions drive demand for high-sensitivity ELISA formats in inflammation biomarker studies.
Germany
Blood bank purchasing cooperatives across Bavaria and North Rhine-Westphalia are consolidating multi-hospital procurement around instrument-agnostic reagent formulations. EMA IVDR technical documentation requirements now exceed eighteen months for Class B in vitro diagnostics, freezing product registrations for several suppliers. Frankfurt's transfusion service networks specify extended shelf stability for quality control materials.
Japan
PMDA oversight of in vitro diagnostics sustains rigorous analytical validation standards for hemolysis screening protocols. Tokyo and Osaka metropolitan hospitals integrate haptoglobin testing into automated coagulation workflows for transfusion safety validation. Japanese blood services enforce stringent endotoxin thresholds for donor screening reagents.
India
The PLI scheme for medical device manufacturing is attracting contract reagent producers to Maharashtra and Gujarat. CDSCO regulatory pathways for IVD imports are streamlining as domestic diagnostic infrastructure expands into tier-2 cities. Bangalore's biotechnology clusters are emerging as contract manufacturing hubs for affordable ELISA kit production.
United Kingdom
NHS procurement frameworks are standardizing reagent specifications across England's reference laboratory networks. MHRA post-Brexit regulatory autonomy is diverging from EU IVDR timelines, creating parallel conformity assessment requirements. Cambridge's research corridor sustains demand for customizable diagnostic reagent concentrations in academic biomarker programs.
Haptoglobin Reagent Market Competitive Landscape
Vertically integrated diagnostics conglomerates and specialized reagent manufacturers split the market between bundled instrument-reagent systems and flexible assay components. The supplier base concentrates around three strategic archetypes: platform-integrated multinationals, independent reagent specialists, and contract manufacturing organizations. Competitive positioning depends on regulatory certification breadth and analyzer compatibility depth. M&A activity targets ISO 17511 traceability capabilities, while capacity expansion focuses on mammalian cell culture facilities for antibody production.
Within the platform-integrated tier, Beckman Coulter Inc. and Abbott Laboratories exemplify instrument-reagent bundling strength across high-throughput clinical chemistry installations. Sekisui Diagnostics occupies a position anchored in vertically controlled polymer chemistry capabilities for assay substrate quality. Randox Laboratories represents the multiplex specialization vector through proprietary biochip array technologies. IBL International and Kamiya Biomedical Company sit within the independent reagent specialist tier, serving research institutions and laboratory-developed test protocols with customizable formulation flexibility.
| Leading Market Players |
|---|
| Sekisui Diagnostics |
| Randox Laboratories |
| Beckman Coulter Inc. |
| Abbott Laboratories |
| IBL International |
| Analytik Jena AG |
| SDIX, LLC |
| Kamiya Biomedical Company |
| BioGenex Laboratories Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on mammalian cell culture facilities for recombinant monoclonal antibody production compresses pricing tier spreads while forcing supply chain consolidation around vertically integrated substrate manufacturers. This input bottleneck simultaneously elevates premium-grade reagent pricing and eliminates mid-tier suppliers lacking captive antibody production.
Pricing Analysis
Price spreads between the United States and India exceed threefold for comparable immunoassay kit specifications. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared automated platform bundles from research-grade ELISA formats and unregulated contract-manufactured alternatives. Pricing pressure stems from blood bank purchasing cooperatives consolidating multi-hospital procurement around instrument-agnostic formulations. Research institutions exhibit highest price sensitivity due to grant-funded budget constraints, while clinical laboratories prioritize automation compatibility over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for magnetic bead substrate components. Manufacturing concentrates in Germany, Japan, and the United States for high-purity antibody production, while India and China supply bulk substrate chemicals and packaging materials. Raw material dependencies include fetal bovine serum for calibrator matrices, specialized polymer resins for solid-phase extraction, and certified reference materials for ISO 17511 traceability. Distribution runs through regional distribution centers serving hospital networks, research institutions, and blood bank cooperatives with temperature-controlled logistics for shelf-stability maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The haptoglobin reagent market sits at an inflection point where IVDR conformity assessments and automated platform miniaturization are compressing development cycles while elevating analytical performance thresholds.
For Market Incumbents: Build regulatory certification moats by expanding notified body relationships across European markets and securing CMS reimbursement coding for novel hemolysis markers. Incumbents should acquire ISO 17511 traceability capabilities through targeted capability purchases while adding mammalian cell culture capacity to reduce fetal bovine serum input cost volatility. Lateral flow substitution in emergency departments threatens laboratory immunoassay volumes, making point-of-care compatibility development essential for platform retention. For New Entrants and Emerging Players: India's tier-2 diagnostic infrastructure expansion offers the most penetrable geographic entry point, particularly for affordable ELISA kit production under the PLI scheme. Contract manufacturing partnerships with Maharashtra and Gujarat facilities enable rapid scale without capital-intensive antibody production investments. A go-to-market angle targeting research institutions with customizable diagnostic reagent concentrations bypasses entrenched clinical laboratory instrument-reagent bundling. For Investors and Strategic Acquirers: EMA's IVDR technical documentation requirements reshapes the acquisition landscape toward targets with established notified body relationships and post-market surveillance infrastructure. Long-term viability centers on suppliers capable of navigating multi-jurisdictional regulatory pathways while serving both high-throughput automation and flexible research workflows. The signal to monitor is CMS reimbursement determinations for novel hemolysis markers, which typically trigger commercial payer follow-through within twenty-four months.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Conformity Assessment Completion | EMA's eighteen-month review timelines freeze revenue recognition for unprepared suppliers. |
| Multiplex Biochip Array Development | Acute-phase protein panels combining haptoglobin with CRP capture premium reference laboratory pricing. |
| Mammalian Cell Culture Capacity Addition | Captive antibody production insulates against fetal bovine serum price volatility and supply interruptions. |
| Instrument-Agnostic Formulation Launch | Blood bank purchasing cooperatives specify extended shelf stability without platform lock-in requirements. |
| Point-of-Care Lateral Flow Expansion | Emergency department adoption displaces central laboratory volumes previously served by immunoassays. |
Research Methodology
The analysis maps immunoassay kits, diagnostic reagents, control materials, and blood typing reagents, each validated through laboratory procurement managers, regulatory affairs specialists, blood bank technical directors, and research principal investigators. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, CMS reimbursement coding databases, and ISO 17511 reference material registries. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from trade flow analysis.
The forecast framework holds regulatory approval timelines and reimbursement coding stability as fixed assumptions while varying IVDR notified body capacity constraints and blood bank purchasing cooperative consolidation rates. Segmentation dimensions modeled include product format, end-user environment, application area, and technology platform across the analysis window. CAGRs derived from weighted average growth rates across segment-specific demand drivers incorporating aging population demographics, transfusion safety protocol expansion, and cardiovascular risk stratification adoption in diabetic patient monitoring.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated multinationals into contract manufacturing or point-of-care formats would shift competitive outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
South Africa in-Vitro Diagnostics Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Global HIV Diagnosis Market